
 Automotive Heat Shield Market | 2026-2036
Automotive Heat Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heat Shield Market Analysis
North American specialty materials producers is broadening heat shield substrate capacity to serve turbocharged gasoline direct-injection platforms. Morgan Advanced Materials leverages ceramic fiber formulations to sustain temperature ratings above 1,200°C in exhaust manifold applications. Autoneum Holding AG anchors acoustic-thermal composite supply to European premium OEMs, while Tenneco Inc. competes through integrated exhaust-aftertreatment-and-shield systems that reduce assembly complexity for vehicle assemblers.
An automotive heat shield is a thermal barrier component, typically fabricated from aluminum sheet, ceramic fiber mat, or multi-layer composite laminates with intumescent coatings, engineered to protect adjacent vehicle structures, cabin spaces, and electronic modules from radiated and conducted heat originating from powertrain and exhaust sources. Its primary commercial purpose is to enable tighter engine bay packaging, maintain passenger compartment comfort, and prevent thermal degradation of sensitive components under hood temperatures that routinely exceed 150°C in conventional vehicles and 200°C in hybrid architectures. Aluminum substrates still occupy the largest volume share across OEM supply chains due to cost efficiency and recyclability, though composite materials are capturing faster growth as engineers seek mass reduction in electric vehicle architectures where every kilogram directly impacts range. Thermal insulation technology leads in value terms because it addresses the most stringent OEM specifications for firewall and tunnel applications where dual heat and acoustic performance commands price premiums.
The EPA enforces tailpipe thermal management requirements that effectively mandate heat shield placement near catalytic converters, while the EU F-Gas Regulation and REACH chemical restrictions constrain certain ceramic fiber chemistries and adhesive formulations used in barrier coatings. NHTSA cabin fire safety standards further shape product testing protocols, particularly for underbody shields in battery-electric vehicles where thermal runaway propagation risks demand new material qualification cycles. Stakeholders must monitor how Euro 7 implementation timelines and evolving Chinese GB standards for new energy vehicle thermal safety will reshape material specifications and testing burdens across their development pipelines.
Market Dynamics
The automotive heat shield market pivots on powertrain electrification timelines, which are compressing development cycles and forcing material suppliers to qualify multi-layer composites for battery thermal runaway protection simultaneously with legacy exhaust applications.
Growth Catalysts
- Euro 7 tailpipe standards:These regulations mandate tighter thermal management near catalytic converters, compelling OEMs to add shield layers that withstand sustained high-temperature operation.
- Electric vehicle battery packs:Thermal runaway propagation risks in lithium-ion architectures are creating dedicated demand for ceramic fiber barriers between cell modules and passenger compartments.
- Turbocharged gasoline direct-injection platforms:Higher exhaust gas temperatures from downsized boosted engines require upgraded manifold insulation that aluminum alone cannot provide.
Market Restraints
- Aluminum price volatility:Raw material cost swings for rolled sheet metal compress margins for stamped shield producers serving high-volume compact vehicle programs.
- REACH chemical restrictions:The EU framework constrains certain ceramic fiber chemistries and adhesive binders, forcing reformulation cycles that extend qualification timelines.
- Substitute thermal management:Active cooling loops and aerodynamic underbody designs are displacing passive shielding in some battery-electric vehicle platforms.
Strategic Opportunities
- Chinese new energy vehicle thermal safety:Evolving GB standards for battery fire containment create first-mover advantage for suppliers with pre-qualified composite barrier systems.
- Acoustic-thermal convergence:Firewall applications combining noise vibration harshness reduction with heat insulation command price premiums from premium OEMs.
- Recyclable aluminum-ceramic hybrids:Closed-loop material recovery programs align with EU Green Deal circular economy mandates and OEM sustainability procurement criteria.
Industry Challenges
- Dual-platform qualification burdens:Suppliers must maintain parallel testing pipelines for internal combustion exhaust shields and battery pack barriers with incompatible thermal profiles.
- Compressed OEM development cycles:Electrification roadmaps are collapsing traditional 48-month validation schedules into 24-month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heat Shield Market |
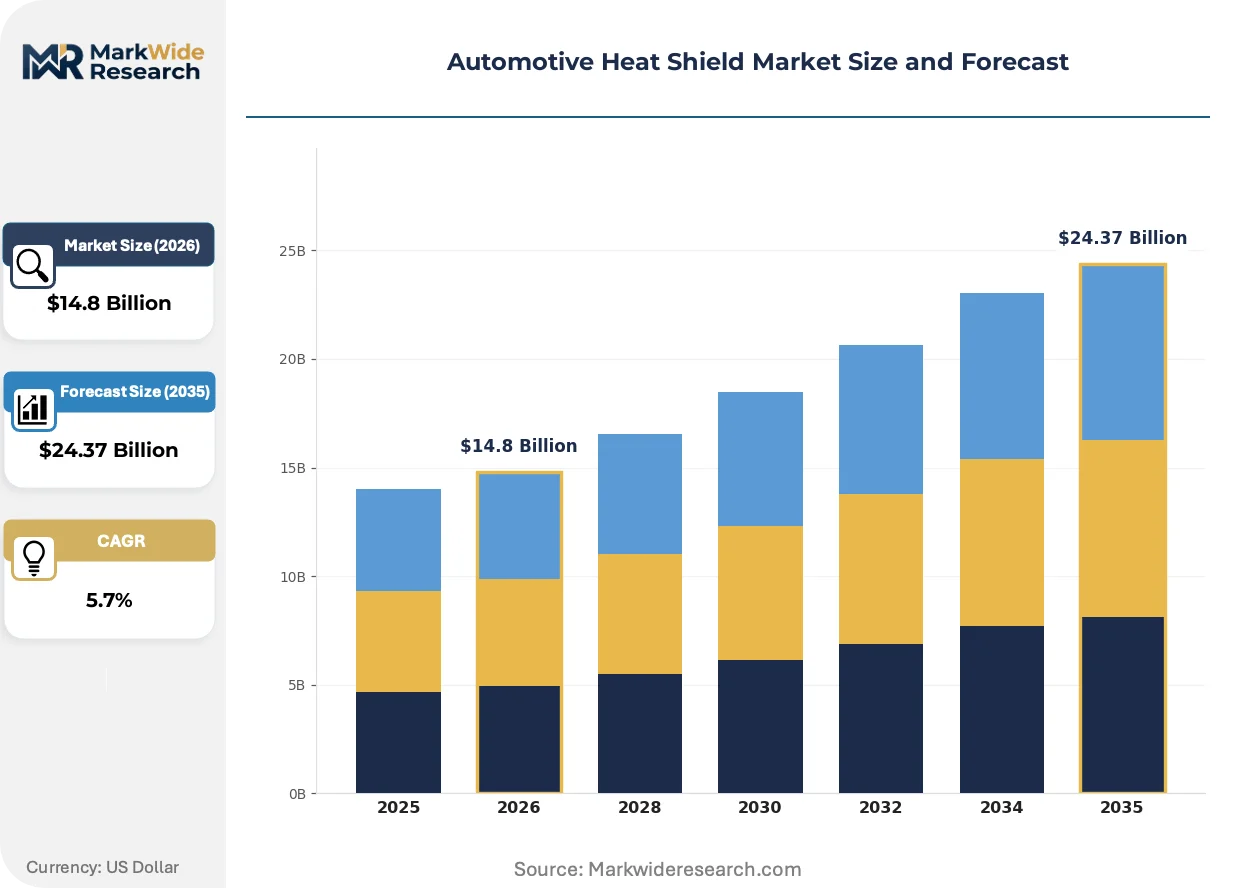
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Ceramic, Composite, Fiberglass Application: Exhaust Systems, Engine Compartments, Underbody Shields, Turbochargers Technology: Heat Reflective, Thermal Insulation, Acoustic Insulation, Barrier Coatings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Morgan Advanced Materials, Sumitomo Riko Co. Ltd., Autoneum Holding AG, Carcoustics International GmbH, Tenneco Inc., Dana Incorporated, Zircotec Ltd, Thermo-Tec Automotive, ElringKlinger AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heat Shield Market Emerging Trajectories
Material science breakthroughs are redefining thermal barrier performance thresholds while regulatory ratchets force simultaneous compliance across incompatible powertrain architectures. Three developments dominate supplier R&D allocation.
Multi-layer intumescent composite laminates are absorbing the thermal expansion stresses that crack traditional ceramic mats during rapid temperature cycling. Battery-electric vehicle engineers at German and Chinese OEMs are specifying these materials for tunnel and floorpan applications where 1,200°C ratings must coexist with 200°C steady-state operation. The technology is absorbing development resources previously allocated to incremental aluminum gauge reductions.
EPA Tier 3 and NHTSA cabin fire safety standards are tightening test protocols for underbody shields in ways that disqualify legacy aluminum-only constructions. The industrial consequence is a bifurcation in supplier capability, with composite-specialized firms capturing battery-electric vehicle programs while metal stampers defend internal combustion exhaust applications. North American producers are responding with hybrid aluminum-ceramic offerings that bridge both regulatory regimes.
Fleet procurement departments are consolidating supplier panels and demanding integrated thermal-acoustic solutions rather than discrete components. Tier 1 system integrators are displacing standalone heat shield vendors in European premium vehicle programs. This concentration is most visible in Germany, where OEMs now specify firewall modules from single-source acoustic-thermal specialists rather than assembling multi-vendor barrier stacks.
Automotive Heat Shield Market Segmentation
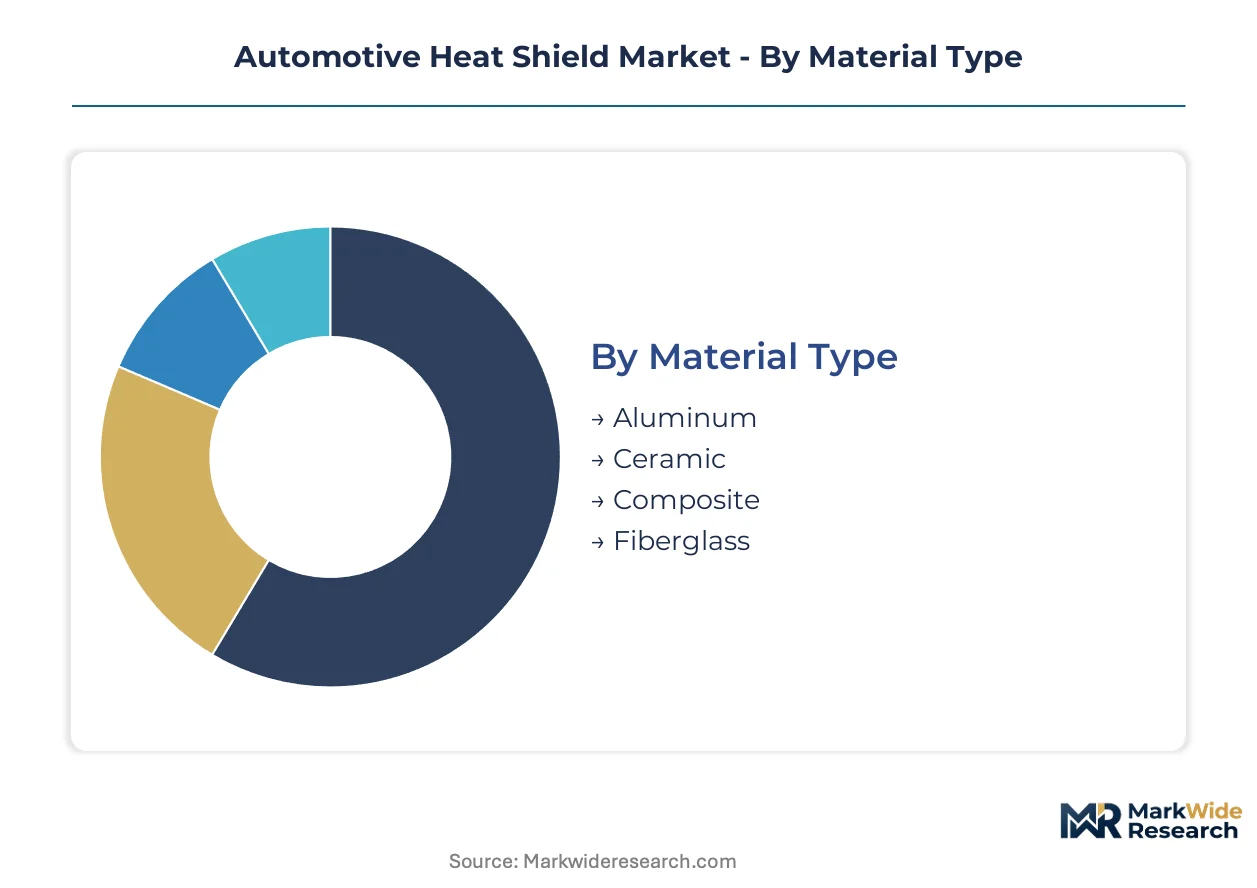
Material selection in automotive heat shields determines thermal performance thresholds, recyclability credentials, and integration complexity with surrounding vehicle structures. Engineers now evaluate substrates against dual-use scenarios spanning 200°C steady-state battery operation and 1,200°C exhaust manifold spikes.
Material Type:
Aluminum dominates standalone stamped shields for cost-sensitive programs, while ceramic and composite formulations embed into multi-layer systems for severe thermal environments.
- Aluminum:Rolled sheet metal substrates offer stampability and closed-loop recyclability that satisfies EU Green Deal procurement criteria. Volume demand concentrates in North American and German compact vehicle programs where cost efficiency outweighs mass reduction targets.
- Ceramic:Refractory fiber mats sustain temperature ratings exceeding 1,000°C in exhaust manifold and catalytic converter proximity zones. Chinese and German OEMs specify these materials for turbocharged gasoline direct-injection platforms where aluminum thermal limits fail.
- Composite:Multi-layer laminates with intumescent coatings absorb thermal expansion stresses during rapid cycling.
- Fiberglass:Lower-cost thermal barriers serve auxiliary underbody and tunnel applications with moderate temperature exposure.
Volume placements concentrate in aluminum; the faster expansion belongs to ceramic.
Application:
Application selection tracks powertrain architecture divergence, with battery-electric vehicle programs demanding entirely new shield locations absent exhaust hardware.
- Exhaust Systems:Catalytic converter and manifold shields face tightening Euro 7 thermal management mandates that add material layers and complexity. German OEMs lead specification intensity here, driven by domestic emissions enforcement timelines.
- Engine Compartments:Firewall and tunnel barriers combine thermal and acoustic performance for cabin comfort. Premium European assemblers pay price premiums for integrated solutions from single-source acoustic-thermal specialists.
- Underbody Shields:Battery pack thermal runaway protection dominates new engineering attention in electric architectures.
- Turbochargers:Downsized boosted engines generate exhaust gas temperatures that exceed aluminum capabilities.
Exhaust system placements retain the largest installed base; underbody shields for battery protection are climbing the fastest.
Technology:
Technology selection separates commodity thermal management from value-added integrated performance, with acoustic-thermal convergence commanding margin premiums.
- Heat Reflective:Polished aluminum surfaces and metallized films redirect radiant energy away from sensitive components. This technology anchors high-volume compact vehicle supply chains where cost minimization dominates procurement.
- Thermal Insulation:Ceramic fiber and composite barriers address the most stringent OEM specifications for sustained high-temperature operation. Firewall and tunnel applications in German premium vehicles drive specification intensity and price premiums.
- Acoustic Insulation:Noise vibration harshness reduction combines with thermal performance in converged barrier systems.
- Barrier Coatings:Intumescent and ablative surface treatments extend substrate temperature ratings.
Thermal insulation commands the highest value per kilogram; acoustic-thermal convergence delivers the steepest expansion trajectory.
End User:
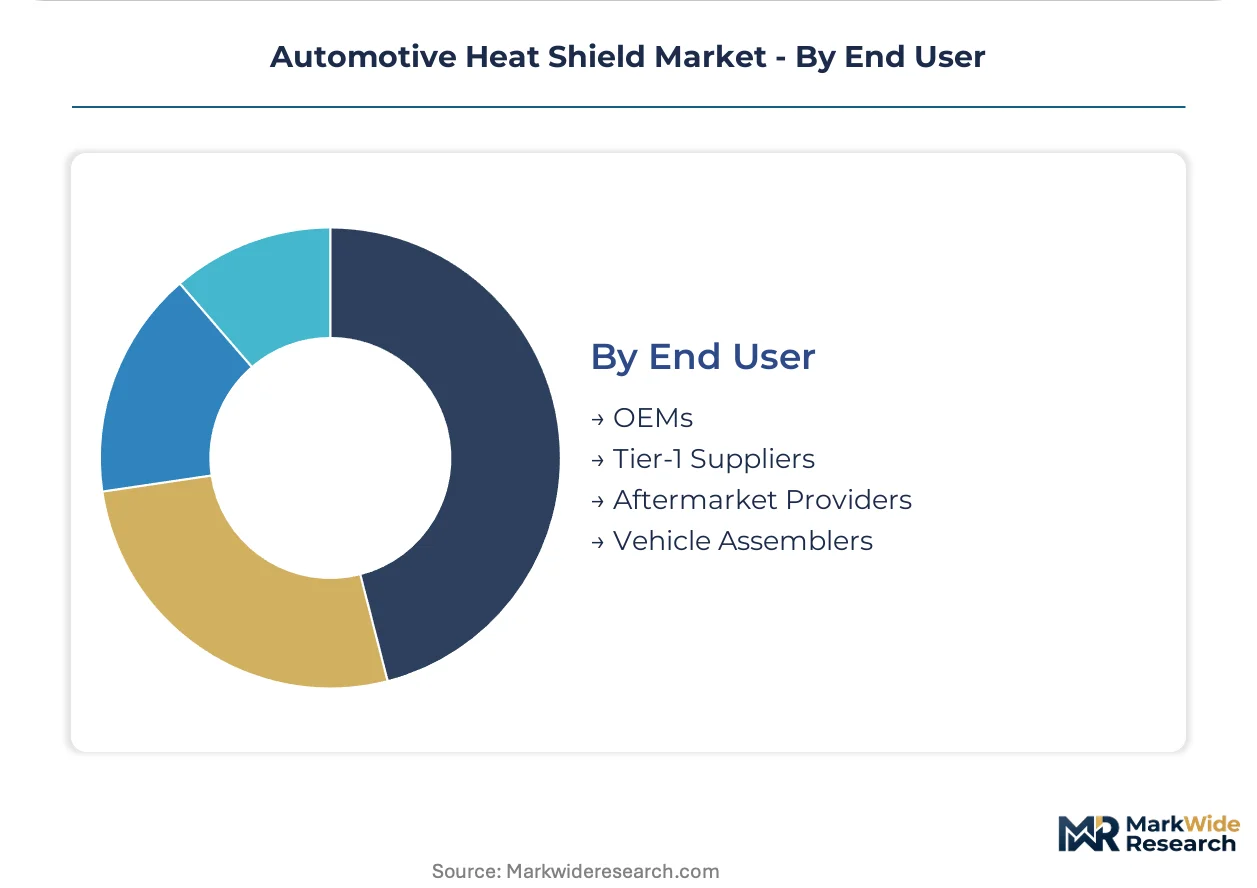
End user category determines qualification burden intensity, with OEM direct relationships demanding full validation pipelines and Tier-1 channels offering faster program entry.
- OEMs:Direct supply relationships with vehicle manufacturers require 24-month compressed validation cycles for battery-electric vehicle platforms. Chinese and German OEMs are consolidating supplier panels and demanding integrated thermal-acoustic modules.
- Tier-1 Suppliers:System integrators capture firewall and tunnel module assembly, displacing standalone heat shield vendors in European premium programs. These intermediaries manage multi-material qualification complexity for vehicle assemblers.
- Aftermarket Providers:Replacement demand follows vehicle parc aging and collision repair volume.
- Vehicle Assemblers:Contract manufacturing arrangements in emerging production regions source pre-validated shield assemblies.
Tier-1 supply channels handle the greatest material throughput; OEM direct relationships are gaining share fastest as electrification compresses development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite refineries in Guinea and Australia supply alumina feedstock for rolled aluminum sheet used across major automotive manufacturing belts. Ceramic fiber precursor plants cluster near industrial gas facilities in Germany and the United States. Composite resin formulation capacity concentrates in Japanese and South Korean chemical corridors serving battery-electric vehicle programs.
China
MIIT production quotas for new energy vehicles and aggressive dual carbon timelines compress supplier qualification windows for battery pack thermal barriers. GB standards for electric vehicle thermal safety are tightening test protocols for underbody shield materials. Yangtze River Delta manufacturing clusters around Shanghai host composite laminate pilot lines serving domestic OEM electrification roadmaps.
Germany
Turbocharged gasoline direct-injection platforms from Munich and Stuttgart-based OEMs sustain demand for ceramic manifold shields exceeding aluminum thermal limits. KBA enforcement of Euro 7 tailpipe standards accelerates multi-layer exhaust system specifications. Bavarian automotive suppliers anchor acoustic-thermal composite production for firewall modules in premium vehicle programs.
United States
EPA Tier 3 thermal management mandates near catalytic converters drive shield layer additions in Detroit Three powertrain architectures. NHTSA cabin fire safety standards reshape underbody material qualification for electric vehicle battery protection. Southeast Michigan stamping corridors expand hybrid aluminum-ceramic capacity to serve turbocharged engine platforms.
Japan
METI carbon neutrality roadmaps for 2050 force simultaneous qualification of exhaust shields and battery barriers with incompatible thermal profiles. JIS standards for automotive thermal management materials are incorporating battery-electric vehicle-specific test cycles. Nagoya-area industrial zones maintain ceramic fiber mat production for domestic OEM hybrid system requirements.
South Korea
MFDS-aligned industrial standards and aggressive OEM electrification targets create dual-platform demand for metal stampers and composite specialists. Domestic battery cell production expansion drives tunnel and floorpan barrier specification intensity. Gyeonggi-do manufacturing belts host integrated thermal-acoustic module assembly for export vehicle programs.
Automotive Heat Shield Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-electric vehicle thermal barrier specializations. The supplier base separates into metal stamping incumbents defending internal combustion exhaust applications and composite-focused firms capturing electric architecture programs. Three archetypes dominate: integrated system integrators, standalone material specialists, and hybrid metal-ceramic bridge suppliers. Competitive moves concentrate on capacity expansion for multi-layer composite laminates and strategic partnerships with battery cell manufacturers.
Among European-based material specialists, Morgan Advanced Materials and Autoneum Holding AG exemplify the composite-specialist archetype serving severe thermal environment specifications. Tenneco Inc. occupies a position within the integrated system integrator tier. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across incompatible powertrain qualification pipelines.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Sumitomo Riko Co. Ltd. |
| Autoneum Holding AG |
| Carcoustics International GmbH |
| Tenneco Inc. |
| Dana Incorporated |
| Zircotec Ltd |
| Thermo-Tec Automotive |
| ElringKlinger AG |
| Others |
Supply Flow & Price Mechanics
Captive vertical integration into ceramic fiber precursor production anchors both supply security and pricing power for Morgan Advanced Materials and Autoneum Holding AG as they serve German premium OEMs. This integration choice insulates these suppliers from aluminum sheet volatility while enabling premium pricing for multi-layer composite laminates that meet Euro 7 thermal specifications.
Pricing Analysis
Extended warranty and thermal performance certification bundling separate premium ceramic-composite suppliers from unbundled aluminum stampers in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks material complexity, with ceramic fiber barriers commanding margin premiums for battery runaway protection while stamped aluminum serves cost-sensitive compact programs. Pricing pressure stems from raw material cost swings in rolled sheet metal that compress margins for high-volume exhaust shield producers. Tier 1 system integrators exhibit lowest price sensitivity due to consolidated module procurement, while standalone aftermarket providers face highest sensitivity on replacement volume.
Supply Chain Analysis
Alumina feedstock for rolled aluminum sheet rests on bauxite refineries in Guinea and Australia, while ceramic fiber precursor production centers on industrial gas corridors in Germany and the United States. Composite resin formulation draws from Japanese and South Korean chemical clusters serving battery-electric vehicle programs. Single-source vulnerability concentrates in ceramic fiber mat supply for turbocharger applications where Morgan Advanced Materials maintains dominant production share. Distribution runs through Tier 1 system integrators that assemble firewall and tunnel modules for European premium OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers capable of parallel qualification for incompatible thermal profiles, forcing standalone aluminum stampers toward acquisition or exit. Compressed OEM development cycles favor integrated composite specialists with captive precursor supply.
For Market Incumbents: Extend ceramic fiber capacity in Bavarian manufacturing clusters to capture battery-electric vehicle barrier demand from Chinese OEMs expanding European production. Secure backward integration into alumina refining or long-term offtake agreements with Guinea and Australian bauxite suppliers to defend margin position against aluminum price volatility. Prioritize dual-platform testing infrastructure that simultaneously validates exhaust manifold shields and battery pack barriers. For New Entrants and Emerging Players: Direct digital engineering collaboration platforms offer entry into Chinese new energy vehicle supply chains where domestic OEMs pre-qualify composite barrier systems against evolving GB standards. Target underbody shield applications for battery thermal runaway protection as the most penetrable segment, given specification intensity and limited incumbent specialization. Pursue joint development agreements with battery cell manufacturers rather than direct OEM supply to reduce qualification burden. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated system integrators seeking acoustic-thermal composite capabilities, with financial sponsor rollup plays secondary. Long-term viability favors suppliers with demonstrated qualification across both internal combustion exhaust and battery-electric architectures. Watch MIIT production quota enforcement and Euro 7 implementation timelines as inflection indicators for material specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Fiber Precursors | Captive supply of high-temperature raw materials insulates Morgan Advanced Materials from feedstock volatility. |
| Dual-Platform Testing Infrastructure Investment | Simultaneous validation capability for exhaust and battery applications reduces OEM development cycle burden. |
| Joint Development with Battery Cell Manufacturers | Early engagement with CATL and BYD secures specification influence before OEM platform finalization. |
| Acoustic-Thermal Module Integration | Single-source firewall supply displaces multi-vendor assemblies in German premium vehicle programs. |
| Closed-Loop Aluminum Recovery Programs | EU Green Deal alignment enables preferential procurement positioning with sustainability-focused OEMs. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, and aftermarket distribution heads underwrites the qualitative findings on specification intensity and channel dynamics. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs records of aluminum sheet and ceramic fiber trade flows. Bottom-up demand modeling across propulsion architectures and top-down market sizing triangulate volume estimates.
Comparable historical periods spanning prior emissions regulation implementations anchor the forecast window for adoption curve calibration. Segmentation dimensions span material type, application location, propulsion architecture, and regional production cluster. CAGRs derive from installed base growth, content-per-vehicle expansion for battery protection, and powertrain mix shifts across the projection horizon. Forecast inputs incorporate MIIT production quotas, Euro 7 enforcement timelines, and OEM electrification roadmap disclosures.
The model holds under stable regulatory enforcement schedules and aluminum price bands; deviation in GB standard acceleration or bauxite supply disruption would shift material substitution timelines. A small set of named triggers—Euro 7 delay, battery chemistry transition to solid-state, Chinese export quota expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market