
 Auto Ventilated Seats Market | 2026-2036
Auto Ventilated Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Ventilated Seats Market Analysis
Asset-light manufacturing partnerships between seat suppliers and contract electronics assemblers is rewriting capital requirements for ventilated seat production. Faurecia leverages its electronics integration capabilities to bundle thermal modules with full seat systems. Lear Corporation anchors North American supply through captive foam and trim operations. Toyota Boshoku Corporation dominates Japanese OEM channels with just-in-time delivery architectures.
Auto ventilated seats incorporate perforated leather or synthetic surfaces coupled with axial or radial fans drawing cabin air through foam substrates, maintaining surface temperatures between 18°C and 24°C for occupant thermal comfort during extended drives. Active Ventilation systems command premium pricing due to higher fan count and sensor density, while Integrated Systems are gaining fastest as OEMs consolidate climate control with massage and memory functions. Aftermarket Solutions remain fragmented with lower margins, though Thermal Regulation technology is displacing simpler Passive Ventilation in retrofit kits.
NHTSA and EPA shape US product requirements through occupant safety and fuel consumption rules, while REACH and RoHS constrain material choices for European suppliers. China's GB standards and MIIT directives govern electromagnetic compatibility and energy efficiency for electrically controlled thermal seats. Stakeholders must monitor how evolving automotive electrification standards redefine power budgets for auxiliary comfort systems.
Market Dynamics
Electrification of vehicle powertrains is compressing auxiliary power budgets and forcing seat thermal systems to operate below 50 watts per occupant zone. This constraint is accelerating supplier migration toward brushless DC motors, aerodynamic fan geometries, and predictive climate algorithms that precondition seats before cabin entry.
Growth Catalysts
- EPA fuel-efficiency mandates:Tier 3 emissions standards penalize high-draw comfort accessories, pushing OEMs to specify seats with intelligent power management and sleep-mode fan controllers.
- Perforated synthetic leather advances:Micro-perforation laser systems now achieve 0.3mm hole density at production speeds viable for mass-market trim, expanding addressable vehicle segments beyond luxury.
- China premium vehicle assembly:Domestic OEMs in the NEV sector are factory-fitting ventilated front seats at trim levels previously reserved for import brands, creating volume pull for localized supply chains.
Market Restraints
- Foam substrate cost volatility:Polyurethane feedstock prices fluctuate with crude oil and isocyanate availability, squeezing margin on integrated seat systems where foam represents 15-20% of bill-of-materials.
- Radial fan motor supply concentration:Precision miniature blower manufacturing clusters in specific East Asian industrial zones, exposing OEMs to single-source risk during logistics disruptions.
- RoHS substance restrictions:European ECHA enforcement against legacy flame retardants in seat foam forces reformulation cycles that extend homologation timelines by 8-14 months.
Strategic Opportunities
- India premium passenger vehicle penetration:Maruti Suzuki and Hyundai Motor India are introducing ventilated seats at compact SUV price points where feature differentiation drives showroom traffic.
- Climate-massage convergence:Integration of pneumatic bladder arrays with thermal modules permits OEMs to bundle wellness features at software-defined price tiers.
- IRA clean vehicle credits:US assembly requirements for consumer tax incentives favor domestic seat module production, creating localized manufacturing pull for thermal component suppliers.
Industry Challenges
- Embedded software validation:Functional safety requirements under ISO 26262 for seat control modules demand ASIL-B rated thermal management firmware, extending development cycles and requiring specialized automotive software engineering talent.
- Legacy HVAC integration:Older vehicle architectures lack CAN-FD bandwidth for seat climate data streams, forcing retrofit of gateway modules or degraded performance in replacement markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Ventilated Seats Market |
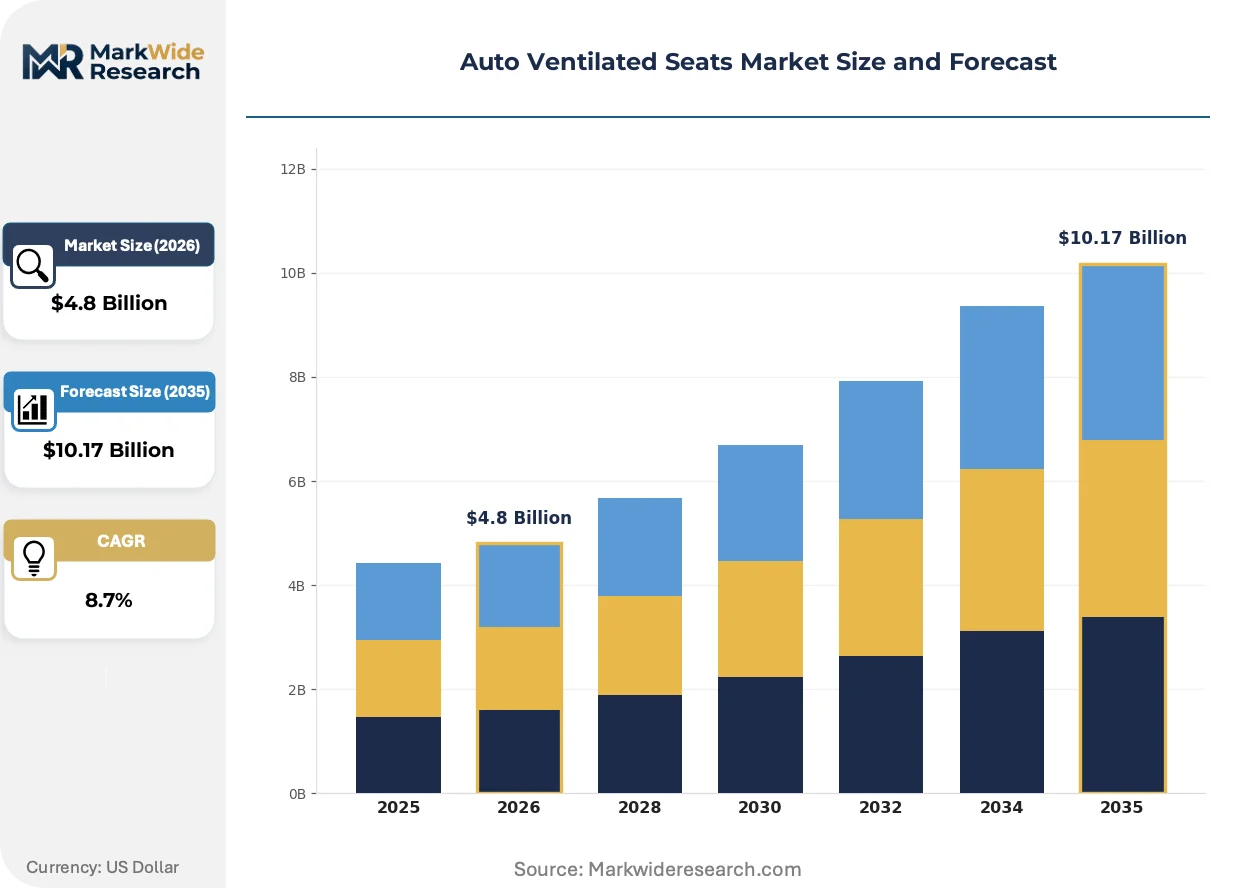
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Ventilation, Passive Ventilation, Heating & Cooling Combination, Integrated Systems Technology: Thermal Regulation, Airflow Management, Electrically Controlled, Pneumatic Systems Application: Passenger Vehicles, Commercial Trucks, Luxury Cars, Aftermarket Solutions End User: Original Equipment Manufacturers, Tier-1 Suppliers, Automotive Aftermarket, Fleet Operators |
| Companies Covered | Faurecia, Adient PLC, Lear Corporation, Toyota Boshoku Corporation, Gentherm Inc., Magna International Inc., TS Tech Co. Ltd., NHK Spring Co. Ltd., TACHI-S Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Ventilated Seats Market Emerging Trajectories
Seat thermal management is converging with biometric sensing and predictive cabin control, transforming a passive comfort feature into an active health and energy optimization node. This shift redefines supplier value propositions and opens new software monetization pathways.
Piezoelectric sensor arrays embedded in seat cushions are digitizing occupant thermal comfort preference mapping. Luxury OEMs in Germany and the United States are deploying these systems to learn individual setpoint preferences across drive cycles. The resulting data streams enable over-the-air refinement of climate algorithms and create subscription-ready feature tiers.
REACH authorization requirements for SVHC substances in automotive textiles are compelling European suppliers to eliminate per- and polyfluoroalkyl substances from water-repellent seat treatments. This regulatory pressure accelerates bio-based coating development while extending material qualification timelines for new vehicle programs. Seat trim suppliers with captive chemical formulation capabilities are capturing specification authority previously held by tier-two material houses.
Fleet operators in North American ride-hail channels are specifying ventilated seats as driver retention tools, shifting procurement criteria from upfront piece cost toward durability and serviceability metrics. This buyer segment now demands modular fan replacement architectures and extended warranty terms that diverge from retail consumer expectations. Tier-one seating suppliers are responding with service-part-prepped designs that separate thermal hardware from structural foam cores.
Auto Ventilated Seats Market Segmentation
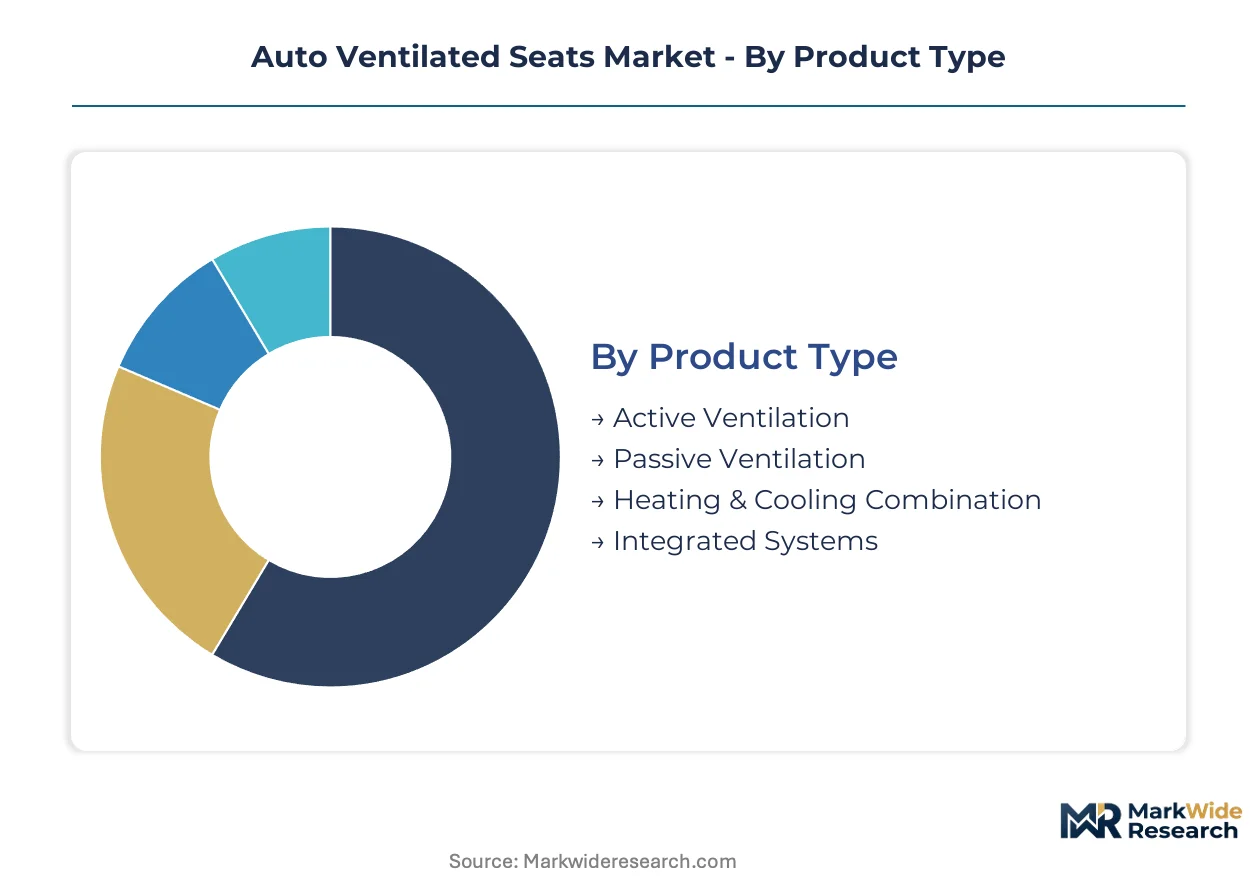
Segmentation in auto ventilated seats reveals how thermal comfort technology stratifies across power budgets, vehicle architectures, and procurement channels. Product refresh cycles vary dramatically from three-year automotive platform updates to decade-long aftermarket retrofit patterns.
Product Type:
Active Ventilation systems turn over fastest with each vehicle generation, while aftermarket retrofit kits cycle slowest as vehicle owners delay comfort upgrades.
- Active Ventilation:Multiple axial fans draw conditioned cabin air through perforated foam substrates, achieving surface temperatures between 18°C and 24°C. Demand concentrates in German luxury OEMs and US premium truck segments where EPA fuel-efficiency standards pressure suppliers to keep power draw below 50 watts per occupant zone.
- Integrated Systems:Bundled climate, massage, and memory functions share control modules and wiring harnesses, reducing per-feature cost. Chinese NEV OEMs are factory-fitting these at mid-trim levels previously reserved for import brands, accelerating volume pull for localized supply chains.
- Passive Ventilation:Perforated trim materials enable natural airflow without powered components, appealing to cost-sensitive vehicle programs in India and Southeast Asia.
- Heating & Cooling Combination:Thermoelectric elements paired with fan arrays deliver year-round comfort, requiring higher power budgets that constrain adoption in battery-electric vehicles.
Integrated Systems anchor the volume base while Active Ventilation gains share at the steepest rate.
Technology:
Cost tiers separate proprietary thermal algorithms from commodity fan controllers, with premium firmware commanding three to five times the module price of basic airflow management.
- Thermal Regulation:Predictive climate algorithms precondition seats before cabin entry using occupancy sensors and weather data integration. German OEMs deploy these systems with over-the-air update capability, creating subscription revenue pathways.
- Electrically Controlled:Brushless DC motor architectures with sleep-mode controllers address NHTSA and EPA joint pressure for low-power thermal management. US domestic OEMs specify these for IRA clean vehicle credit eligibility.
- Airflow Management:Aerodynamic fan geometries and duct routing optimization reduce noise, vibration, and harshness metrics for luxury vehicle programs.
- Pneumatic Systems:Bladder-based air circulation integrates with massage functions, requiring complex valve arrays that extend supplier qualification timelines.
Electrically Controlled technology anchors the volume base while Thermal Regulation climbs the fastest.
Application:
Passenger vehicle volumes dwarf commercial applications, yet fleet procurement criteria diverge sharply from retail consumer expectations on durability and serviceability.
- Passenger Vehicles:Factory-fit penetration expands from luxury into compact SUV segments as micro-perforation laser systems achieve 0.3mm hole density at mass-market production speeds. Maruti Suzuki and Hyundai Motor India are introducing ventilated seats at price points where feature differentiation drives showroom traffic.
- Luxury Cars:Piezoelectric sensor arrays embedded in cushions digitize occupant thermal preference mapping, enabling personalized climate profiles across drive cycles.
- Commercial Trucks:Long-haul driver retention concerns in North American freight corridors are elevating ventilated seats from optional to standard equipment on premium cab configurations.
- Aftermarket Solutions:Fragmented distribution through online retailers and specialty installers faces margin pressure from simpler Passive Ventilation kits displacing complex Thermal Regulation retrofits.
Passenger Vehicles anchor the volume base while Commercial Trucks expands most quickly as fleet operators recognize driver retention value.
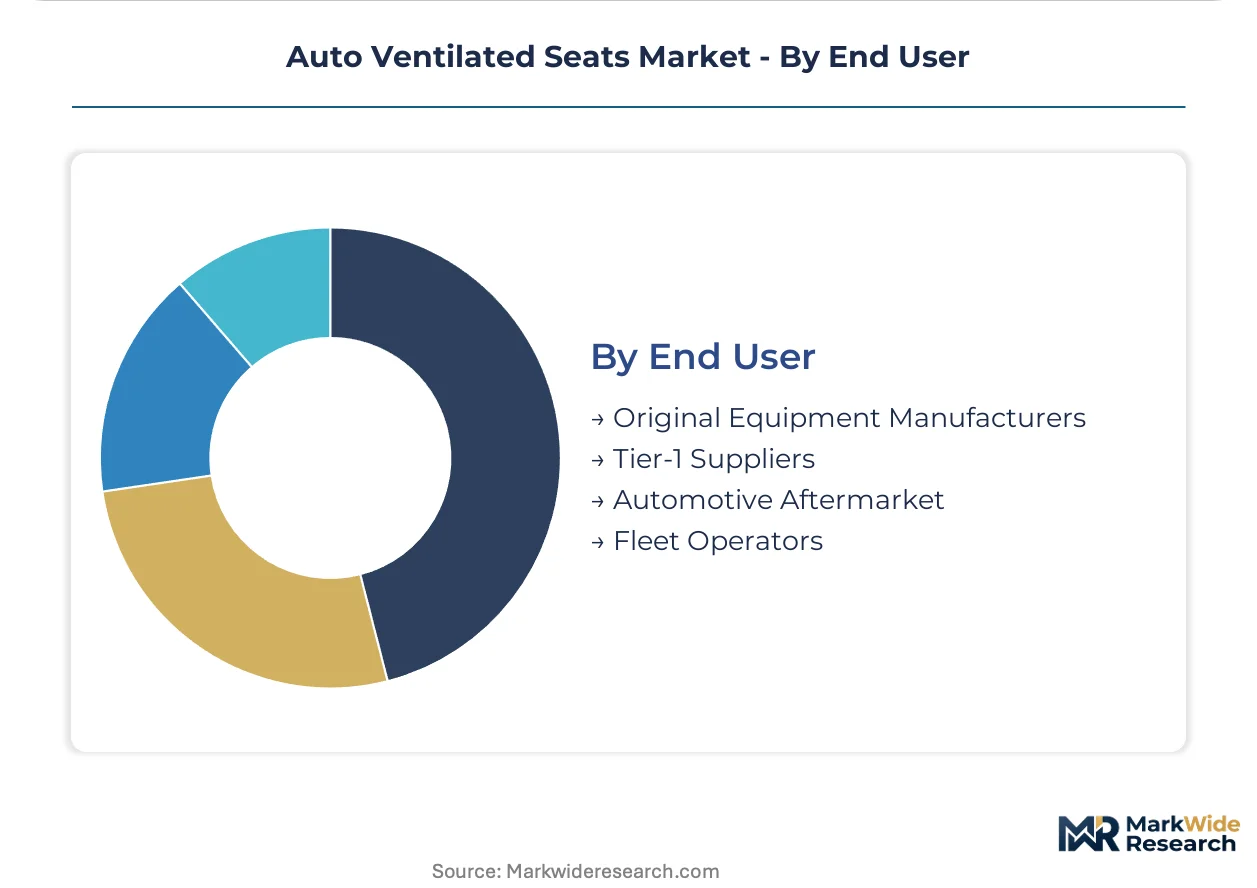
End User:
Supply concentration differs sharply between captive OEM engineering teams and independent aftermarket distributors, with Tier-1 suppliers occupying the intermediate position on margin and volume.
- Original Equipment Manufacturers:In-house seat engineering teams at premium brands specify proprietary thermal modules, backward integrating into fan motor design to differentiate cabin experience.
- Tier-1 Suppliers:Full-system integrators like Faurecia and Lear Corporation bundle thermal hardware with foam, trim, and structural components, capturing specification authority through just-in-time delivery architectures.
- Automotive Aftermarket:Independent distributors and specialty retailers serve vehicle owners outside warranty periods, with procurement decisions driven by installation simplicity rather than OEM-grade performance.
- Fleet Operators:North American ride-hail and freight channels demand modular fan replacement architectures and extended warranty terms that diverge from retail consumer expectations.
Tier-1 Suppliers anchor the volume base while Fleet Operators gains share at the steepest rate as commercial buyers shift procurement criteria toward total cost of ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in auto ventilated seats tilt toward export-heavy manufacturing clusters in East Asia and Germany, while the United States and China absorb the dominant import share as premium vehicle assembly centers.
United States
Domestic OEMs specify ventilated seats for IRA clean vehicle credit eligibility, with NHTSA cabin comfort guidelines pressuring suppliers toward sub-50-watt thermal modules. EPA Tier 3 emissions standards penalize high-draw accessories, accelerating intelligent power management adoption. Michigan and Ohio host concentrated seat system integration facilities serving Detroit Three assembly plants.
Germany
Luxury OEMs deploy piezoelectric sensor arrays for personalized climate profiles, with REACH authorization requirements forcing PFAS elimination from seat treatments. ECHA enforcement against legacy flame retardants extends homologation timelines. Bavaria and Baden-Württemberg anchor precision blower motor manufacturing for European premium vehicle programs.
China
NEV OEMs factory-fit ventilated front seats at mid-trim levels previously reserved for imports, with MIIT directives governing electromagnetic compatibility for electrically controlled thermal systems. GB standards on energy efficiency constrain power budgets. Yangtze River Delta clusters around Shanghai dominate localized supply chain buildout for domestic brands.
Japan
Just-in-time delivery architectures prioritize minimal inventory thermal modules, with METI industrial policy supporting brushless DC motor development for auxiliary power reduction. JIS standards on automotive electronics reliability shape supplier qualification. Aichi Prefecture's Nagoya corridor concentrates Toyota and Honda captive seat engineering operations.
India
Maruti Suzuki and Hyundai Motor India introduce ventilated seats at compact SUV price points, with BIS automotive safety standards governing seat structure and thermal system integration. PLI scheme incentives for auto component manufacturing attract thermal module assembly investments. Haryana and Tamil Nadu host emerging seat system integration facilities for domestic OEM supply.
Auto Ventilated Seats Market Vendor Landscape
On the supply side, the industry is consolidating around full-system integrators capable of bundling thermal hardware with foam, trim, and structural components. Tier-1 seating suppliers capture specification authority through just-in-time architectures, while specialized thermal component houses occupy technology niches. Two strategic archetypes dominate: captive OEM engineering teams at premium brands and independent full-system suppliers with multi-OEM relationships. Competitive moves center on backward integration into fan motor design and geographic co-location with high-volume vehicle assembly.
Among Japanese specialists, Toyota Boshoku Corporation exemplifies the captive supply archetype through just-in-time architectures, while NHK Spring Co. Ltd. and TACHI-S Co. Ltd. represent independent full-system suppliers with multi-OEM reach. Faurecia and Lear Corporation anchor Western supply through electronics integration and North American foam operations respectively. These five names illustrate how competitive positioning splits between geographic proximity to OEM engineering centers and scale-driven module cost efficiency.
| Leading Market Players |
|---|
| Faurecia |
| Adient PLC |
| Lear Corporation |
| Toyota Boshoku Corporation |
| Gentherm Inc. |
| Magna International Inc. |
| TS Tech Co. Ltd. |
| NHK Spring Co. Ltd. |
| TACHI-S Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision miniature blower motor manufacturing clusters across East Asian industrial zones is driving extended order backlogs and elevated pricing power for radial fan suppliers serving German and US luxury OEMs. This utilization squeeze forces Tier-1 seat integrators to absorb input cost volatility or pass through to factory-fit contracts, reshaping procurement negotiations across the value chain.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on fan motor density and ISO 26262 functional safety certification levels. Price differentiation centers on thermal algorithm sophistication and geographic delivery cost from Yangtze River Delta assembly hubs. Cost compression in mass-market compact SUV segments is intensifying because Chinese NEV OEMs are factory-fitting ventilated seats at mid-trim levels previously reserved for import brands. Fleet operators exhibit lowest price sensitivity due to total cost of ownership framing, while aftermarket distributors face highest sensitivity from simpler Passive Ventilation kit competition.
Supply Chain Analysis
Extended payment terms from German luxury OEMs and supply-chain finance facilities from Japanese trading houses are restructuring working capital requirements for thermal module suppliers. Manufacturing concentrates in China, Germany, and Japan, with precision blower production drawing from polyurethane foam substrates, brushless DC motors, and perforated synthetic leather feedstocks. Single-source vulnerability in East Asian radial fan motor manufacturing exposes the chain to logistics disruption. Distribution runs through just-in-time architectures anchored by Toyota Boshoku and captive OEM engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as automotive production volumes normalize and premium vehicle assembly rebounds from semiconductor-constrained lows. OEM platform refresh cycles are accelerating content-per-vehicle expansion for thermal comfort systems.
For Market Incumbents: Harden specification authority by backward integrating into fan motor design and capturing proprietary thermal algorithm IP. Defend against emerging Chinese NEV suppliers by co-locating module assembly with Yangtze River Delta vehicle plants. Lock in IRA clean vehicle credit eligibility through US manufacturing footprint expansion.
For New Entrants and Emerging Players: Pursue aftermarket retrofit white space in India and Southeast Asia where Passive Ventilation kits still dominate and Thermal Regulation penetration remains nascent. Target fleet operator procurement channels in North American ride-hail corridors where modular serviceability requirements diverge from retail specifications. Lead with installation simplicity and extended warranty terms as the go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Tier-1 seating suppliers are capturing specification authority through full-system integration while specialized thermal component houses face margin compression. Target acquisition candidates with captive chemical formulation capabilities and REACH-compliant coating IP. Watch for inflection in brushless DC motor supply concentration as a signal for supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate climate, massage, and memory functions to reduce per-feature wiring harness cost. |
| Backward Integration | Faurecia and Lear Corporation capture fan motor design authority to differentiate cabin experience. |
| Geographic Manufacturing Footprint | IRA clean vehicle credit eligibility favors domestic seat module production in Michigan and Ohio. |
| Software-Defined Vehicle Investment | German OEMs deploy over-the-air thermal algorithm updates creating subscription revenue pathways. |
| Long-term Supply Agreement | Fleet operators demand modular fan replacement architectures with extended warranty terms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings, and customs records. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed demand-side validation. Bottom-up triangulation across fan motor shipment volumes and top-down reconciliation against premium vehicle assembly data anchored value estimates.
Forecast inputs include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation. CAGRs derive from modeling thermal module adoption curves across luxury, mid-premium, and mass-market trim levels. Power budget constraints from EPA Tier 3 standards and NHTSA cabin comfort guidelines shape penetration assumptions across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, crude oil and isocyanate feedstock pricing, or Chinese NEV subsidy policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market