
 India Automotive Adaptive Lighting System Market | 2026-2036
India Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Adaptive Lighting System Market Foresight
Market Context
Automotive Research Association of India (ARAI) homologation under AIS-008 is collapsing the supplier base to firms with certified testing infrastructure. Osram leverages its Pune optical engineering center to sustain local validation capacity for OEM programs. Lumax Industries anchors domestic production through its backward-integrated LED module lines in Bhiwadi. HELLA KGaA Hueck & Co competes via technology leadership in matrix beam control systems adapted for Indian road geometries.
Technical Definition and Segment Structure
Automotive adaptive lighting systems are electromechanical headlamp assemblies that modulate beam pattern, intensity, and direction in response to vehicle speed, steering angle, and ambient conditions, typically operating between 12V and 48V electrical architectures with CAN bus integration. These systems primarily enhance nighttime visibility while reducing glare to oncoming traffic, directly supporting road safety mandates and insurance risk profiles. LED product types now dominate installed value given their thermal efficiency and digital controllability, though laser segments command the highest per-unit margins due to precision optics and limited supplier base. Matrix technology leads growth velocity as it enables pixel-level beam segmentation without mechanical actuators, while static adaptive configurations remain mature with compressed margins in economy vehicle tiers.
Regulatory Framework and Outlook
BIS enforces AIS-008 and AIS-010 standards that govern photometric performance and electromagnetic compatibility for lighting systems sold in India, while CDSCO oversight extends to automotive-grade laser components used in emerging headlamp architectures. The Ministry of Road Transport and Highways periodically revises these technical norms, forcing suppliers to recertify platforms and OEMs to redesign electrical harnesses. Stakeholders must monitor alignment between state-level electric vehicle policies and lighting voltage standards, as 48V mild-hybrid architectures spread through domestic passenger vehicle portfolios.
Market Dynamics
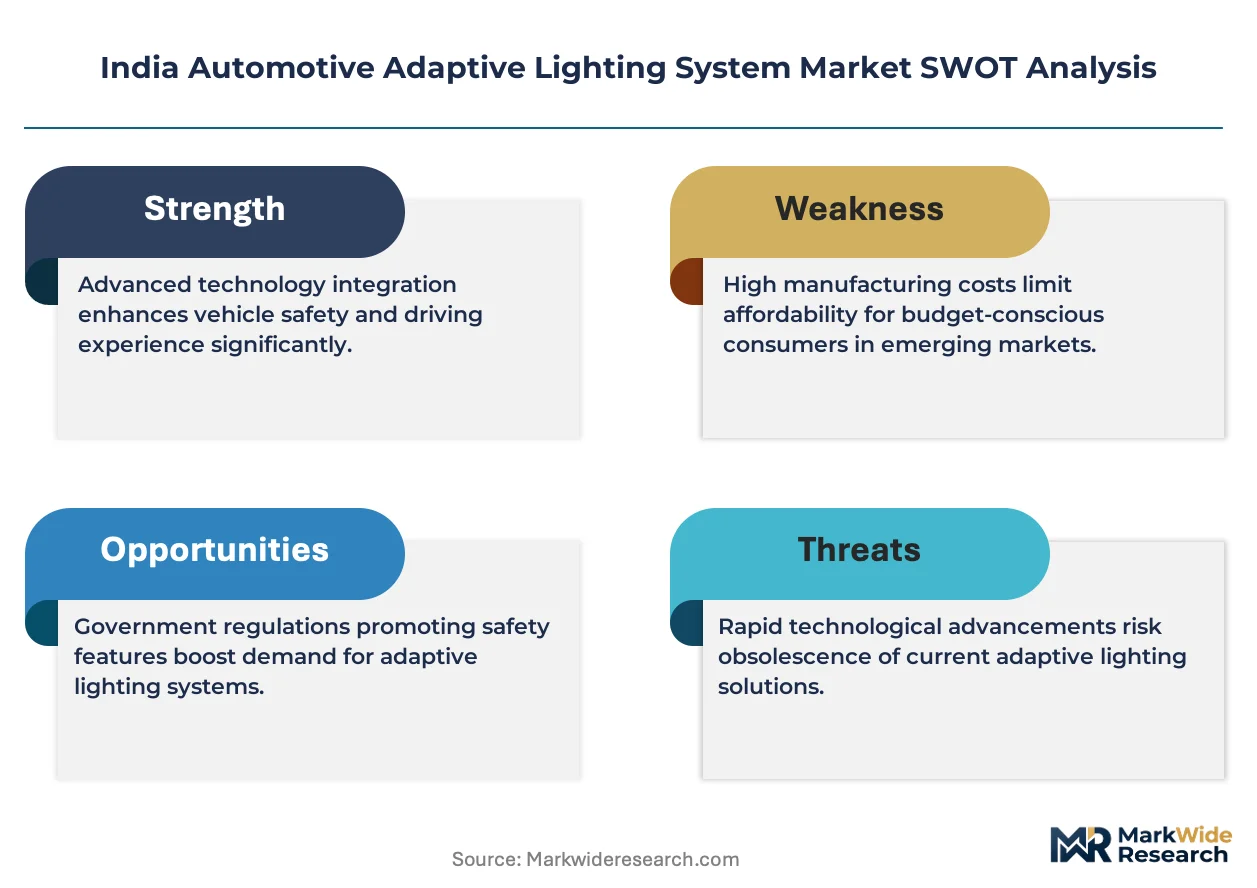
Matrix LED architectures are compressing static adaptive configurations into economy vehicle tiers while BIS recertification cycles force suppliers to rebuild validation infrastructure around AIS-008 amendments.
Growth Catalysts
- 48V Mild-Hybrid Proliferation:Higher voltage electrical architectures enable more sophisticated beam modulation algorithms without overloading legacy 12V harnesses. OEMs in Maharashtra and Tamil Nadu assembly corridors are prioritizing these platforms.
- AIS-008 Homologation Stringency:Tighter photometric thresholds under BIS enforcement are eliminating uncertified suppliers and consolidating procurement toward ARAI-validated sources. This accelerates formal channel adoption over aftermarket alternatives.
- Insurance Risk Reclassification:Nighttime visibility improvements from adaptive systems are triggering premium recalibration by domestic underwriters. Fleet operators now specify matrix configurations to reduce liability exposure.
Market Restraints
- Optics-Grade Silicone Cost Volatility:Thermal management substrates for LED modules face input price swings tied to petrochemical feedstocks. Domestic molders lack backward integration into silicone precursors.
- Pune-Bhiwadi Supply Concentration:Certified optical engineering and LED module production cluster within 200 kilometers, creating single-region exposure to Maharashtra industrial policy shifts or logistics disruption.
- Mechanical Actuator Obsolescence:Static adaptive configurations with servo-driven leveling face displacement by solid-state matrix alternatives. Tooling amortization traps mid-tier suppliers in depreciating product lines.
Strategic Opportunities
- Gujarat Assembly Corridor Underpenetration:Sanand and Halol vehicle plants currently source lighting from Maharashtra-based suppliers. Localized module assembly could capture logistics savings and state incentive eligibility.
- PLI Scheme Component Localization:Production-linked incentives for automotive electronics extend to LED driver ICs and optical sensors. Captive semiconductor packaging addresses import dependency in beam control systems.
- CAN-FD Architecture Convergence:Faster in-vehicle networking enables real-time camera-to-headlamp data pipelines. Integration with ADAS perception stacks creates bundled specification opportunities.
Industry Challenges
- Optical Engineering Talent Scarcity:Ray-tracing simulation and thermal-fluid modeling for precision optics requires specialized skill sets concentrated at ARAI and select IIT programs. OEM program timelines outpace graduate pipeline expansion.
- Homologation Cycle Compression:BIS amendment schedules force redesign-validation loops within single fiscal windows. Testing queue bottlenecks at Pune facilities delay platform launches.
- Legacy Harness Integration Friction:Retrofitting adaptive systems into existing 12V electrical architectures requires proprietary gateway modules. Compatibility testing multiplies variant complexity for multi-OEM suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Adaptive Lighting System Market |
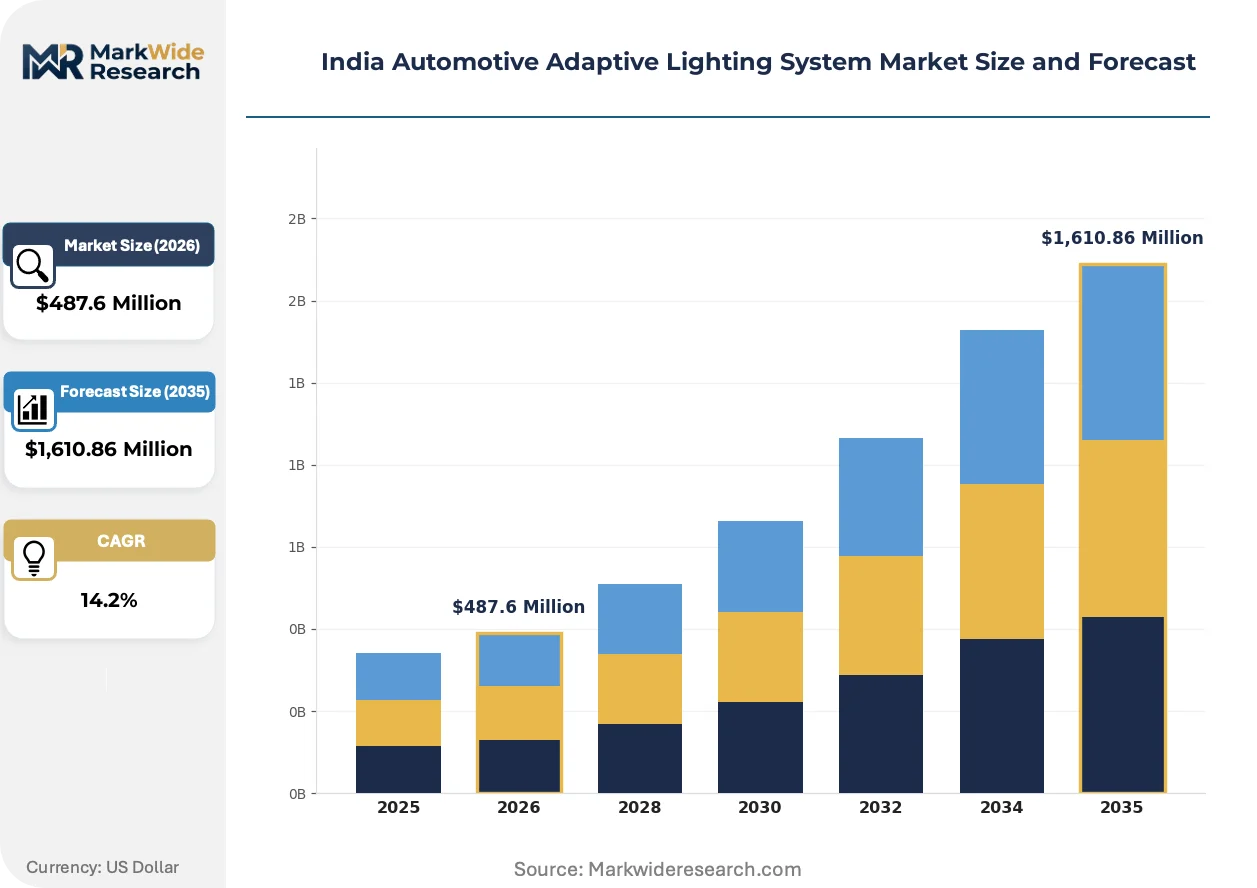
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Laser Technology: Matrix, Dynamic, Static, Adaptive End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Front, Rear, Side, Ceiling |
| Companies Covered | Osram, Stanley Electric Co. Ltd, HELLA KGaA Hueck & Co, Lumax Industries, Magneti Marelli SpA, Koito Manufacturing Co. Ltd, Koninklijke Philips N.V., Hyundai Mobis, Valeo SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Adaptive Lighting System Market Shifts & Advancements
Digital beam control is displacing mechanical actuation across price tiers while regulatory pressure on photometric precision accelerates validation technology investment.
Matrix LED technology is bifurcating the supplier base into pixel-capable integrators and legacy leveling-system assemblers. Tier-1 suppliers with optical design software and thermal simulation capacity are capturing OEM program awards for premium passenger vehicles. Static adaptive configurations with servo motors are retreating to commercial vehicle and economy segments where specification tolerance permits slower refresh cycles.
BIS amendments to AIS-008 are tightening luminous intensity tolerances and glare zone definitions for oncoming traffic protection. Suppliers must recalibrate optical molds and resubmit ARAI validation for existing platforms. Maharashtra-based testing facilities face capacity constraints as multiple OEMs synchronize redesign cycles to regulatory publication schedules.
Fleet procurement is consolidating specification authority at headquarters level rather than permitting regional plant discretion. Centralized technical teams now mandate matrix configurations across all vehicle classes above compact SUVs, compressing supplier negotiation leverage. Tamil Nadu and Karnataka assembly operations report shortest implementation lag for headquarter-directed lighting upgrades.
India Automotive Adaptive Lighting System Market Segmentation
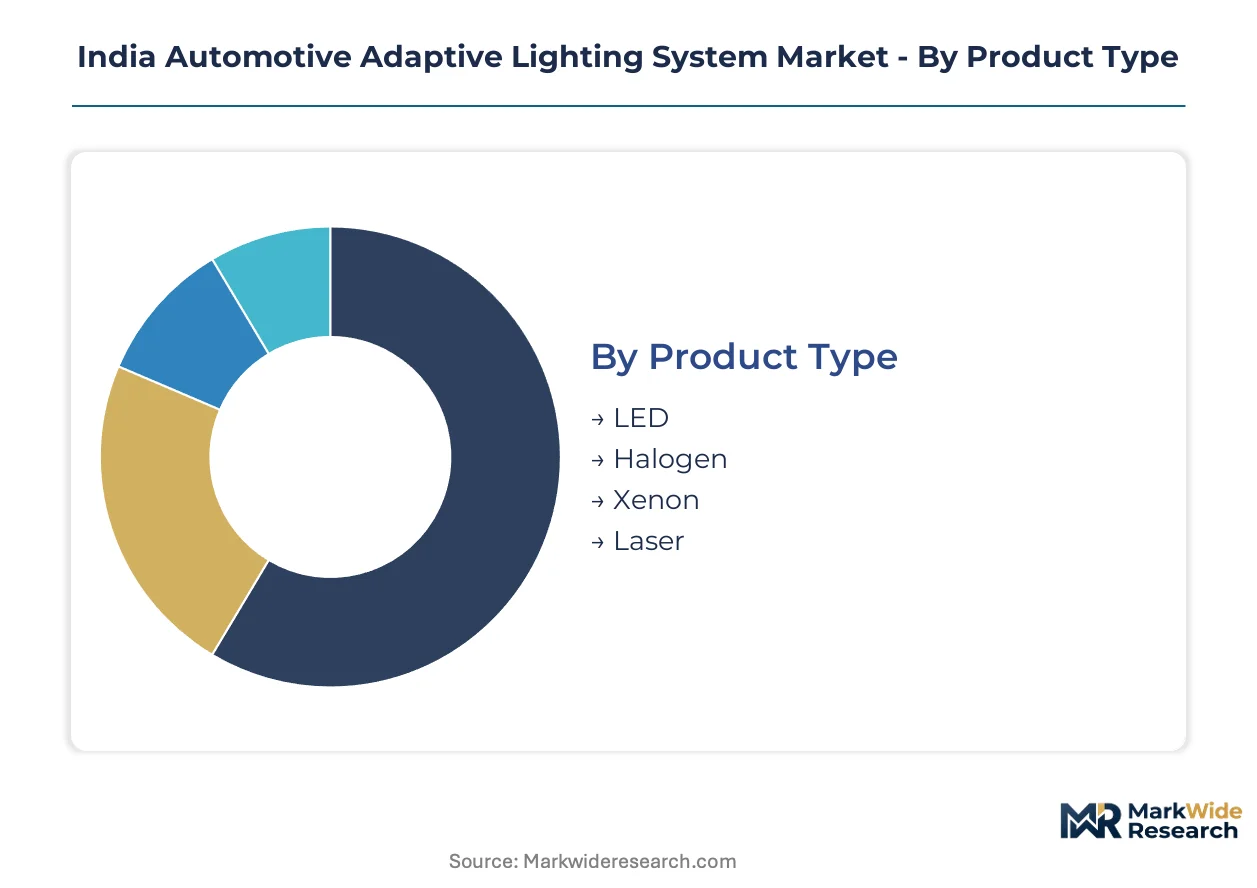
Adaptive lighting segmentation in India reflects divergent technical maturity across price tiers and regulatory certification requirements. Product type and technology choices determine supplier capability thresholds and ARAI homologation pathways.
Product Type:
LED modules dominate domestic production with localized assembly in Bhiwadi and Pune corridors, while laser systems remain import-dependent with concentrated validation at ARAI facilities.
- LED:Solid-state emitters with thermal management substrates enable digital beam control through driver IC modulation. Maharashtra and Tamil Nadu assembly plants specify these for mid-premium passenger vehicles under tightening AIS-008 photometric thresholds.
- Laser:Precision diode-pumped sources project high-intensity beams through phosphor-converted optics. Demand concentrates in imported premium platforms where per-unit margins justify CDSCO component oversight and limited supplier base constraints.
- Xenon:High-intensity discharge arcs with mechanical shutter systems.
- Halogen:Tungsten-filament technology with reflector-based beam shaping.
LED commands the established base. The steepest expansion runs through laser configurations in ultra-premium segments.
Technology:
Cost tier separation is pronounced: matrix systems carry three to five times the module cost of static alternatives, creating distinct procurement channels.
- Matrix:Pixel-level LED segmentation eliminates mechanical actuators through solid-state switching. Fleet operators in Karnataka and Tamil Nadu mandate these for liability reduction under recalibrated insurance risk profiles.
- Adaptive:Sensor-integrated beam modulation responds to steering angle and vehicle speed. OEM electrical harness redesigns for 48V mild-hybrid architectures favor these over legacy static configurations.
- Dynamic:Continuous beam pattern adjustment through motorized reflector assemblies.
- Static:Fixed beam geometry with manual leveling correction.
Matrix technology is gaining share fastest in new platform awards. Static systems retain volume leadership in commercial vehicle retrofit applications.
End User:
Volume concentration differs sharply: OEMs and Tier-1 suppliers drive formal channel adoption, while aftermarket penetration faces BIS enforcement barriers.
- OEMs:Integrated platform specifications with ARAI homologation at design phase.
- Tier-1 Suppliers:Module assembly with backward-integrated LED sourcing and optical validation.
- Vehicle Assemblers:Final integration responsibility with harness compatibility testing.
- Aftermarket Providers:Uncertified import channels facing AIS-008 compliance compression.
OEMs anchor procurement volume. Tier-1 suppliers are expanding fastest through PLI scheme component localization.
Installation:
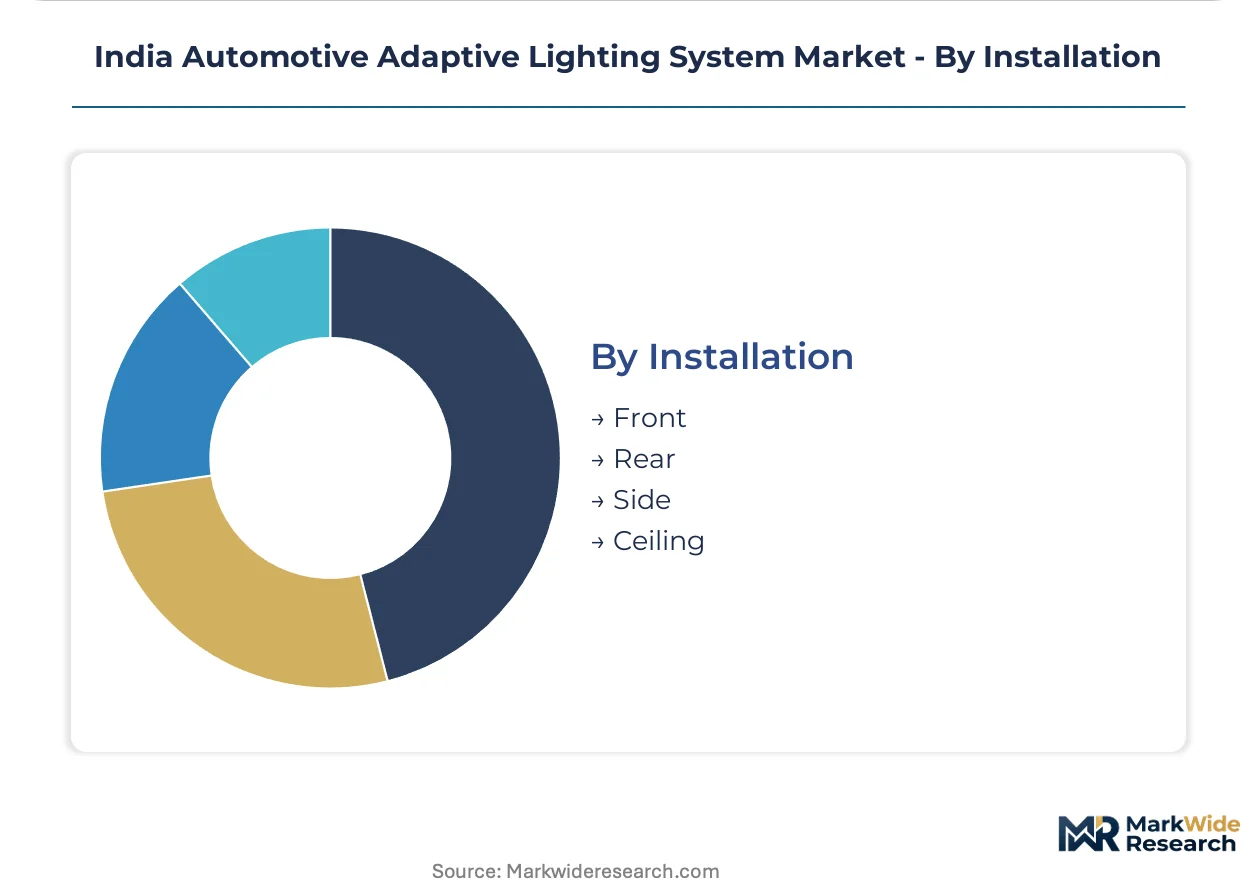
Application geometry determines thermal design and regulatory classification, with front installations carrying the full burden of oncoming traffic glare protection.
- Front:Headlamp assemblies with high/low beam modulation and cornering functions.
- Rear:Adaptive tail and stop lamps with intensity modulation.
- Side:Mirror-integrated turn indicators and puddle lamps.
- Ceiling:Interior ambient lighting with zone control.
Front installations dominate value capture. Ceiling applications are expanding most quickly through premium cabin experience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium passenger vehicle OEMs and fleet operators concentrate procurement authority in Maharashtra and Tamil Nadu, where vehicle assembly density and BIS-certified testing infrastructure create buyer-archetype clustering around formal channel adoption.
Maharashtra
ARAI homologation facilities in Pune anchor validation capacity for matrix LED platforms. BIS enforces AIS-008 recertification cycles that compress supplier redesign timelines. The Pune-Bhiwadi corridor concentrates optical engineering talent and LED module production within 200 kilometers, creating single-region exposure to industrial policy shifts.
Tamil Nadu
Major vehicle assembly plants in Chennai and Sriperumbudur drive specification authority for fleet procurement mandates. The state's electric vehicle policy alignment with 48V mild-hybrid architectures accelerates electrical harness redesigns. Karnataka and Tamil Nadu assembly operations report shortest implementation lag for headquarter-directed lighting upgrades.
Gujarat
Sanand and Halol vehicle plants currently source adaptive lighting from Maharashtra-based suppliers, creating logistics inefficiency and incentive eligibility gaps. The state's automotive electronics PLI scheme extends to LED driver ICs and optical sensors. Localized module assembly could capture state-level production-linked benefits.
Karnataka
Fleet operators in Bengaluru mandate matrix configurations for liability reduction under recalibrated insurance risk profiles. The state's technology corridor attracts CAN-FD architecture development for real-time camera-to-headlamp data pipelines. Integration with ADAS perception stacks creates bundled specification opportunities for Tier-1 suppliers.
Haryana
Commercial vehicle retrofit applications in Gurugram and Manesar retain static adaptive configurations where specification tolerance permits slower refresh cycles. The state's industrial policy supports automotive component manufacturing through dedicated electronics clusters. Tooling amortization pressures mid-tier suppliers facing displacement by solid-state matrix alternatives.
India Automotive Adaptive Lighting System Market Competitive Landscape
Player mix skews toward multinational Tier-1 suppliers with ARAI-validated testing infrastructure and domestic LED module assemblers with backward-integrated production lines. Market structure consolidates around firms capable of simultaneous optical design software deployment and thermal simulation capacity. Two strategic archetypes dominate: technology licensors with matrix beam control intellectual property, and scale-driven fabricators with captive LED sourcing. Competitive moves center on homologation cycle compression through Pune facility partnerships and PLI scheme component localization for driver ICs.
Among Germany-based lighting specialists, HELLA KGaA Hueck & Co and Osram occupy positions within the technology leadership archetype, leveraging European optical engineering heritage for Indian road geometry adaptation. Lumax Industries represents the domestic integration archetype, anchoring local production through Bhiwadi-based LED module lines. These three firms exemplify the bifurcation between foreign technology licensors and backward-integrated domestic assemblers competing for OEM program awards under tightening BIS certification requirements.
| Leading Market Players |
|---|
| Osram |
| Stanley Electric Co. Ltd |
| HELLA KGaA Hueck & Co |
| Lumax Industries |
| Magneti Marelli SpA |
| Koito Manufacturing Co. Ltd |
| Koninklijke Philips N.V. |
| Hyundai Mobis |
| Valeo SA |
| Others |
Supply & Pricing Matrix
BIS certification under AIS-008 simultaneously gates supplier qualification and stratifies price tiers, as uncertified firms face exclusion while ARAI-validated sources command premiums for homologated optical platforms. This regulatory filter compresses margins for legacy assemblers while concentrating pricing power among firms with captive testing infrastructure.
Pricing Analysis
Cost-plus contracts with silicone precursor indexation dominate Tier-1 procurement, insulating LED module suppliers from petrochemical volatility while passing thermal substrate swings to OEMs. Pricing stratifies across matrix-capable integrators, sensor-integrated adaptive assemblers, and servo-driven static configurations, with the latter facing compression as solid-state alternatives displace mechanical actuators. Price erosion runs through economy vehicle tiers where specification tolerance permits slower refresh cycles. Fleet operators in Karnataka and Tamil Nadu exhibit lowest price sensitivity due to insurance risk recalibration, while aftermarket channels face collapse under AIS-008 enforcement.
Supply Chain Analysis
Germany and Japan anchor precision optical component fabrication, while China and Taiwan feed LED driver ICs and thermal management substrates into Indian assembly corridors. Domestic production draws from imported silicone precursors, phosphor-converted optics, and CAN-FD networking chipsets, with limited backward integration into semiconductor packaging. Single-region exposure concentrates in the Pune-Bhiwadi corridor, creating vulnerability to Maharashtra industrial policy shifts or logistics disruption. Distribution runs through OEM-directed Tier-1 module assembly with direct-to-plant delivery, compressing aftermarket channel viability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined beam calibration and over-the-air update subscriptions expand faster than hardware shipments, creating service-attach economics that favor firms with embedded control architecture.
For Market Incumbents: Consolidate optical engineering talent through ARAI facility partnerships in Pune, compressing homologation cycle times as BIS amendment schedules accelerate. Deepen backward integration into LED driver IC packaging under PLI scheme incentives, defending margin position against import-dependent competitors. Lock in 48V mild-hybrid platform specifications with Maharashtra and Tamil Nadu OEMs before electrical harness redesigns solidify. For New Entrants and Emerging Players: Lead with Gujarat assembly corridor localization, capturing state-level production-linked benefits and logistics savings from Sanand and Halol vehicle plants. Target fleet procurement headquarters in Bengaluru with matrix configuration bundles tied to insurance risk recalibration. Enter through CAN-FD architecture integration partnerships, positioning as ADAS perception stack collaborators rather than standalone lighting suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across semiconductor packaging and optical validation infrastructure, favoring scaled players with captive testing capacity. Five-to-ten year viability hinges on PLI scheme qualification and ARAI homologation track records. Target acquisition profiles center on Tier-1 assemblers with backward-integrated LED module lines and existing OEM program awards. The signal to watch is BIS publication schedules for AIS-008 amendments, which trigger synchronized redesign cycles and testing queue bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| ARAI Homologation Partnership | Pune facility access compresses validation timelines for matrix LED platforms under BIS enforcement. |
| LED Driver IC Localization | PLI scheme capture reduces import dependency in beam control systems for 48V architectures. |
| Gujarat Manufacturing Footprint | Sanand module assembly captures state incentives and logistics savings from Halol vehicle plants. |
| CAN-FD Architecture Integration | Real-time camera-to-headlamp pipelines enable ADAS bundling with Karnataka fleet operators. |
| Software-Defined Beam Calibration | Over-the-air update subscriptions create recurring revenue layers beyond hardware shipments. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings. Primary interviews with ARAI homologation officers, OEM electrical system architects, Tier-1 LED module procurement leads, and fleet operator technical specification teams were synthesized with secondary validation from BIS regulatory filings, vehicle production databases, PLI scheme beneficiary disclosures, and customs import records for optical components. Bottom-up segmentation modeling triangulates against top-down market sizing from assembly plant capacity and content-per-vehicle assumptions.
Sensitivity analysis on silicone precursor pricing, BIS amendment timing, and 48V mild-hybrid penetration rates stress-tests projection stability across the modeling period. The analytical framework segments by product type, technology architecture, end-user channel, and installation position, with vehicle class and OEM tier as cross-cutting dimensions. CAGRs derive from installed base evolution and replacement cycle dynamics, with explicit modeling of matrix LED adoption curves and static adaptive displacement rates.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme extension, stable petrochemical feedstock pricing, or accelerated BIS recertification cycles would require recalibration. Forecasts reflect documented assumptions on OEM platform launch timing and fleet procurement centralization trends. Recalibration cycles align with material shifts in regulatory publication schedules, semiconductor packaging capacity expansion, and insurance risk classification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market