
 Automotive Front-End Collision Warning System Market | 2026-2036
Automotive Front-End Collision Warning System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Front-End Collision Warning System Market Outlook
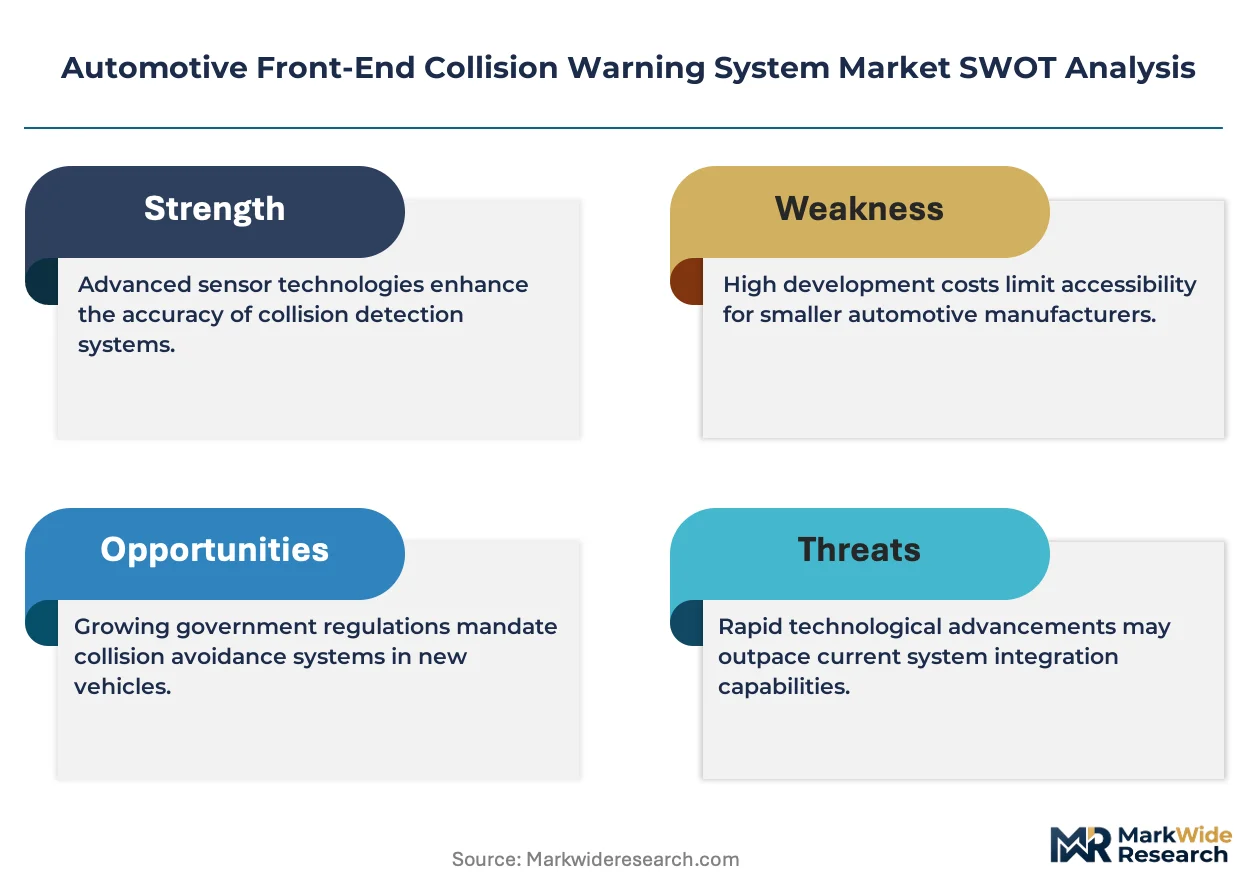
Sensor fusion between radar and camera modules is narrowing the performance gap between premium and mid-range vehicle platforms. Continental AG leverages its integrated radar production in Germany to sustain cost advantages across European OEM programs. Robert Bosch GmbH anchors its competitive position through in-house semiconductor development for 77 GHz radar chipsets. Mobileye N.V. differentiates via proprietary EyeQ processor architectures that consolidate perception algorithms on single silicon.
Automotive front-end collision warning systems combine electromagnetic sensing, optical imaging, and real-time processing to detect imminent forward obstacles and alert drivers or trigger autonomous braking interventions; typical radar units operate at 76-81 GHz with detection ranges exceeding 150 meters under adverse weather conditions. Camera Systems dominate current installation volumes due to lower unit costs and mature supply chains, while LiDAR Systems represent the fastest-expanding category as solid-state designs reduce mechanical complexity and price points for mass-market deployment. Factory-installed configurations capture the majority of value as OEMs embed warning capabilities within broader ADAS suites rather than offering discrete retrofit alternatives.
The European Union's General Safety Regulation and the United States NHTSA New Car Assessment Program collectively mandate forward collision mitigation capabilities for passenger and commercial vehicles seeking type approval or five-star safety ratings. Japan's METI guidelines and China's MIIT connected-vehicle standards further condition market access on documented sensor performance and software validation protocols. Stakeholders must monitor divergence between regional test protocols for cut-in scenarios and pedestrian detection as these variations determine engineering resource allocation and platform architecture choices.
Market Dynamics
Radar-camera sensor fusion is compressing cost differentials between vehicle tiers while NHTSA and EU General Safety Regulation mandates force platform standardization across OEM portfolios.
Growth Catalysts
- EU General Safety Regulation:Mandates advanced driver assistance systems for new vehicle categories, compelling OEMs to embed forward collision warning as baseline equipment rather than optional trim.
- Commercial fleet liability reduction:North American trucking and logistics operators are installing forward collision platforms to lower insurance premiums and accident-related litigation exposure.
- 77 GHz radar semiconductor maturation:In-house chipset development at major tier-1 suppliers is reducing bill-of-material costs for electromagnetic sensing modules.
Market Restraints
- LiDAR cost structure:Mechanical scanning units remain prohibitively expensive for mass-market deployment despite solid-state design advances.
- German supply concentration:Bosch, Continental, and ZF control concentrated manufacturing footprints for sensor fusion modules, creating single-source vulnerability.
- Adverse weather optical degradation:Camera-dependent systems suffer performance degradation in heavy precipitation, fog, and direct sunlight glare conditions.
Strategic Opportunities
- India connected-vehicle standards:MIIT-aligned regulations are conditioning market access on documented sensor performance, creating first-mover advantage for validated platform suppliers.
- Retrofit aftermarket channel:Insurance telematics providers are bundling forward collision warning hardware with usage-based policy products for existing vehicle fleets.
- Radar-LiDAR fusion architectures:Convergence of electromagnetic and optical depth sensing is enabling redundant perception stacks for conditional automation.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-D validation timelines for automotive-grade software extend development cycles and strain engineering resource allocation.
- Legacy vehicle electrical architecture integration:CAN-FD and Ethernet backbone upgrades are required to support real-time sensor data throughput in older platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Front-End Collision Warning System Market |
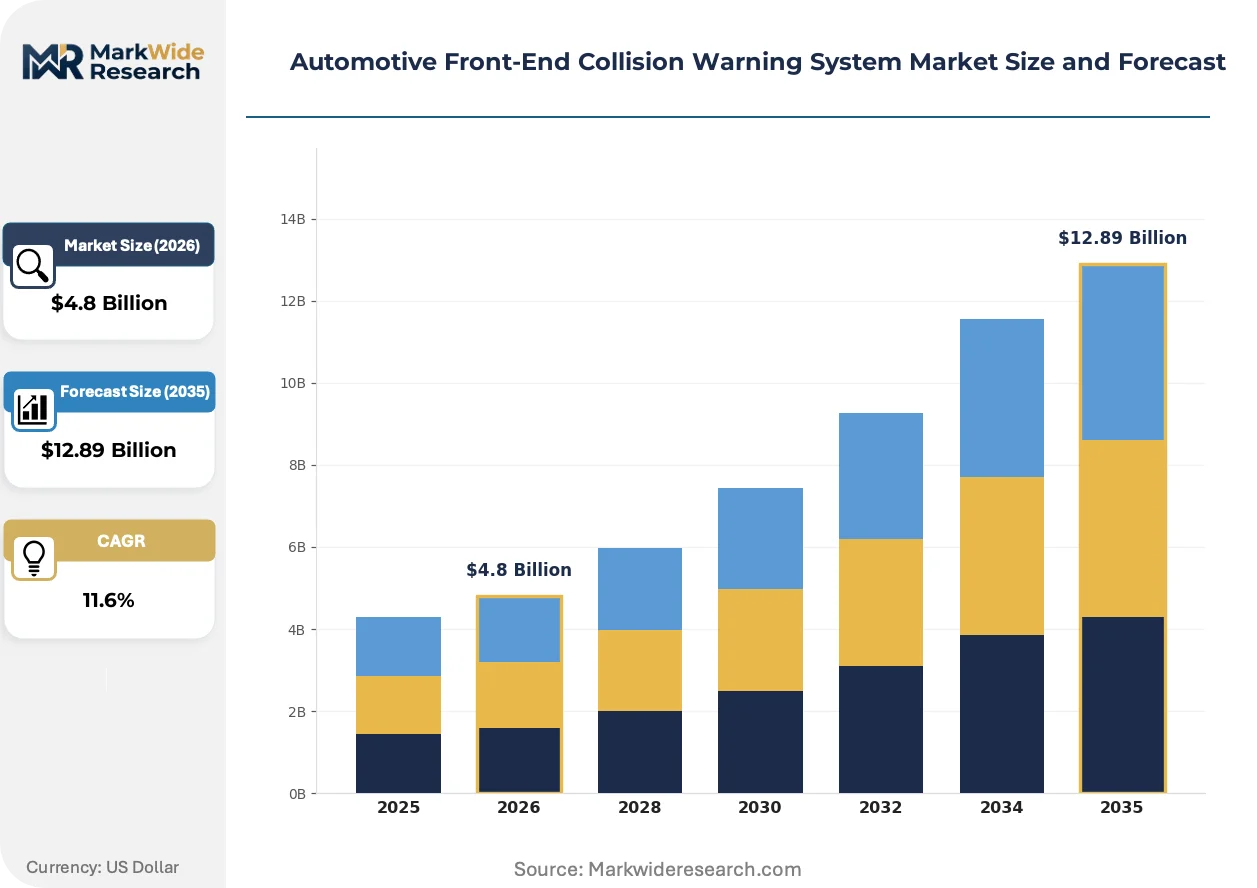
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Camera Systems, LiDAR Systems, Ultrasonic Sensors Technology: Adaptive Cruise Control, Automatic Emergency Braking, Forward Collision Warning, Pre-Collision System End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Integrated Systems, Standalone Systems, Retrofit Solutions, Factory-installed |
| Companies Covered | Robert Bosch GmbH, Continental AG, Mobileye N.V., ZF Friedrichshafen AG, Aptiv PLC, Denso Corporation, Valeo SA, Autoliv Inc., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Front-End Collision Warning System Market Strategic Shifts
Solid-state LiDAR designs are collapsing mechanical complexity barriers while regulatory test protocol divergence is fragmenting engineering resource allocation across regional type-approval requirements.
Frequency-modulated continuous-wave radar is collapsing the performance gap between premium and mid-range vehicle segments. Tier-1 suppliers are shipping 77 GHz units to mass-market OEM programs at price points previously reserved for luxury platforms. This compression is forcing camera-only system suppliers to add radar fusion or exit the forward collision warning category entirely.
The EU General Safety Regulation and NHTSA New Car Assessment Program are converging on mandatory forward collision mitigation for type approval and five-star ratings. This regulatory alignment is accelerating platform standardization across passenger and commercial vehicle categories. Divergence in cut-in scenario and pedestrian detection test protocols, however, is forcing OEMs to maintain multiple software validation tracks.
Fleet procurement managers are consolidating supplier relationships around full-stack ADAS providers rather than discrete sensor vendors. Insurance-backed financing models are displacing traditional capital expenditure approaches for commercial vehicle retrofits. This behavioral shift is most visible in North American long-haul trucking, where telematics-integrated warning systems are becoming a condition of coverage renewal.
Automotive Front-End Collision Warning System Market Segmentation
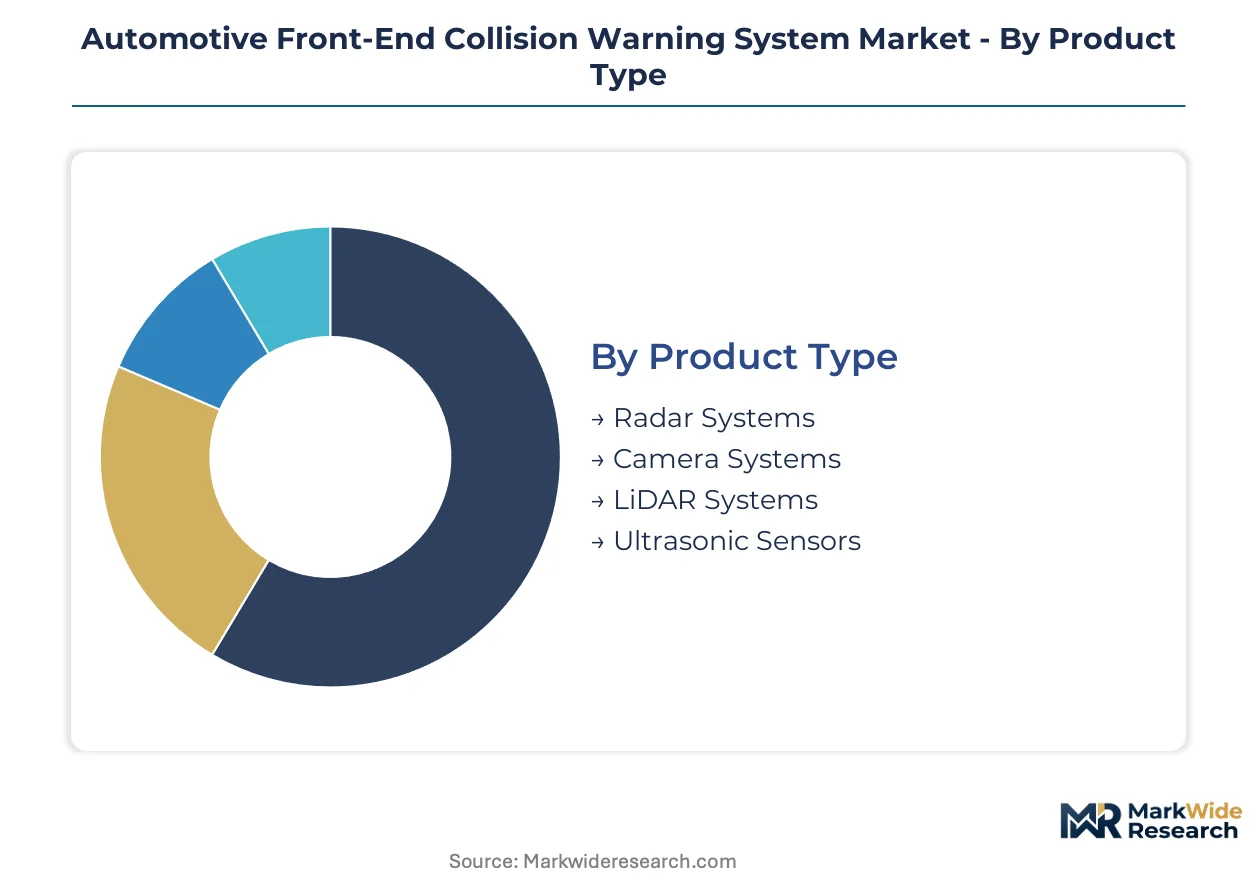
Technology choices in front-end collision warning systems determine cost structures, performance envelopes, and regulatory compliance pathways across vehicle platforms. Segment boundaries are compressing as sensor fusion architectures merge historically discrete product categories into unified perception stacks.
Product Type:
Cost tier differentiation separates electromagnetic sensing modules from optical depth systems, with unit economics driving adoption patterns across mass-market and premium vehicle lines.
- Radar Systems:Frequency-modulated continuous-wave units operating at 76-81 GHz deliver 150-meter detection ranges through precipitation and fog. Fleet operators in the United States prioritize radar-dominant configurations to satisfy NHTSA New Car Assessment Program requirements for commercial vehicle coverage renewals.
- Camera Systems:Optical imaging modules leverage mature CMOS supply chains and lower bill-of-material costs to dominate current installation volumes. Performance degrades under heavy precipitation and direct glare, constraining single-sensor deployments in regions with adverse weather exposure.
- LiDAR Systems:Solid-state designs are collapsing mechanical complexity barriers for mass-market deployment.
- Ultrasonic Sensors:Short-range proximity detection complements primary forward-sensing architectures in low-speed maneuvering scenarios.
Camera Systems command the established base. The steepest expansion runs through LiDAR Systems.
Technology:
Application maturity varies from baseline alert functions to full autonomous intervention, with regulatory mandates forcing convergence on automatic braking capabilities.
- Automatic Emergency Braking:Autonomous braking intervention without driver input represents the regulatory floor under EU General Safety Regulation and NHTSA guidelines. German OEM programs now embed AEB as non-negotiable baseline equipment across passenger and light-commercial categories.
- Forward Collision Warning:Driver-alert-only systems without autonomous intervention face displacement as mandatory automatic braking spreads. Aftermarket providers in North America retain niche positioning for legacy fleet retrofits where full AEB integration proves cost-prohibitive.
- Adaptive Cruise Control:Speed-maintaining functionality with forward-vehicle following extends collision warning into longitudinal vehicle control.
- Pre-Collision System:Integrated warning and preparation sequences activate seatbelt pretensioners and brake assist before impact detection.
Forward Collision Warning commands the established base. The steepest expansion runs through Automatic Emergency Braking.
End User:
Customer type concentration reflects supply chain control points, with factory integration decisions residing at distinct tiers of vehicle manufacturing.
- OEMs:Vehicle manufacturers specify sensor fusion architectures and validate software stacks against regional type-approval protocols. European OEMs source integrated modules from concentrated German supplier footprints to satisfy EU General Safety Regulation timelines.
- Tier-1 Suppliers:Bosch, Continental, and ZF manufacture sensor fusion modules and radar chipsets for multiple OEM programs from German production facilities.
- Aftermarket Providers:Insurance telematics bundling is displacing traditional capital expenditure models for fleet retrofits.
- Vehicle Assemblers:Contract manufacturing arrangements delegate final integration of warning system hardware.
OEMs command the established base. The steepest expansion runs through Aftermarket Providers.
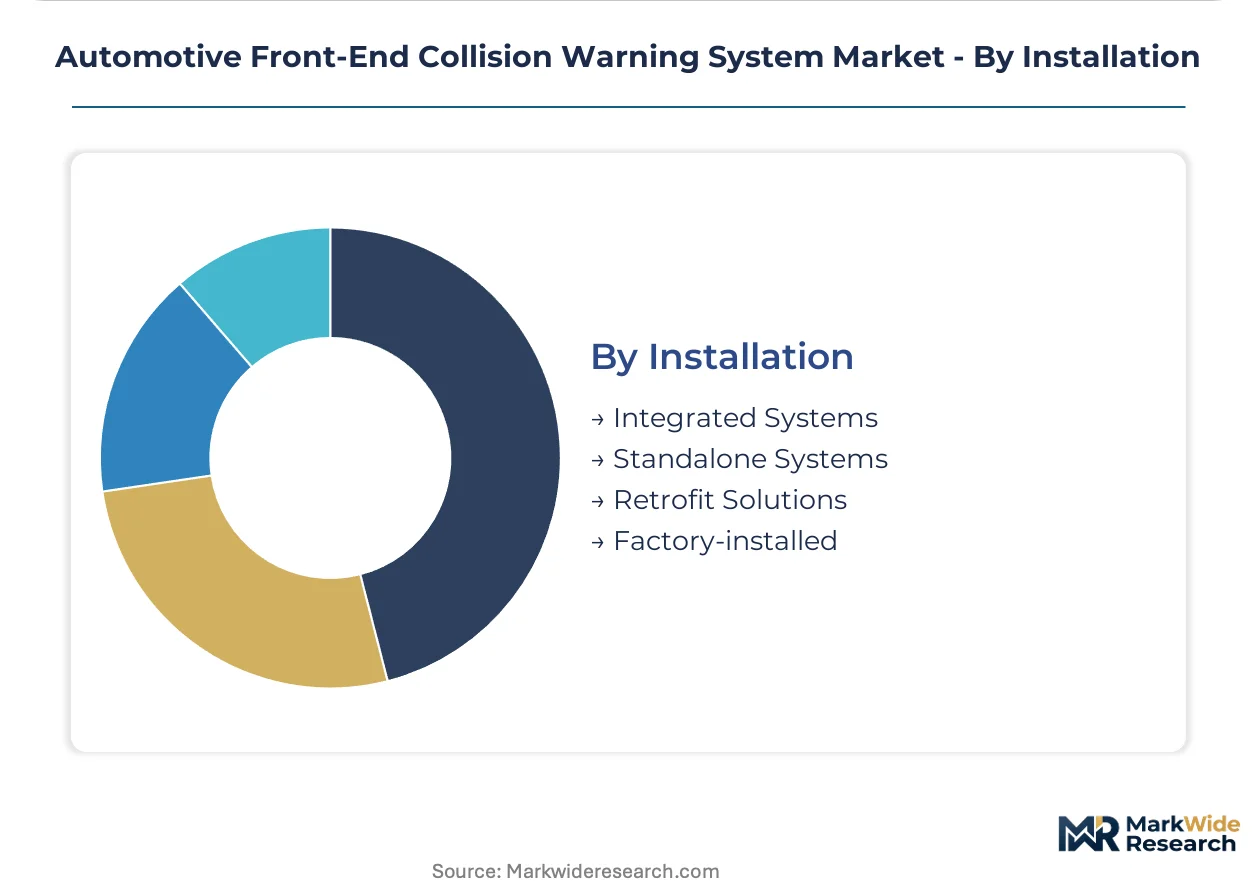
Installation:
Volume concentration favors pre-production integration, with retrofit channels constrained by legacy electrical architecture limitations.
- Factory-installed:Embedded ADAS suite integration captures majority value as OEMs consolidate warning capabilities within comprehensive perception platforms rather than discrete options. CAN-FD and Ethernet backbone requirements in newer vehicle generations favor original equipment placement.
- Integrated Systems:Multi-sensor fusion modules ship as unified hardware-software combinations from Tier-1 suppliers to assembly lines.
- Standalone Systems:Single-sensor alert units serve price-sensitive market segments with limited functionality.
- Retrofit Solutions:CAN bus compatibility constraints and calibration complexity limit addressable fleet penetration in older platforms.
Factory-installed configurations command the established base. The steepest expansion runs through Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sensor fusion modules to European, North American, and Asian OEM assembly plants. This trade corridor concentrates high-value manufacturing in German industrial clusters while distributing finished vehicles across consumer markets.
United States
Commercial fleet operators prioritize radar-dominant configurations to satisfy NHTSA New Car Assessment Program requirements for coverage renewals. The Department of Transportation enforces automatic emergency braking mandates for heavy trucks through FMCSA regulations. Michigan's automotive corridor hosts validation facilities where Tier-1 suppliers test integrated radar-camera systems against federal protocols.
Germany
Bosch, Continental, and ZF manufacture 77 GHz radar chipsets and fusion modules from concentrated R&D footprints in Baden-Württemberg and Lower Saxony. The EU General Safety Regulation mandates advanced driver assistance systems as baseline equipment across passenger and commercial categories. Stuttgart anchors development activity for electromagnetic sensing architectures serving premium OEM programs.
China
Domestic OEMs accelerate localization of LiDAR and radar production to satisfy MIIT connected-vehicle standards for documented sensor performance. The Ministry of Industry and Information Technology conditions market access on software validation protocols and cybersecurity certification. Shanghai's Yangtze River Delta cluster hosts emerging solid-state LiDAR fabricators supplying mass-market electric vehicle platforms.
Japan
Denso and other Tier-1 suppliers integrate forward collision warning within comprehensive ADAS suites for domestic and export vehicle programs. METI guidelines establish performance benchmarks for pedestrian detection and cut-in scenario validation. Aichi Prefecture's Chubu region maintains concentrated electronics manufacturing for camera-based perception systems.
India
MIIT-aligned regulations are conditioning market access on documented sensor performance, creating first-mover advantage for validated platform suppliers. The Ministry of Road Transport and Highways advances mandatory fitment timelines for commercial vehicles under Bharat NCAP adoption. Tamil Nadu's Sriperumbudur-Oragadam belt hosts assembly operations where OEMs integrate imported radar modules with localized camera production.
Automotive Front-End Collision Warning System Market Competitive Environment
On the supply side, the industry is consolidating around full-stack ADAS providers rather than discrete sensor vendors. Tier-1 suppliers with in-house semiconductor development and integrated manufacturing footprints command pricing power over camera-only specialists. Two strategic archetypes dominate: diversified automotive electronics conglomerates with captive radar production, and vision-processing specialists with proprietary silicon architectures. Competitive moves center on backward integration into 77 GHz chipset fabrication and strategic partnerships with solid-state LiDAR developers.
Among German-based diversified suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG exemplify the integrated manufacturing archetype through concentrated sensor fusion module production. Mobileye N.V. occupies a distinct position as a vision-processing specialist anchoring its competitive posture through proprietary EyeQ processor architectures. These named entities represent the structural division between electromagnetic sensing generalists and optical computing specialists competing for platform specification wins across OEM portfolios.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Mobileye N.V. |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Denso Corporation |
| Valeo SA |
| Autoliv Inc. |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
German Tier-1 manufacturing clusters for 77 GHz radar chipsets and sensor fusion modules anchor margin capture at the component level, concentrating pricing power among Bosch, Continental, and ZF while OEMs and aftermarket distributors compete downstream on volume scale and installation efficiency.
Pricing Analysis
Frequency-modulated continuous-wave radar modules at 76-81 GHz carry 40-60% premiums over legacy 24 GHz units, while solid-state LiDAR prototypes trade at 3-4x camera-only system costs despite collapsing mechanical complexity. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated ASIL-D certified platforms from aftermarket alert-only retrofit kits. Cost compression in camera-dominant tiers is intensifying because Tier-1 suppliers are shipping radar fusion at mass-market price points previously reserved for luxury segments. Fleet operators in North America exhibit highest price sensitivity due to insurance-backed financing constraints, while German premium OEMs absorb certification premiums without volume negotiation.
Supply Chain Analysis
Silicon germanium wafer supply and CMOS image sensor fabrication feed from concentrated footprints in Taiwan, South Korea, and Germany, with 77 GHz radar MMIC production anchored in Baden-Württemberg foundries. Automotive-grade semiconductor packaging draws from Malaysian and Vietnamese assembly operations, while optical lens modules source from Japanese precision glass manufacturers. Single-source vulnerability concentrates in German radar chipset fabrication where Bosch, Continental, and ZF maintain captive production. Distribution runs through Tier-1 direct OEM supply contracts with limited aftermarket channel penetration due to CAN-FD compatibility constraints in legacy vehicle architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive front-end collision warning systems are recovering from cyclical lows as commercial fleet replacement cycles and EU regulatory mandates synchronize demand inflection across OEM and aftermarket channels.
For Market Incumbents: Harden ASIL-D certification portfolios against emerging solid-state LiDAR entrants by accelerating backward integration into 77 GHz semiconductor fabrication. Lock in multi-year OEM platform specifications before NHTSA heavy-truck mandates fully phase in. Defensive consolidation around radar-LiDAR fusion architectures preserves specification wins as camera-only suppliers face displacement. For New Entrants and Emerging Players: India's Tamil Nadu assembly belt offers underpenetrated retrofit opportunity where MIIT-aligned regulations are conditioning market access on documented sensor performance. Target insurance telematics bundling partnerships for legacy commercial fleets in North America where capital expenditure constraints favor usage-based policy integration. Solid-state LiDAR cost curves enable white-space entry into mid-range electric vehicle platforms ahead of mass-market price parity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding captive radar production but lacking software-defined vehicle integration capabilities. Five-to-ten year viability hinges on EyeQ-class processor architecture control or Tier-1 fusion module specification dominance. Watch for divergence between regional pedestrian detection test protocols as signal for engineering resource strain and M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Camera Fusion Platform Standardization | Continental AG leverages integrated German production to compress cost tiers across European OEM programs. |
| 77 GHz Semiconductor Backward Integration | Robert Bosch GmbH anchors margin control through in-house chipset fabrication for electromagnetic sensing modules. |
| Solid-State LiDAR Manufacturing Scale-Up | Shanghai Yangtze River Delta cluster hosts emerging fabricators supplying mass-market electric vehicle platforms. |
| Insurance Telematics Channel Partnership | North American fleet operators adopt usage-based policy bundling to displace traditional retrofit capital expenditure. |
| ASIL-D Functional Safety Certification Investment | ISO 26262 validation timelines extend development cycles and strain engineering resource allocation across suppliers. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations heads, and commercial fleet maintenance managers and refined through secondary validation against vehicle production databases, IHS Markit registration data, NHTSA NCAP test protocols, and EU General Safety Regulation implementation timelines. Bottom-up unit economics modeling triangulated against top-down OEM ADAS penetration assumptions across passenger and commercial vehicle segments.
Demand-supply-balance framing anchored volume projections across the analysis window, with segmentation modeled by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from S-curve adoption dynamics for automatic emergency braking mandates and fleet replacement cycle synchronization. Industry-specific inputs included NHTSA heavy-truck rulemaking timelines and EU type-approval protocol divergence for cut-in scenario validation.
Practitioners should monitor solid-state LiDAR cost curve trajectories and German supply concentration risk for early signals of forecast revision. Cross-checking against IHS Markit vehicle production forecasts and NHTSA compliance filing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market