
 Automotive Radar Market | 2026-2036
Automotive Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radar Market Analysis
The capability gap between silicon foundry ownership and fabless design is redrawing competitive boundaries in automotive radar. Infineon Technologies AG leverages captive gallium-nitride capacity to anchor its long-range radar module supply. Robert Bosch GmbH sustains integrated manufacturing from MMIC design to antenna-in-package assembly, controlling cost structures that fabless rivals struggle to match. Continental AG differentiates through its 4D imaging radar architecture, positioning the supplier for premium autonomous vehicle programs.
Automotive radar denotes radio-frequency sensors operating in the 77-81 GHz band that transmit millimeter-wave signals and process reflected echoes to detect object range, velocity, and azimuth. These devices typically integrate multiple transmit-receive channels, digital beamforming processors, and automotive-grade Ethernet outputs to feed fusion algorithms in central domain controllers. Long-range radar dominates highway-speed adaptive cruise control applications where detection past 200 meters is essential, while imaging radar represents the fastest-expanding product type as angular resolution demands tighten for urban autonomous navigation. Collision avoidance technology captures the largest technology segment share due to regulatory mandates across major vehicle markets, though blind spot detection applications are gaining traction in commercial truck specifications where side-object warning reduces lane-change incidents.
The U.S. NHTSA automatic emergency braking mandate for light vehicles and the EU's General Safety Regulation requiring intelligent speed assistance and lane-keeping systems are structurally expanding radar fitment rates across vehicle classes. China's SAMR and MIIT enforce GB standards for electromagnetic compatibility and radio spectrum allocation that condition market access for foreign radar suppliers. Japan's METI coordinates 79 GHz band harmonization with U.S. FCC frameworks, reducing engineering fragmentation for multi-market platform programs. Stakeholders must monitor spectrum reallocation proceedings and NCAP protocol revisions to anticipate sensor specification shifts before design-lock commitments.
Market Dynamics
The automotive radar sector is undergoing a fundamental restructuring as frequency-modulated continuous-wave architectures replace legacy pulse-Doppler designs, forcing module suppliers to retool manufacturing lines and requalify antenna-in-package assemblies for 77-81 GHz operation.
Growth Catalysts
- NCAP Safety Mandates:Euro NCAP and U.S. NHTSA protocols now require automatic emergency braking and lane-keeping systems as baseline for five-star ratings, compelling OEMs to fit radar across vehicle trim levels regardless of brand positioning.
- 79 GHz Spectrum Harmonization:Japan's METI alignment with U.S. FCC band allocation reduces engineering fragmentation for multi-market platform programs, cutting validation cycles for tier-1 suppliers serving trans-Pacific vehicle architectures.
- Silicon-Germanium BiCMOS:This semiconductor process enables cost-effective integration of RF front-ends with digital signal processors, democratizing radar deployment into economy-class vehicle segments previously served by ultrasonic parking sensors alone.
Market Restraints
- Gallium Nitride Wafer Supply:Captive GaN capacity concentrates among three foundry operators, creating input bottlenecks for high-power long-range radar modules when automotive demand spikes.
- Electromagnetic Compatibility Testing:China's GB standards for radio spectrum allocation impose lengthy certification timelines that delay foreign supplier market entry by 12-18 months versus domestic competitors.
- LiDAR Convergence Threat:Solid-state LiDAR price curves are compressing faster than projected, threatening radar's cost advantage in premium autonomous vehicle sensor suites above Level 3 automation.
Strategic Opportunities
- Commercial Vehicle Underserved Demand:Heavy truck blind-spot detection remains below 40% fitment rates in India and Brazil, creating white space for radar suppliers with temperature-hardened modules.
- 4D Imaging Radar Architectures:Elevation-angle resolution enables direct height measurement of objects, opening replacement opportunities for short-range LiDAR in urban autonomous navigation stacks.
- EU General Safety Regulation Phase-In:Intelligent speed assistance mandates effective 2024-2026 create regulatory pull for radar-camera fusion systems across European passenger vehicle platforms.
Industry Challenges
- RF Simulation Talent Scarcity:Electromagnetic modeling expertise for millimeter-wave antenna design concentrates among aging specialists in Germany and Japan, constraining module supplier expansion.
- Domain Controller Integration Complexity:Centralized zonal E/E architectures demand raw radar data transmission over automotive Ethernet rather than processed object lists, forcing firmware rearchitecture.
- Functional Safety Certification Burden:ISO 26262 ASIL-B compliance for radar signal processing chains requires redundant compute paths that inflate silicon area and thermal budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radar Market |
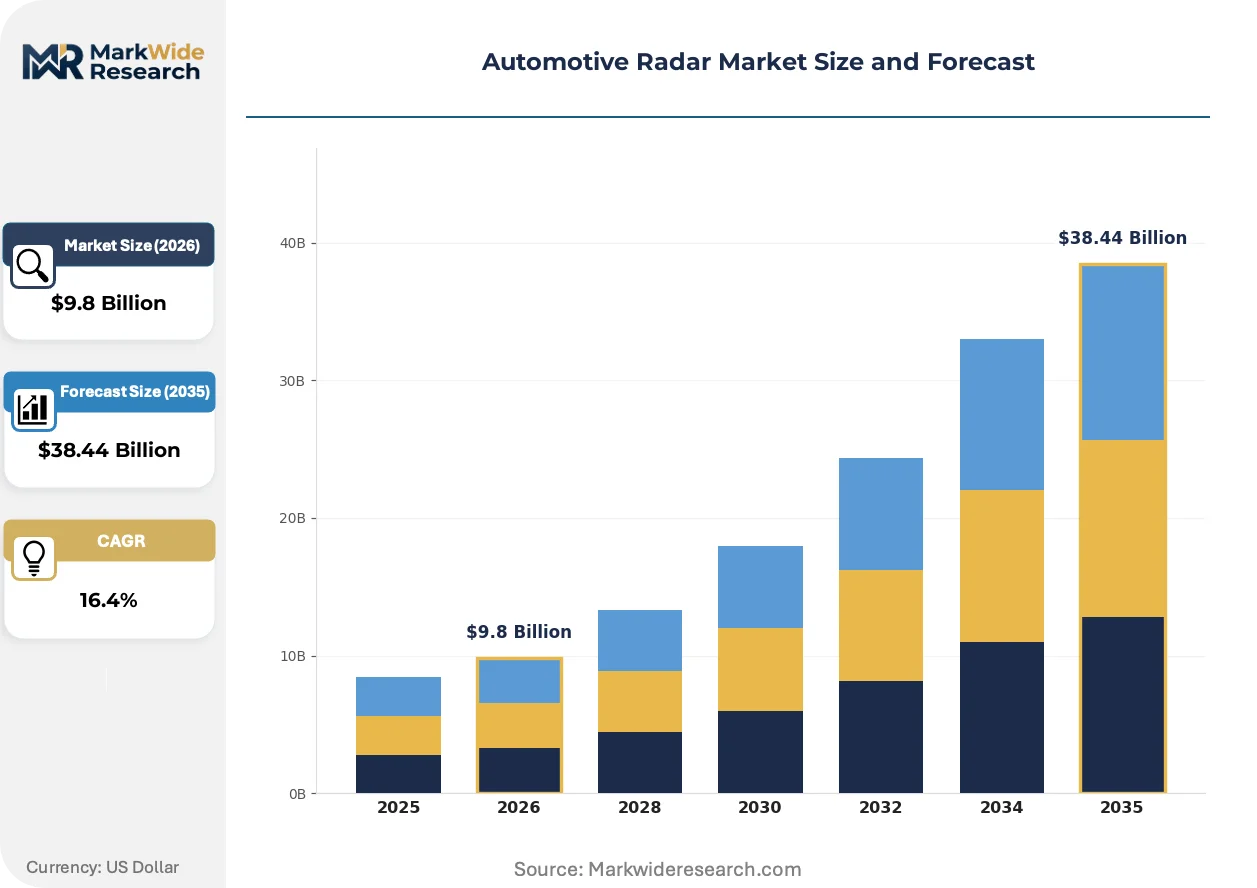
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Range Radar, Short-Range Radar, Medium-Range Radar, Imaging Radar Technology: Adaptive Cruise Control, Collision Avoidance, Blind Spot Detection, Lane Change Assistance End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Safety Systems, Autonomous Vehicles, Driver Assistance, Fleet Management |
| Companies Covered | Denso Corporation, Infineon Technologies AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Valeo, Continental AG, NXP Semiconductors, Texas Instruments, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radar Market Emerging Trajectories
Automotive radar is pivoting from discrete sensor modules to software-defined perception nodes, with algorithmic differentiation displacing hardware specifications as the primary competitive battleground.
Silicon-germanium BiCMOS is supplanting gallium arsenide MMICs in mid-range radar applications by integrating RF transceivers with baseband processors on single die. Tier-1 suppliers serving mass-market OEMs have accelerated adoption timelines, with platform commitments now spanning 2026-2030 vehicle generations. This semiconductor transition is compressing bill-of-material costs while enabling digital beamforming capabilities previously reserved for premium imaging radar tiers.
China's MIIT connected-vehicle testing guidelines are mandating V2X interoperability certification for radar sensors deployed in intelligent transportation system corridors. This regulatory requirement is forcing foreign suppliers to open firmware interfaces for local telematics integration that they previously guarded as proprietary. Urban autonomous shuttle programs in Beijing and Shanghai are the most affected segments, with design-lock commitments now contingent upon MIIT field-test validation.
Fleet procurement of radar-equipped vehicles is tilting toward total cost of ownership calculations that weight sensor reliability and calibration intervals more heavily than upfront module pricing. Rental car operators and ride-hail platforms are displacing traditional retail buyer influence in specification-setting for Level 2+ automation packages. This behavior shift is most visible in North American and European commercial fleet renewals, where procurement committees now demand predictive maintenance telemetry from radar units.
Automotive Radar Market Segmentation
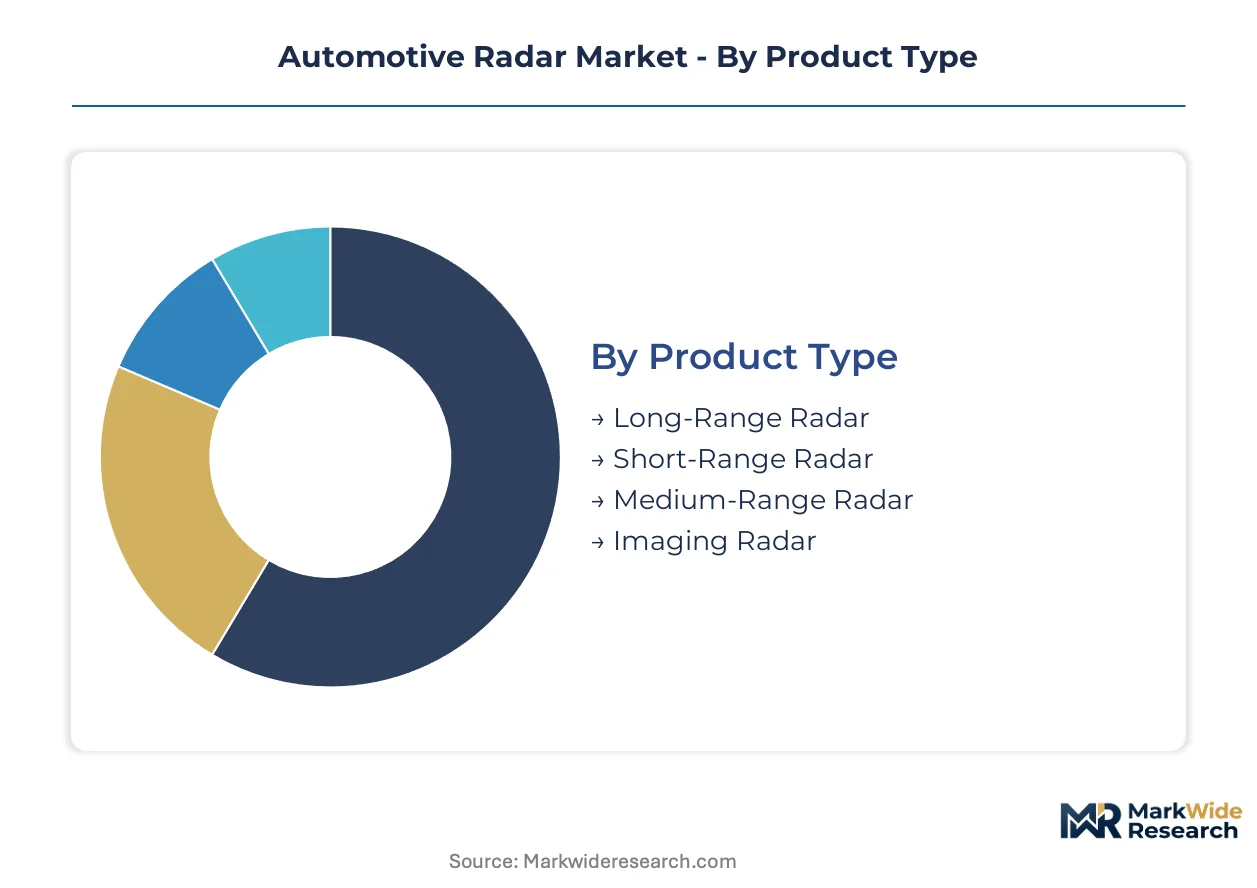
Automotive radar segmentation reveals how sensor specifications diverge across vehicle automation tiers and regulatory environments. Suppliers must align module architectures with distinct performance ceilings and cost constraints embedded in each category.
Product Type:
Imaging radar faces the most acute substitution pressure from solid-state LiDAR in premium autonomous stacks, while long-range modules defend their position through highway-speed detection requirements that optical sensors struggle to match.
- Long-Range Radar:Detects objects beyond 200 meters using narrow beamwidths and high transmit power for adaptive cruise control at highway velocities. German KBA type-approval protocols mandate this capability for automatic emergency braking systems, cementing fitment across European passenger vehicle platforms regardless of trim level.
- Imaging Radar:Deploys dense antenna arrays and digital beamforming to resolve elevation angles alongside azimuth and range, enabling height discrimination for urban navigation. China's MIIT connected-vehicle testing guidelines in Beijing and Shanghai corridors are accelerating validation timelines for 4D architectures that replace short-range LiDAR in robotaxi sensor suites.
- Short-Range Radar:Covers 0-30 meter detection zones with wide field-of-view for parking assistance and cross-traffic alert functions.
- Medium-Range Radar:Bridges gap coverage for urban adaptive cruise and intersection assistance with 30-100 meter range envelopes.
Long-range radar retains volume leadership; imaging radar holds the steepest expansion curve.
Technology:
Cost tier differentiation separates collision avoidance as the regulatory-mandated baseline from lane change assistance as the discretionary upgrade path.
- Collision Avoidance:Integrates automatic emergency braking algorithms with radar object tracking to meet NCAP five-star thresholds. U.S. NHTSA mandates for light vehicles and EU General Safety Regulation requirements are structurally expanding fitment rates across economy through premium vehicle classes.
- Blind Spot Detection:Monitors adjacent lanes through rear-corner radar placement, with commercial truck specifications in India and Brazil driving temperature-hardened module demand for side-object warning systems that reduce lane-change incidents.
- Adaptive Cruise Control:Maintains set following distances through longitudinal radar tracking, predominantly deployed via long-range front-facing modules.
- Lane Change Assistance:Combines blind spot radar with steering intervention capabilities, gaining traction in European fleet procurement where total cost of ownership calculations favor predictive maintenance telemetry.
Collision avoidance commands the largest installed base; blind spot detection is climbing the fastest in commercial vehicle penetration.
End User:
Supply concentration favors integrated manufacturers over fabless designers in the current procurement cycle.
- Tier-1 Suppliers:Dominate module assembly through captive semiconductor capacity and antenna-in-package integration, with Robert Bosch GmbH and Continental AG controlling cost structures that fabless rivals struggle to match.
- OEMs:Specify radar performance requirements directly for flagship autonomous programs while outsourcing volume production to tier-1 partners.
- Aftermarket Providers:Serve vehicle retrofit segments with calibration-dependent add-on systems for aging fleet renewal.
- Vehicle Assemblers:Integrate radar modules during final assembly line sequencing for regional platform variants.
Tier-1 suppliers retain volume leadership; OEM direct procurement holds the steepest expansion curve for imaging radar programs.
Application:
Customer type divergence separates safety system mandates from autonomous vehicle discretionary investment.
- Safety Systems:Encompasses regulatory-mandated automatic emergency braking and lane-keeping support where radar-camera fusion is becoming the default architecture.
- Autonomous Vehicles:Demands imaging radar with raw data output for centralized domain controller processing, requiring firmware rearchitecture for automotive Ethernet transmission.
- Driver Assistance:Covers Level 2 automation features where processed object lists suffice for vehicle control systems.
- Fleet Management:Weighs sensor reliability and calibration intervals in total cost of ownership calculations for rental and ride-hail platform procurement.
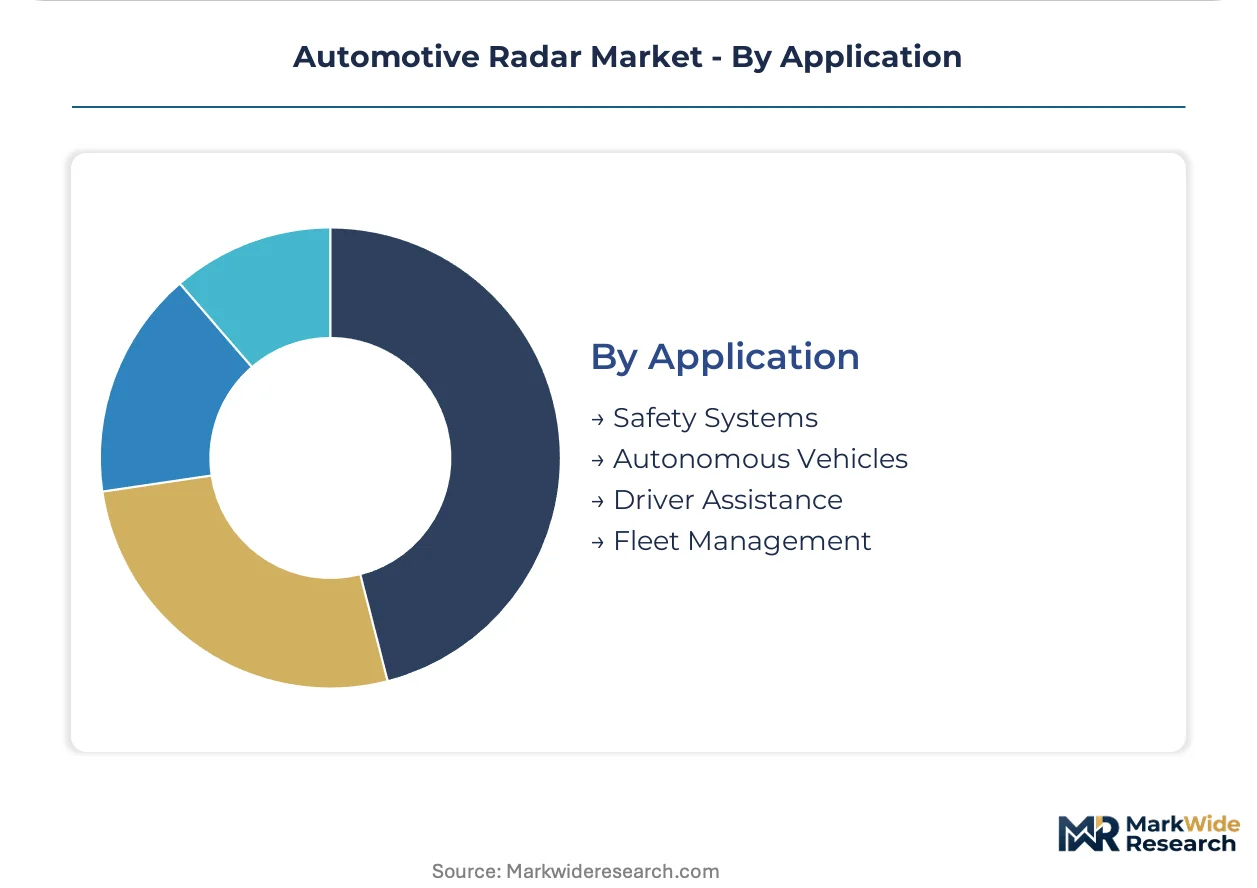
Safety systems retain volume leadership; autonomous vehicle applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Japanese module suppliers while Chinese domestic vendors compete on volume. North American procurement committees favor predictive maintenance telemetry in fleet specifications. European regulatory mandates create the steepest compliance-driven demand curves.
United States
NHTSA automatic emergency braking mandates for light vehicles and fleet procurement by rental operators drive sensor deployment. FCC 79 GHz spectrum harmonization with Japan reduces engineering fragmentation for trans-Pacific platforms. Detroit-area automotive clusters and Austin semiconductor corridors anchor tier-1 supplier engineering centers.
Germany
KBA type-approval protocols for radar-based systems and premium OEM autonomous programs sustain long-range module demand. EU General Safety Regulation intelligent speed assistance mandates accelerate radar-camera fusion adoption. Stuttgart and Ingolstadt industrial corridors concentrate captive semiconductor capacity and antenna-in-package assembly.
China
MIIT connected-vehicle testing guidelines and SAMR electromagnetic compatibility standards condition market access for foreign suppliers. GB radio spectrum allocation creates certification timelines that domestic competitors navigate faster. Beijing and Shanghai intelligent transportation corridors validate 4D imaging radar for urban autonomous shuttle programs.
Japan
METI 79 GHz band alignment with U.S. frameworks and aging demographic pressure for collision avoidance sustain fitment rates. JIS standards harmonization reduces validation cycles for multi-market architectures. Nagoya automotive clusters and Tokyo Bay manufacturing zones anchor MMIC design-to-assembly integration.
South Korea
Domestic OEM Level 2+ automation roadmaps and government-funded autonomous shuttle pilots drive imaging radar procurement. MFDS automotive safety system coordination aligns with export market regulatory requirements. Seoul Capital Area and Busan-Ulsan industrial corridors concentrate module supplier technical centers.
Automotive Radar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive semiconductor capacity control premium long-range radar segments while fabless designers compete on silicon-germanium BiCMOS cost curves. Three archetypes dominate: vertically integrated module suppliers, semiconductor-focused component vendors, and system integrators with antenna-in-package capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for 2026-2030 platform commitments.
Within the integrated manufacturing tier, Robert Bosch GmbH and Continental AG exemplify archetypes combining MMIC design with antenna-in-package assembly. Infineon Technologies AG anchors the semiconductor-centric vector through captive gallium-nitride capacity. These three entities represent distinct strategic positions: full-stack module control, imaging radar architecture specialization, and RF front-end semiconductor supply respectively.
| Leading Market Players |
|---|
| Denso Corporation |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Valeo |
| Continental AG |
| NXP Semiconductors |
| Texas Instruments |
| Aptiv |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with gallium-nitride foundries lock in both semiconductor supply access and cost visibility for tier-1 radar module suppliers serving European and North American OEM platforms through 2030.
Pricing Analysis
The customization-premium spread between configured-to-order imaging radar and standard long-range modules runs wide, with three-tier pricing structure across premium, standard, and economy levels separating 4D architectures from highway-speed cruise control units. Price differentiation hinges on ISO 26262 ASIL-B certification grade and volume scale commitments from OEM platform engineers. Cost compression in mid-range segments is intensifying because silicon-germanium BiCMOS process adoption democratizes RF front-end integration. Fleet procurement committees exhibit the highest price sensitivity, while premium autonomous vehicle programs remain least sensitive due to performance-tier specifications.
Supply Chain Analysis
Inventory buffers for GaN wafers and antenna-in-package substrates stretch lead times when automotive demand spikes exceed foundry capacity planning. Supply concentrates in Germany, Japan, and Taiwan for MMIC fabrication and module assembly. Raw material dependencies center on gallium-nitride substrates, silicon-germanium wafers, and automotive-grade epoxy molding compounds. Single-source vulnerability in captive GaN capacity creates bottleneck risk when three foundry operators serve simultaneous OEM program ramps. Distribution runs through tier-1 supplier direct channels to OEM platform engineering teams, bypassing traditional aftermarket wholesalers for original fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive radar sits in early-cycle expansion as NCAP safety mandates structurally lift fitment rates from luxury into economy vehicle segments regardless of buyer automation preference.
For Market Incumbents: Fortify captive semiconductor capacity through backward integration into gallium-nitride wafer supply or exclusive foundry partnerships, insulating margin structures from input bottlenecks when demand spikes. Deepen antenna-in-package assembly scale in Stuttgart and Ingolstadt corridors to match Bosch and Continental cost positions that fabless rivals cannot replicate. Prioritize ISO 26262 certification investment as regulatory baseline hardens. For New Entrants and Emerging Players: Anchor in commercial vehicle blind-spot detection for heavy trucks in India and Brazil, where fitment rates sit below 40 percent and temperature-hardened module demand outstrips established supplier focus. Target 4D imaging radar firmware architecture for urban autonomous shuttle programs in Beijing and Shanghai corridors where MIIT V2X interoperability requirements force incumbent interface opening. Lead with predictive maintenance telemetry value proposition for fleet procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated module suppliers with captive MMIC design and antenna-in-package assembly, or semiconductor-focused component vendors with gallium-nitride process ownership. Long-term viability favors entities controlling upstream supply inputs through 2030 platform commitment windows. Watch for LiDAR price curve compression as inflection signal threatening radar's cost advantage in Level 3+ sensor suites.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation with GaN Foundries | Locks in semiconductor supply access for tier-1 suppliers serving 2026-2030 OEM platform commitments. |
| Antenna-in-Package Scale Expansion | Consolidates cost position in Germany's industrial corridors against fabless module competitors. |
| 4D Imaging Radar Firmware Architecture | Opens replacement opportunities for short-range LiDAR in Beijing and Shanghai autonomous shuttle programs. |
| ISO 26262 ASIL-B Certification Investment | Meets EU General Safety Regulation functional safety mandates for radar signal processing chains. |
| Predictive Maintenance Telemetry Integration | Aligns with North American and European fleet procurement TCO calculations favoring sensor reliability. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and semiconductor foundry planning officers; and secondary validation through vehicle production databases, IHS Markit registration data, NHTSA mandate documentation, and MIIT connected-vehicle testing guidelines. Bottom-up unit economics triangulated against top-down market sizing across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation.
Across the projection horizon, the analytical framework modeled volume and value outputs through driver-assistance penetration curves, regulatory mandate phase-in schedules, and semiconductor process transition timelines. CAGRs derived from segment-level build-up analysis incorporating NCAP protocol revision impacts, fleet procurement behavior shifts, and LiDAR substitution threat trajectories. Industry-specific forecast inputs included GB standards certification timelines for China market access and KBA type-approval protocol requirements for European platform compliance.
Material uncertainties — spectrum reallocation proceedings, GaN wafer supply disruptions, and solid-state LiDAR price compression trajectories — sit outside the modeled envelope and could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market