
 Automatic Emergency Braking System (AEBS) Market | 2026-2036
Automatic Emergency Braking System (AEBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Emergency Braking System (AEBS) Market Insights
Germany is rewriting the competitive map for AEBS manufacturing through expanded radar sensor production corridors near Stuttgart and Munich. Robert Bosch GmbH leverages backward integration into semiconductor supply chains to secure component availability. Continental AG anchors European OEM relationships through dedicated engineering centers in Wolfsburg and Ingolstadt. ZF Friedrichshafen AG dominates heavy-duty commercial vehicle braking systems with specialized actuator platforms.
Automatic Emergency Braking Systems deploy fused sensor architectures combining radar emitters, stereo cameras, and control modules to detect imminent collisions and autonomously apply braking force. The technology operates through millimeter-wave radar operating at 77 GHz paired with image-processing algorithms to classify obstacles and calculate stopping distances. Collision Avoidance Systems command the largest revenue pool among product types due to premium pricing on integrated sensor suites. Camera-Based technology represents the fastest-expanding segment as neural network processing costs decline and automakers pursue vision-first strategies. Passenger Vehicles absorb the majority of OEM installation volumes, though Commercial Fleets generate superior per-unit margins through fleet-wide retrofitting contracts.
NHTSA mandates phased AEBS requirements for passenger vehicles and light trucks, while the EU General Safety Regulation mandates intelligent speed assistance and automatic emergency braking across all new vehicle categories. ISO 26262 functional safety standards govern software integrity levels for AEBS control modules, creating certification barriers for new entrants. Stakeholders must monitor evolving NCAP rating protocols, as five-star safety scores increasingly depend on pedestrian and cyclist detection capabilities rather than vehicle-to-vehicle scenarios alone.
Market Dynamics
Fleet operators are accelerating collision avoidance investments as liability exposure from rear-end incidents reshapes total cost of ownership calculations across commercial vehicle portfolios.
Growth Catalysts
- NHTSA Mandates:Phased automatic emergency braking requirements for passenger vehicles and light trucks are compelling OEMs to standardize AEBS across model lineups, eliminating optional equipment strategies.
- Commercial Fleet Liability:Insurance carriers are attaching premium reductions to verified AEBS installations, creating direct financial incentives for retrofitting existing heavy-duty vehicles.
- 77 GHz Radar Proliferation:Millimeter-wave sensor costs have compressed sufficiently to enable multi-radar architectures that previously required single-sensor compromises.
Market Restraints
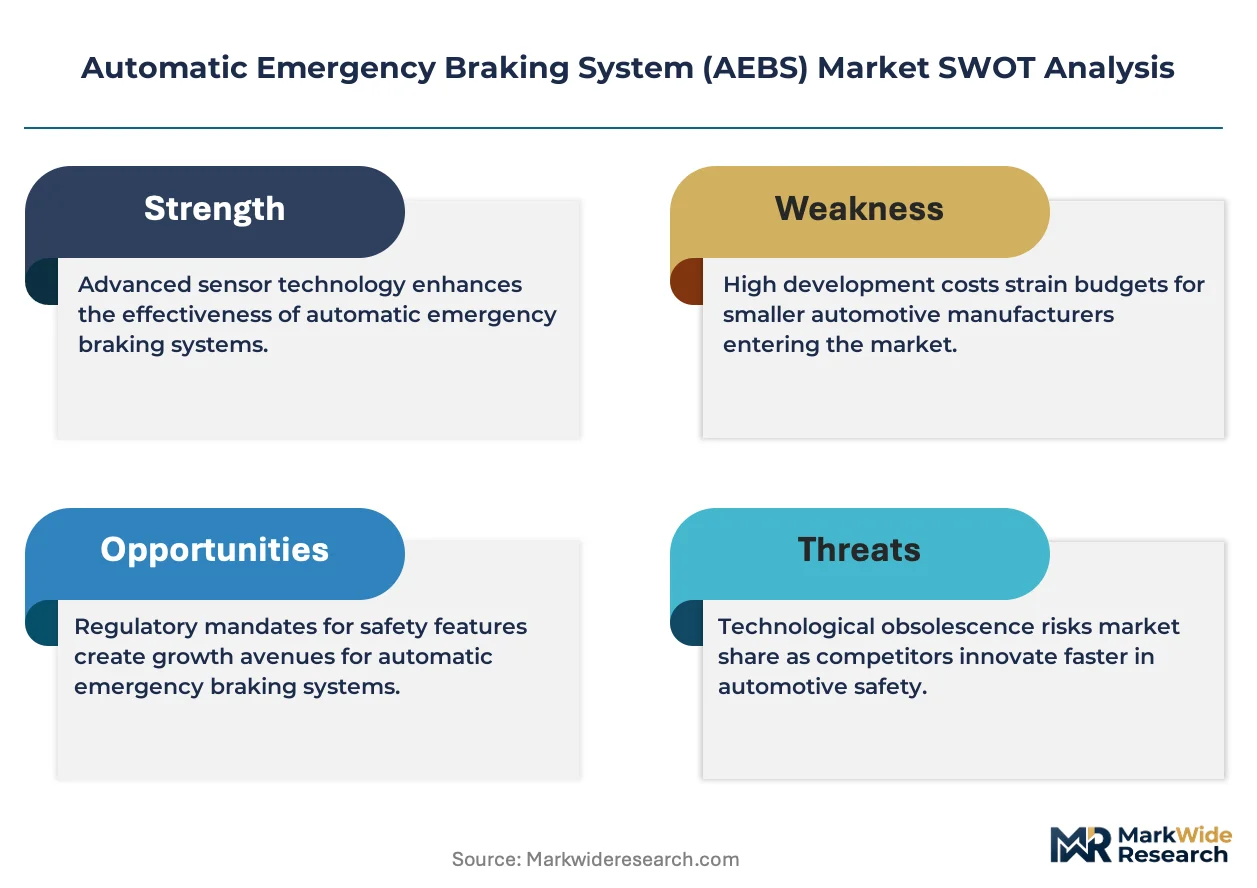
- Semiconductor Supply Concentration:Silicon carbide substrates and radar-specific ASICs remain concentrated among Taiwanese and German foundries, exposing AEBS module production to single-source vulnerabilities.
- Calibration Infrastructure Gaps:Post-collision sensor realignment requires specialized optical and radar calibration equipment that independent repair networks lack, extending vehicle downtime.
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for braking control modules demands 18-24 month validation cycles that freeze architecture decisions early in development programs.
Strategic Opportunities
- Aftermarket Fleet Retrofit:Medium-duty commercial vehicles in the United States represent an underpenetrated installed base where plug-and-play AEBS kits bypass OEM integration timelines.
- Camera-First Architectures:Neural network inference costs have fallen sufficiently to enable vision-dominant systems that reduce radar dependency and simplify sensor fusion complexity.
- Pedestrian Detection Mandates:Evolving NCAP protocols that weight vulnerable road user recognition are creating competitive differentiation for stereo camera configurations with enhanced edge-case training.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering and real-time sensor fusion algorithm development require specialized expertise that automotive suppliers compete aggressively to secure.
- Legacy Vehicle Integration Friction:Retrofitting AEBS onto platforms lacking electronic brake boosters or CAN-FD architectures demands mechanical actuator redesigns that compromise performance.
- Homologation Timeline Compression:Divergent NCAP, NHTSA, and UN ECE test protocols force parallel validation programs that strain engineering bandwidth without harmonization prospects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Emergency Braking System (AEBS) Market |
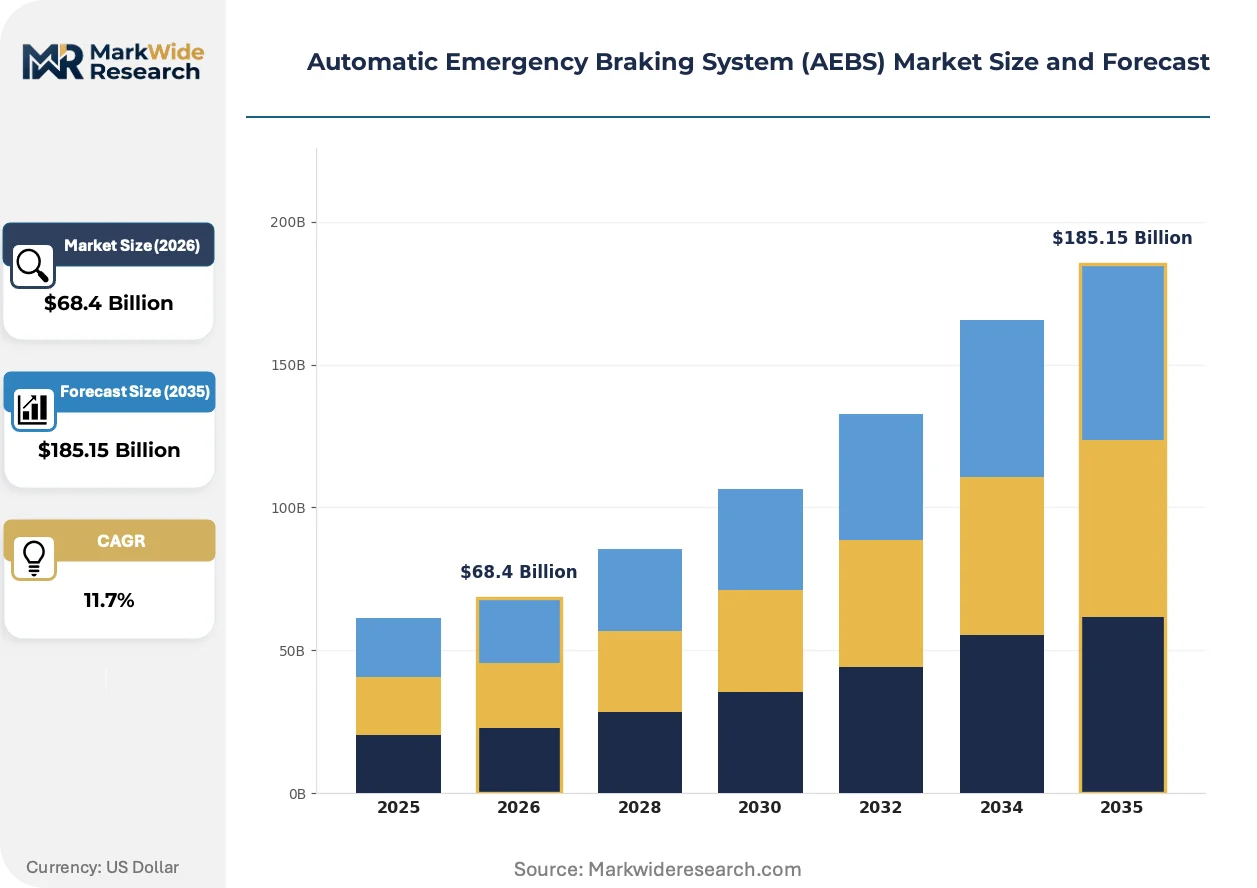
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional AEBS, Collision Avoidance Systems, Adaptive Cruise Control, Integrated Systems End User: Passenger Vehicles, Commercial Fleets, Public Transport, Emergency Services Technology: LiDAR, Radar-Based, Camera-Based, Ultrasonic Sensors Installation Type: OEM, Aftermarket, Retrofitting, Lease Programs |
| Companies Covered | ZF Friedrichshafen AG, Hyundai Mobis, Robert Bosch GmbH, Aisin Seiki Co. Ltd., Valeo SA, Continental AG, Autoliv Inc., Mobileye Global Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Emergency Braking System (AEBS) Market Trends and Innovations
Sensor fusion architectures are compressing cost structures while regulatory test protocols are expanding detection requirements beyond vehicle-to-vehicle scenarios into vulnerable road user recognition.
Radar-centric AEBS designs are migrating from single forward-facing units to distributed corner and rear-facing configurations that enable intersection and reversing collision mitigation. Heavy-duty truck manufacturers are adopting these multi-radar suites most aggressively as trailer blind spots create liability exposure distinct from passenger vehicle use cases. This migration from centralized to distributed sensing is compressing the addressable market for standalone camera suppliers while expanding radar module volumes.
EU General Safety Regulation mandates for intelligent speed assistance and automatic emergency braking are eliminating voluntary adoption pathways across all new vehicle categories including previously exempt heavy goods vehicles. The regulation's 2024 enforcement deadline has compressed supplier qualification timelines and forced parallel engineering tracks for European and non-European vehicle programs. Commercial vehicle segments face the steepest compliance burden as their legacy platform architectures require more extensive braking system modifications.
Fleet procurement departments are consolidating collision avoidance system specifications into master service agreements that span multi-year vehicle replacement cycles. Third-party fleet management providers are displacing direct OEM relationships as the primary specification authority, particularly among national logistics operators with centralized safety departments. This concentration of buying influence is most visible in the United States where large for-hire trucking fleets operate standardized equipment pools across thousands of power units.
Automatic Emergency Braking System (AEBS) Market Segmentation
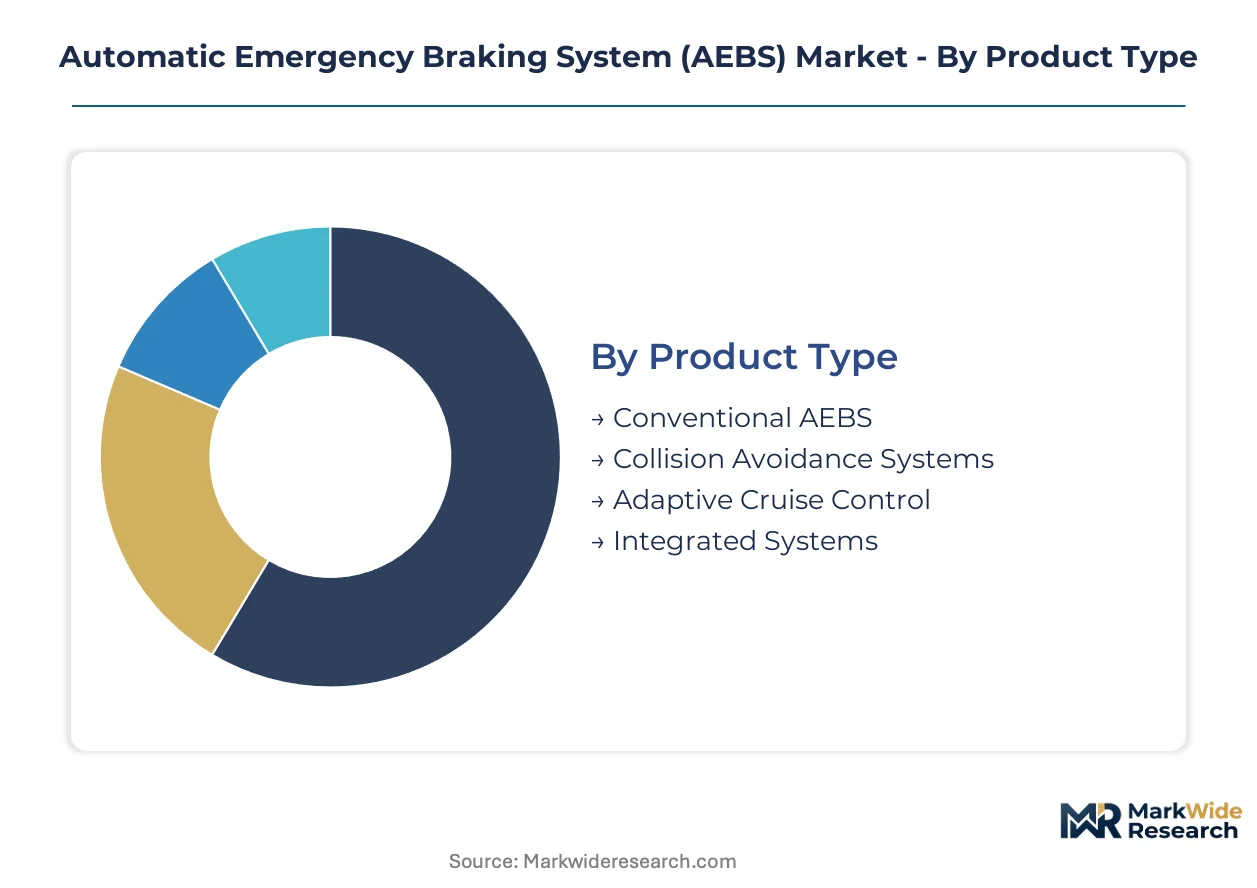
Segmentation in the AEBS market reveals divergent procurement cycles and margin structures across product architectures and customer categories. Fleet operators refresh collision avoidance systems on compressed timelines compared to passenger vehicle OEM programs, while retrofitting channels operate on spot-demand patterns distinct from factory-line integration.
Product Type:
Cycle times vary sharply across product categories, with integrated systems locked to multi-year vehicle development programs while standalone collision avoidance modules turn over on annual fleet procurement schedules.
- Collision Avoidance Systems:Fused sensor architectures combining radar emitters, stereo cameras, and control modules detect imminent collisions and autonomously apply braking force. Demand concentrates in United States commercial fleets where insurance carriers attach premium reductions to verified installations, creating direct financial incentives for heavy-duty vehicle retrofitting.
- Integrated Systems:Factory-embedded AEBS modules synchronized with electronic brake boosters and vehicle stability control operate through centralized domain controllers. Passenger vehicle OEMs in Germany and the United States standardize these configurations across model lineups to satisfy NHTSA phased mandates and EU General Safety Regulation requirements.
- Conventional AEBS:Single-sensor radar or camera configurations with discrete control modules predominate in emerging market vehicle platforms.
- Adaptive Cruise Control:Longitudinal speed management systems with integrated emergency braking override functionality serve highway-focused vehicle segments.
Collision Avoidance Systems anchor the volume base while Integrated Systems gains share at the steepest rate.
End User:
Cost tier stratification separates premium OEM installations from mid-market fleet retrofits and economy-grade public transport specifications.
- Commercial Fleets:For-hire trucking operators and national logistics providers specify collision avoidance systems through master service agreements spanning multi-year vehicle replacement cycles. Third-party fleet management providers in the United States displace direct OEM relationships as primary specification authority, consolidating buying influence across standardized equipment pools.
- Passenger Vehicles:Light-duty automotive OEMs absorb the majority of factory-installation volumes through model-year integration programs. NHTSA mandates for automatic emergency braking on new passenger vehicles and light trucks are compelling standardization across domestic manufacturing plants, eliminating optional equipment strategies.
- Public Transport:Municipal bus operators and transit authorities deploy AEBS under procurement frameworks prioritizing pedestrian detection capabilities and vulnerable road user recognition.
- Emergency Services:Police, fire, and ambulance fleets require specialized high-speed collision avoidance calibration distinct from civilian vehicle parameters.
Passenger Vehicles generate the highest absolute installation volumes while Commercial Fleets command superior per-unit margins through fleet-wide contracting.
Technology:
Application-specific performance requirements drive technology selection, with highway-speed scenarios demanding radar precision and urban environments favoring camera classification.
- Camera-Based:Stereo vision systems with neural network processing for obstacle classification and stopping distance calculation. Neural network inference costs have declined sufficiently to enable vision-dominant architectures that reduce radar dependency, with automakers in Germany and the United States pursuing vision-first strategies for cost compression.
- Radar-Based:Millimeter-wave sensors operating at 77 GHz paired with control modules for all-weather detection reliability. Heavy-duty truck manufacturers adopt distributed multi-radar configurations most aggressively as trailer blind spots create liability exposure distinct from passenger vehicle use cases.
- LiDAR:Laser-ranging sensors with centimeter-level precision for complex urban collision scenarios and pedestrian detection edge cases.
- Ultrasonic Sensors:Short-range proximity detection for low-speed reversing and parking collision mitigation in constrained environments.
Radar-Based technology retains the largest installed base while Camera-Based configurations expand most quickly as processing economics shift.
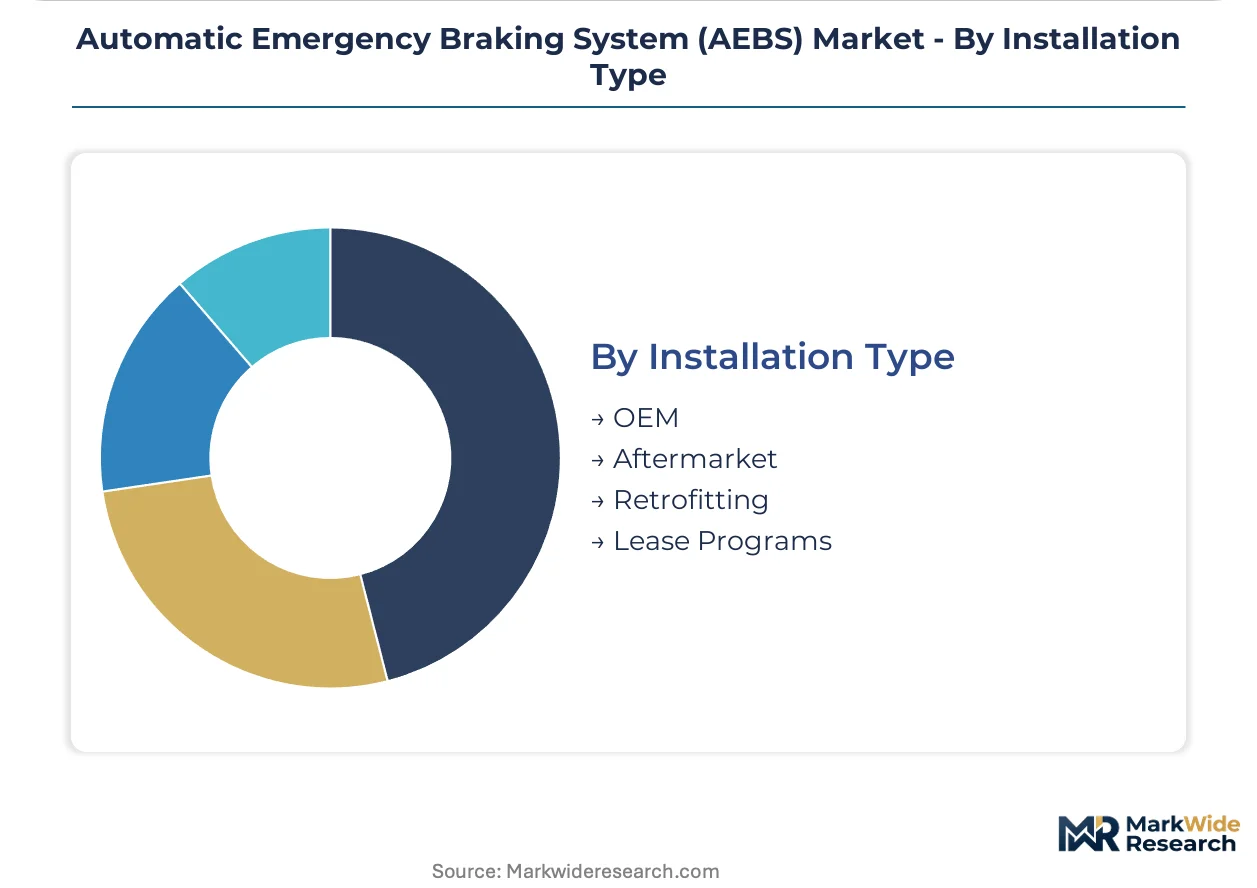
Installation Type:
Customer type fragmentation separates captive OEM supply from independent aftermarket channels with distinct service relationships and technical support requirements.
- OEM:Factory-integrated AEBS modules installed during vehicle assembly with synchronized calibration to electronic brake boosters and CAN-FD architectures. EU General Safety Regulation mandates have compressed supplier qualification timelines for European vehicle programs, forcing parallel engineering tracks.
- Aftermarket:Plug-and-play AEBS kits for medium-duty commercial vehicles bypass OEM integration timelines and address underpenetrated installed bases. United States fleet operators utilize these channels where legacy platforms lack factory-installed collision avoidance capability.
- Retrofitting:Mechanical actuator redesigns for vehicles lacking electronic brake boosters demand specialized integration engineering that compromises performance relative to native installations.
- Lease Programs:Equipment financing structures bundling AEBS installation with vehicle lease terms, transferring specification authority to lessor entities.
OEM installation dominates value capture while Aftermarket retrofitting climbs the fastest as fleet liability exposure reshapes total cost of ownership calculations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for AEBS concentrates in Germany's automotive corridors and the United States' industrial Midwest, with assembly integration spreading to secondary markets as OEMs localize production. Taiwan and Germany dominate semiconductor substrate supply for radar modules, creating geographic chokepoints in the value chain.
United States
NHTSA mandates for automatic emergency braking on passenger vehicles and light trucks compel domestic OEMs to standardize AEBS across model lineups, eliminating optional equipment strategies. The 2024 enforcement timeline for heavy-duty vehicle provisions accelerates supplier qualification programs. Michigan and Ohio manufacturing clusters host brake system integration facilities serving Detroit-based automakers.
Germany
EU General Safety Regulation requirements for intelligent speed assistance and automatic emergency braking compress engineering timelines for European vehicle programs. Stuttgart and Munich corridors anchor expanded radar sensor production serving Continental AG and Robert Bosch GmbH supply chains. Wolfsburg and Ingolstadt engineering centers maintain dedicated OEM relationships for integrated braking system development.
China
Domestic OEM integration programs expand AEBS penetration across local brand passenger vehicles as MIIT guidelines align with UN ECE technical standards. Yangtze River Delta manufacturing bases concentrate camera module assembly for vision-first system architectures. Shanghai-based suppliers develop neural network processing capabilities for cost-optimized pedestrian detection.
Japan
METI industrial policy supports sensor fusion R&D investments as domestic automakers pursue multi-radar configurations for highway-speed collision avoidance. Kanto region electronics clusters produce millimeter-wave radar components for 77 GHz applications. Toyota City and Hiroshima manufacturing networks integrate AEBS with electronic brake booster platforms.
South Korea
Hyundai Motor Group and Kia Corporation standardize AEBS across domestic and export vehicle lines to maintain NCAP five-star ratings. Seoul Capital Area suppliers develop camera-based systems reducing radar dependency for cost compression. Busan-Ulsan automotive corridors host brake actuator manufacturing for heavy-duty commercial vehicle applications.
Automatic Emergency Braking System (AEBS) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in radar emitters, stereo cameras, and control modules. The vendor base separates into consolidated tier-one suppliers with OEM captive relationships and fragmented specialty manufacturers serving aftermarket retrofit channels. Two archetypes dominate: diversified automotive conglomerates with braking system heritage, and vision-technology specialists with neural network processing capabilities. Competitive moves center on backward integration into semiconductor supply chains and multi-radar architecture development for commercial vehicle blind-spot coverage.
Among diversified automotive suppliers, ZF Friedrichshafen AG anchors heavy-duty commercial vehicle braking systems through specialized actuator platforms. Robert Bosch GmbH exemplifies backward integration strategies into semiconductor supply chains for component security. Continental AG represents European OEM relationship depth through dedicated engineering center configurations. These three entities occupy positions spanning integrated system supply and component manufacturing tiers.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Robert Bosch GmbH |
| Aisin Seiki Co. Ltd. |
| Valeo SA |
| Continental AG |
| Autoliv Inc. |
| Mobileye Global Inc. |
| Denso Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwanese silicon carbide foundries and German radar ASIC suppliers determines both pricing tier spreads and supply chain shape across AEBS module production. NHTSA mandate compression forces OEMs to absorb premium pricing for qualified components while fleet retrofitters face spot-market volatility in sensor availability.
Pricing Analysis
EU General Safety Regulation dictates the pricing tier structure across factory-integrated, fleet-retrofit, and aftermarket kit configurations. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified OEM modules from fleet retrofit bundles and uncertified emerging-market alternatives. Cost compression in camera-dominant architectures is intensifying because neural network inference silicon prices are falling faster than radar component costs. Fleet procurement departments exhibit highest price sensitivity through consolidated master service agreements, while passenger vehicle OEMs accept premium positioning to secure five-star NCAP ratings.
Supply Chain Analysis
TSMC and GlobalFoundries hold concentrated capacity for 77 GHz radar ASIC fabrication serving Continental AG and Robert Bosch GmbH module production. Taiwan, Germany, and South Korea anchor component supply for millimeter-wave substrates, stereo camera sensors, and electronic brake boosters respectively. The supply chain draws from silicon carbide wafers, radar-specific semiconductors, and automotive-grade control module housings as critical inputs. Single-source vulnerability in Taiwanese foundry exposure creates tariff and geopolitical risk without qualified secondary sources. Distribution runs through captive OEM supply agreements and independent aftermarket channels with distinct technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-first perception systems and insurance-telematics bundling threaten incumbent radar-centric suppliers with functional substitution, demanding defensive repositioning around sensor fusion integration depth.
For Market Incumbents: Insulate market position through backward integration into semiconductor supply chains and captive radar sensor production corridors near Stuttgart and Munich engineering centers. Accelerate multi-radar architecture development for heavy-duty commercial vehicle blind-spot coverage before camera-dominant challengers achieve highway-speed reliability. Certification investment in ISO 26262 ASIL-D validation capabilities creates switching costs that emerging entrants cannot replicate within compressed EU mandate timelines.
For New Entrants and Emerging Players: Build out aftermarket fleet retrofit capabilities targeting medium-duty commercial vehicles in the United States where OEM integration timelines leave installed base exposed. Camera-first system architectures represent the most penetrable technology segment as neural network processing costs enable vision-dominant cost structures. Direct sales to third-party fleet management providers bypass entrenched OEM supply relationships and consolidate specification authority through multi-year master service agreements.
For Investors and Strategic Acquirers: The market sits at a mandate-driven consolidation phase that favors diversified automotive conglomerates with braking system heritage and functional safety engineering depth. Long-term viability hinges on regulatory compliance bandwidth across divergent NCAP, NHTSA, and UN ECE test protocols that strain engineering resources. Acquisition targets with established OEM captive relationships and radar module manufacturing capabilities offer defensive positioning. Watch for inflection in camera-first NCAP test performance as signal of technology substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Radar Architecture Development | Distributed corner and rear-facing configurations enable intersection collision mitigation for heavy-duty truck liability reduction. |
| Backward Integration into Semiconductors | Captive supply of radar-specific ASICs and silicon carbide substrates insulates against Taiwanese foundry concentration risk. |
| Camera-First System Investment | Neural network processing cost compression enables vision-dominant architectures that reduce radar dependency for cost leadership. |
| Fleet Retrofit Channel Expansion | Plug-and-play AEBS kits for medium-duty vehicles bypass OEM integration timelines and capture underpenetrated installed base. |
| Functional Safety Certification Acceleration | ISO 26262 ASIL-D compliance creates 18-24 month barriers that freeze architecture decisions and lock out unqualified competitors. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet safety managers provided ongoing calibration across primary interview rounds. Secondary validation drew from NHTSA regulatory filings, EU General Safety Regulation implementation guidance, NCAP test protocol documentation, and vehicle production databases. Bottom-up unit economics triangulated against top-down OEM integration program targets to anchor volume assumptions.
Scenario bracketing around mandate enforcement timelines and sensor cost compression curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user category, technology type, and installation channel alongside vehicle class and regional production cluster. CAGRs derived from fitted adoption curves reflecting NHTSA phase-in requirements and fleet replacement cycles. Industry-specific forecast inputs incorporated 77 GHz radar cost trajectories and neural network inference silicon pricing trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vision-technology specialists or insurance-backed fleet telematics providers would shift outcomes beyond modeled ranges. Quarterly review of NCAP protocol evolution, foundry capacity announcements, and fleet procurement specification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market