
 Car Safety Market | 2026-2036
Car Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Car Safety Market Intelligence
The consolidation of purchasing power among a handful of large, global automotive OEMs is restructuring the supply chain for safety components. Robert Bosch GmbH leverages its extensive R&D in sensors and software to secure large-volume contracts for integrated safety solutions. Continental AG differentiates through its systems approach, combining active and passive safety technologies into cohesive platforms for automakers. This dynamic forces smaller suppliers to specialize in niche applications like specific sensor types to remain competitive.
Car safety encompasses the active and passive systems engineered to prevent accidents or reduce the severity of injuries during a collision. These systems integrate data from multiple sensors, such as radar and cameras, with sophisticated algorithms in an electronic control unit to trigger responses. While passive components like Airbags and Seat Belts form a mature base, active systems like Electronic Stability Control represent the primary growth area. Within technology, Lidar and AI-based systems are gaining traction over traditional ultrasonic sensors for advanced applications like pedestrian detection.
Regulatory frameworks, including mandates from the US National Highway Traffic Safety Administration (NHTSA) and performance ratings from Europe's NCAP, set the baseline for market entry. In parallel, China's GB standards are increasingly harmonizing with international norms, compelling both domestic and foreign automakers to upgrade safety features. Suppliers must now decide whether to focus on commoditizing hardware or invest in high-margin software and artificial intelligence development for autonomous functions.
Market Dynamics
The convergence of stringent regulatory mandates and the automotive industry's push toward autonomous driving is the central force shaping the car safety market. This dynamic compels suppliers to innovate beyond passive components, focusing on integrated, software-intensive active safety systems.
Growth Catalysts
- Regulatory Mandates:The EU's General Safety Regulation requires features like intelligent speed assistance and emergency lane-keeping systems, creating non-discretionary demand for advanced sensors and control units across all new vehicle platforms.
- Technology Maturation:Falling production costs for Lidar and advanced camera systems are enabling their deployment beyond premium vehicles into mass-market segments, significantly expanding the addressable market for sophisticated ADAS functions.
- Consumer Awareness:Safety ratings from programs like Europe's NCAP and the US IIHS heavily influence consumer purchasing decisions, incentivizing automakers to exceed minimum requirements and offer superior safety packages as a competitive differentiator.
Market Restraints
- System Integration Cost:The high upfront cost associated with integrating and validating complex sensor fusion systems, including radar, camera, and Lidar, remains a significant barrier for cost-sensitive vehicle segments.
- Software Complexity:Developing and verifying millions of lines of code for safety-critical functions according to standards like ISO 26262 presents a major technical hurdle and extends development timelines for automotive OEMs.
- Component Scarcity:Persistent global shortages of automotive-grade semiconductors directly impact the production of essential components like electronic control units (ECUs) and advanced sensors, constraining overall market growth.
Strategic Opportunities
- Software and Services:A transition toward software-defined vehicles opens opportunities for recurring revenue through over-the-air (OTA) updates and subscription-based access to enhanced safety features and autonomous driving capabilities.
- Emerging Market Penetration:Equipping entry-level vehicles in high-volume markets like India and Brazil with foundational active safety systems, such as anti-lock brakes and electronic stability control, represents a major volume opportunity.
- V2X Communication:The development of vehicle-to-everything (V2X) technology creates a new frontier for cooperative safety systems, enabling vehicles to share data on hazards and traffic conditions to prevent accidents preemptively.
Industry Challenges
- Specialized Talent Shortage:The industry faces a critical lack of software engineers and data scientists with expertise in both artificial intelligence and the stringent functional safety requirements mandated by ISO 26262.
- Data Standardization:A lack of universal standards for sensor data formats and communication protocols among different suppliers complicates the integration process, increasing development costs and time for automakers.
- Cybersecurity Vulnerabilities:Increasing vehicle connectivity exposes safety-critical systems like steering and braking to potential cyberattacks, requiring robust and continuously updated security measures to prevent malicious remote control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Safety Market |
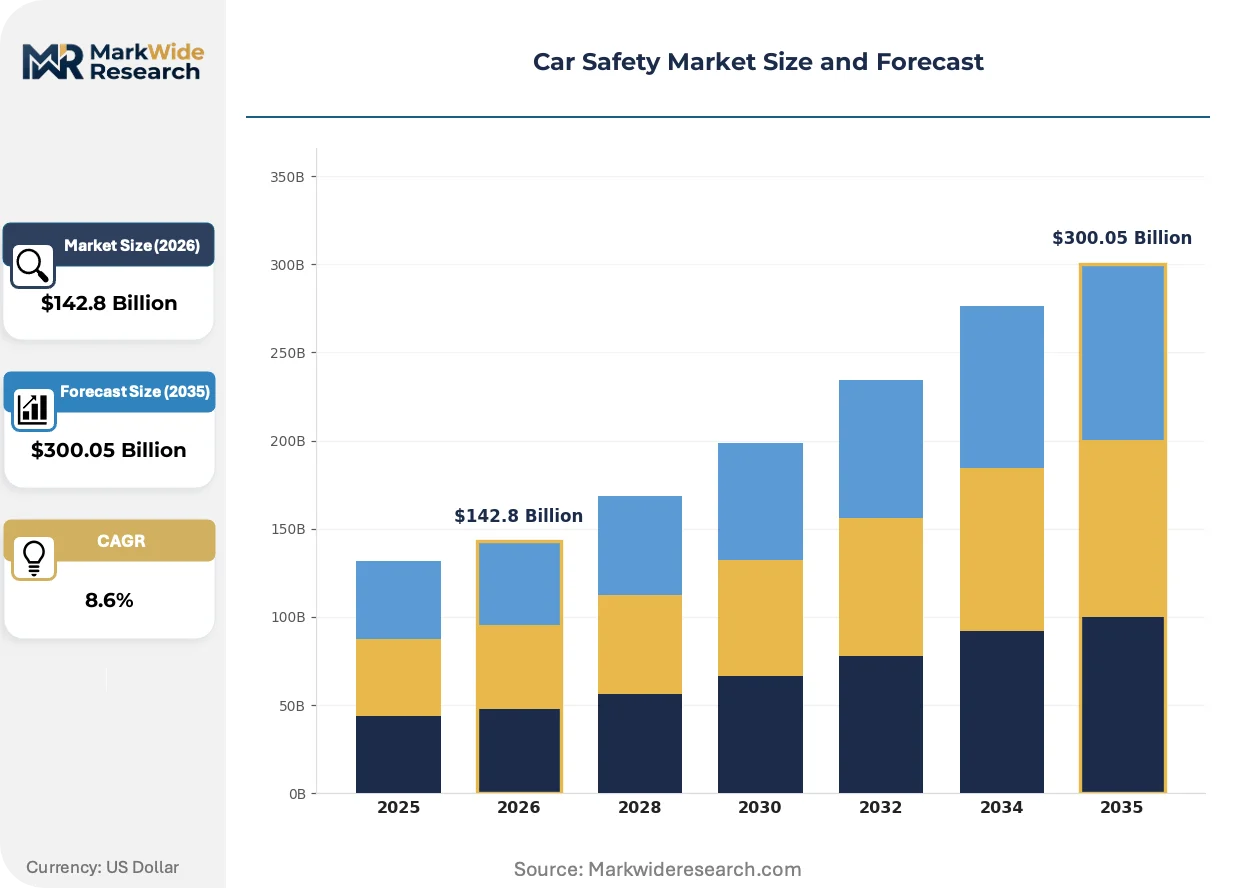
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $300.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags, Anti-lock Braking System, Seat Belts, Electronic Stability Control, Lane Departure Warning, Blind Spot Detection Technology: Radar, Ultrasonic Sensors, Lidar, Camera-Based Systems, Infrared Sensors, Artificial Intelligence Application: Collision Avoidance, Driver Monitoring, Parking Assistance, Emergency Braking, Adaptive Cruise Control, Pedestrian Detection End User: OEMs, Vehicle Assemblers, Aftermarket Service Providers, Fleet Operators, Insurance Companies, Driver Training Centers |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Autoliv Inc., Denso Corporation, Magna International, Hyundai Mobis, Valeo SA, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Safety Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from discrete hardware components to integrated, software-centric safety architectures. This shift is fundamentally altering vehicle design, supplier relationships, and the long-term value proposition of safety technology for consumers.
Centralized domain controllers are emerging as the new computational core for vehicle safety systems. Automakers are adopting these powerful processors to manage the immense data streams generated by an expanding array of cameras, radar, and Lidar sensors. This architectural shift is consolidating processing power into a single unit, which simplifies vehicle wiring, reduces weight, and enables complex, over-the-air software updates for safety functions.
China's evolving GB standards are progressively mandating the inclusion of advanced driver-assistance systems in all new passenger vehicles. This regulatory pressure compels both domestic Chinese brands and foreign joint ventures to accelerate the deployment of features like automatic emergency braking and lane-keeping assist. The urban passenger car segment is most affected, driving intense demand for compliant sensor suites from suppliers operating within the country.
A significant behavioral change is the unbundling of advanced safety features from traditional, rigid trim packages by automotive OEMs. This new model allows consumers to purchase specific ADAS functions, such as an advanced highway pilot, on an a-la-carte basis or through a subscription service after the initial vehicle sale. This trend is most visible within the premium electric vehicle segment in North America and Europe.
Car Safety Market Segmentation
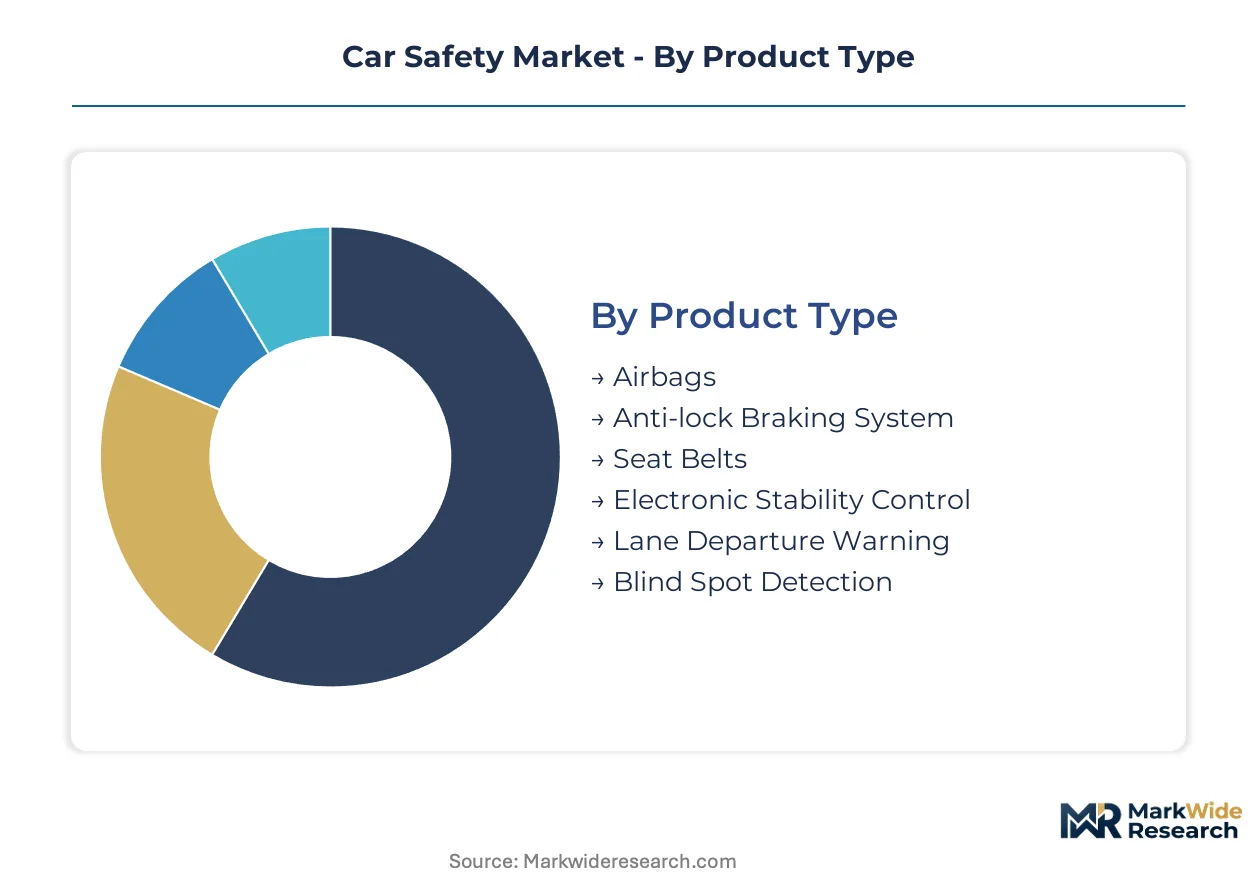
Segmentation analysis provides a structured view of the car safety market, revealing distinct demand patterns and technological preferences across various dimensions. Understanding these segments helps automakers and suppliers tailor product development and market strategies for optimal penetration.
Product Type:
Buyers in the car safety market differentiate their product choices based on the core function and direct impact of the safety component on vehicle occupants or accident prevention.
- Electronic Stability Control:This active safety system integrates sensor data to detect and prevent vehicle skidding or loss of control during abrupt maneuvers. Demand for ESC is concentrating in mass-market segments across Europe and North America, driven by regulatory mandates from the EU and NHTSA.
- Airbags:As a fundamental passive safety system, airbags rapidly inflate during a collision to cushion occupants and reduce injury severity. Global regulatory requirements across all vehicle platforms, including those in Japan and South Korea, ensure widespread adoption.
- Anti-lock Braking System:This system prevents wheels from locking during emergency braking, maintaining steering control and reducing stopping distances.
- Seat Belts:A primary passive restraint, seat belts secure occupants, significantly reducing the risk of ejection and injury in a crash.
- Lane Departure Warning:This system alerts drivers when the vehicle unintentionally drifts out of its lane, enhancing safety on highways.
- Blind Spot Detection:Sensors monitor areas not visible to the driver, providing warnings of vehicles in adjacent lanes to prevent side-swipe collisions.
Volume sits with Airbags and Seat Belts; growth tilts toward Electronic Stability Control and Lane Departure Warning.
Technology:
Performance characteristics drive technology selection within car safety, influencing sensor capabilities, data processing, and overall system effectiveness for advanced functions.
- Lidar:Utilizing laser pulses, Lidar technology generates precise 3D maps of the vehicle's surroundings, enabling accurate distance measurement and object detection. Demand is concentrating in advanced ADAS and autonomous driving systems, particularly within premium vehicles in Germany and the United States.
- Camera-Based Systems:These systems capture visual data for object recognition, lane keeping, and traffic sign interpretation, forming a cornerstone of modern ADAS. Mass-market integration into vehicles across China and India is expanding rapidly for features like pedestrian detection.
- Radar:Radar technology uses radio waves to detect objects, measure distance, and determine speed, offering robust performance in adverse weather conditions.
- Ultrasonic Sensors:Emitting sound waves, these short-range sensors are commonly employed for parking assistance and low-speed obstacle detection.
- Infrared Sensors:These sensors detect heat signatures, providing capabilities for night vision and occupant monitoring within the vehicle cabin.
- Artificial Intelligence:AI algorithms process complex sensor data from multiple sources, enabling sophisticated decision-making for ADAS and autonomous driving functions.
Technology evolution favors Lidar and Artificial Intelligence for future capabilities, while Radar and Camera-Based Systems maintain foundational importance.
Application:
End-user needs dictate the specific application of car safety systems, ranging from immediate accident prevention to driver support functions.
- Collision Avoidance:This broad application integrates various sensors and algorithms to detect potential impacts and automatically intervene to prevent or mitigate collisions. Regulatory mandates in Europe and strong consumer preference in North America are driving its widespread implementation.
- Pedestrian Detection:Systems utilizing cameras and Lidar identify vulnerable road users, triggering warnings or automatic braking to prevent accidents. The urban passenger car segment in China and NCAP ratings globally are accelerating its adoption.
- Driver Monitoring:This application tracks driver attention, fatigue levels, and distraction, issuing alerts to enhance safety during vehicle operation.
- Parking Assistance:Designed to aid drivers in maneuvering into parking spaces, this application reduces the likelihood of low-speed impacts and scrapes.
- Emergency Braking:Automatically applies brakes when a frontal collision risk is imminent, significantly reducing impact force or preventing the crash entirely.
- Adaptive Cruise Control:This system automatically adjusts vehicle speed to maintain a safe following distance from vehicles ahead, enhancing comfort and safety on highways.
Market emphasis is shifting towards Collision Avoidance and Pedestrian Detection as critical safety functions, while Parking Assistance remains a core offering.
End User:
Business models and integration points define the primary end-user segments for car safety components and solutions, influencing procurement and deployment strategies.
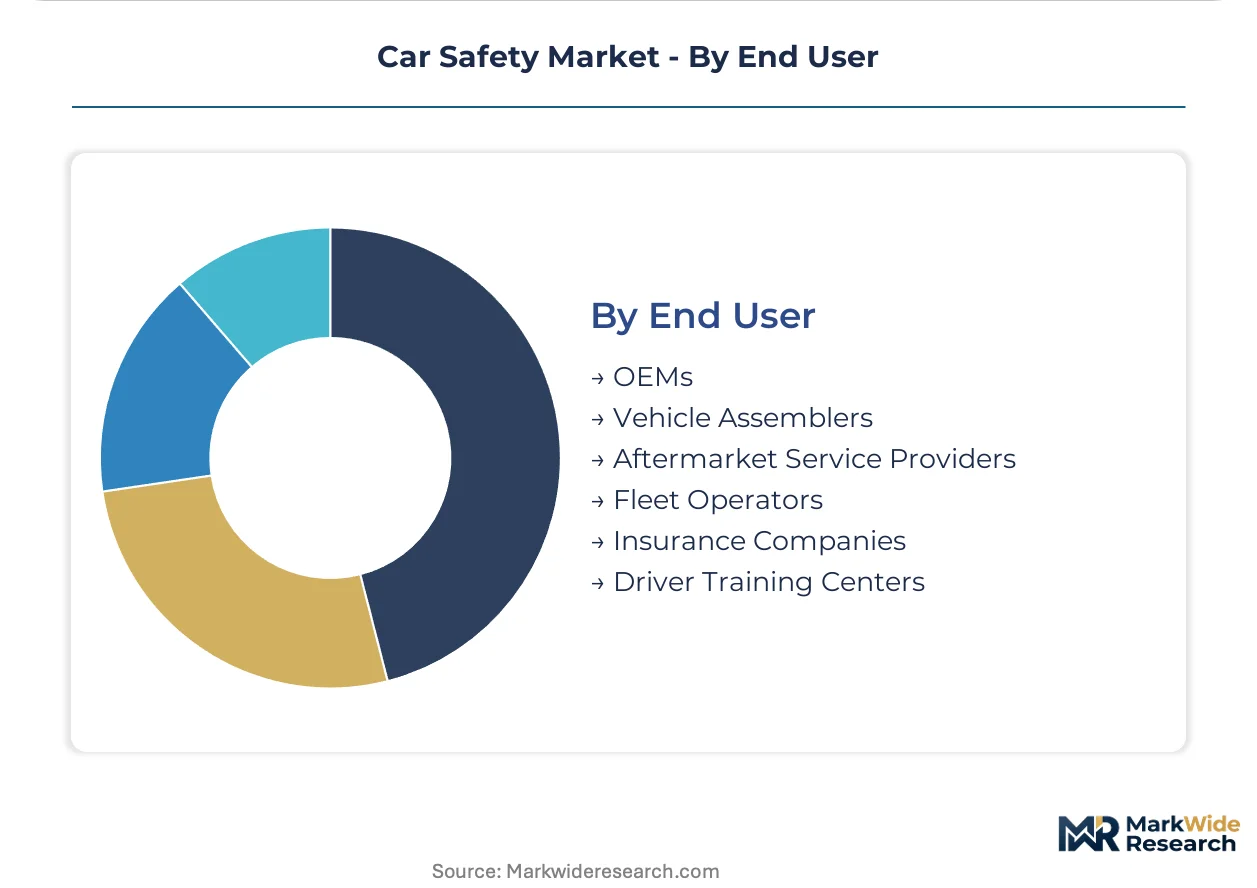
- OEMs:Original Equipment Manufacturers integrate safety systems directly into their new vehicle designs during the manufacturing process. Demand is concentrating in major automotive manufacturing hubs like Germany and China, driven by stringent regulatory compliance and brand differentiation.
- Fleet Operators:These entities deploy safety features across their commercial vehicle fleets to manage risk, enhance driver safety, and reduce operational costs. The logistics and transportation sectors in the United States and Brazil are showing significant adoption to improve accident rates and lower insurance premiums.
- Vehicle Assemblers:These companies integrate pre-manufactured safety modules and components into final vehicle production lines.
- Aftermarket Service Providers:These businesses install, maintain, and upgrade safety systems in vehicles already on the road.
- Insurance Companies:Insurers influence the adoption of safety technologies through policy incentives, premium adjustments, and claims data analysis.
- Driver Training Centers:These institutions incorporate education on advanced safety technologies into their curriculum for new and experienced drivers.
The largest volume of demand originates from OEMs, with Fleet Operators showing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for car safety systems concentrates in major automotive production centers globally, driven by stringent regulatory frameworks and advancing vehicle technologies. These regions are actively integrating advanced driver-assistance systems into new vehicle platforms. Global automotive manufacturing hubs are prioritizing the deployment of sophisticated safety solutions to meet evolving consumer expectations and legal requirements.
United States
Consumer preference for advanced safety features drives demand in the United States, especially for collision avoidance and pedestrian detection systems. NHTSA mandates and IIHS ratings heavily influence automaker decisions regarding standard safety equipment. Silicon Valley and Detroit collaborate on AI-driven safety solutions and advanced sensor integration.
Germany
Regulatory mandates from the EU's General Safety Regulation boost demand for active safety systems in Germany, including intelligent speed assistance. German automakers integrate advanced sensors and control units into their vehicle platforms. Bavaria and Baden-Württemberg are key R&D and manufacturing hubs for these sophisticated automotive technologies.
China
GB standards increasingly harmonize with international norms, compelling automakers to upgrade safety features across their fleets in China. The urban passenger car segment drives intense demand for compliant sensor suites for pedestrian detection and automatic emergency braking. The Yangtze River Delta region is a major production and innovation cluster for automotive safety components.
Japan
Global regulatory requirements ensure widespread adoption of passive safety systems like airbags and seat belts across all vehicle platforms in Japan. METI promotes advanced driver assistance systems development and deployment in new vehicles. Tokyo and Nagoya are centers for automotive safety research and manufacturing, fostering technological innovation.
India
Emerging market penetration for foundational active safety systems, such as anti-lock brakes and electronic stability control, offers a major volume opportunity in India. BIS standards push for enhanced vehicle safety features across all segments. Chennai and Pune are significant automotive manufacturing regions, attracting investment in safety technology production.
Car Safety Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-defined vehicle architectures and AI-driven autonomous functions. The supply chain for safety components is restructuring due to consolidated purchasing power among global automotive OEMs. Integrated solution providers and specialized sensor manufacturers form distinct strategic archetypes. Companies engage in extensive R&D and strategic partnerships to secure large-volume contracts.
Robert Bosch GmbH and Continental AG exemplify the archetype of large, integrated safety solution providers, leveraging extensive R&D in sensors and software. ZF Friedrichshafen AG also sits within this tier, supplying comprehensive active and passive safety systems to global automakers. These Germany-based companies anchor the market for advanced safety technologies and solutions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Autoliv Inc. |
| Denso Corporation |
| Magna International |
| Hyundai Mobis |
| Valeo SA |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in sensor manufacturing face unique challenges, influencing both their supply behavior and pricing discipline within the car safety market. This dynamic shapes component availability and cost structures for automotive OEMs globally.
Pricing Analysis
Volume-driven contracts for foundational safety components contrast sharply with high-margin, value-based pricing for advanced software solutions. Price differentiation stems from ISO 26262 functional safety certification and the level of customization required for specific vehicle platforms. Pricing softness reflects the intense purchasing power of large automotive OEMs for commoditized hardware. Mass-market vehicle segments exhibit the highest price sensitivity, while premium brands prioritize advanced feature integration over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks optimize delivery of mass-market components, streamlining logistics for global automakers. The supply chain concentrates manufacturing in Germany, China, and Japan for critical electronic control units and sensors. Production relies heavily on specialized semiconductors and optical components, creating dependencies on specific upstream suppliers. Component scarcity, particularly for automotive-grade semiconductors, represents a significant structural risk. Distribution runs through a tiered supplier model, with large integrators supplying directly to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car safety market operates as a supply-constrained story, with persistent global shortages of automotive-grade semiconductors propping pricing for essential electronic control units.
For Market Incumbents: Hedge against the increasing software complexity and talent shortage by investing heavily in AI development and functional safety certification. Strategic partnerships with key semiconductor manufacturers can mitigate component scarcity. Expand R&D into integrated software platforms to counter the threat of specialized software firms. Leverage ISO 26262 expertise to maintain a competitive advantage in safety-critical system development.
For New Entrants and Emerging Players: Enter via niche applications like specialized Lidar for specific use cases or AI-based pedestrian detection algorithms for urban environments. The urban passenger car segment in China presents a penetrable market for compliant sensor suites. A go-to-market angle focusing on licensing advanced software IP to existing Tier 1 suppliers or directly to new EV OEMs can prove effective. Target emerging markets like India with foundational active safety systems.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric IP firms in Germany and the United States, offering long-term value in the evolving car safety landscape. The market's long-term viability is underpinned by continuous regulatory mandates and the push towards autonomous driving. Acquisition targets should focus on companies with proven expertise in AI algorithms or functional safety software development. The signal to watch is the standardization of V2X communication protocols, indicating readiness for cooperative safety systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven software platforms | Enhances system intelligence for advanced ADAS functions and autonomous driving capabilities. |
| Secure long-term semiconductor supply agreements | Mitigates production risks and ensures component availability for safety-critical electronic control units. |
| Expand ISO 26262 functional safety expertise | Ensures compliance with stringent automotive safety standards, critical for market entry and product acceptance. |
| Develop V2X communication modules | Enables cooperative safety systems, preventing accidents through real-time data exchange between vehicles and infrastructure. |
| Target emerging market active safety penetration | Unlocks significant volume opportunities by equipping entry-level vehicles with essential accident prevention technologies. |
Research Approach
Independent corroboration across OEM procurement leaders, Tier 1 R&D engineers, and regulatory body representatives underwrites the qualitative findings. This approach combines primary interviews with industry stakeholders and secondary validation through comprehensive data sources. Secondary research includes NHTSA mandates, EU General Safety Regulation documents, NCAP ratings, and corporate filings from key market players. Bottom-up and top-down triangulation ensures robust data integrity.
Rate-of-change decomposition frames the market trajectory across the analysis window, integrating historical performance with future projections. The analytical framework models segmentation dimensions including product type, technology, application, end-user, vehicle class, and regional regulatory influence. Compound annual growth rates are derived from a detailed assessment of market drivers and restraints. Forecast inputs include ADAS penetration rates in new vehicles and Lidar cost reduction curves.
Revisions become necessary when significant shifts in semiconductor supply, regulatory mandates, or cybersecurity threats materialize. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market