
 Asia Pacific Lane Departure Warning Systems Market | 2026-2036
Asia Pacific Lane Departure Warning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Lane Departure Warning Systems Market Outlook
Sensor fusion architectures that merge camera feeds with radar inputs is reshaping how lane departure warning systems achieve reliability in adverse weather. Continental AG leverages its integrated sensor portfolio to dominate ADAS module supply for European-headquartered OEMs manufacturing in Thailand. Robert Bosch GmbH anchors its regional position through localized radar production facilities in India and Vietnam. Denso Corporation specializes in compact camera modules calibrated for narrow Asian road geometries.
Lane departure warning systems detect unintended lane crossings through optical or electromagnetic sensing, triggering haptic steering wheel vibrations or audible alerts when a vehicle crosses painted lane markings without activation of turn signals. Camera-based technology leads installation volumes due to declining CMOS sensor costs and compatibility with multi-function ADAS platforms. OEM end users capture the dominant margin pool as factory-fit integration eliminates aftermarket calibration complexity. Passenger cars represent the most mature vehicle category, while heavy-duty trucks show the fastest expansion trajectory driven by fleet safety mandates.
China's MIIT enforces GB/T standards for commercial vehicle advanced driver-assistance systems, directly compelling domestic and joint-venture manufacturers to pre-install LDWS. Japan's METI coordinates with JIS standards bodies to harmonize sensor performance benchmarks across kei car and full-size vehicle platforms. India's Automotive Research Association defines test protocols under Ministry of Road Transport oversight, shaping product homologation requirements for entry into that market. Stakeholders must monitor divergence between national certification regimes when designing unified regional product architectures.
Market Dynamics
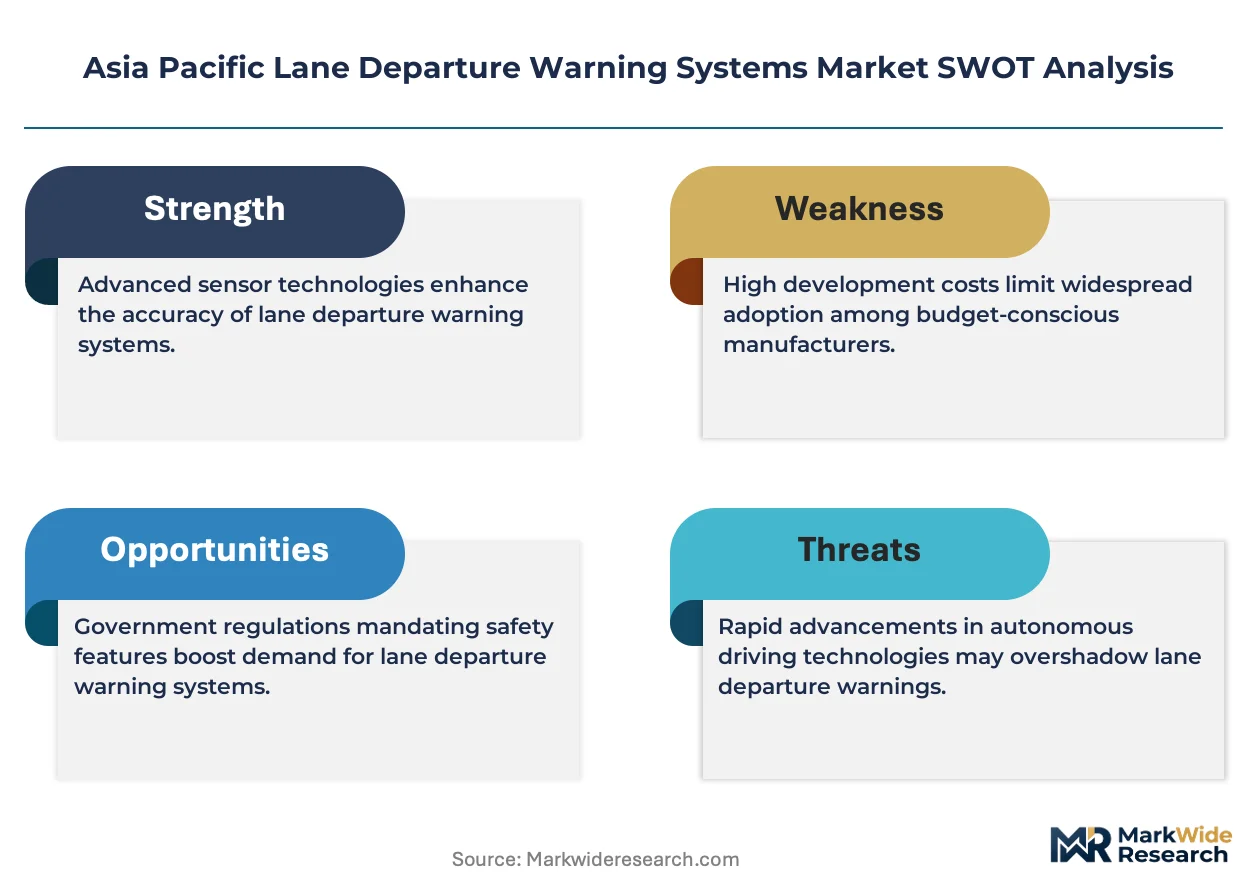
Sensor fusion architectures that merge camera feeds with radar inputs are compressing margins for single-sensor suppliers while rewarding integrated module producers with factory-fit contracts from commercial vehicle manufacturers.
Growth Catalysts
- MIIT GB/T mandates:China's Ministry of Industry and Information Technology compels heavy-duty truck manufacturers to pre-install LDWS, creating guaranteed demand for integrated ADAS suppliers serving domestic OEMs.
- Fleet liability reduction:Commercial trucking operators across Thailand and Vietnam are retrofitting existing vehicle pools with aftermarket LDWS to lower collision insurance premiums and driver injury claims.
- CMOS sensor cost decline:Falling image sensor prices enable multi-function camera platforms that bundle LDWS with traffic sign recognition and pedestrian detection for kei car producers in Japan.
Market Restraints
- Radar chip supply concentration:Foundry capacity for 77GHz automotive radar silicon concentrates in Taiwan and South Korea, exposing tier-one module suppliers to allocation risk during semiconductor demand spikes.
- Monocular camera performance limits:Single-lane detection systems fail on unpaved rural roads lacking painted markings across Indonesia and the Philippines, restricting addressable market penetration.
- Homologation timeline fragmentation:Divergent test protocols between Japan's JIS standards and India's ARAI certification force suppliers to maintain parallel validation facilities, inflating fixed cost structures.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Production-linked incentives for advanced driver-assistance component manufacturing attract module assembly investment to Tamil Nadu and Gujarat industrial corridors.
- Sensor-to-cloud integration:Fleet telematics providers are converging LDWS alert data with predictive maintenance platforms, opening subscription revenue streams for commercial vehicle operators in Australia.
- Aftermarket retrofit channels:Independent service centers across Malaysia and Indonesia represent underpenetrated distribution for camera-only LDWS kits targeting used vehicle imports from Japan.
Industry Challenges
- Embedded software talent scarcity:Machine learning engineers capable of training edge-detection algorithms for tropical weather conditions command premium compensation in Singapore and Bangalore, constraining R&D expansion for mid-tier suppliers.
- Legacy CAN bus integration:Older commercial vehicle platforms in Vietnam and Thailand lack the data bandwidth to support real-time LDWS processing, requiring costly gateway hardware retrofits that erode aftermarket margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Lane Departure Warning Systems Market |
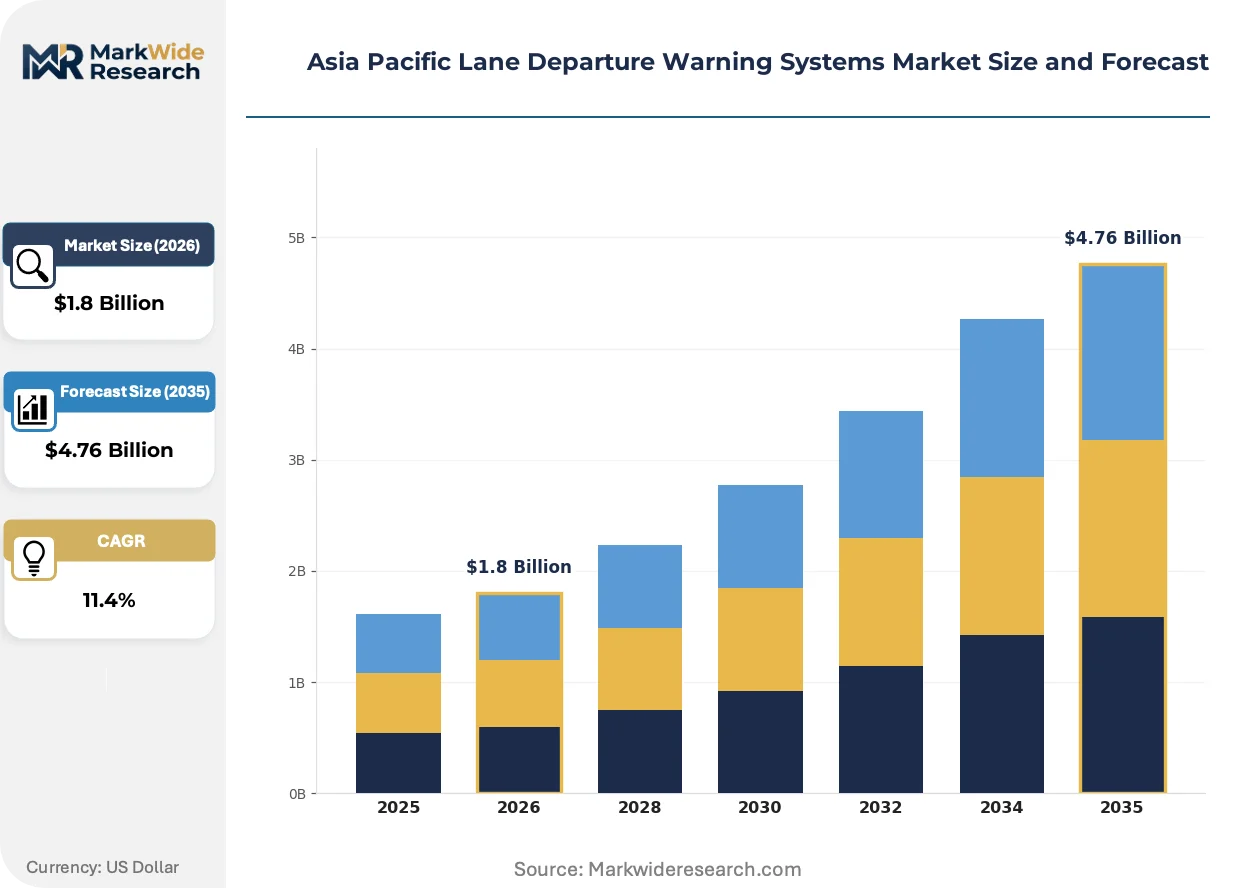
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Laser-Based, Infrared, Ultrasonic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, Buses Service Type: Installation, Maintenance, Calibration, Upgrades |
| Companies Covered | Denso Corporation, Continental AG, Robert Bosch GmbH, Mobileye, Delphi Automotive, Magna International, ZF Friedrichshafen AG, Hyundai Mobis Co., Ltd., Fujitsu Laboratories Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Lane Departure Warning Systems Market Strategic Shifts
Edge computing migration and neural network compression are enabling lane departure warning functionality on lower-cost hardware, reshaping competitive positioning between premium integrated suppliers and specialized component vendors.
Neural processing units with dedicated convolutional accelerators are rendering obsolete discrete DSP-based lane detection chips that previously dominated cost-sensitive vehicle segments. Tier-two camera module suppliers in South Korea and Taiwan are adopting these SoCs for entry-level passenger car contracts. The compression of processing hardware costs is collapsing the price floor for factory-fit LDWS, pressuring aftermarket retrofit providers to differentiate through installation speed rather than component pricing.
METI's coordination with JIS standards bodies is harmonizing sensor performance benchmarks across kei car and full-size vehicle platforms, reducing SKU complexity for suppliers serving Japanese OEMs. The standardization eliminates parallel certification tracks that previously fragmented production runs. Component manufacturers with existing JIS-compliant test facilities are capturing expanded contract scope from domestic manufacturers pivoting toward unified regional architectures.
Fleet procurement departments are consolidating ADAS vendor relationships from multi-source component purchasing toward single-module supplier frameworks with integrated warranty coverage. This concentration favors tier-one electronics producers with captive radar and camera production over specialized sensor vendors. The behavioral shift is most visible among logistics operators in China's Yangtze River Delta and Japan's Kanto industrial belt, where procurement teams prioritize supplier solvency over unit cost minimization.
Asia Pacific Lane Departure Warning Systems Market Segmentation
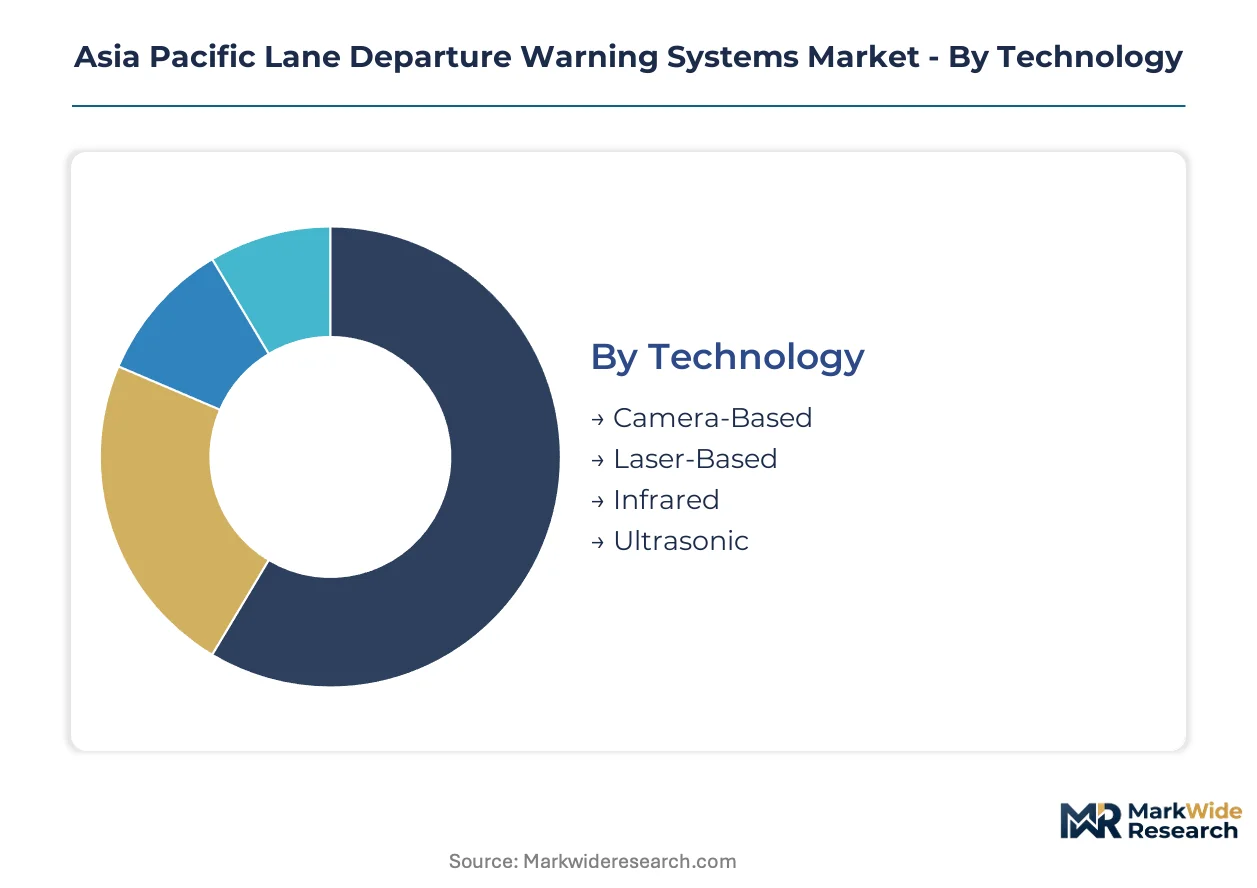
Technology choice determines hardware cost floors and weather resilience. End-user channel selection shapes margin capture and warranty liability. Vehicle type segmentation reflects divergent regulatory mandates across commercial and passenger fleets.
Technology:
Cost tier positioning separates premium multi-sensor fusion from single-sensor economy configurations.
- Camera-Based:CMOS image sensors capture painted lane markings through forward-facing windscreen modules. Factory-fit penetration concentrates in Japanese kei car platforms and Chinese compact sedans where declining sensor costs enable bundling with traffic sign recognition. MIIT GB/T mandates for commercial vehicles accelerate module standardization.
- Laser-Based:LiDAR emitters generate high-resolution road geometry maps independent of ambient lighting conditions. Deployment clusters in premium passenger vehicles manufactured for Australian and South Korean markets where night-time highway driving demands superior detection range.
- Infrared:Thermal imaging sensors detect lane boundaries through temperature differentials rather than visual contrast. Niche adoption persists in fog-prone corridors of Vietnam and northern Thailand where optical systems suffer frequent false negatives.
- Ultrasonic:Acoustic ranging sensors supplement primary detection with proximity verification at low speeds. Parking-assist integration drives aftermarket retrofit demand across Indonesia's urban used-vehicle import channels.
Camera-based systems command the established base. The steepest expansion runs through laser-based configurations.
End User:
Channel structure determines who bears homologation costs and field failure liability.
- OEMs:Vehicle manufacturers integrate LDWS at design phase, capturing warranty control and software update pathways. Chinese state-owned enterprises and Japanese kei car specialists dominate procurement volumes under MIIT and METI compliance frameworks.
- Tier-1 Suppliers:Electronics module producers such as Denso and Bosch deliver pre-validated ADAS assemblies to multiple OEM platforms. Consolidation favors integrated radar-camera producers over discrete sensor vendors.
- Aftermarket Providers:Independent distributors serve fleet retrofit demand in Thailand and Vietnam where collision insurance premium reductions justify hardware investment. Installation calibration complexity limits price competition.
- Vehicle Assemblers:Contract manufacturers for regional brands source LDWS through open-bill-of-materials arrangements. India's Tamil Nadu automotive corridor attracts this segment under PLI scheme incentives.
OEMs retain margin concentration. Aftermarket providers gain share fastest in fleet liability reduction applications.
Vehicle Type:
Application severity dictates sensor redundancy requirements and alert intervention thresholds.
- Passenger Cars:Factory-fit penetration peaks in Japan and South Korea where consumer ADAS awareness drives option take rates. Multi-function camera platforms bundle LDWS with pedestrian detection.
- Light Commercial Vehicles:Delivery van fleets across Australia's eastern seaboard deploy telematics-integrated LDWS for driver behavior monitoring. Subscription revenue models emerge.
- Heavy-Duty Trucks:China's MIIT mandates pre-installation for vehicles over 12 tonnes. Yangtze River Delta logistics operators consolidate vendor relationships toward single-module suppliers with integrated warranty coverage.
- Buses:Public transit authorities in Singapore and Japan specify haptic seat vibration alerts to accommodate hearing-impaired operators. Procurement runs through municipal tender processes.
Passenger cars anchor volume. Heavy-duty trucks climb the fastest on regulatory compulsion.
Service Type:
Recurring revenue potential varies with calibration complexity and software update frequency.
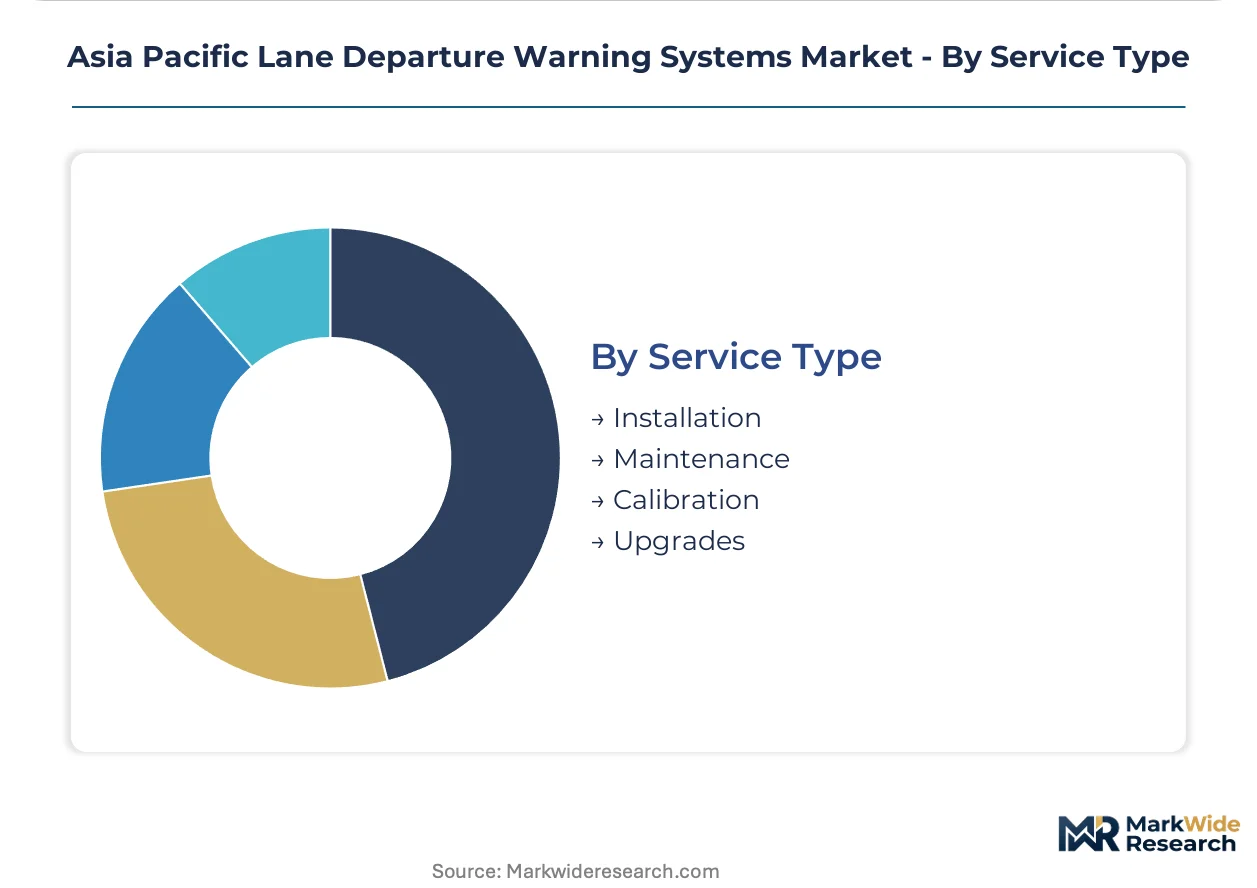
- Installation:Windscreen-mounted camera modules require precise angular alignment within 0.5 degrees. OEM factory-fit eliminates this cost; aftermarket channels in Malaysia and Indonesia absorb technician training expenses.
- Maintenance:Lens cleaning protocols and connector inspection prevent degradation in tropical humidity. Fleet operators in Thailand bundle LDWS maintenance with scheduled brake service intervals.
- Calibration:Post-collision or windscreen replacement recalibration demands manufacturer-specific diagnostic tools. Authorized service networks capture this revenue in Japan and Australia.
- Upgrades:Firmware enhancements expand detection to faded markings or construction zones. Over-the-air capability separates premium integrated platforms from entry-level hardware.
Installation revenue concentrates in aftermarket channels. Upgrades expand most quickly through connected vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision camera modules to assembly plants across Thailand and Vietnam, establishing the dominant trade-flow corridor for LDWS components in Southeast Asia.
China
Domestic heavy-duty truck production absorbs the majority of regional LDWS module output as MIIT GB/T mandates compel factory-fit installation. The Yangtze River Delta logistics corridor concentrates fleet procurement decisions among state-owned transport operators. Tier-one electronics producers in Jiangsu and Zhejiang provinces capture expanded contract scope under this regulatory compulsion.
Japan
Kei car manufacturers drive volume demand for compact multi-function camera platforms bundling LDWS with traffic sign recognition. METI coordinates JIS standard harmonization across vehicle size classes, reducing SKU complexity for domestic suppliers. Precision electronics clusters in Aichi and Kanagawa prefectures specialize in narrow-road-geometry calibration for regional export markets.
India
Tamil Nadu and Gujarat industrial corridors attract module assembly investment under the PLI scheme for automotive electronics. ARAI test protocols shape homologation requirements for entry into domestic and export markets. Domestic OEMs and contract manufacturers source LDWS through open-bill-of-materials arrangements concentrated in these southern and western states.
Thailand
European-headquartered OEMs manufacturing for ASEAN export markets source integrated ADAS modules from regional supply bases. Fleet operators retrofit existing commercial vehicle pools to reduce collision insurance premiums. Eastern seaboard industrial zones host assembly operations serving both domestic consumption and re-export to neighboring Vietnam and Indonesia.
Australia
Fleet telematics providers converge LDWS alert data with predictive maintenance platforms, opening subscription revenue streams for commercial vehicle operators. Premium passenger vehicle segments demand LiDAR-based systems for night-time highway driving. Victoria and New South Wales transport authorities specify integrated warranty coverage in municipal procurement frameworks.
Asia Pacific Lane Departure Warning Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure concentrates around integrated module producers with captive radar and camera production, while discrete sensor vendors face margin compression. Three archetypes dominate: diversified automotive electronics conglomerates with regional manufacturing footprints; specialized ADAS technology developers focused on algorithm and software layers; and tier-two component suppliers serving cost-sensitive vehicle segments. Competitive moves center on strategic partnerships for sensor fusion architectures and geographic expansion through localized assembly facilities.
Within the diversified conglomerate tier, Denso Corporation and Continental AG exemplify integrated production structures spanning multiple sensor modalities. Robert Bosch GmbH anchors a position through established regional manufacturing presence. These three entities represent the dominant channel-control archetype, capturing factory-fit contracts through combined hardware and software validation capabilities rather than single-component supply relationships.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Mobileye |
| Delphi Automotive |
| Magna International |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co., Ltd. |
| Fujitsu Laboratories Ltd |
| Others |
Value Chain & Pricing Dynamics
Foundry capacity for 77GHz automotive radar silicon concentrates in Taiwan and South Korea, channeling margin pools toward integrated module producers with captive radar production while squeezing discrete sensor vendors. Tier-one suppliers with in-house semiconductor fabrication capture pricing power in factory-fit negotiations with Chinese OEMs and Japanese kei car manufacturers.
Pricing Analysis
Next-generation neural processing units with dedicated convolutional accelerators command premium positioning against prior-generation DSP-based lane detection chips and current-generation multi-sensor fusion platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under MIIT GB/T mandates versus entry-level camera-only configurations. Cost compression in economy tiers is intensifying because South Korean and Taiwanese tier-two suppliers are adopting low-cost SoCs for kei car contracts. Fleet procurement departments in China's Yangtze River Delta exhibit lowest price sensitivity due to consolidated vendor relationships, while independent aftermarket channels in Indonesia and Malaysia face acute margin pressure from installation calibration complexity.
Supply Chain Analysis
Tariff exposure between China and key semiconductor source markets dominates supply chain risk assessment for radar-dependent module suppliers. Component sourcing draws from Taiwan for 77GHz radar silicon, South Korea for CMOS image sensors, and Japan for precision optical assemblies. Single-source vulnerability concentrates in automotive-grade radar chip foundries, with limited qualified alternatives beyond the dominant Taiwan-based producers. Distribution runs through tier-one electronics module producers delivering pre-validated ADAS assemblies to OEM factory floors, supplemented by authorized service networks handling post-collision recalibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineers capable of training edge-detection algorithms for tropical weather conditions command premium compensation in Singapore and Bangalore, constraining R&D expansion for mid-tier suppliers. This capability scarcity favors incumbents with established talent pools and penalizes new entrants lacking embedded software depth.
For Market Incumbents: Build algorithmic moats around sensor fusion architectures that merge camera feeds with radar inputs, compressing margins for single-sensor competitors. Deepen backward integration into radar chip supply through foundry partnerships in Taiwan, securing allocation priority during semiconductor demand spikes. Invest in JIS-compliant test facilities to capture expanded contract scope from Japanese OEMs pivoting toward unified regional architectures under METI coordination. For New Entrants and Emerging Players: Pursue aftermarket retrofit channels across Malaysia and Indonesia where independent service centers represent underpenetrated distribution for camera-only LDWS kits targeting used vehicle imports from Japan. Target fleet liability reduction applications in Thailand and Vietnam where collision insurance premium reductions justify hardware investment despite installation calibration complexity. Lead with telematics-integrated offerings that converge LDWS alert data with predictive maintenance platforms, opening subscription revenue streams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-to-cloud integration sub-segments as fleet telematics providers demand edge-computing hardware with over-the-air firmware capability. Long-term viability over the coming decade rests on acquisition targets with integrated radar-camera production and software validation capabilities rather than discrete component suppliers. Watch for MIIT mandate expansion beyond heavy-duty trucks into light commercial vehicles as the signal indicating accelerated factory-fit penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Continental AG leverages integrated portfolios to dominate ADAS module supply for European-headquartered OEMs manufacturing in Thailand. |
| Localized Radar Production Expansion | Robert Bosch GmbH anchors regional position through manufacturing facilities in India and Vietnam reducing tariff exposure. |
| Compact Camera Module Specialization | Denso Corporation captures kei car contracts through narrow-road-geometry calibration for Japanese domestic and export markets. |
| Telematics Platform Integration | Fleet operators in Australia's eastern seaboard deploy subscription revenue models converging LDWS alerts with predictive maintenance. |
| PLI Scheme Manufacturing Investment | Module assembly investment concentrates in Tamil Nadu and Gujarat industrial corridors under India's production-linked incentive framework. |
Study Parameters
A standing panel of Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operations directors provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, MIIT GB/T compliance filings, and METI JIS standard harmonization documents. Bottom-up module shipment estimates triangulated with top-down OEM platform penetration assumptions across the analysis window.
Scenario-bracketing framed demand projections across technology, end user, vehicle type, and service type segmentation dimensions. CAGRs derived from fitted growth curves incorporating regulatory mandate timelines, CMOS sensor cost decline trajectories, and fleet procurement behavioral shifts. Industry-specific inputs included MIIT GB/T enforcement schedules, METI JIS standardization progress, and India's PLI scheme uptake rates across Tamil Nadu and Gujarat corridors.
Sensitivities concentrate around semiconductor foundry allocation disruptions, divergence between national homologation regimes, and embedded software talent availability in tropical weather algorithm development. Forecasts reflect documented assumptions subject to revision from regulatory mandate expansion or contraction, technology substitution rates, and supply chain reconfiguration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market