
 Automotive Roof Bar and Roof Racks Market | 2026-2036
Automotive Roof Bar and Roof Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Roof Bar and Roof Racks Market Analysis
A capital-intensity divergence between extrusion-capable aluminum processors and assembly-only brands is unwinding competitive stability in the roof systems space. Thule Group leverages integrated Swedish R&D and testing facilities to sustain premium positioning across Nordic and North American channels. Yakima Products Inc. anchors its competitiveness through specialized outdoor-retail partnerships rather than broad automotive distribution. Cruzber SA dominates Southern European markets with region-specific clamp geometries suited to narrower roof rail spacing common on compact vehicles sold in Spain and Portugal.
Automotive roof bars and roof racks constitute load-bearing exterior accessories engineered to distribute cargo weight across a vehicle's roof structure, typically fabricated from extruded aluminum alloys rated for dynamic loads during highway-speed operation. Their primary commercial purpose centers on expanding vehicle cargo capacity for recreational equipment, commercial goods transport, and fleet utility applications without compromising cabin interior space. Aluminum material grades command the dominant margin pool due to corrosion resistance and weight advantages, while carbon fiber represents the fastest-growing structural segment despite current cost premiums. Clamp-on mounting styles retain the largest installed base across aftermarket channels, though flush-mount systems are gaining share among OEMs seeking aerodynamic integration and reduced wind noise.
Federal Motor Vehicle Safety Standards administered by NHTSA govern roof rack integrity in the United States, while ECE R14 regulations in Europe mandate dynamic testing for exterior-mounted accessories. China's SAMR enforces GB standards that increasingly align with ECE protocols, creating convergence pressure on multinational suppliers. Stakeholders must monitor how divergent crash-test protocols between NHTSA and European NCAP programs reshape load-rating methodologies and cross-border product certification requirements.
Market Dynamics
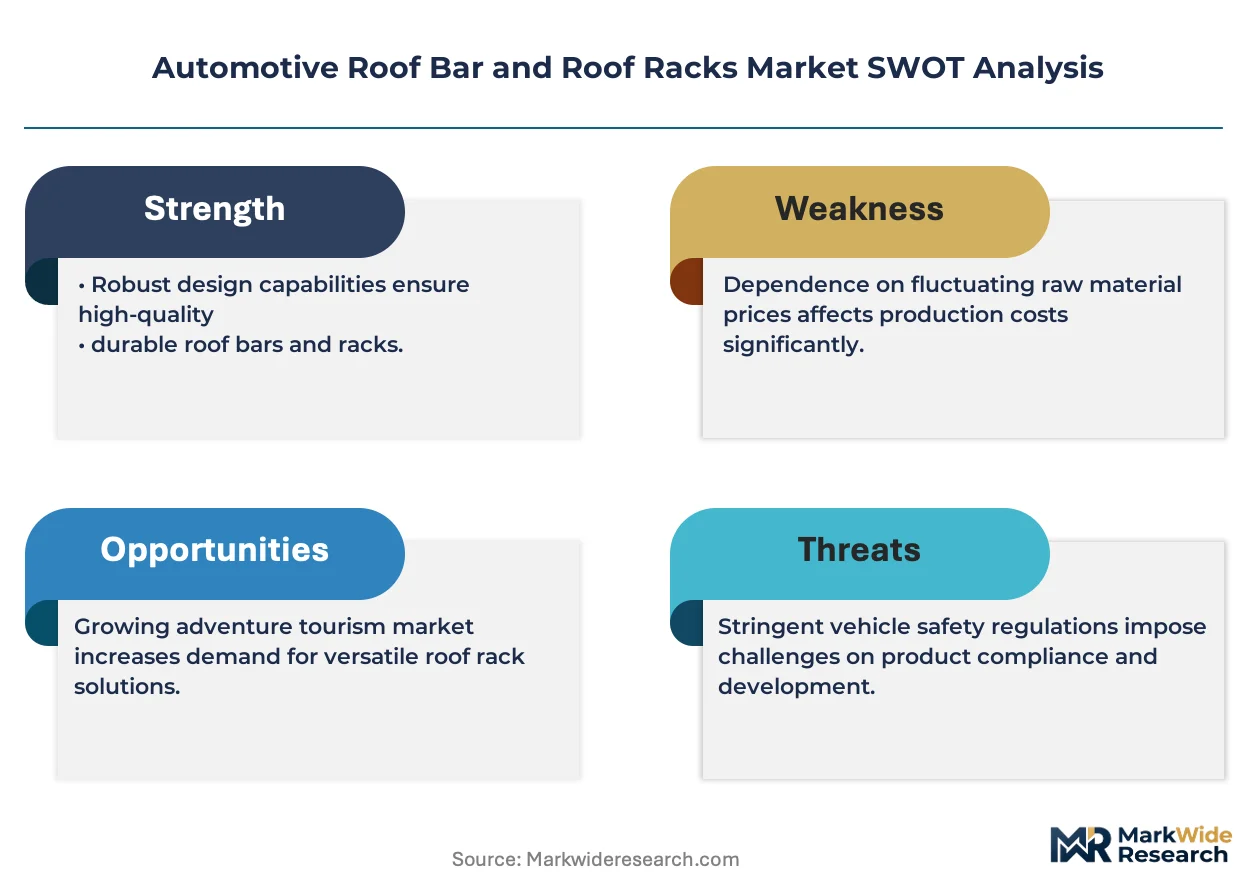
Capital intensity divergence between extrusion-capable aluminum processors and assembly-only brands is unwinding competitive stability, forcing mid-tier suppliers to secure captive alloy sourcing or exit load-bearing segments entirely.
Growth Catalysts
- ECE R14 Protocol Alignment:China's SAMR is tightening GB standards to mirror European dynamic testing requirements, accelerating certification convergence for multinational suppliers serving dual markets.
- Carbon Fiber Structural Adoption:Advanced composite manufacturing is reducing weight penalties for electric vehicle compatibility, opening premium positioning for performance-oriented outdoor enthusiasts.
- Adventure Tourism Participation:Equipment-intensive recreation is expanding addressable demand for load-rated systems capable of handling kayaks, rooftop tents, and expedition cargo.
Market Restraints
- Aluminum Alloy Input Volatility:Extrusion-grade 6061-T6 pricing swings compress margin pools for brands without long-term smelter contracts or scrap-recycling capabilities.
- Regional Supply Concentration:Southern European clamp geometry specialization locks out non-adapted competitors from Spain and Portugal's compact-vehicle aftermarket.
- Aerodynamic Integration Mandates:OEM flush-mount specifications are displacing traditional clamp-on architectures, stranding tooling investments at legacy assembly houses.
Strategic Opportunities
- German Manufacturing Anchoring:Thule Group and Cruzber SA have established R&D and distribution infrastructure that smaller players can access through private-label or co-manufacturing arrangements.
- Electric Vehicle Payload Optimization:Lightweight rack systems address range-anxiety constraints, creating white space for magnesium-alloy and hybrid composite architectures.
- Specialized Outdoor Retail Channel:REI, MEC, and regional co-ops offer margin premiums absent from mass automotive distribution, rewarding brands with technical storytelling capabilities.
Industry Challenges
- Cross-Border Certification Timeline Compression:Divergent NHTSA and European NCAP crash-test protocols force redundant load-rating methodologies, extending product development cycles.
- Extrusion Die Capex Requirements:Custom aluminum profiles demand six-figure tooling investments with 18-month amortization horizons, excluding capital-constrained entrants from premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Roof Bar and Roof Racks Market |
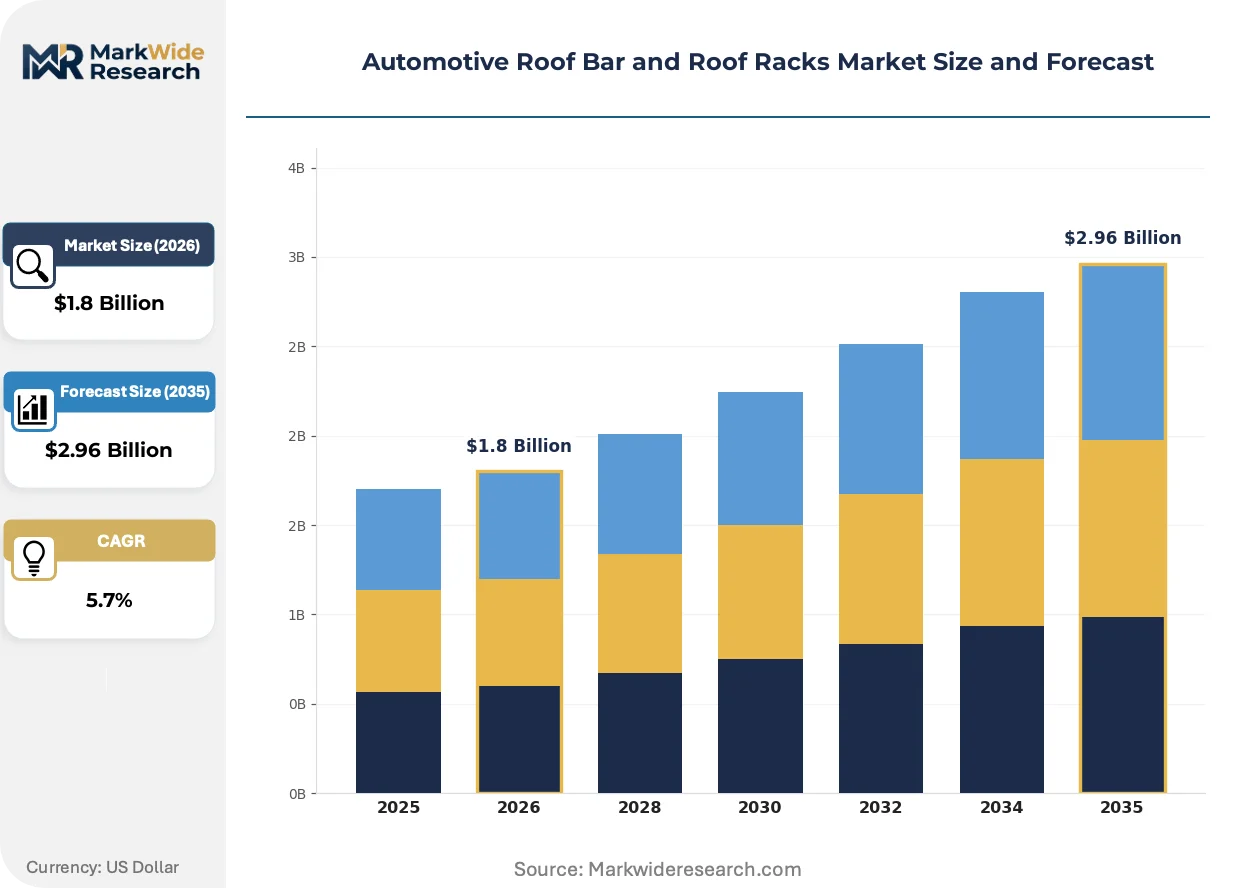
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bar, Adjustable Bar, Utility Rack, Cargo Rack Material: Aluminum, Steel, Plastic, Carbon Fiber Mounting Style: Clamp-On, Flush Mount, Strap Mount, Snap-On End User: OEMs, Retail Customers, Commercial Fleets, Aftermarket Installers |
| Companies Covered | Thule Group, Yakima Products Inc., Rhino-Rack, Cruzber SA, Magna International Inc., MINTH Group Ltd., JAC Products, Atera GmbH, Kuat Racks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Roof Bar and Roof Racks Market Emerging Trajectories
Active reshaping of this market centers on material substitution pressures, regulatory protocol convergence, and channel specialization that rewards technical differentiation over price competition.
Modular rail-and-tower architectures are fragmenting traditional fixed-bar configurations. Outdoor enthusiasts and fleet operators are adopting component systems that reconfigure for bike carriers, ski mounts, or cargo boxes without full rack replacement. This adaptability is compressing replacement-cycle revenue for legacy fixed-bar manufacturers while expanding attach-rate opportunities for accessory specialists.
China's GB standard revisions under SAMR oversight are forcing structural redesigns for brands serving Asia-Pacific markets. Load-bearing certification now requires dynamic testing protocols previously mandatory only under ECE R14, eliminating grandfathered products and accelerating facility upgrades among export-dependent suppliers. European-anchored multinationals with existing ECE testing infrastructure capture compliance timing advantages.
Buyer concentration among specialty outdoor retailers is displacing traditional automotive aftermarket distribution. REI, MEC, and regional adventure co-ops now curate roof rack assortments based on technical performance metrics rather than price-tier slotting. This shift is most visible in Nordic and Pacific Northwest markets where consumer research depth and brand storytelling determine shelf access.
Automotive Roof Bar and Roof Racks Market Segmentation
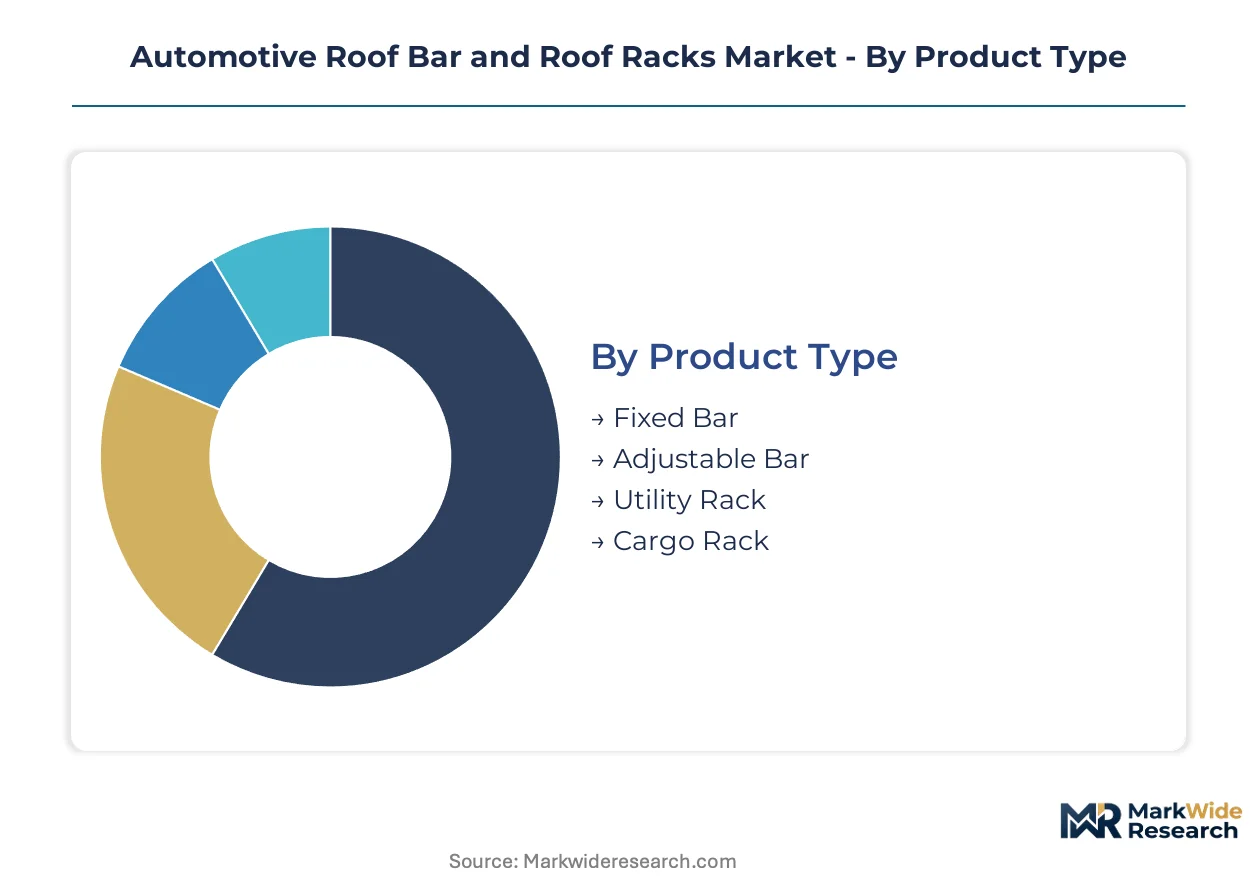
Segmentation in the automotive roof bar and roof racks market reveals distinct channel affinities and margin structures. Product type and mounting style determine whether volume flows through mass automotive distribution or specialized outdoor retail. Material selection separates premium positioning from commodity competition.
Product Type:
Fixed bars dominate mass-market automotive channels, while adjustable and utility configurations concentrate in specialty outdoor retail and commercial fleet procurement.
- Fixed Bar:Permanent crossbar configurations engineered for standardized load distribution across passenger vehicles. Demand concentrates in Germany and Sweden where Thule Group and Cruzber SA anchor OEM supply agreements and aftermarket distribution networks. Clamp-on mounting compatibility preserves broad vehicle coverage.
- Adjustable Bar:Telescoping crossbar systems accommodating variable roof widths without custom sizing. Expansion concentrates among outdoor recreation enthusiasts in Nordic markets and Pacific Northwest regions where rooftop tent and kayak mounting drive modular system preferences. REI and MEC curate these configurations based on technical load ratings.
- Utility Rack:Heavy-duty platforms designed for commercial goods transport and contractor applications. Fleet procurement channels in Spain and Portugal favor these systems for compact vehicle compatibility.
- Cargo Rack:Enclosed weather-resistant boxes integrating with base bar architectures. Seasonal demand spikes align with ski and expedition tourism cycles.
Fixed bars dominate installed base. Adjustable bar configurations are where expansion concentrates.
Material:
Cost tier stratification separates extrusion-grade aluminum processors from assembly-only brands competing on price.
- Aluminum:Extruded 6061-T6 alloys delivering corrosion resistance and weight optimization for dynamic highway loads. German and Swedish manufacturers leverage captive smelter contracts to defend margin pools against input volatility. ECE R14 certification requirements favor established European testing infrastructure.
- Steel:Lower-cost alternative for commercial fleet applications where weight penalties are secondary to durability. Demand concentrates in price-sensitive Southern European aftermarket channels.
- Plastic:Injection-molded components for non-structural fairings and cosmetic covers. OEM flush-mount integration mandates are displacing traditional plastic-heavy architectures.
- Carbon Fiber:Advanced composite structures reducing mass for electric vehicle payload optimization. Premium positioning targets performance-oriented outdoor enthusiasts in Germany and Nordic markets where technical storytelling commands shelf access at specialty retailers.
Aluminum commands the dominant margin pool. Carbon fiber is climbing the fastest on electric vehicle compatibility requirements.
Mounting Style:
Customer type determines mounting architecture selection, with OEMs driving flush-mount adoption while retail channels preserve clamp-on volumes.
- Clamp-On:Universal attachment systems gripping door frames or existing roof rails without vehicle modification. Retains the largest installed base across aftermarket channels in Spain and Portugal where compact vehicle roof rail spacing demands region-specific clamp geometries.
- Flush Mount:Integrated factory installations reducing aerodynamic drag and wind noise. OEM specifications in Germany and Sweden are stranding tooling investments at legacy assembly houses unable to meet aerodynamic integration mandates.
- Strap Mount:Temporary attachment for occasional-use scenarios on vehicles lacking factory rails. Seasonal demand from casual outdoor recreation participants.
- Snap-On:Tool-free installation systems targeting convenience-oriented retail customers. Limited load ratings restrict application to lightweight cargo.
Clamp-on architectures dominate installed base. Flush mount is gaining share fastest among OEM integration mandates.
End User:
Volume concentration varies sharply by procurement sophistication and technical specification requirements.
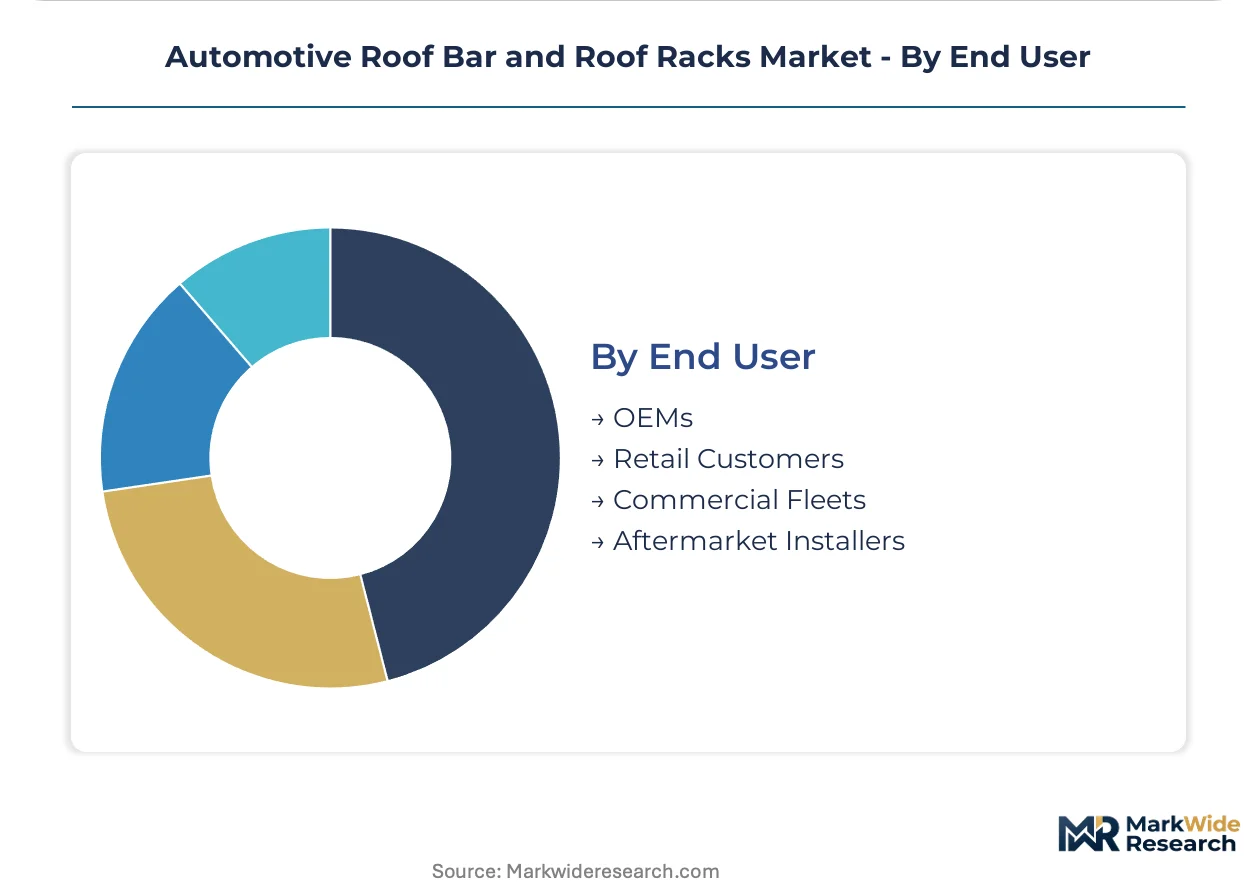
- OEMs:Vehicle manufacturers specifying aerodynamic integration and reduced wind noise. German automotive producers anchor European demand with stringent ECE R14 compliance requirements.
- Retail Customers:Individual outdoor recreation enthusiasts researching technical performance metrics. Nordic and Pacific Northwest markets show deepest consumer research behavior.
- Commercial Fleets:Contractor and utility vehicle operators prioritizing durability over weight optimization. Southern European fleet procurement favors utility rack configurations.
- Aftermarket Installers:Independent service providers bridging product supply and vehicle-fit expertise. Spain and Portugal's compact-vehicle specialization creates regional concentration.
OEMs dominate value concentration. Retail customers represent the steepest expansion trajectory on adventure tourism participation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural export surplus in precision-engineered roof systems, while Spain and Portugal depend on Southern European supply chains for compact-vehicle architectures. China's regulatory convergence with ECE protocols is reshaping import certification requirements for multinational brands.
Germany
Thule Group and Cruzber SA anchor OEM supply agreements and aftermarket distribution networks across Nordic and Central European channels. KBA-administered type approval requirements for exterior-mounted accessories enforce stringent dynamic load testing. Manufacturing clusters concentrate in Baden-Württemberg and Bavaria, where integrated R&D facilities support ECE R14 certification workflows.
United States
NHTSA Federal Motor Vehicle Safety Standards govern roof rack integrity for highway-speed dynamic loads, creating compliance barriers for non-tested imports. Adventure tourism participation in Pacific Northwest and Rocky Mountain states drives specialty retail channel expansion. Yakima Products Inc. leverages outdoor-retail partnerships in Washington and Colorado markets where technical storytelling determines shelf access.
China
SAMR-enforced GB standard revisions are eliminating grandfathered products without dynamic testing protocols previously mandatory only under ECE R14. Yangtze River Delta manufacturing bases face facility upgrade pressures to meet converged certification timelines. MINTH Group Ltd. and JAC Products occupy positions within domestic supply chains serving both export and local OEM integration mandates.
Spain
Compact vehicle roof rail spacing common on local-market automobiles demands region-specific clamp geometries that lock out non-adapted competitors. Cruzber SA dominates Southern European aftermarket channels through specialized fitment architectures. Andalusian and Catalonian distribution hubs service Portugal's parallel compact-vehicle aftermarket requirements.
Sweden
Integrated aluminum extrusion and testing infrastructure supports premium positioning across Nordic and North American export markets. Thule Group leverages captive Swedish R&D facilities for ECE R14 compliance that accelerates multi-market certification. Manufacturing concentration in southern industrial corridors supplies both OEM flush-mount specifications and adjustable aftermarket configurations.
Automotive Roof Bar and Roof Racks Market Vendor Landscape
Concentration sits with integrated aluminum processors capable of captive alloy sourcing and in-house extrusion die production. Assembly-only brands without smelter contracts face margin compression from input volatility and are retreating toward non-structural accessory segments. Two strategic archetypes dominate: vertically integrated European multinationals with ECE testing infrastructure, and specialized outdoor-retail partners leveraging technical storytelling for shelf access. Competitive moves center on backward integration into extrusion-grade aluminum supply and geographic expansion through private-label manufacturing arrangements.
Among Swedish-anchored integrated manufacturers, Thule Group exemplifies the premium-tier archetype through captive R&D and testing facilities. Cruzber SA occupies a position within Southern European specialization, while Yakima Products Inc. represents the outdoor-retail partnership model concentrated in North American specialty channels. These three anchors illustrate how competitive positioning diverges between extrusion-capable processors and assembly-focused brands dependent on third-party alloy supply.
| Leading Market Players |
|---|
| Thule Group |
| Yakima Products Inc. |
| Rhino-Rack |
| Cruzber SA |
| Magna International Inc. |
| MINTH Group Ltd. |
| JAC Products |
| Atera GmbH |
| Kuat Racks |
| Others |
Supply Flow & Price Mechanics
Extrusion-grade 6061-T6 aluminum capacity utilization above eighty percent in German and Swedish manufacturing clusters concentrates pricing power among integrated processors with captive smelter contracts. Scale economies at Thule Group and Cruzber SA facilities compress unit fixed costs below what assembly-only competitors can achieve through third-party alloy sourcing. This cost asymmetry propagates through aftermarket channels in Spain and Portugal, where regional clamp geometry specialization locks out non-adapted brands from premium positioning.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ECE R14 certification grade and extrusion die ownership. Cost compression in the economy tier is intensifying because aluminum alloy input volatility squeezes margin pools at brands without scrap-recycling capabilities. Commercial fleet procurement in Southern Europe exhibits highest price sensitivity, while specialty outdoor retailers in Nordic markets absorb premium positioning for carbon fiber configurations.
Supply Chain Analysis
Yangtze River Delta port congestion periodically chokes containerized flow of extrusion-grade aluminum from Chinese smelters to European assembly houses. Supply concentrates in Germany, Sweden, and China, with raw material dependencies on bauxite refining capacity, extrusion die tooling, and ECE testing infrastructure. Single-source vulnerability runs through Yangtze-based alloy processors subject to SAMR facility upgrade mandates. Distribution runs through OEM direct supply agreements, specialty outdoor retail partnerships, and aftermarket installer networks serving compact-vehicle fitment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flush-mount OEM integration threatens to substitute away traditional clamp-on architectures, forcing incumbents to defend installed base relationships while repositioning toward aerodynamic system supply.
For Market Incumbents: Compound ECE R14 certification advantages by accelerating multi-market homologation timelines before China's GB standard convergence eliminates grandfathered products. Secure captive aluminum extrusion capacity in Baden-Württemberg or Bavaria clusters to defend margin pools against input volatility from Yangtze River Delta supply interruptions. Prioritize flush-mount R&D partnerships with German OEMs to offset displacement risk in aftermarket channels. For New Entrants and Emerging Players: Aftermarket installer technical support gaps in Spain and Portugal's compact-vehicle specialization present accessible entry points where Cruzber SA's regional dominance has not extended to service-layer depth. Target utility rack configurations for Southern European commercial fleets through direct procurement relationships with contractor associations. Pursue private-label manufacturing arrangements with Swedish integrated processors lacking Southern European distribution infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty outdoor retail partnerships where REI and MEC co-op memberships generate repeat accessory purchases across modular rail-and-tower architectures. Long-term viability in this market depends on backward integration into extrusion-grade aluminum supply or exclusive channel control at technical retailers. Monitor SAMR certification timeline compression as inflection indicator for consolidation pressure among export-dependent Chinese suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Capacity Expansion | Captive 6061-T6 alloy supply in German manufacturing clusters defends margin pools against Yangtze input volatility. |
| ECE R14 Certification Acceleration | Multi-market homologation timelines compress before China's GB standards eliminate grandfathered products from export eligibility. |
| Specialty Retail Channel Partnership | REI and MEC technical curation criteria reward brands with load-rating storytelling capabilities over price competition. |
| Flush-Mount R&D Investment | OEM aerodynamic integration mandates in Sweden and Germany displace traditional clamp-on architectures without design adaptation. |
| Regional Fitment Specialization | Spain and Portugal compact-vehicle roof rail spacing demands clamp geometries that exclude non-adapted competitors from aftermarket access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, vehicle production databases, and IHS Markit registration data. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and specialty outdoor retail category buyers. Secondary validation drew from KBA type approval filings, NHTSA Federal Motor Vehicle Safety Standard interpretations, and SAMR GB standard revision notices. Bottom-up demand modeling triangulated against top-down production capacity assessments across German, Swedish, and Chinese manufacturing clusters.
Segmentation dimensions modeled include product type, material grade, mounting architecture, and end-user procurement channel across the analysis window. CAGRs derived from regression analysis of historical production volumes against adventure tourism participation indices and electric vehicle payload optimization requirements. Forecast inputs incorporated aluminum alloy pricing volatility scenarios and ECE R14 certification timeline compression effects on multi-market product launch schedules.
Underlying assumptions cover stable regulatory convergence between SAMR and ECE protocols, with deviation risk concentrated in divergent NHTSA crash-test protocol adoption or Yangtze River Delta logistics disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Structural Sheet Market