
 Automotive Roof Rails Market | 2026-2036
Automotive Roof Rails Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Roof Rails Market Outlook
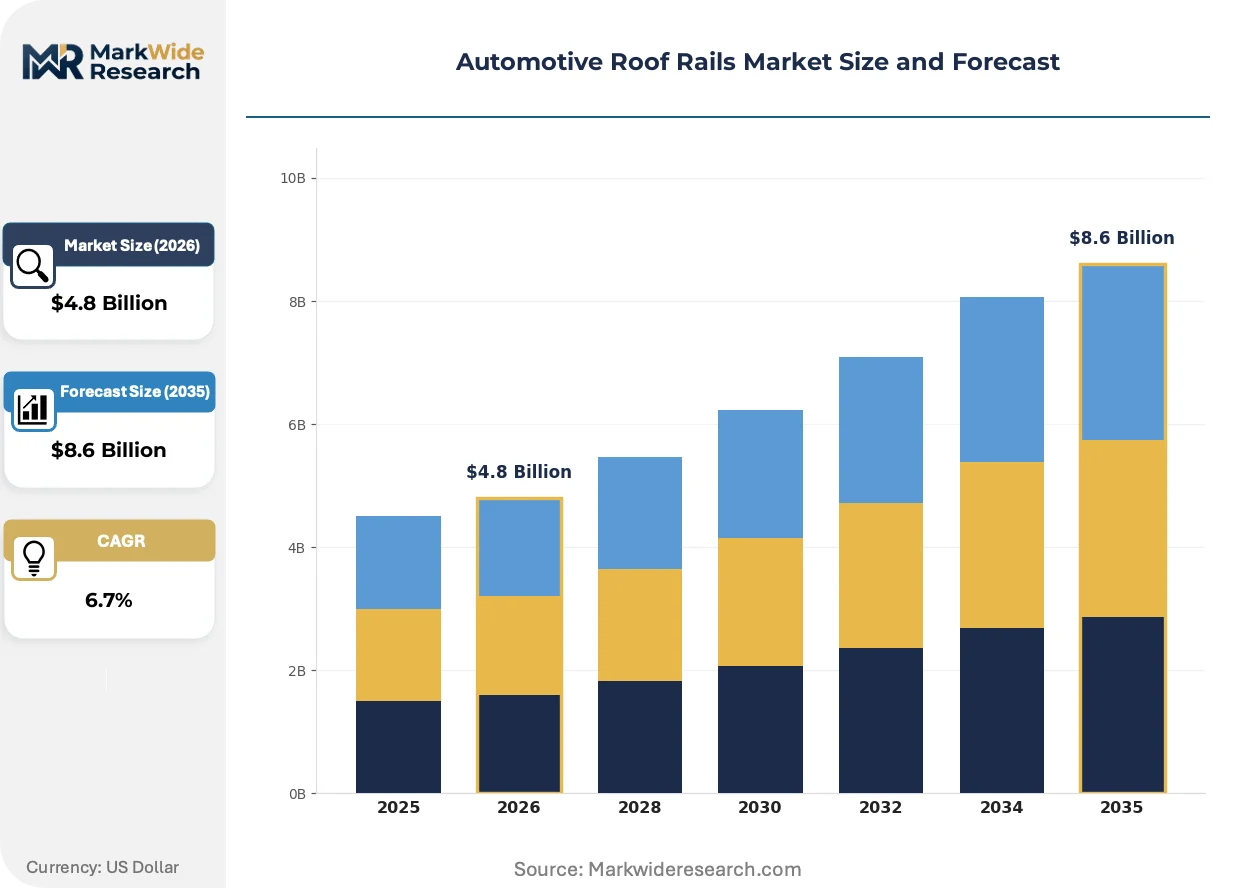
Subscription-based accessory activation is repositioning how roof rails enter vehicle transactions, with automakers treating crossbars and carrier compatibility as software-unlockable features rather than standard hardware. Thule Group AB leverages its brand strength across premium outdoor retail channels to sustain pricing power in the aftermarket. Magna International Inc. anchors factory-installed programs through direct OEM relationships, while Yakima Products Inc. competes on specialized rack architectures for trucks and overland vehicles.
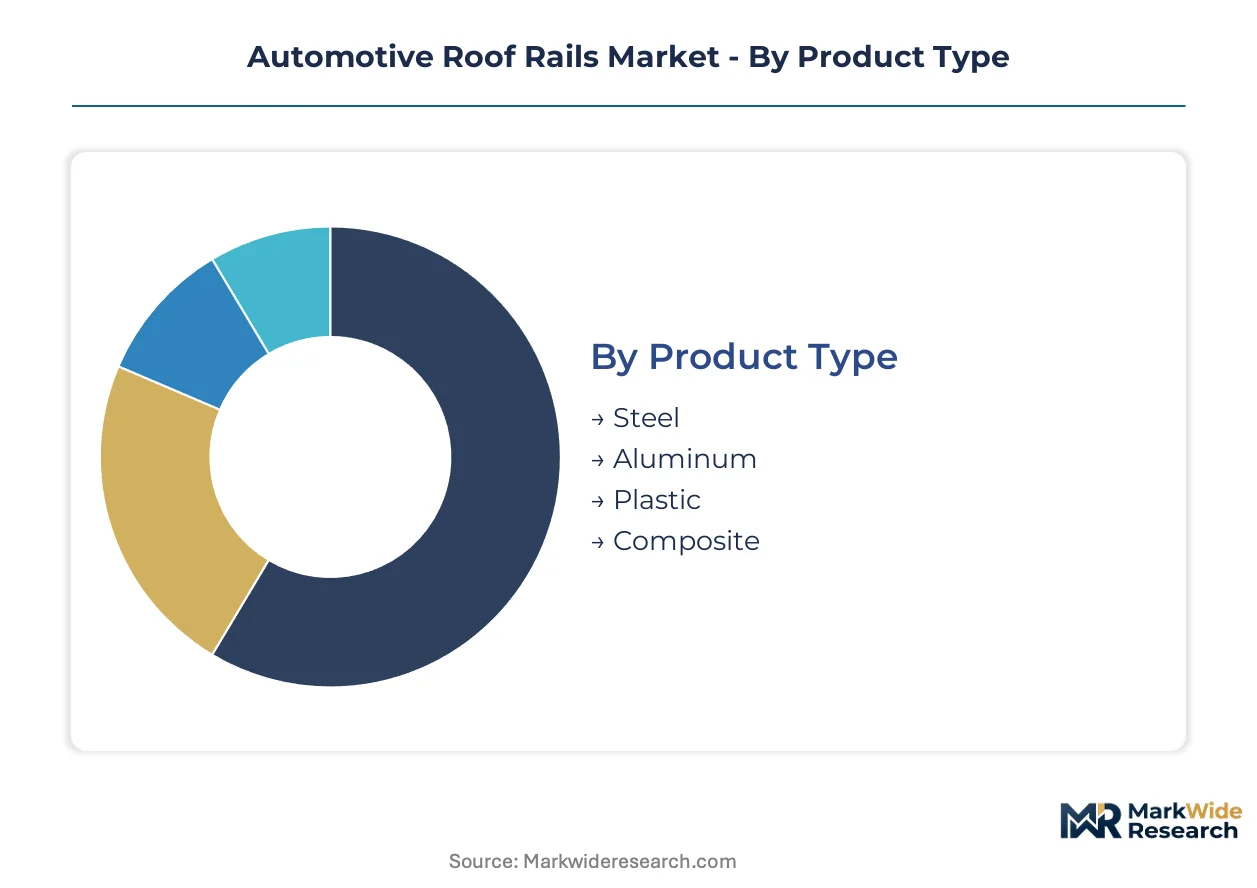
Automotive roof rails are load-bearing structural members mounted longitudinally along a vehicle's roof, typically extruded from aluminum alloys or stamped steel and rated for dynamic loads between 75 and 100 kilograms at highway speeds. Their primary purpose is to provide certified anchor points for cargo carriers, bicycle mounts, and ski racks without compromising roof panel integrity. Aluminum roof rails lead product type value generation due to their strength-to-weight advantage in crossover and SUV platforms, while composite materials represent the fastest-growing segment as thermoplastic manufacturing processes mature. Factory-installed systems dominate volume among OEMs, though aftermarket channels capture higher per-unit margins through customization and retrofit demand.
NHTSA roof crush resistance standards and ECE R14 seat and seat anchor regulations indirectly shape roof rail load certification requirements in the United States and Europe. EPA fuel economy testing methodologies penalize weight, pushing automakers toward lighter aluminum and composite rail designs that still satisfy FMVSS 216a structural criteria. Stakeholders must monitor how software-defined vehicle architectures convert physical roof rail sales into digital accessory ecosystems with recurring revenue potential.
Market Dynamics
EPA fuel-economy testing protocols and EU pedestrian safety standards are compressing material choices toward aluminum and composite architectures, while software-defined vehicle platforms convert physical roof rails into digital accessory ecosystems with recurring revenue potential.
Growth Catalysts
- Adventure trim bundling:Automakers package roof rails with outdoor lifestyle options on SUV and crossover platforms, embedding factory-installed systems into premium vehicle configurations.
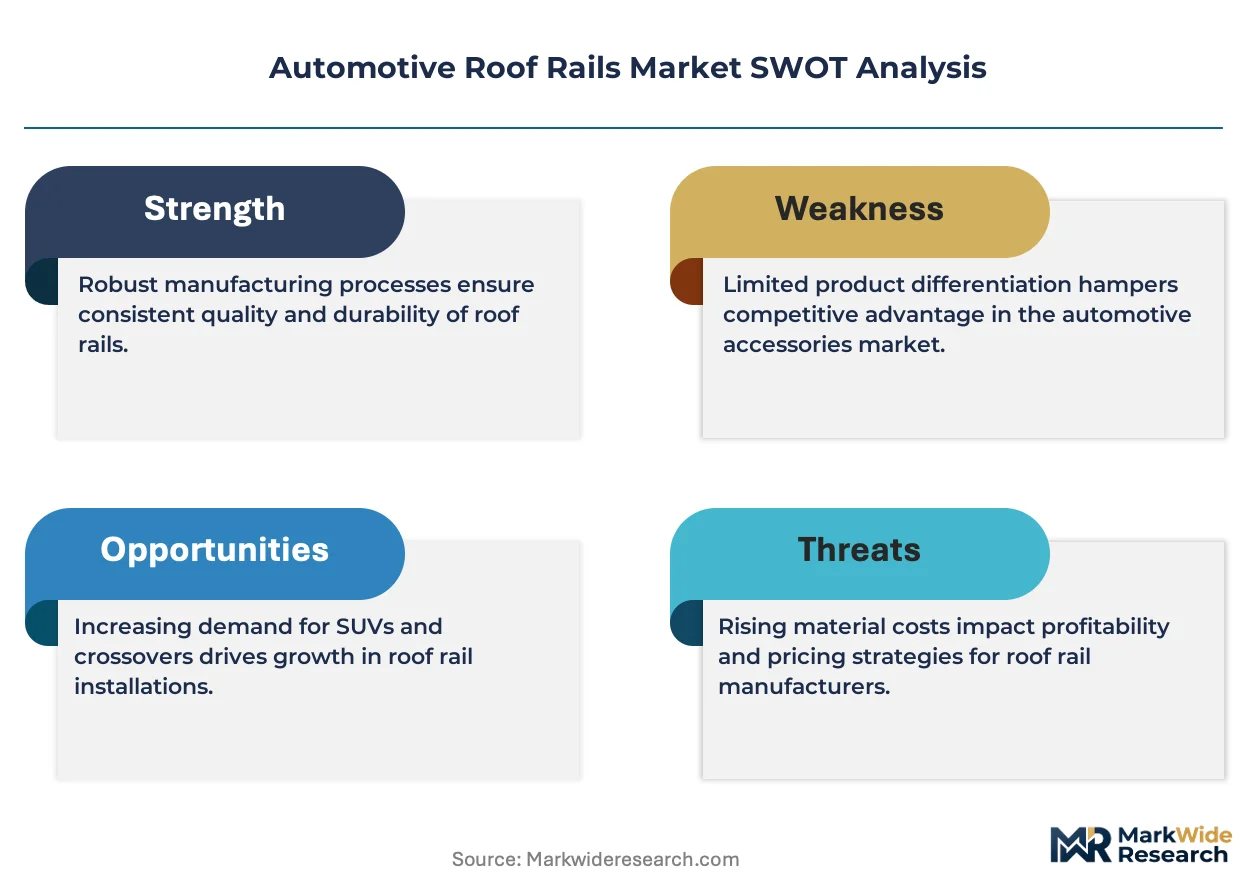
- REACH compliance pressure:European chemical safety mandates accelerate thermoplastic composite adoption by restricting certain metal finishing processes and coating chemistries.
- Lightweighting imperatives:Aluminum extrusion advances deliver strength-to-weight ratios that satisfy FMVSS 216a roof crush criteria while reducing mass penalties in EPA test cycles.
Market Restraints
- Aluminum price volatility:LME aluminum futures fluctuations compress margins for extruded rail manufacturers locked into annual OEM supply agreements.
- German supplier cluster concentration:Thule Group AB and Atera GmbH anchor production in a single regulatory jurisdiction, creating geographic exposure to EU energy cost spikes.
- Steel substitution threat:High-strength stamped steel rails retain cost advantage in economy vehicle segments where weight penalties are less critical to fleet averages.
Strategic Opportunities
- Software-unlockable crossbars:Subscription-based accessory activation treats roof rail functionality as digital features rather than standard hardware, opening recurring revenue streams.
- Overland vehicle specialization:Dynamic load ratings above 100 kilograms for truck and off-road platforms address unmet demand in the aftermarket channel.
- India PLI scheme alignment:Component manufacturing incentives for automotive suppliers create localized production advantages for export-oriented rail systems.
Industry Challenges
- Cross-functional talent scarcity:Composite thermoplastic processing expertise remains concentrated in aerospace and wind energy sectors, limiting automotive transfer.
- Dual certification timelines:Parallel NHTSA and ECE R14 homologation requirements extend product launch cycles by 8-14 months for global platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Roof Rails Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Plastic, Composite Vehicle Type: SUVs, Trucks, Vans, Crossover Installation Type: Permanent, Removable, Factory-Installed, Aftermarket End User: OEMs, Aftermarket Retailers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Thule Group AB, Yakima Products Inc., Rhino-Rack, Magna International Inc., Atera GmbH, Cruzber SA, KAMEI GmbH & Co. KG, Kuat Innovations, JAC Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Roof Rails Market Strategic Shifts
Material science advances and regulatory compression are converging to reshape how roof rails enter vehicle transactions, with digital monetization models displacing traditional hardware bundling strategies.
Thermoplastic composite manufacturing is consolidating around long-fiber reinforced polypropylene systems that integrate directly with roof panel stampings. Tier 1 suppliers adopt these processes for 2026-2028 platform refreshes. This consolidation is compressing the supplier base by favoring capital-intensive integrators over discrete component vendors.
EPA fuel economy testing methodologies now penalize roof rail mass in corporate fleet calculations, pushing automakers toward hollow aluminum extrusions and hybrid metal-composite designs. The structural consequence extends beyond material substitution to platform-level architecture decisions. Crossover segments in the United States face the steepest compliance pressure.
Outdoor retail channel consolidation concentrates aftermarket purchasing power in specialty chains and direct-to-consumer platforms. Independent distributors lose shelf space to Thule Group AB's vertical retail presence. This behavioral shift is most visible in Germany and Nordic markets where adventure tourism penetration drives replacement cycle compression.
Automotive Roof Rails Market Segmentation
Roof rail upgrade cycles diverge sharply across vehicle platforms, with factory-installed systems locking in material specifications for 5-7 year platform lifespans while aftermarket channels compress replacement intervals through seasonal accessory turnover. Segmentation reveals where margin concentrates versus where volume scales.
Product Type:
Upgrade decisions pivot on weight penalties versus structural certification requirements, with each material class occupying distinct positions in the cost-performance spectrum.
- Steel:High-strength stamped steel rails deliver lowest unit cost for economy vehicle segments. Fleet procurement in India and Brazil favors steel for its durability in high-temperature climates where coating degradation accelerates.
- Aluminum:Hollow aluminum extrusions dominate crossover and SUV factory installations, satisfying FMVSS 216a roof crush criteria at 40% lower mass than equivalent steel sections. EPA fuel economy testing methodologies penalize weight, concentrating aluminum demand in United States premium platforms where fleet compliance pressure intensifies.
- Plastic:Glass-filled nylon rails serve cosmetic and light-duty applications in entry-level hatchbacks. Thermoplastic processing enables color-matched integration with roof moldings, though dynamic load ratings remain below 50 kilograms.
- Composite:Long-fiber reinforced polypropylene systems integrate directly with roof panel stampings, emerging as the primary lightweighting pathway for 2026-2028 platform refreshes. REACH compliance pressure accelerates adoption by restricting certain metal finishing chemistries in European production.
Aluminum sits at the top of the volume ranking, with composite climbing the fastest.
Vehicle Type:
Application intensity varies by roof architecture, with raised-rail designs enabling higher dynamic load ratings than flush-mount systems.
- SUVs:Body-on-frame SUVs generate highest per-vehicle rail specification, with dynamic load ratings of 100 kilograms supporting rooftop tent and cargo carrier configurations. Factory-installed systems dominate, bundled with adventure trim packages in German and United States markets.
- Trucks:Cab-mounted rails on pickup trucks address overland and contractor segments, requiring reinforced anchor points for ladder racks and utility carriers. Aftermarket channels capture elevated margins through specialized mounting hardware.
- Vans:Commercial van fleets prioritize low-cost steel rails for ladder and equipment mounting, with procurement concentrated in fleet operator direct agreements rather than retail channels.
- Crossover:Unibody crossovers represent the largest addressable volume, with flush-mount rail designs proliferating as automakers streamline roof profiles for aerodynamic efficiency. Weight sensitivity in this segment drives aluminum specification.
Crossover generates the highest unit volume, with truck applications expanding most quickly in aftermarket channels.
Installation Type:
Channel economics diverge between captive OEM supply and independent retail, with installation permanence determining replacement frequency.
- Permanent:Welded or adhesive-bonded rails integrated during body-in-white assembly deliver structural continuity but eliminate upgrade pathways. OEMs favor permanent installation for platforms targeting 10-year service life.
- Removable:Bolt-on rail systems enable seasonal removal to reduce aerodynamic drag, concentrated in Nordic markets where winter ski carrier demand peaks. Thule Group AB anchors aftermarket supply for removable configurations.
- Factory-Installed:Line-fit rails specified at vehicle order capture command premium pricing through bundling with exterior trim packages. Magna International Inc. holds direct OEM relationships for factory-installed programs.
- Aftermarket:Retrofit rails address vehicle populations without factory equipment, with demand concentrated in 3-5 year old used vehicle cohorts. Specialty chains and direct-to-consumer platforms consolidate purchasing power, compressing independent distributor margins.
Factory-installed systems lead in value generation, with aftermarket climbing fastest through e-commerce channel expansion.
End User:
Procurement authority determines specification control, with OEMs dictating material standards that cascade through supplier tiers.
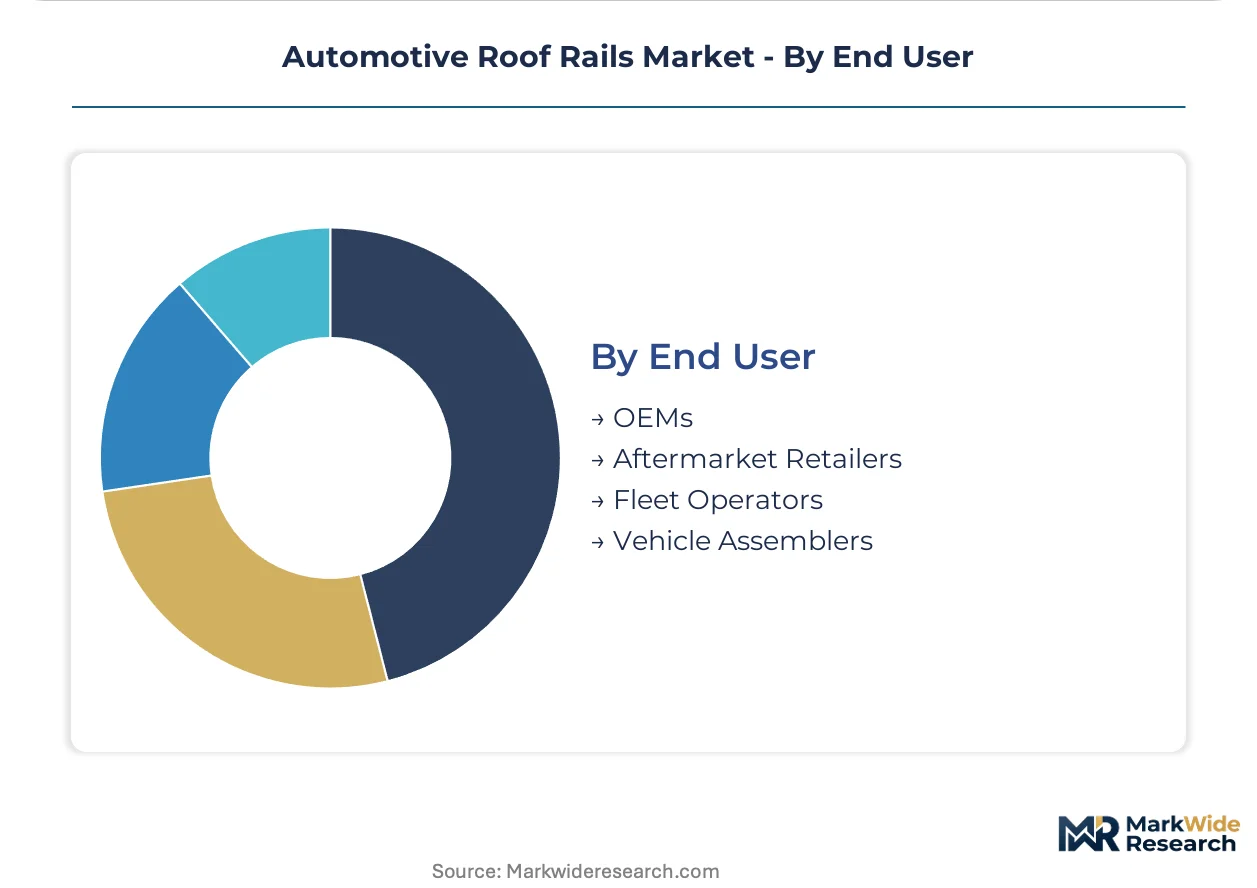
- OEMs:Vehicle manufacturers specify rail architecture during platform development, locking in 5-7 year supply agreements with Tier 1 integrators. Aluminum extrusion and composite processing capabilities filter supplier selection.
- Aftermarket Retailers:Specialty outdoor chains and direct-to-consumer platforms curate carrier-compatible rail systems, with Thule Group AB's vertical retail presence concentrating shelf space in Germany and Nordic markets.
- Fleet Operators:Commercial vehicle fleets procure rails through direct specification in upfitter agreements, prioritizing steel durability and standardized mounting patterns across vehicle classes.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants source rails through kit consolidation, with India PLI scheme alignment creating localized production advantages for export-oriented systems.
OEMs command the specification hierarchy, with aftermarket retailers gaining share fastest through channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium SUV factory installations while the United States drives aluminum lightweighting compliance, revealing divergent material priorities across major automotive markets.
United States
NHTSA roof crush resistance standards and EPA fuel economy testing penalize rail mass in corporate fleet calculations. FMVSS 216a structural criteria push automakers toward hollow aluminum extrusions. Detroit's supplier corridor anchors Magna International Inc. factory-installed programs for domestic crossover platforms.
Germany
Thule Group AB and Atera GmbH concentrate production in a dense supplier cluster serving premium SUV and crossover output. REACH compliance pressure restricts certain metal finishing chemistries, accelerating thermoplastic composite adoption. Stuttgart and Munich metropolitan areas host integrated rail-to-platform engineering centers.
China
MIIT fuel consumption standards and GB vehicle safety protocols shape aluminum specification for domestic crossover production. Yangtze River Delta manufacturing bases supply both local OEMs and export-oriented rail systems. Shanghai-based stamping integrators consolidate composite thermoplastic processing capabilities.
India
PLI scheme alignment for automotive component manufacturing creates localized production advantages for export-oriented rail systems. BIS certification requirements filter supplier entry for factory-installed programs. Gujarat and Maharashtra industrial corridors attract aluminum extrusion investments serving compact SUV platforms.
Japan
METI energy efficiency regulations and JIS structural standards favor lightweight aluminum architectures in domestic crossover segments. Kanto region engineering centers specialize in adhesive-bonded rail integration for unibody platforms. Toyota City supplier networks pioneer hybrid metal-composite designs for 2026-2028 platform refreshes.
Automotive Roof Rails Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with aftermarket channels concentrating around outdoor retail brands while OEM supply tilts toward tier-one integrators. The vendor base organizes into three strategic archetypes: premium branded specialists, diversified automotive suppliers, and regional fabrication houses. Consolidation pressures favor capital-intensive integrators with composite processing capabilities. Competitive moves center on direct OEM relationship expansion and vertical control over aluminum extrusion supply.
Among branded specialists, Thule Group AB and Yakima Products Inc. exemplify the premium-tier archetype, occupying positions that leverage outdoor retail channel presence. Magna International Inc. represents the diversified automotive supplier model, anchoring factory-installed programs through direct OEM relationships. These three entities illustrate how competitive positioning diverges between aftermarket margin capture and captive supply agreements.
| Leading Market Players |
|---|
| Thule Group AB |
| Yakima Products Inc. |
| Rhino-Rack |
| Magna International Inc. |
| Atera GmbH |
| Cruzber SA |
| KAMEI GmbH & Co. KG |
| Kuat Innovations |
| JAC Products |
| Others |
Value Chain & Pricing Dynamics
Aluminum-to-composite certification tiers split the market into distinct procurement lanes, with premium unibody platforms commanding hollow extrusion systems while economy segments tolerate stamped steel. This material divergence concentrates supply chain leverage among German and Chinese extrusion houses, compressing margin capture for fabricators lacking in-house smelter relationships or thermoplastic processing capabilities.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for aluminum extrusions, forcing incumbent suppliers to defend position through long-term offtake contracts with Yangtze River Delta mills. Three-tier pricing structure across premium, standard, and economy levels reflects FMVSS 216a certification grade, volume scale commitments, and geographic delivery cost. Price erosion runs through economy steel rails as Indian PLI scheme recipients absorb margin compression to secure OEM qualification. Fleet operators exhibit highest price sensitivity, while German premium SUV platforms prioritize lightweighting performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Detroit and Stuttgart OEMs mandate multi-supplier qualification across Germany, China, and Mexico, preventing single-factory dependency. Raw material flows draw from LME-linked aluminum smelters, long-fiber polypropylene compounders, and high-strength steel coil producers. Single-source vulnerability concentrates in thermoplastic composite processing, where aerospace-trained technicians remain scarce. Distribution runs through Tier 1 integrators for factory-installed programs, while aftermarket channels consolidate around Thule Group AB's direct-to-consumer platforms and specialty retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs and Indian PLI scheme subsidies, with component manufacturing incentives in Gujarat and Maharashtra undercutting European energy-adjusted production by substantial margins.
For Market Incumbents: Anticipate thermoplastic composite substitution by securing aerospace processing talent through targeted recruitment from wind energy sectors. Defend margin position by deepening backward integration into aluminum billet supply and qualifying secondary extrusion capacity in India before PLI scheme windows narrow. Certification investment in parallel NHTSA-ECE R14 homologation accelerates global platform access. For New Entrants and Emerging Players: Capture overland vehicle specialization in the aftermarket channel, where dynamic load ratings above 100 kilograms remain underserved by incumbent catalog offerings. Target truck and off-road platforms in the United States and Australia through direct-to-consumer digital distribution. Go-to-market leverage rests on specialized mounting hardware compatibility with Yakima Products Inc. and Rhino-Rack carrier ecosystems. For Investors and Strategic Acquirers: Consolidation pressure builds where composite thermoplastic capabilities intersect with direct OEM relationships, squeezing discrete component vendors without platform integration expertise. Long-term viability favors capital-intensive integrators controlling extrusion supply and adhesive-bonded assembly processes. Acquisition target archetype: regional fabricators with qualified Magna International Inc. or Thule Group AB supply history and latent composite processing capacity. Signal to watch: NHTSA rulemaking on software-defined accessory monetization that would revalue hardware suppliers toward recurring revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies rail architectures across crossover and SUV lineups, reducing Magna International Inc. engineering overhead. |
| Aluminum Supply Agreement | Locks in Yangtze River Delta smelter capacity for Detroit OEM lightweighting compliance. |
| Software-Defined Vehicle Investment | Converts Thule Group AB hardware sales into subscription-unlockable crossbar revenue streams. |
| Geographic Manufacturing Footprint | Positions Gujarat extrusion plants to capture India PLI scheme benefits for export-oriented rail systems. |
| Composite Processing Partnership | Transfers aerospace thermoplastic expertise to automotive roof panel stamping integration. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists were cross-validated against secondary sources including vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and customs records tracking aluminum extrusion trade flows. Triangulation between end-use demand signals and supply-side capacity announcements filters out inventory distortion effects.
Input-output matrices map material flow from aluminum smelter and polypropylene compounder through extrusion, stamping, and adhesive assembly stages to final vehicle line-fit or aftermarket retail. Segmentation dimensions span vehicle class, installation permanence, material specification, and regional production cluster. CAGRs were derived from production volume trajectories weighted by content-per-vehicle assumptions and material substitution curves. Industry-specific forecast inputs include EPA fuel economy test cycle weight penalties and ECE R14 homologation timeline compression.
Aluminum price volatility, REACH regulatory expansion, and software-defined vehicle monetization timing are the dominant revision risks to the projection horizon. Forecasts embed assumptions on composite thermoplastic adoption rates and OEM bundling strategies for adventure trim packages. Deviation in NHTSA rulemaking on digital accessory activation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
China Automotive Heat Exchanger Market