
 Automotive Constant Velocity Joint Market | 2026-2036
Automotive Constant Velocity Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Constant Velocity Joint Market Analysis
Electric vehicle powertrains are rebalancing the traditional CVJ demand mix as front-wheel-drive architectures give way to dual-motor and e-axle configurations. SKF leverages its bearing-to-joint integration expertise to capture design-in opportunities with European EV platforms. GKN Automotive sustains technology leadership through its countertrack joint architecture optimized for high-torque e-motor outputs. JTEKT Corp. anchors its position in Asian supply chains with manufacturing scale across Japan, China, and Thailand.
An automotive constant velocity joint transmits rotational power between shafts at variable angles while maintaining constant angular velocity, typically employing hardened steel races with precision-ground ball bearings or tripod rollers operating within grease-lubricated housings. These components enable independent suspension articulation and steering function in front-wheel-drive and all-wheel-drive vehicles, with torque capacity ratings spanning from compact passenger car loads to heavy-duty commercial vehicle demands. Standard joint configurations still occupy the largest installed base across internal combustion portfolios, yet bolt-on joint variants are gaining traction in modular EV platform designs where serviceability and assembly speed carry premium value. Composite material experimentation is accelerating among tier-1 suppliers seeking mass reduction for range-sensitive battery electric applications, though steel retains dominance in torque-dense segments.
FDA oversight of automotive-grade lubricants and EPA fuel economy standards indirectly shape CVJ efficiency targets in the United States, while China's MIIT enforces NEV penetration quotas that cascade into driveline specification changes for domestic assemblers. The EU Green Deal's embedded carbon requirements are pressuring suppliers to document Scope 3 emissions across steel and aluminum feedstocks, tightening market access for undifferentiated producers. Stakeholders must monitor how platform consolidation among EV-native architectures reshapes joint count per vehicle and whether aftermarket channel structures adapt to sealed e-axle units with non-serviceable designs.
Market Dynamics
EV platform consolidation is compressing joint counts per vehicle while simultaneously elevating torque density requirements for remaining driveline positions, forcing suppliers to recalibrate volume forecasts against performance premiums.
Growth Catalysts
- China's NEV mandate:MIIT penetration quotas force domestic OEMs to redesign drivelines around e-axle architectures, creating procurement pull for high-efficiency joint variants.
- Composite material experimentation:Tier-1 suppliers accelerate carbon fiber-reinforced polymer trials to reduce unsprung mass in battery electric platforms.
- Yangtze River Delta concentration:Joint-venture partnerships between global suppliers and Chinese OEMs localize production capacity for regional EV export programs.
Market Restraints
- Steel feedstock volatility:Hardened alloy steel prices fluctuate with energy costs, compressing margin buffers for precision-ground race manufacturers.
- Sealed e-axle designs:Non-serviceable integrated units eliminate traditional aftermarket replacement cycles, eroding recurring revenue streams for independent distributors.
- Euro 7 tolerance tightening:Rotational efficiency thresholds demand manufacturing investments that smaller forging houses cannot amortize across thin EV volumes.
Strategic Opportunities
- Modular EV platforms:Bolt-on joint configurations enable faster assembly line integration for contract manufacturers serving EV-native startups.
- EU Green Deal Scope 3 documentation:Early adopters of embedded carbon tracking capture preferential sourcing status with European OEMs facing CSRD disclosure requirements.
- Countertrack architecture licensing:High-torque joint designs developed for performance e-motors transfer to heavy-duty commercial electrification applications.
Industry Challenges
- Precision grinding skill scarcity:Hardened steel race finishing requires journeyman-level expertise that vocational pipelines have not replenished as automotive manufacturing automated.
- Grease formulation recertification:FDA automotive lubricant standards and evolving OEM specs force repeated validation cycles that delay platform launches.
- Legacy ICE joint inventory:Front-wheel-drive service parts demand persists while EV joint specifications diverge, complicating SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Constant Velocity Joint Market |
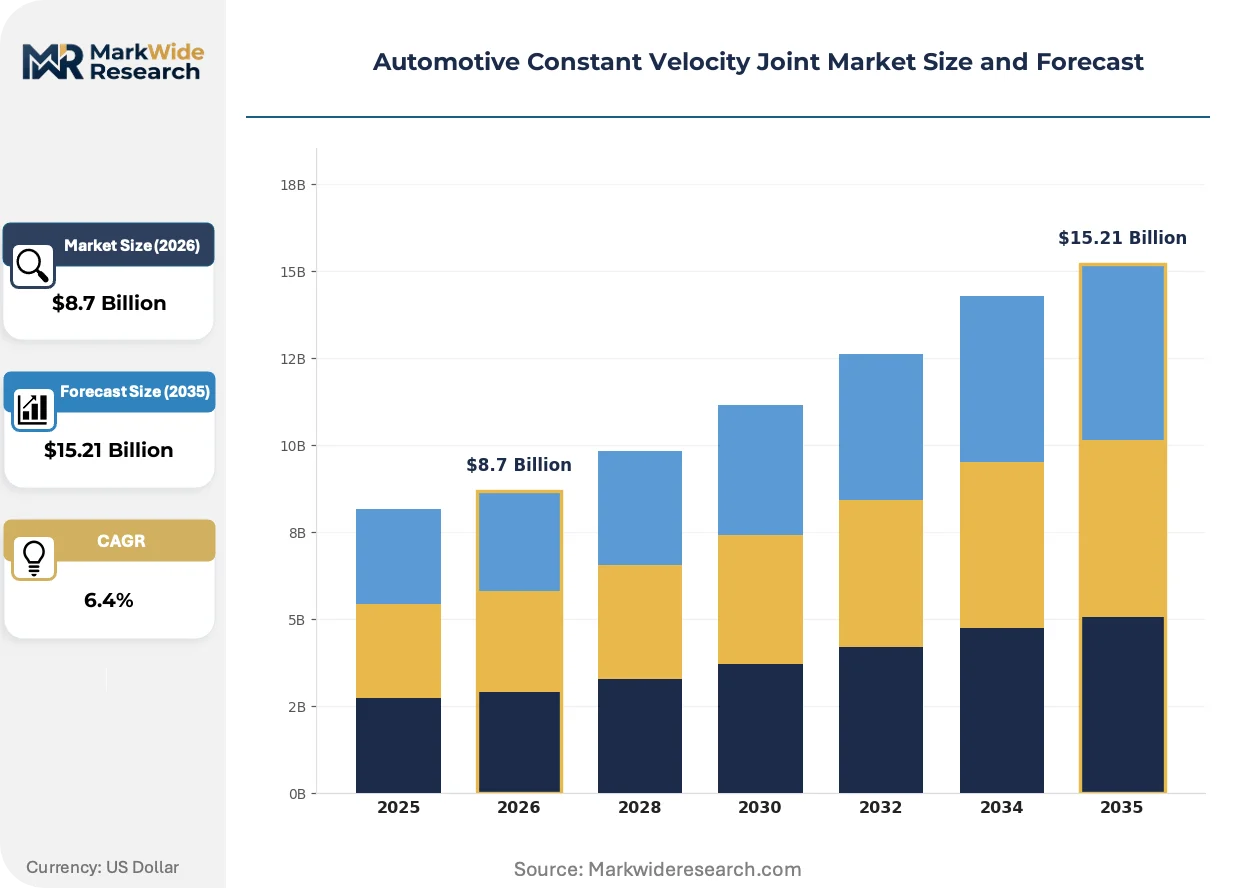
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Joint, Tripod Joint, Double Offset Joint, Bolt-On Joint End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Steel, Aluminum, Composite, Plastic Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles |
| Companies Covered | SKF, Hyundai WIA Corporation, GKN Automotive, Dana Inc., JTEKT Corp., NTN Corporation, IFA Rotorion, Nexteer Automotive, American Axle & Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Constant Velocity Joint Market Emerging Trajectories
Powertrain electrification is fundamentally rewiring CVJ design priorities away from angular articulation range toward torque density optimization and thermal management integration.
Integrated bearing-joint units are electrifying driveline packaging efficiency by combining rotational support and torque transmission in single housings. European EV platforms specify these consolidated modules to reclaim underhood volume for battery thermal systems. SKF and GKN Automotive capture design-in opportunities by offering validated subassemblies that reduce OEM assembly steps.
REACH substance restrictions on perfluorinated grease chemistries force reformulation of high-temperature lubricants used in e-axle applications. Suppliers must resubmit material safety documentation while maintaining viscosity stability across wider thermal operating windows. German KBA type-approval timelines extend as regulators scrutinize biodegradability claims against actual field degradation data.
Aftermarket channel structures face compression as sealed e-axle units eliminate traditional service intervals. Independent distributors in North America pivot toward diagnostic equipment and thermal management fluids to offset declining joint replacement volumes. OEM captive service networks capture an expanding share of driveline maintenance spend through software-locked calibration procedures.
Automotive Constant Velocity Joint Market Segmentation
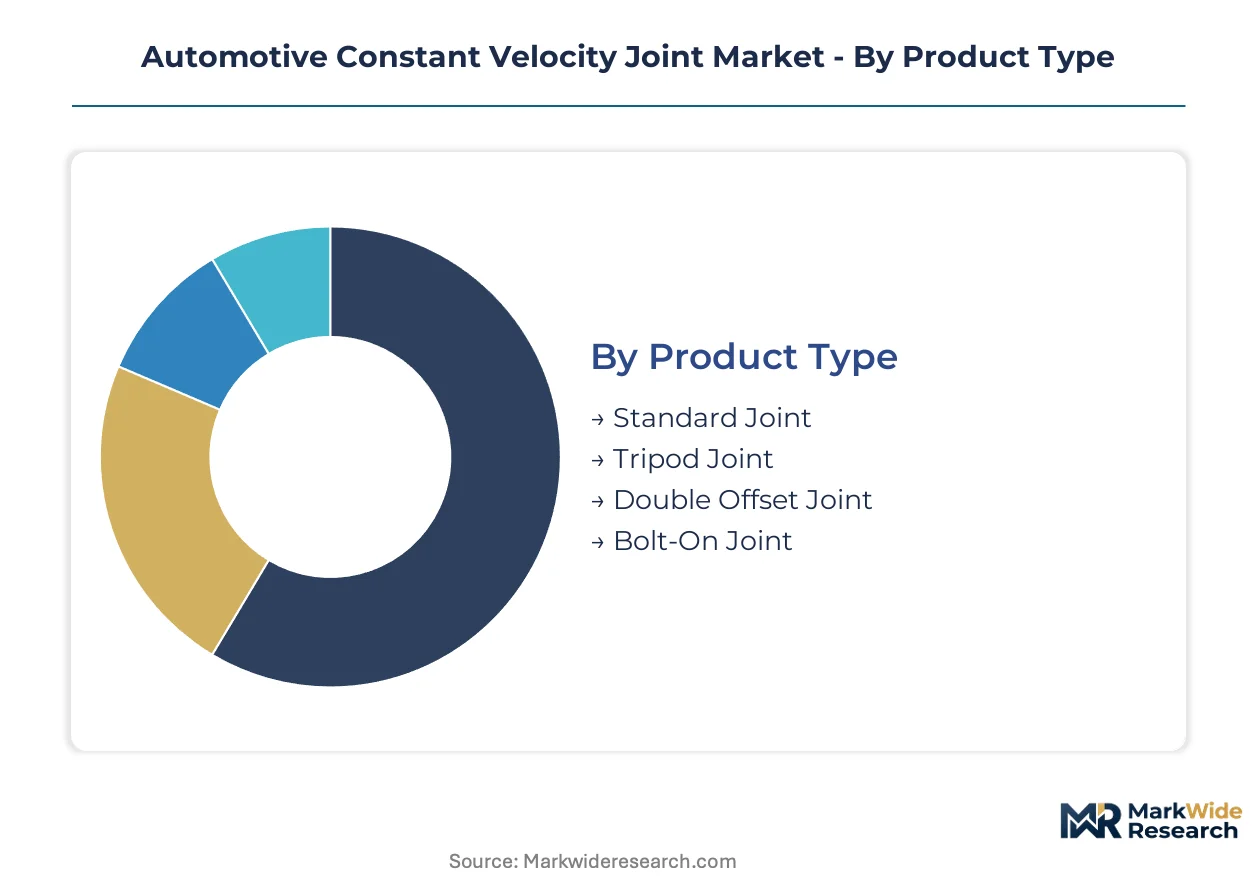
CVJ procurement patterns diverge sharply across product architectures and customer channels, with electrification forcing suppliers to rebalance capacity between legacy ICE service parts and torque-dense e-axle designs. Material choices and application specifications now determine factory tooling requirements more than volume scale alone.
Product Type:
Capital intensity peaks with precision grinding investments for ball-race geometries, while bolt-on variants require lighter assembly automation.
- Standard Joint:Hardened steel races with six-ball configurations dominate front-wheel-drive ICE portfolios. Demand concentrates in China's Yangtze River Delta service channels, where domestic OEMs maintain dual sourcing for joint-venture export programs.
- Tripod Joint:Three-roller architectures accommodate higher plunge angles in transverse powertrains. European EV platforms specify these for e-axle inner joint positions, driven by packaging constraints in dual-motor configurations.
- Double Offset Joint:Offset center designs enable constant velocity across wider articulation ranges.
- Bolt-On Joint:Modular interfaces prioritize assembly line speed over maximum torque density.
Most installed capacity flows through Standard Joint variants. Expansion is steepest in Bolt-On Joint configurations for contract EV manufacturing.
End User:
Customer concentration shapes working capital requirements, with OEMs demanding 90-day payment terms and aftermarket distributors requiring buffer inventory financing.
- OEMs:Platform engineering teams specify joint torque ratings and thermal envelopes during vehicle development cycles. Procurement concentrates with German and Japanese automakers integrating e-axle modules at dedicated EV assembly plants.
- Aftermarket Providers:Independent distributors stock replacement joints for ICE vehicle parc maintenance. Sealed e-axle designs threaten this channel's recurring revenue, forcing pivots toward diagnostic tooling.
- Vehicle Assemblers:Contract manufacturers serving EV-native startups favor pre-validated subassemblies.
- Tier-1 Suppliers:Driveline integrators capture design-in value through bearing-joint consolidation.
Volume concentrates with OEM direct procurement. Margin expansion is most pronounced in Tier-1 Supplier captive production arrangements.
Material:
Raw material volatility exposure varies by feedstock, with alloy steel spot prices tracking energy costs more closely than aluminum ingot.
- Steel:Case-hardened alloy grades retain dominance in torque-dense applications. Demand concentrates in heavy-duty commercial electrification, where e-motor peak outputs exceed 500 Nm.
- Aluminum:Die-cast housings reduce unsprung mass in battery electric passenger vehicles. European OEMs specify these for range-sensitive platforms, driven by EU Green Deal embedded carbon accounting requirements.
- Composite:Carbon fiber-reinforced polymer trials target mass reduction in performance EV segments.
- Plastic:Polyamide cages and seals replace metal in low-load auxiliary drives.
Steel maintains the largest installed base. Composite experimentation is gaining share fastest in premium EV architectures.
Application:
Duty cycle severity determines validation testing duration, with off-road applications requiring extended durability certification.
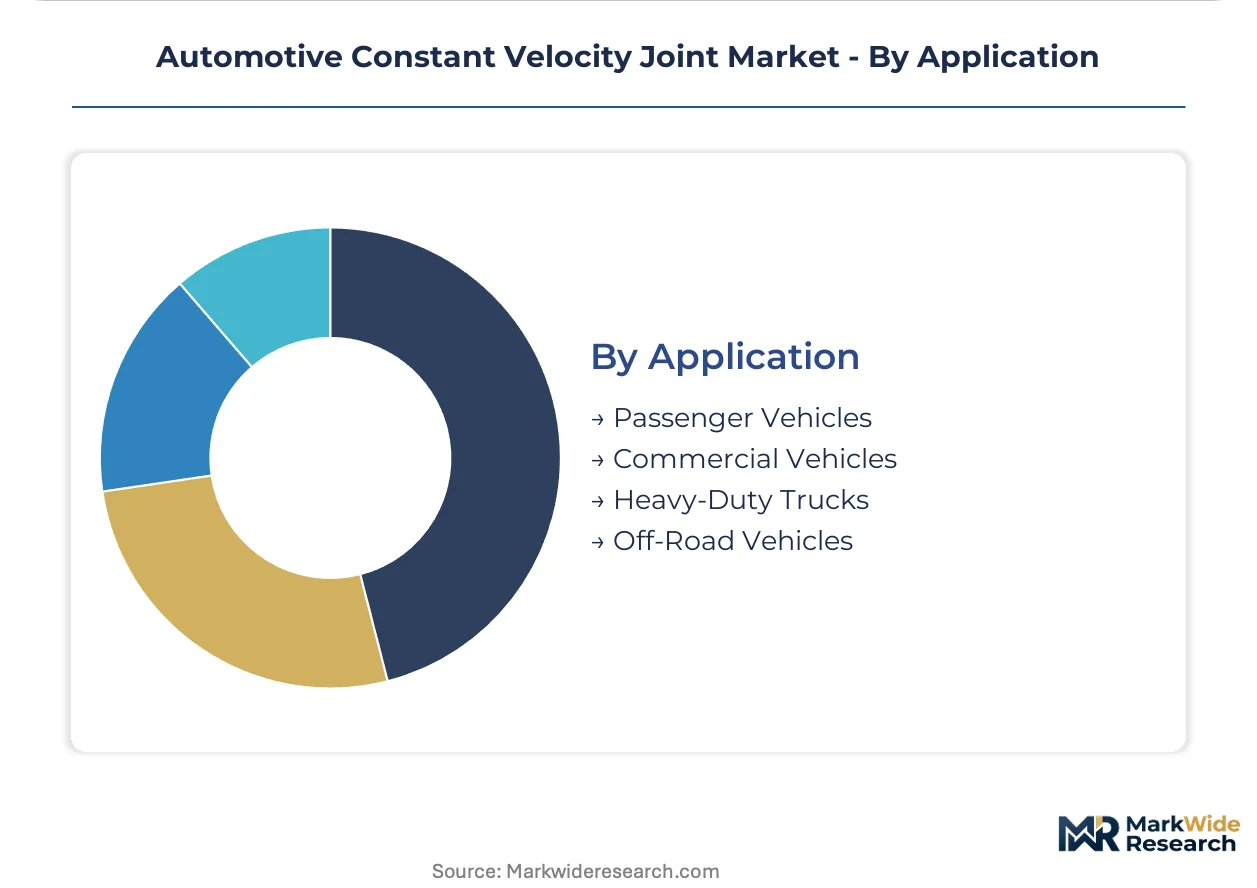
- Passenger Vehicles:Compact and midsize platforms generate highest unit volumes. China's MIIT NEV quotas redirect procurement toward e-axle optimized designs with integrated thermal management.
- Commercial Vehicles:Light commercial electrification demands higher torque density than passenger car equivalents. European urban delivery fleets specify these for last-mile logistics consolidation.
- Heavy-Duty Trucks:Long-haul electrification prototypes stress-test joint architectures at sustained high torque.
- Off-Road Vehicles:Agricultural and construction equipment requires sealed designs against contamination ingress.
Passenger Vehicles absorb most production capacity. Commercial Vehicles are climbing the fastest as urban logistics electrifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta automotive cluster concentration shapes procurement patterns across the industry's largest volume basin. MIIT NEV quotas and Euro 7 tolerance thresholds are compressing supplier margins in divergent regulatory directions. Regional production footprints now determine market access more than historical brand relationships.
China
Domestic OEMs and joint-venture partners source localized CVJ production for regional EV export programs. MIIT enforces NEV penetration quotas that cascade into driveline specification changes for assemblers. Shanghai and surrounding Jiangsu and Zhejiang provinces concentrate forging capacity serving both European and Southeast Asian export channels.
Germany
KBA type-approval timelines extend as regulators scrutinize biodegradability claims against field degradation data. EU Green Deal embedded carbon requirements pressure suppliers to document Scope 3 emissions across steel feedstocks. Stuttgart and Wolfsburg engineering centers specify integrated bearing-joint modules for dedicated EV assembly plants.
United States
FDA oversight of automotive-grade lubricants and EPA fuel economy standards indirectly shape CVJ efficiency targets. Detroit Three platform engineering teams specify joint torque ratings during development cycles. Michigan and Ohio manufacturing corridors retain forging heritage despite accelerating EV transition timelines.
Japan
METI industrial policy supports precision grinding skill retention through vocational pipeline investments. JIS standards govern case-hardened alloy grade specifications for torque-dense applications. Nagoya and Tokyo metropolitan areas anchor tier-1 supplier headquarters coordinating Thailand and Indonesia satellite production.
South Korea
Domestic chaebol EV platforms drive procurement pull for high-efficiency joint variants optimized for e-motor outputs. MFDS substance restrictions parallel REACH grease chemistry reformulation pressures. Gyeonggi Province concentration houses dedicated driveline engineering centers serving Hyundai-Kia global export programs.
Automotive Constant Velocity Joint Market Vendor Landscape
Technology licensing dominates the current landscape as specialized joint architectures transfer across electrification applications. The vendor base organizes around three tiers: integrated bearing-joint specialists, forged race manufacturers with grinding expertise, and modular assembly providers serving contract EV manufacturers. Two archetypes capture premium positioning: torque-density leaders optimizing for e-motor outputs, and scope-3 documentation early adopters securing European OEM preferential status. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers anchoring Yangtze River Delta production to capture MIIT-mandated localization requirements.
Among European-anchored specialists, SKF leverages bearing-to-joint integration expertise, while GKN Automotive exemplifies countertrack architecture development for high-torque applications. JTEKT Corp. represents Asian manufacturing scale across Japan, China, and Thailand production nodes. These three occupy positions within the tier-1 supplier tier where design-in relationships determine multi-year procurement contracts.
| Leading Market Players |
|---|
| SKF |
| Hyundai WIA Corporation |
| GKN Automotive |
| Dana Inc. |
| JTEKT Corp. |
| NTN Corporation |
| IFA Rotorion |
| Nexteer Automotive |
| American Axle & Manufacturing |
| Others |
Supply Flow & Price Mechanics
Hardened alloy steel spot prices cascade through CVJ manufacturing tiers, forging cost premiums that concentrate in precision-ground race production while contract assemblers absorb margin compression through lighter bolt-on joint variants.
Pricing Analysis
Distributor margins in the aftermarket channel absorb the steepest compression as sealed e-axle designs eliminate recurring replacement demand. Pricing stratifies across premium torque-dense designs, standard ICE service parts, and economy-grade modular joints for contract manufacturers. Cost compression in standard joint tiers intensifies because Yangtze River Delta forging overcapacity feeds price competition among undifferentiated suppliers. Aftermarket distributors exhibit highest price sensitivity as revenue pools shrink, while OEM procurement teams prioritize torque density specifications over unit cost in e-axle applications.
Supply Chain Analysis
MIIT-mandated domestic content quotas reshape sourcing patterns, compelling global suppliers to establish Yangtze River Delta forging partnerships for NEV platform access. Feedstock draws from Chinese alloy steel mills, German precision grinding equipment manufacturers, and Japanese case-hardening technology providers. Single-source vulnerability concentrates in specialized grinding machinery where European and Japanese OEMs dominate. Distribution runs through tier-1 driveline integrators consolidating bearing-joint modules before OEM assembly line delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where torque density specifications and embedded carbon documentation separate viable suppliers from margin-eroded commodity producers.
For Market Incumbents: Anchor position through countertrack architecture licensing to heavy-duty electrification segments where torque requirements exceed 500 Nm. Capture design-in value by consolidating bearing-joint modules for European EV platforms facing EU Green Deal Scope 3 disclosure mandates. Defend against precision grinding skill scarcity by underwriting vocational pipeline investments in Nagoya and Stuttgart engineering corridors.
For New Entrants and Emerging Players: Composite material expertise offers entry into premium EV architectures where carbon fiber-reinforced polymer trials target unsprung mass reduction. Target contract vehicle assemblers serving EV-native startups with pre-validated bolt-on joint subassemblies. Accelerate platform qualification through tier-1 supplier partnerships rather than direct OEM development cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where precision grinding capability scarcity intersects with Euro 7 tolerance tightening that smaller forging houses cannot amortize. Five-to-ten-year viability favors suppliers with documented Scope 3 emissions tracking securing preferential sourcing status with European OEMs. Monitor KBA type-approval timeline extensions for grease reformulation validation as inflection signal for lubricant-dependent joint architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Countertrack Architecture Licensing | High-torque joint designs transfer from passenger e-axles to commercial electrification applications. |
| Scope 3 Emissions Documentation | Early adopters capture preferential sourcing status with European OEMs facing CSRD requirements. |
| Composite Material Scale-Up | Carbon fiber-reinforced polymer trials target mass reduction in range-sensitive battery electric platforms. |
| Yangtze River Delta Localization | Domestic forging partnerships satisfy MIIT NEV content mandates for regional export programs. |
| Integrated Bearing-Joint Module Development | Consolidated subassemblies reduce OEM assembly steps while reclaiming underhood thermal management volume. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down tier-1 supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 driveline procurement managers, aftermarket distributor operators, and precision grinding equipment manufacturers informed demand-side assumptions. Secondary validation drew from vehicle registration databases, IHS Markit production forecasts, SEC filings of publicly listed suppliers, and MIIT NEV penetration statistics. Triangulation between end-use consumption patterns and supply-side capacity announcements anchored volume estimates.
Historical trendline analysis of joint count per vehicle and torque density evolution across ICE-to-EV platform transitions established baseline growth parameters. Segmentation modeling incorporated propulsion architecture, vehicle class, material grade, and regional production cluster dimensions. CAGRs were derived from slope analysis of normalized adoption curves rather than single-point extrapolation. Forecast inputs included e-axle penetration rates, Euro 7 tolerance implementation timelines, and REACH substance restriction enforcement patterns affecting grease chemistry.
The model holds under sustained NEV quota enforcement and gradual Euro 7 phase-in; deviation in raw material volatility or abrupt trade restriction implementation would shift supplier margin projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Track Bars Market