
 Automotive Ball Joints Market | 2026-2036
Automotive Ball Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ball Joints Market Analytics
OEM-grade forged steel specifications is collapsing the gap between premium and standard tier suppliers as automakers consolidate approved vendor lists. ZF Friedrichshafen AG leverages its chassis systems integration expertise to bundle ball joint modules with control arm assemblies. MOOG sustains aftermarket dominance through channel density in North American auto parts retail. Hyundai Mobis anchors its position through captive supply to the Hyundai Motor Group's global assembly footprint.
Automotive ball joints are spherical bearings that connect control arms to steering knuckles, typically machined from SAE 4140 or 4340 alloy steel with hardness ratings of 58-64 HRC to withstand cyclic loads exceeding 50 kN. They permit multi-axis rotation while maintaining precise axial location of the wheel carrier relative to the vehicle body. Lower ball joints carry higher load fractions in SLA and MacPherson strut architectures, concentrating margin pools with forged steel suppliers who certify to OEM pull-out strength protocols. The aftermarket channel exhibits faster volume velocity than authorized dealer networks as vehicle aging fleets extend replacement cycles across passenger vehicles and light trucks.
NHTSA enforces FMVSS 126 stability control mandates that propagate through Tier-1 suppliers as tightened ball joint angular deflection limits. EPA corrosion standards and ISO 11469 material marking requirements shape surface treatment specifications for salt-spray durability. ECE R79 steering equipment regulations in Europe impose additional homologation burdens on exports. Stakeholders must monitor how EV platform weight redistribution alters load-case specifications in OEM technical sourcing documents.
Market Dynamics
EV platform weight redistribution is compressing ball joint load-case tolerances as automakers recalibrate suspension geometries for battery pack mass, forcing forged steel suppliers to recertify pull-out strength protocols under tighter NHTSA FMVSS 126 angular deflection limits.
Growth Catalysts
- FMVSS 126 electronic stability mandates:NHTSA tightening of steering linkage tolerance specifications is accelerating OEM technical sourcing document revisions across North American assembly plants.
- China supply chain localization:Domestic OEMs and joint ventures are reducing import dependency through captive chassis component manufacturing within the country's automotive industrial clusters.
- Forged steel certification protocols:OEM-grade SAE 4140 and 4340 alloy specifications are collapsing vendor list fragmentation by demanding uniform hardness ratings of 58-64 HRC.
Market Restraints
- SAE 4140 alloy steel price volatility:Cyclic input cost swings compress margin pools for standard-tier suppliers lacking long-term mill contracts.
- Single-source forging concentration:Heat-treatment capacity for 50 kN+ load-rated ball joints concentrates in legacy industrial regions of the US Midwest and Germany's Ruhr Valley.
- ECE R79 homologation friction:European steering equipment regulations impose additional testing burdens on exporters seeking dual-market certification.
Strategic Opportunities
- India aftermarket channel expansion:Aging passenger vehicle fleets extend replacement cycles faster than authorized dealer network capacity, opening independent retail penetration.
- EV platform module bundling:Chassis systems integration expertise enables ball joint-to-control arm assembly packaging for battery-electric vehicle architectures.
- ISO 11469 material marking convergence:Global surface treatment specification alignment reduces salt-spray durability testing duplication across export markets.
Industry Challenges
- Heat-treatment technician scarcity:Specialized furnace operation skills for 58-64 HRC hardness certification are concentrating at retiring workforce demographics in traditional forging hubs.
- Multi-axis rotation testing capex:Cyclic load simulation equipment for 50 kN+ validation requires capital allocation that mid-tier suppliers struggle to finance.
- Legacy SLA architecture integration:Lower ball joint load fraction recalibration for EV weight distribution demands reverse-engineering compatibility with existing steering knuckle geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ball Joints Market |
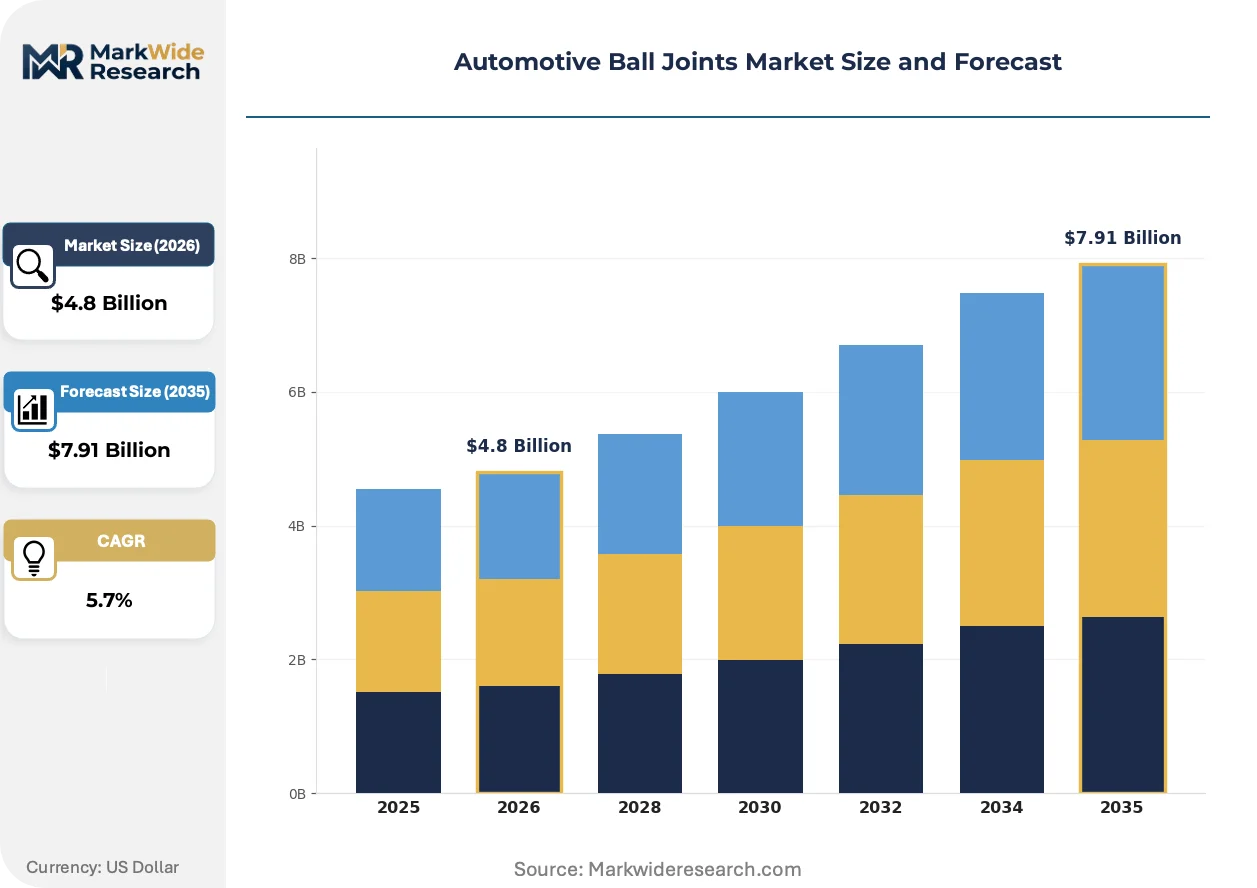
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Ball Joints, Lower Ball Joints, Pressed Ball Joints, Adjustable Ball Joints Material: Steel, Aluminum, Composite, Rubber Vehicle Type: Passenger Vehicles, Commercial Vehicles, Heavy Duty Trucks, SUVs Distribution Channel: Online Retail, Authorized Dealers, Aftermarket, Auto Parts Stores |
| Companies Covered | Hyundai Mobis, Somic Ishikawa, MOOG, Mevotech, ACDelco, ZF Friedrichshafen AG, CTR, GMB, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ball Joints Market Evolving Landscape
Material science advances and regulatory precision demands are compressing traditional manufacturing tolerances while redistributing competitive advantage toward integrated chassis module suppliers.
Carbon fiber-reinforced polymer bearing housings are miniaturizing unsprung mass in performance EV applications. Porsche and BMW M-division procurement teams have accelerated validation timelines for these assemblies. The technology is miniaturizing the boundary between forged steel legacy supply and advanced composite substitution in premium tier sourcing.
REACH Annex XVII substance restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation chemistries across European supplier parks. German KBA type-approval delays have compressed implementation windows to 18-month certification cycles. Tier-1 suppliers in Stuttgart and Wolfsburg industrial corridors are absorbing reformulation R&D costs ahead of 2025 enforcement.
Aftermarket channel disintermediation is accelerating as Amazon Business and RockAuto capture independent repair shop procurement share from traditional warehouse distributors. North American auto parts retail velocity now exceeds authorized dealer network throughput for ball joint SKUs. Independent service chains in Texas and Florida metropolitan clusters are consolidating purchase volumes through digital procurement platforms.
Automotive Ball Joints Market Segmentation
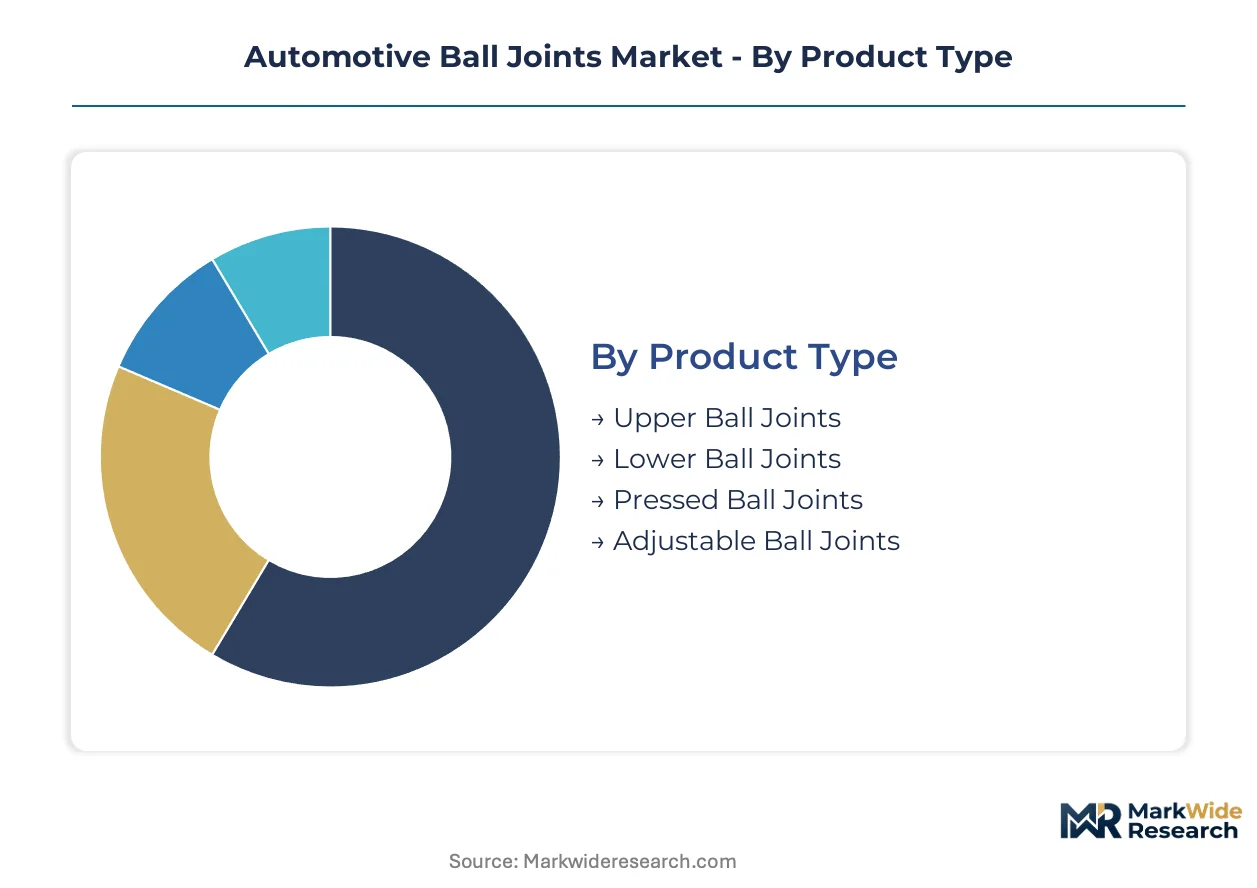
Ball joint specification tiers diverge sharply across OEM certification protocols, aftermarket durability expectations, and EV platform load-case recalibrations. Segment boundaries harden around material hardness ratings, angular deflection tolerances, and channel-specific warranty terms that reshape supplier qualification pathways.
Product Type:
NHTSA FMVSS 126 mandates propagate differently across joint positions, with lower assemblies facing tightened pull-out strength verification while upper joints navigate reduced deflection limits for electronic stability compliance.
- Lower Ball Joints:These carry the highest load fractions in SLA and MacPherson strut architectures, with SAE 4140 forged steel specifications demanding 58-64 HRC hardness ratings. Automakers in China are consolidating approved vendor lists around suppliers certifying to 50 kN+ cyclic load protocols for battery-electric vehicle platforms.
- Upper Ball Joints:Positioned above the steering knuckle centerline, these manage camber adjustment loads with reduced vertical stress. North American OEMs are recalibrating angular deflection limits for EV weight redistribution, compressing tolerance bands for Tier-1 chassis integrators.
- Pressed Ball Joints:Cold-formed construction suits high-volume economy vehicle programs where unit cost compression dominates sourcing decisions.
- Adjustable Ball Joints:Threaded housing designs serve performance aftermarket applications requiring camber correction for modified suspension geometries.
Lower ball joints handle the majority of throughput; adjustable variants are expanding most quickly on share as performance EV tuning gains traction.
Material:
Cost stratification in raw material procurement separates forged alloy suppliers with mill-direct contracts from converters dependent on spot market exposure.
- Steel:SAE 4140 and 4340 alloy grades dominate OEM-grade specifications with 58-64 HRC heat-treatment certification. Heat-treatment capacity concentrates in legacy US Midwest and Germany's Ruhr Valley forging corridors, creating single-source bottlenecks for 50 kN+ load-rated components.
- Aluminum:Die-cast housing designs reduce unsprung mass in premium EV applications where battery weight distribution demands suspension light-weighting.
- Composite:Carbon fiber-reinforced polymer bearing housings are miniaturizing mass in Porsche and BMW M-division performance procurement, compressing validation timelines for advanced material substitution.
- Rubber:Elastomer boot formulations protect ball stud articulation points against EPA corrosion standards for salt-spray durability.
Steel commands the volume base; composite formulations are climbing the fastest as EV performance tier sourcing accelerates.
Vehicle Type:
Platform architecture diversity fragments demand across load-case specifications, with EV chassis redesigns altering joint positioning and force distribution patterns.
- Passenger Vehicles:MacPherson strut dominance in compact and mid-size segments concentrates lower ball joint procurement around high-volume forging capacity. China's domestic OEMs and joint ventures are localizing chassis supply chains to reduce import dependency for these volume platforms.
- SUVs:Higher center-of-gravity architectures impose multi-axis rotation demands on joint assemblies, with SLA suspension designs concentrating load fractions in lower joint positions.
- Commercial Vehicles:Fleet duty cycles extend replacement intervals, channeling demand toward aftermarket durability specifications rather than OEM-grade tolerance bands.
- Heavy Duty Trucks:Severe-service load ratings require specialized heat-treatment protocols that concentrate supply among legacy forging specialists with technician scarcity pressures.
Passenger vehicles absorb the dominant share; SUVs are gaining share fastest as EV platform diversification expands segment boundaries.
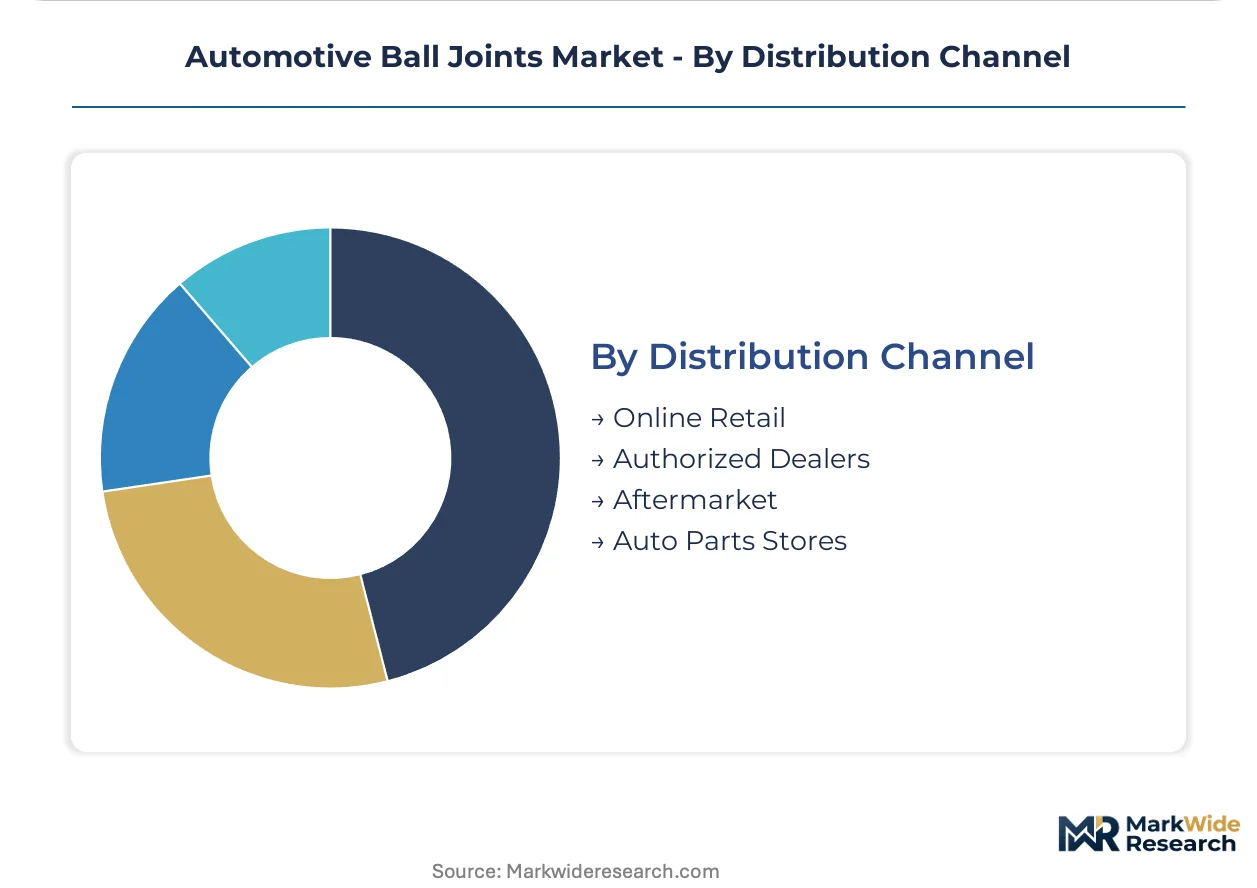
Distribution Channel:
Channel velocity patterns diverge as digital procurement platforms capture independent repair shop volumes from traditional warehouse distributor networks.
- Aftermarket:Aging vehicle fleets across North America and India extend replacement cycles faster than authorized dealer network capacity, opening penetration for independent retail and digital platforms. Amazon Business and RockAuto are consolidating purchase volumes from service chains in Texas and Florida metropolitan clusters.
- Auto Parts Stores:Channel density in North American retail sustains inventory velocity for standard-tier ball joint SKUs with immediate availability requirements.
- Authorized Dealers:OEM warranty coverage and certified technician installation preserve positioning for complex steering linkage assemblies under FMVSS 126 compliance protocols.
- Online Retail:Direct-to-consumer penetration remains constrained by fitment verification complexity and return logistics for precision chassis components.
Aftermarket channels manage the bulk of transaction volume; online retail is expanding most steeply as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India demonstrate the highest price elasticity, squeezing margin pools for standard-tier forged steel suppliers, while German and Japanese OEMs absorb premium pricing for certified 58-64 HRC hardness ratings without volume attrition.
China
Domestic OEMs and joint ventures are localizing chassis component supply chains to reduce import dependency for battery-electric vehicle platforms. MIIT dual carbon goals and GB standards for automotive components are tightening material traceability requirements. Yangtze River Delta industrial clusters in Shanghai and Jiangsu province are concentrating heat-treatment capacity for 50 kN+ load-rated ball joints.
Germany
Porsche and BMW M-division procurement teams are accelerating validation timelines for carbon fiber-reinforced polymer bearing housings in performance EV applications. KBA type-approval protocols under ECE R79 steering equipment regulations are compressing certification windows to 18-month cycles. Stuttgart and Wolfsburg industrial corridors are absorbing REACH Annex XVII reformulation R&D costs ahead of enforcement.
United States
NHTSA FMVSS 126 electronic stability mandates are propagating through Tier-1 suppliers as tightened angular deflection limits for steering linkage components. EPA corrosion standards shape surface treatment specifications for salt-spray durability in Midwest winter markets. Michigan and Ohio legacy forging hubs are experiencing heat-treatment technician scarcity as workforce demographics shift toward retirement.
India
Aging passenger vehicle fleets are extending replacement cycles faster than authorized dealer network capacity, opening independent retail penetration for aftermarket ball joint SKUs. BIS automotive component standards are converging with ISO 11469 material marking requirements for export qualification. Maharashtra and Gujarat industrial zones are attracting chassis component manufacturing investments from domestic OEM supply chain localization programs.
Japan
METI industrial policy is supporting advanced material substitution in suspension components for next-generation EV architectures. JIS standards for automotive steering equipment maintain stringent homologation burdens on component suppliers. Kansai and Nagoya manufacturing belts are consolidating forged steel supplier networks around certified pull-out strength protocols.
Automotive Ball Joints Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with forged steel certification expertise separating premium-tier chassis integrators from standard-volume commodity suppliers. The vendor base concentrates around three strategic archetypes: captive OEM suppliers with in-house production, independent Tier-1 chassis system integrators, and aftermarket-focused channel specialists. Dominant competitive moves include strategic partnerships for EV platform module bundling and geographic expansion into China and India supply chain localization zones.
Among captive OEM suppliers, Hyundai Mobis anchors its position through integrated chassis component supply. On the independent Tier-1 vector, ZF Friedrichshafen AG exemplifies chassis systems integration expertise. Within the aftermarket channel, MOOG occupies a position representing North American auto parts retail density. These three companies represent distinct competitive archetypes rather than direct substitutes across procurement segments.
| Leading Market Players |
|---|
| Hyundai Mobis |
| Somic Ishikawa |
| MOOG |
| Mevotech |
| ACDelco |
| ZF Friedrichshafen AG |
| CTR |
| GMB |
| Delphi Technologies |
| Others |
Value Network & Pricing Analysis
NHTSA FMVSS 126 certification gates both supplier qualification and price differentiation simultaneously, as automakers restrict approved vendor lists to forged steel producers meeting 58-64 HRC hardness protocols. This regulatory threshold collapses mid-tier competitors into commodity pricing while rewarding certified suppliers with OEM-grade contract premiums.
Pricing Analysis
Aftermarket parts revenue drives lifetime value through replacement-cycle capture as vehicle aging fleets extend service intervals. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and channel density. Cost compression in standard-tier forged steel is intensifying because SAE 4140 alloy spot market exposure lacks mill-direct contract protection. Domestic OEMs in China demonstrate highest price elasticity, while German and Japanese automakers absorb premium pricing for certified pull-out strength ratings without volume attrition.
Supply Chain Analysis
Just-in-time inventory preferences dominate OEM procurement, while aftermarket channels maintain strategic stockpiles for immediate availability requirements. Heat-treatment capacity concentrates in the United States, Germany, and China, with legacy forging corridors in Michigan, the Ruhr Valley, and the Yangtze River Delta anchoring 50 kN+ load-rated production. Raw material procurement draws from SAE 4140 alloy steel mills, carbon fiber-reinforced polymer feedstock, and trivalent chromium surface treatment chemistries. Single-source vulnerability in legacy forging hubs creates supply chain risk as retiring workforce demographics concentrate specialized furnace operation skills. Distribution runs through Tier-1 chassis integrators, authorized dealer networks, and digital procurement platforms capturing independent repair shop volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs. NHTSA FMVSS 126 certification requirements lock automakers into approved vendor relationships that resist price-based displacement.
For Market Incumbents: Secure heat-treatment technician pipelines through apprenticeship programs in Michigan and Ruhr Valley forging hubs to counter retiring workforce demographics. Deepen backward integration into SAE 4140 alloy steel mill contracts to buffer spot market volatility. Carbon fiber-reinforced polymer substitution in Porsche and BMW M-division procurement represents the priority threat requiring advanced material R&D allocation.
For New Entrants and Emerging Players: Differentiate on EV platform module bundling expertise, packaging ball joint assemblies with control arm modules for battery-electric vehicle architectures. Target India aftermarket channel expansion where aging passenger vehicle fleets outpace authorized dealer network capacity. Pursue digital procurement platform partnerships with Amazon Business and RockAuto to capture independent service chain volumes in Texas and Florida metropolitan clusters.
For Investors and Strategic Acquirers: REACH Annex XVII enforcement reshapes the acquisition landscape by forcing trivalent passivation chemistry conversion costs onto European supplier parks. Five-to-ten-year viability favors forged steel certification specialists with captive OEM relationships over spot-market-dependent converters. Watch KBA type-approval delays as the inflection signal indicating which suppliers have absorbed reformulation R&D ahead of enforcement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of approved vendor lists around 58-64 HRC certified suppliers reduces procurement fragmentation. |
| Battery Supply Agreement | EV chassis redesigns for battery weight distribution recalibrate ball joint load-case specifications in technical sourcing documents. |
| Software-Defined Vehicle Investment | Electronic stability control integration tightens angular deflection limits for steering linkage components under FMVSS 126. |
| Geographic Manufacturing Footprint | China supply chain localization reduces import dependency for domestic OEMs and joint ventures in Yangtze River Delta clusters. |
| Charging Infrastructure Partnership | Aftermarket channel digitization through Amazon Business and RockAuto captures independent repair shop procurement volumes. |
Research Methodology
A standing panel of Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and heat-treatment facility operators provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS compliance filings, and SEC 10-K disclosures from chassis component suppliers. Bottom-up unit demand modeling and top-down market sizing triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated output ranges across the projection horizon. The analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves applied to base-year market sizing. Industry-specific forecast inputs incorporated EV platform weight redistribution effects on load-case specifications and aftermarket replacement cycle velocity by vehicle age cohort.
The analysis sits within stated boundaries; outcomes outside sustained EV adoption rates, stable alloy steel pricing, or unchanged NHTSA enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding certification protocol stability and heat-treatment capacity expansion. Revision becomes warranted when REACH Annex XVII enforcement timelines or KBA type-approval delays cross thresholds that alter supplier R&D burden distribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Engine Fixture Market