
 Global Automotive Transfer Case Market | 2026-2036
Global Automotive Transfer Case Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Transfer Case Market Analysis
ISO 26262 functional safety certification is collapsing the supplier base for electronically controlled transfer cases. ZF Friedrichshafen AG leverages its integrated mechatronics portfolio to sustain design wins across European and North American OEM platforms. BorgWarner Inc. anchors its position through captive torque-vectoring technology and in-house clutch manufacturing. Magna International Inc. competes on manufacturing scale with dual-clutch transfer case output spanning multiple vehicle assembly sites.
An automotive transfer case is a drivetrain component that distributes engine torque between the front and rear axles through a gear train, chain drive, or clutch pack, typically operating at input speeds of 3,000–7,000 rpm and requiring case hardening of hypoid gear sets for durability in high-torque applications. Its primary purpose is to enable selectable or full-time all-wheel-drive and four-wheel-drive functionality in vehicles with longitudinally mounted engines. Automatic transfer cases now dominate OEM fitment due to seamless torque biasing and integration with vehicle stability control systems, while electric transfer cases represent the fastest-growing product type as battery-electric platforms demand compact, multi-motor torque distribution without mechanical prop shafts. Aluminum material grades capture the largest volume share by weight reduction mandate, though magnesium castings are gaining ground in premium SUV architectures where every kilogram of unsprung mass carries fuel economy penalty.
EPA fuel economy regulations and NHTSA safety standards in the United States, alongside EU Green Deal fleet emissions targets and REACH material compliance in Europe, are reshaping transfer case design requirements toward lighter housings and lower-friction lubrication. China's MIIT new energy vehicle mandates and GB standards for electric drivetrain components are accelerating domestic supplier qualification for e-AWD systems. Stakeholders must monitor how powertrain electrification timelines in key production markets redefine the boundary between mechanical torque split and software-controlled motor dispatch.
Market Dynamics
Powertrain electrification is dissolving the mechanical boundary between transfer cases and motor control units, forcing suppliers to requalify for software-defined torque distribution contracts as OEMs consolidate drivetrain electronics.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Light-weighting mandates in the United States are accelerating aluminum and magnesium housing adoption across domestic truck platforms.
- China MIIT new energy vehicle procurement quotas:State-owned OEMs must source locally qualified e-AWD systems, creating captive demand for domestic transfer case suppliers.
- Hypoid gear case hardening advances:Improved surface treatment processes are extending service intervals for high-torque off-highway applications.
Market Restraints
- Magnesium price volatility:Primary magnesium smelting concentration in Shanxi Province creates input cost exposure for premium SUV architectures.
- ISO 26262 functional safety certification:The ASIL-D compliance burden is collapsing the supplier base for electronically controlled transfer cases to Tier 1 incumbents with captive validation labs.
- Integrated e-axle substitution:Battery-electric platforms with dual-motor layouts are eliminating mechanical torque split hardware entirely.
Strategic Opportunities
- India sub-4-meter SUV segment:Compact all-wheel-drive platforms for domestic automakers remain underpenetrated by multi-mode transfer case suppliers.
- EU Green Deal fleet emissions targets:CO2 penalties are creating regulatory tailwinds for active torque-vectoring systems that improve fuel economy through predictive load distribution.
- Over-the-air calibration channels:Cloud-based clutch engagement mapping allows aftermarket revenue capture from terrain-specific drive mode subscriptions.
Industry Challenges
- Mechatronics systems integration talent:The scarcity of engineers fluent in both hypoid gear design and embedded motor control firmware is extending development timelines.
- Legacy 4WD platform coexistence:Suppliers must maintain parallel production lines for mechanical transfer cases while scaling e-AWD validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Transfer Case Market |
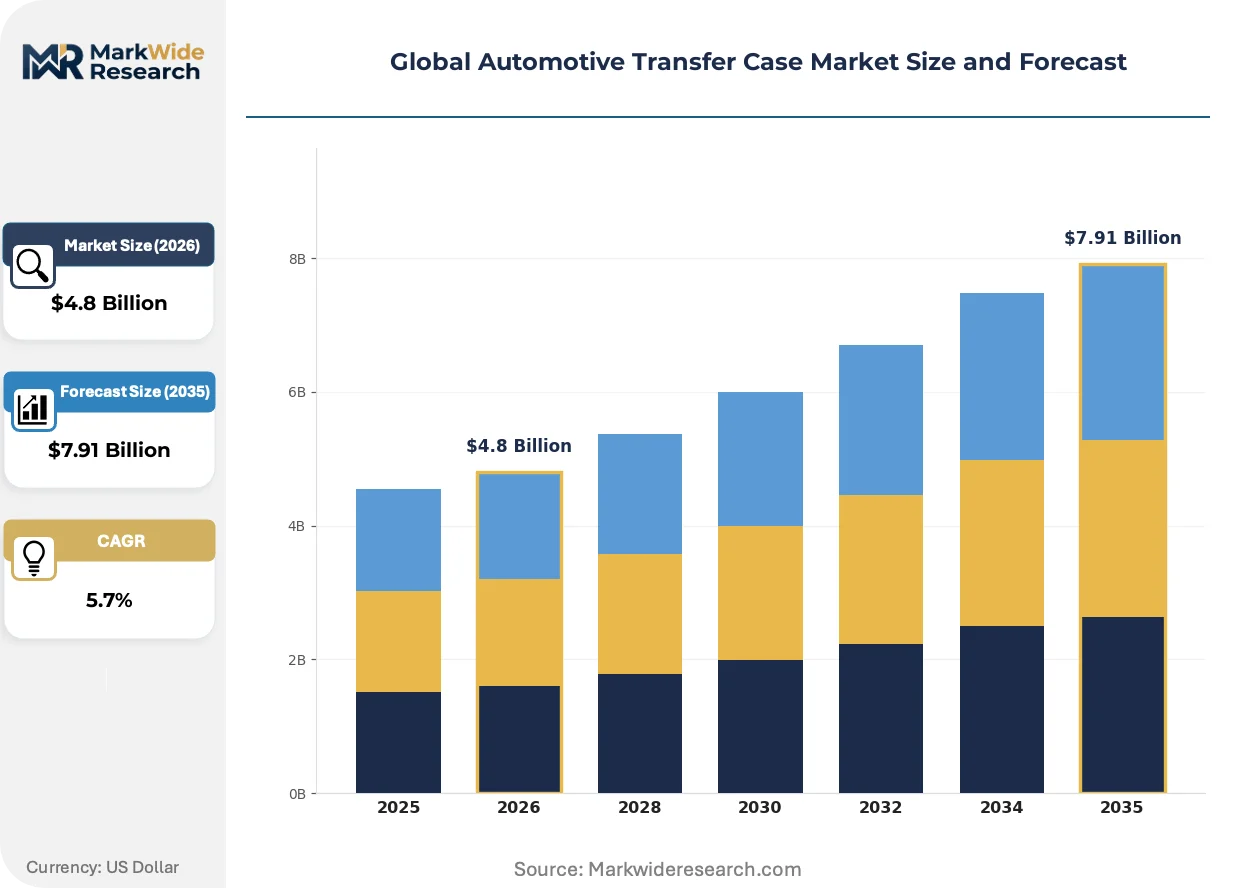
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Electric, Dual-clutch Vehicle Type: SUV, Truck, Passenger Car, All-terrain Material: Aluminum, Steel, Composite, Magnesium End User: OEMs, Aftermarket Installers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Aisin Seiki Co. Ltd., Hyundai Motor Company, ZF Friedrichshafen AG, Linamar Corporation, JTEKT Corporation, BorgWarner Inc., Dana Limited, American Axle and Manufacturing Inc., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Transfer Case Market Emerging Trajectories
Software-defined drivetrains are collapsing hardware differentiation into firmware layers, while material science and regulatory pressure compress traditional mechanical architectures into electrified torque management systems.
Electric transfer cases with integrated clutch-actuated torque biasing are displacing chain-driven mechanical units in battery-electric platforms. OEMs with longitudinal motor layouts in Germany and the United States are adopting these compact modules to eliminate prop shafts. The technology is displacing incumbent suppliers without in-house motor control firmware development.
REACH material compliance and EU F-Gas Regulation are banning specific lubricant formulations and refrigerants used in thermal management of transfer case control modules. European suppliers must reformulate friction materials and resubmit homologation dossiers. Premium SUV platforms with magnesium housings face the steepest retesting burden.
Fleet procurement departments are consolidating drivetrain component sourcing under platform-level contracts rather than discrete subsystem awards. Tier 1 suppliers with integrated mechatronics portfolios are capturing full axle system business. This pattern is most visible in North American full-size truck manufacturing where OEMs have reduced qualified transfer case vendors by half.
Global Automotive Transfer Case Market Segmentation
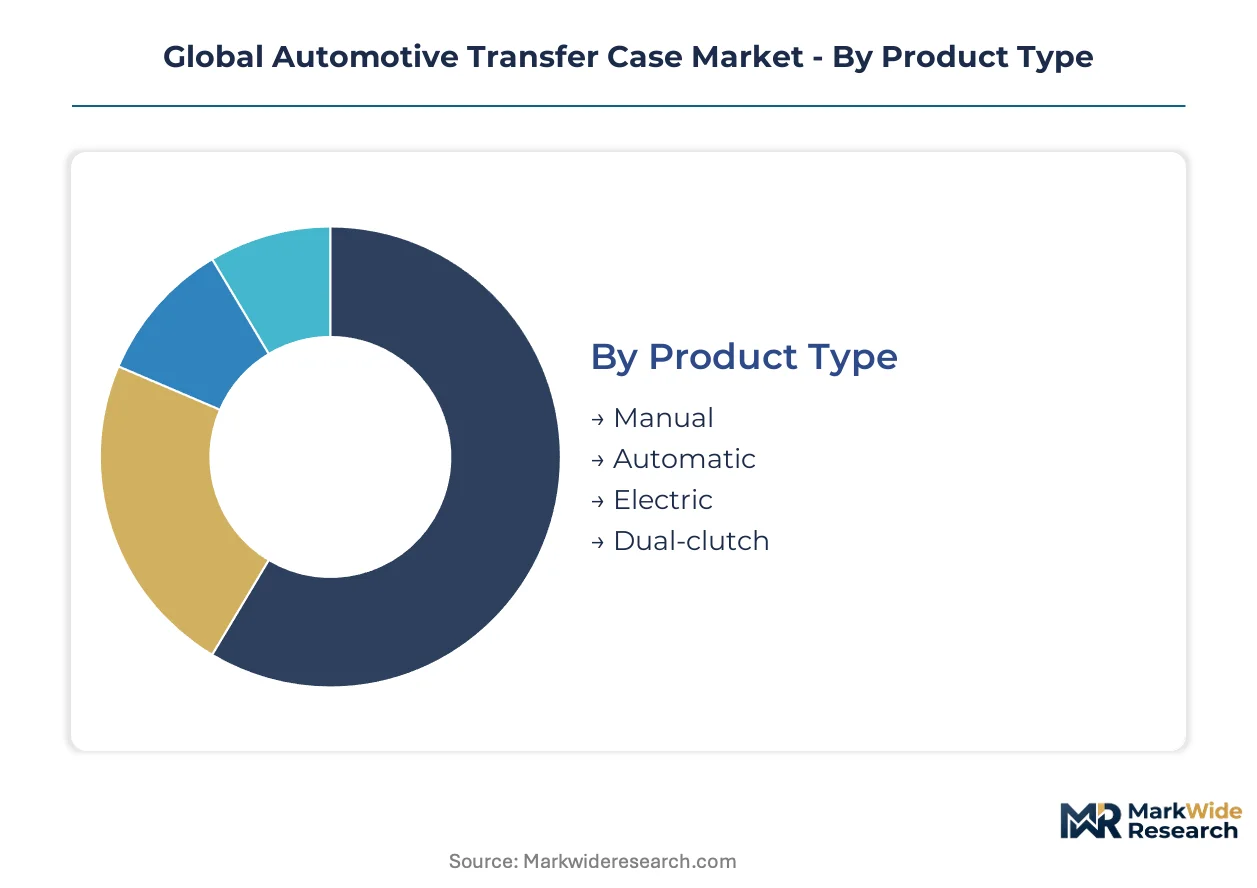
Transfer case procurement patterns diverge sharply across product architectures and vehicle platforms, with regulatory compliance costs and electrification timelines reshaping supplier qualification criteria. OEM sourcing strategies now weight software integration capability as heavily as mechanical durability, fragmenting traditional segment boundaries.
Product Type:
EPA fuel economy standards and EU CO2 fleet targets are forcing rapid product portfolio rebalancing, with electronic control modules now mandatory for any platform seeking all-wheel-drive homologation in regulated markets.
- Automatic:Seamless torque biasing systems integrate with vehicle stability control architectures through clutch-actuated gear trains. United States full-size truck manufacturers specify these units for their volume platforms, driven by NHTSA rollover safety mandates requiring predictive load distribution.
- Electric:Compact multi-motor torque distribution modules eliminate mechanical prop shafts in battery-electric platforms with longitudinal motor layouts. German OEMs lead procurement for these units as EU Green Deal penalties intensify pressure to reduce drivetrain mass.
- Manual:Selectable gear-driven units retain niche demand in off-highway and emerging-market commercial applications where electronic service infrastructure remains limited.
- Dual-clutch:Torque-vectoring variants command premium positioning in performance SUV architectures, with active yaw control enabled through independent clutch pack modulation.
Automatic handles the majority of throughput; Electric is the fastest mover on share.
Vehicle Type:
Production volume concentration in specific vehicle categories determines supplier manufacturing scale and capital allocation priorities, with platform-level contracts favoring integrated axle system vendors.
- SUV:Unibody and body-on-frame architectures drive the largest absolute demand for multi-mode transfer cases, with China MIIT procurement quotas accelerating domestic supplier qualification for state-owned OEM platforms. Three-row family SUVs in the United States specify active torque-vectoring variants to meet EPA light-truck fuel economy loophole utilization.
- Truck:Full-size pickup platforms in North America sustain demand for chain-driven mechanical units with high-torque capacity, though electrification timelines are compressing product lifecycle planning horizons.
- Passenger Car:Longitudinal-engine luxury sedans in Germany retain limited fitment of full-time all-wheel-drive systems, with ZF and BorgWarner capturing remaining platform awards.
- All-terrain:Off-highway vehicles and military applications require hardened hypoid gear sets with extended service intervals, supplied by specialists with captive heat treatment capabilities.
SUV dominates current volume; All-terrain maintains the steepest expansion trajectory in per-unit value terms.
Material:
Lightweighting mandates and REACH compliance burdens are restructuring raw material sourcing, with magnesium price volatility in Shanxi Province creating input cost exposure for premium architectures.
- Aluminum:High-pressure die-cast housing grades capture volume share across mid-range truck and SUV platforms, with silicon-modified alloys meeting case hardening compatibility requirements for hypoid gear bores.
- Magnesium:Thixomolded housings penetrate premium SUV segments where every kilogram of unsprung mass carries measurable fuel economy penalty, though EU F-Gas Regulation retesting requirements extend homologation timelines.
- Steel:Ductile iron retains cost-sensitive commercial vehicle applications and legacy platform continuity production in emerging markets.
- Composite:Thermoplastic housing prototypes validate for future electric transfer case architectures, with polymer suppliers targeting elimination of secondary machining operations.
Aluminum carries the bulk of unit volume; Magnesium is climbing the fastest on value per kilogram.
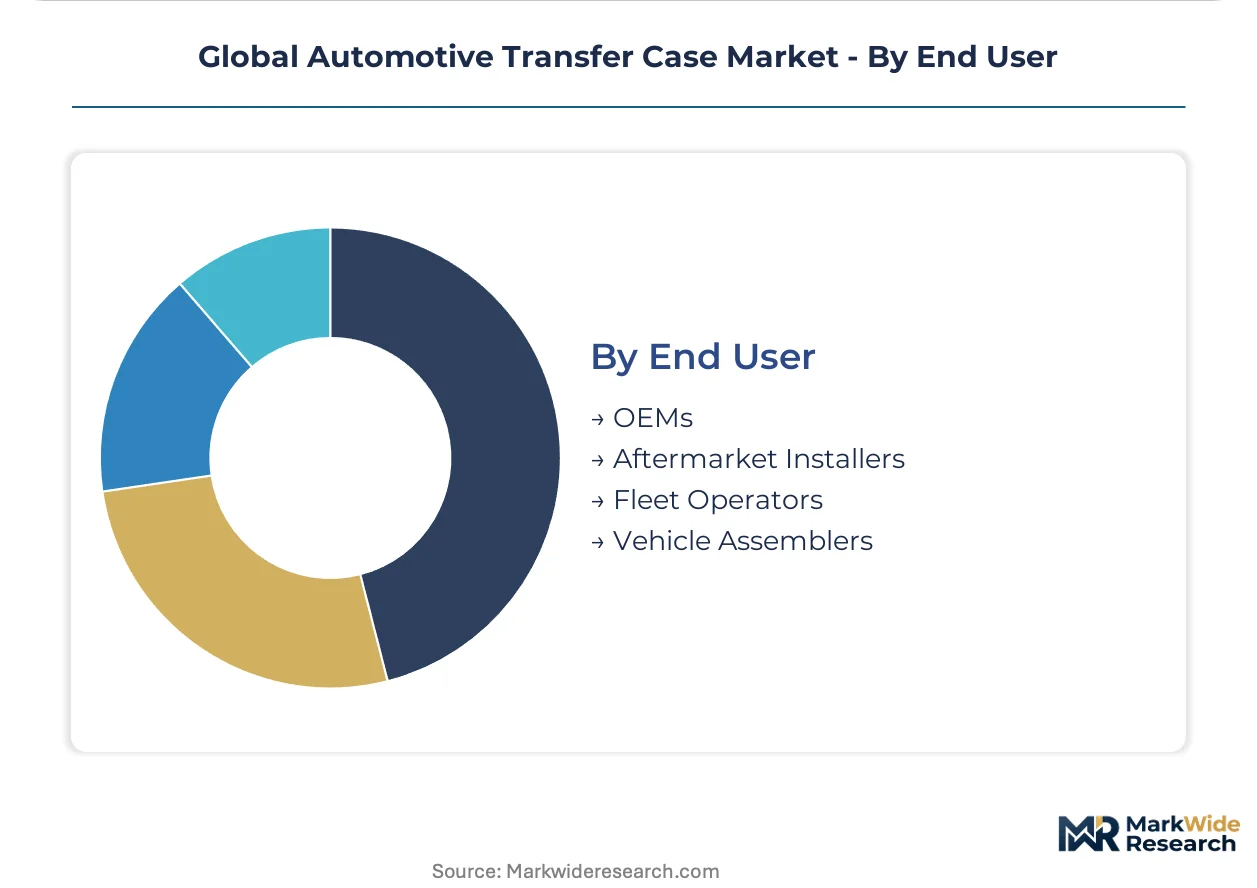
End User:
Fleet procurement consolidation and over-the-air calibration capabilities are redistributing value capture between original equipment and aftermarket channels, with subscription revenue models emerging in terrain-specific drive mode offerings.
- OEMs:Platform-level drivetrain contracts now bundle transfer cases with axle assemblies and motor control units, collapsing discrete subsystem awards. Tier 1 suppliers with integrated mechatronics portfolios capture full system business in North American truck manufacturing.
- Fleet Operators:Commercial vehicle procurement departments specify predictive maintenance telemetry and extended drain intervals, prioritizing total cost of ownership over acquisition price.
- Aftermarket Installers:Specialty upfitters serve off-highway and recreational vehicle segments with mechanical conversion kits, though ISO 26262 certification requirements limit electronic control module availability.
- Vehicle Assemblers:Contract manufacturers in emerging markets source knock-down kits for local assembly, with MIIT domestic content rules shaping supplier geography.
OEMs command the dominant procurement volume; Fleet Operators are gaining share fastest in data-enabled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT procurement quotas and EPA fuel economy mandates are redrawing supplier geography across major automotive production clusters. Domestic content rules in China, lightweighting deadlines in Germany, and truck platform consolidation in the United States are concentrating transfer case manufacturing in specific regulatory corridors.
United States
Full-size pickup production at Detroit Three assembly plants sustains demand for high-torque chain-driven units. NHTSA rollover safety mandates require predictive load distribution systems that integrate with electronic stability control. Michigan and Ohio house the densest supplier engineering corridors for axle system integration.
China
State-owned OEM procurement quotas under MIIT new energy vehicle mandates are accelerating domestic e-AWD supplier qualification. GB standards for electric drivetrain components force reformulation of friction materials and control module architectures. Shanghai and Yangtze River Delta clusters concentrate thixomolding capacity for magnesium housing production.
Germany
EU Green Deal fleet emissions penalties drive active torque-vectoring adoption in premium SUV platforms. REACH compliance and F-Gas Regulation ban specific lubricant formulations, extending homologation timelines for friction material resubmission. Bavaria and Baden-Württemberg anchor ZF and BorgWarner engineering centers for mechatronics integration.
India
Sub-4-meter SUV segments for domestic automakers remain underpenetrated by multi-mode transfer case suppliers. PLI scheme incentives for advanced automotive components attract foreign joint ventures for local clutch manufacturing. Tamil Nadu and Maharashtra assembly corridors concentrate contract manufacturing for knock-down kit sourcing.
Japan
Longitudinal-engine luxury platforms and kei-class all-terrain vehicles sustain dual demand for full-time AWD and compact mechanical units. METI carbon neutrality roadmaps compress electrification timelines for drivetrain component suppliers. Aichi Prefecture clusters integrate JTEKT and Aisin Seiki production with Toyota platform engineering.
Global Automotive Transfer Case Market Vendor Landscape
Player mix skews toward integrated mechatronics conglomerates with captive validation labs and software-defined torque distribution capability. Tier 1 incumbents with ISO 26262 ASIL-D certification capture platform-level contracts that bundle transfer cases with axle assemblies and motor control units. Two strategic archetypes dominate: diversified automotive suppliers with full drivetrain portfolios, and drivetrain specialists with captive gear manufacturing and heat treatment. Competitive moves center on M&A for firmware talent acquisition and capacity expansion for electric transfer case architectures.
Among diversified conglomerates, ZF Friedrichshafen AG and Magna International Inc. occupy positions that exemplify integrated axle system bundling, while BorgWarner Inc. anchors the specialist tier with in-house clutch manufacturing and torque-vectoring technology. These three represent the supplier consolidation pattern visible across North American truck and European SUV platform awards.
| Leading Market Players |
|---|
| Aisin Seiki Co. Ltd. |
| Hyundai Motor Company |
| ZF Friedrichshafen AG |
| Linamar Corporation |
| JTEKT Corporation |
| BorgWarner Inc. |
| Dana Limited |
| American Axle and Manufacturing Inc. |
| Magna International Inc. |
| Others |
Supply Flow & Price Mechanics
Magnesium substitution for aluminum in premium SUV housings simultaneously redraws raw material sourcing toward Shanxi Province smelters and compresses margin structures for European suppliers facing REACH retesting costs. This input shift concentrates pricing power with integrated foundries while fragmenting Tier 2 component vendors unable to absorb volatility.
Pricing Analysis
ISO 26262 ASIL-D certification level creates the primary spread between Tier 1 incumbents and qualified challengers. Three-tier pricing structure across premium torque-vectoring, standard automatic, and economy mechanical units reflects software integration depth and validation burden. Cost compression in magnesium-dependent architectures is intensifying because EU F-Gas Regulation extends homologation timelines. Fleet operators exhibit lowest price sensitivity due to total cost of ownership contracting, while aftermarket installers face acute margin pressure from control module scarcity.
Supply Chain Analysis
Inbound logistics costs through Yangtze River Delta ports and Rotterdam container terminals determine landed cost competitiveness for magnesium thixomolding feedstock. Manufacturing concentrates in Germany, China, and the United States, with hypoid gear steel drawing from Japanese and Austrian specialty mills. Single-source vulnerability in Shanxi Province primary magnesium creates input cost exposure. Distribution runs through platform-level axle system contracts rather than discrete component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification is compressing mechanical transfer case lifecycles while expanding software-defined torque distribution contracts, creating a high-growth disruption window for suppliers with embedded motor control firmware capability.
For Market Incumbents: Consolidate through captive validation lab investment to defend ISO 26262 certification moats against emerging e-AWD specialists. Acquire firmware talent pools in Bavaria and Michigan engineering corridors. Backward integration into magnesium thixomolding mitigates Shanxi supply concentration risk.
For New Entrants and Emerging Players: Cloud-based terrain calibration subscriptions represent a service-layer gap where incumbents under-serve fleet operators. Target India's sub-4-meter SUV segment through joint ventures with Tamil Nadu contract manufacturers. Lead with over-the-air update capability rather than hardware differentiation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive suppliers lacking electric transfer case validation capacity. Five-to-ten year viability hinges on software-defined drivetrain positioning rather than mechanical scale. Monitor MIIT domestic content enforcement as inflection signal for Chinese supplier revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of axle system contracts favors integrated mechatronics suppliers with multi-vehicle coverage. |
| Battery Supply Agreement | Long-term cathode material offtake secures cost position for electric transfer case motor control modules. |
| Software-Defined Vehicle Investment | Firmware talent acquisition in Baden-Württemberg engineering clusters enables torque-vectoring algorithm development. |
| Geographic Manufacturing Footprint | Yangtze River Delta magnesium foundry proximity reduces EU F-Gas Regulation compliance logistics burden. |
| Charging Infrastructure Partnership | Utility collaboration on bidirectional charging protocols extends transfer case thermal management system applications. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution managers, and foundry operations heads provided ongoing calibration against secondary validation from vehicle production databases, IHS Markit registration data, SEC supplier filings, and MIIT new energy vehicle procurement records. Bottom-up unit volume estimates triangulated with top-down OEM platform allocation models across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation dimensions. CAGRs derived from regression analysis of historical fitment rates projected against electrification timeline scenarios. Industry-specific inputs included EPA fuel economy compliance cost curves and EU Green Deal penalty forecasts.
Forecasts assume regulatory continuity in EPA, NHTSA, and MIIT regimes; material policy shifts would require re-modeling. Technology substitution risk from integrated e-axle architectures and magnesium price volatility represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Cell Vent Spacer Market