
 Automotive Throttle Body Assembly Market | 2026-2036
Automotive Throttle Body Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Throttle Body Assembly Market Outlook
Electronic throttle control integration with engine management systems is tilting supplier capabilities toward mechatronics and software calibration. Bosch GmbH leverages its powertrain electronics portfolio to anchor high-volume contracts with European OEMs. Denso Corporation sustains manufacturing scale across Asian production networks. Continental AG competes on integrated throttle-valve architectures that merge airflow sensing with actuator control.
An automotive throttle body assembly regulates air intake volume into an internal combustion engine through a butterfly valve actuated by electronic or mechanical linkage, typically machined from aluminum die-cast housings with throttle position sensors providing closed-loop feedback to the engine control unit. Electronic throttle control dominates OEM fitment due to precision mapping requirements for emissions compliance and fuel optimization, while manual throttle configurations persist in cost-sensitive motorcycle and aftermarket replacement applications. Passenger cars generate the largest volume demand, though commercial vehicle segments command higher per-unit pricing through heavy-duty durability specifications.
EPA tailpipe standards and the EU Green Deal's transport decarbonization framework compel throttle body suppliers to tighten airflow measurement accuracy and reduce hysteresis in electronic actuators. Japan's METI enforces fuel efficiency benchmarks that cascade into throttle calibration tolerances for domestic and export vehicle programs. Stakeholders must monitor how powertrain electrification thresholds alter the addressable market for traditional throttle body architectures.
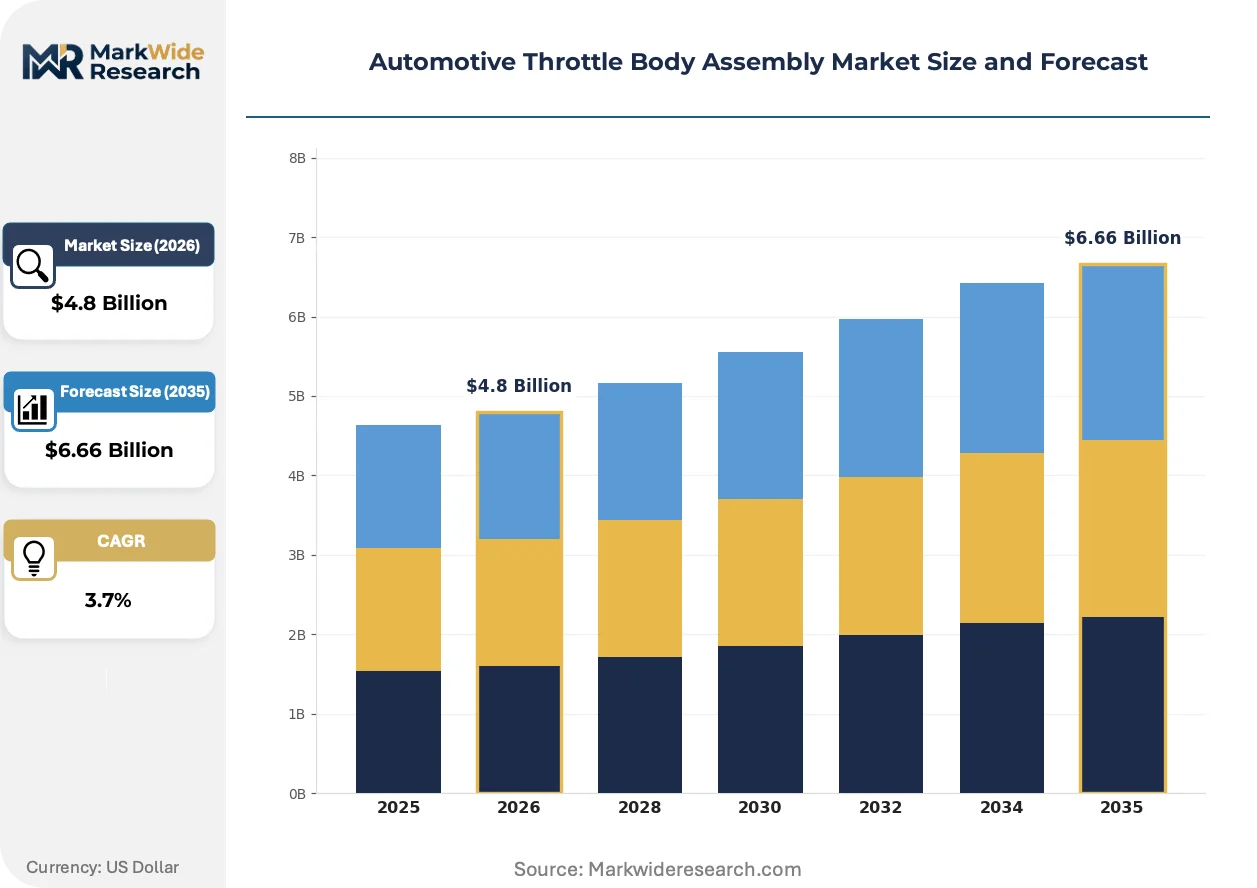
Market Dynamics
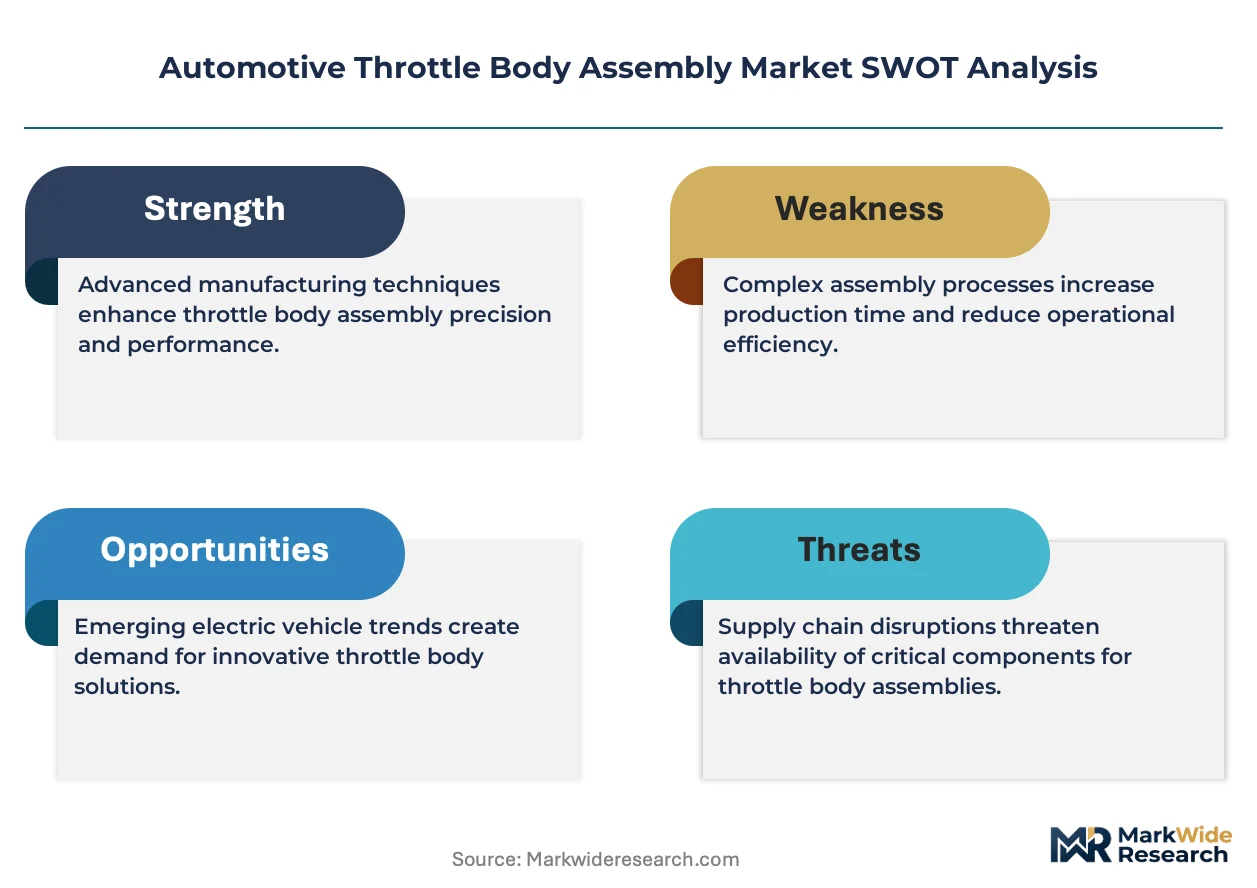
The Automotive Throttle Body Assembly Market faces structural compression as powertrain electrification thresholds redraw the addressable demand for traditional airflow regulation hardware. Electronic throttle control systems now dominate OEM procurement, yet hybrid architectures and battery-electric platforms are progressively eliminating mechanical air intake components from vehicle programs.
Growth Catalysts
- Euro 7 emissions standards:German passenger car OEMs are expanding electronic throttle procurement to meet tightened calibration requirements for NOx and particulate limits.
- China's automotive manufacturing corridor:Domestic vehicle producers are accelerating localization of throttle body supply chains, concentrating demand in the Yangtze River Delta and Pearl River Delta clusters.
- Dual carbon goals:MIIT fuel efficiency mandates cascade into precision airflow control requirements for internal combustion engines in hybrid transition vehicles.
Market Restraints
- Aluminum die-cast input volatility:Housing material costs fluctuate with energy-intensive smelting operations, compressing margin stability for machined component suppliers.
- Powertrain electrification substitution:Battery-electric platforms eliminate throttle bodies entirely, structurally capping long-term demand growth in passenger vehicle segments.
- REACH substance restrictions:Sensor coating materials face compliance friction from ECHA substance-of-very-high-concern listings, extending qualification timelines.
Strategic Opportunities
- Commercial vehicle durability specifications:Heavy-duty trucking segments command premium per-unit pricing for throttle bodies with extended service intervals and harsh-environment sealing.
- ISO 26262 functional safety convergence:Throttle position sensor integration with ASIL-rated engine management systems creates white space for mechatronics suppliers with software calibration capabilities.
- Motorcycle aftermarket persistence:Manual throttle configurations retain demand in cost-sensitive two-wheeler replacement markets across Southeast Asian production networks.
Industry Challenges
- Mechatronics talent scarcity:Software calibration engineers with powertrain control expertise command premium compensation, constraining supplier scaling velocity.
- Legacy ECU integration complexity:Backward compatibility requirements for 12-volt electrical architectures delay electronic throttle adoption in certain vehicle refresh programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Throttle Body Assembly Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Throttle Control, Manual Throttle, Dual Throttle, Integrated Throttle Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Aftermarket Suppliers, Distributors, Vehicle Manufacturers Technology: Hybrid Technology, Adaptive Technology, Conventional Technology, Others |
| Companies Covered | Delphi Technologies, Hitachi Automotive Systems, Bosch GmbH, Valeo SA, Keihin Corporation, Denso Corporation, Magneti Marelli, Aisin Seiki Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Throttle Body Assembly Market Strategic Shifts
Throttle body architecture is converging with powertrain electronics as mechatronics integration redefines supplier capability requirements. Three developments are compressing traditional component boundaries and reshaping competitive positioning.
Integrated throttle-valve architectures that merge airflow sensing with actuator control are rendering obsolete standalone throttle position sensors in next-generation engine management systems. European OEMs are specifying these consolidated units for 48-volt mild-hybrid platforms, compressing the supplier base toward electronics-integrated tier ones.
Japan's METI fuel efficiency benchmarks cascade into throttle calibration tolerances that demand closed-loop feedback precision below 0.5 percent hysteresis. Domestic and export vehicle programs must demonstrate compliance through standardized test cycles, forcing suppliers to invest in laser-welded butterfly valve joints and ceramic-coated shaft bearings.
Buyer concentration among Chinese state-owned vehicle producers is consolidating procurement authority toward centralized platform teams. Tier-one suppliers are responding with localized engineering centers in Shanghai and Wuhan, displacing arm's-length distribution relationships that previously governed component sourcing in the market.
Automotive Throttle Body Assembly Market Segmentation
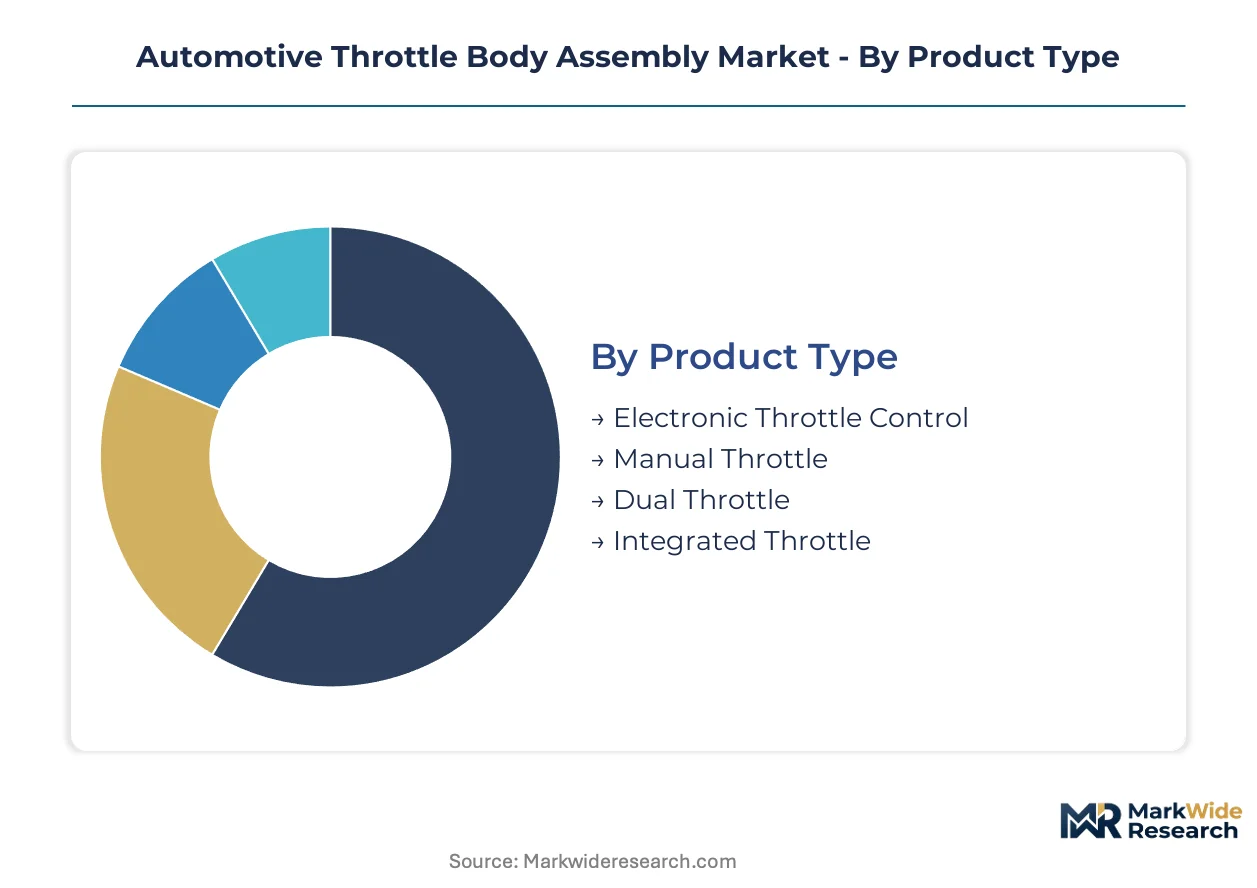
Throttle body procurement patterns diverge sharply across product architectures and vehicle platforms. OEM sourcing strategies favor integrated electronic systems for new vehicle programs while aftermarket channels sustain legacy mechanical configurations.
Product Type:
Cost tier differentiation separates precision-mapped electronic systems from mechanical linkages serving replacement markets.
- Electronic Throttle Control:Drive-by-wire architectures with DC motor actuators and redundant position sensors dominate OEM fitment. German passenger car producers specify these units for Euro 7 compliance, with procurement volumes concentrating in Stuttgart and Munich manufacturing corridors.
- Manual Throttle:Cable-actuated butterfly valves machined from aluminum castings serve cost-sensitive two-wheeler and commercial vehicle segments. Southeast Asian motorcycle assemblers in Thailand and Indonesia sustain demand through localized supplier networks.
- Dual Throttle:Twin-valve configurations optimize airflow stratification for performance engines. Ferrari and Porsche specify these units for high-revving naturally aspirated powertrains.
- Integrated Throttle:Consolidated units merging airflow sensing with actuator control reduce wiring complexity. Continental AG and Bosch GmbH compete for 48-volt mild-hybrid platform contracts.
Electronic Throttle Control commands the established base. The steepest expansion runs through Integrated Throttle architectures.
Vehicle Type:
Application severity dictates durability specifications and per-unit pricing tiers across mobility platforms.
- Passenger Cars:Light-duty throttle bodies with polymer gear trains and Hall-effect sensors generate the largest unit volumes. China's SAIC Motor and Geely Auto anchor procurement through Yangtze River Delta supply clusters.
- Commercial Vehicles:Heavy-duty castings with stainless steel shafts and extended service intervals command premium pricing. Daimler Truck and Volvo Group specify these for long-haul durability.
- Motorcycles:Compact single-barrel units with minimal electronic content serve mass-market two-wheeler production. Hero MotoCorp and Bajaj Auto drive volumes through Indian manufacturing.
- Electric Vehicles:Battery-electric platforms eliminate throttle bodies entirely, structurally excluding this segment from component demand.
Passenger Cars anchor current volumes. Commercial Vehicles deliver the highest margin expansion trajectory.
End User:
Customer type determines technical specification authority and contract structure complexity.
- OEMs:Direct platform engineering relationships with tier-one suppliers govern electronic throttle procurement. Volkswagen Group and Toyota Motor consolidate sourcing through centralized powertrain procurement teams.
- Aftermarket Suppliers:Independent distributors stock mechanical replacement units for legacy vehicle parc. O'Reilly Auto Parts and AutoZone maintain inventory depth for North American repair channels.
- Distributors:Regional wholesalers bridge arm's-length relationships between manufacturers and smaller repair networks. LKQ Corporation manages European aftermarket logistics.
- Vehicle Manufacturers:Captive component divisions at BYD and Tata Motors source throttle bodies through internal supply chains.
OEMs control specification authority. Aftermarket Suppliers provide the most resilient demand floor during production cycle downturns.
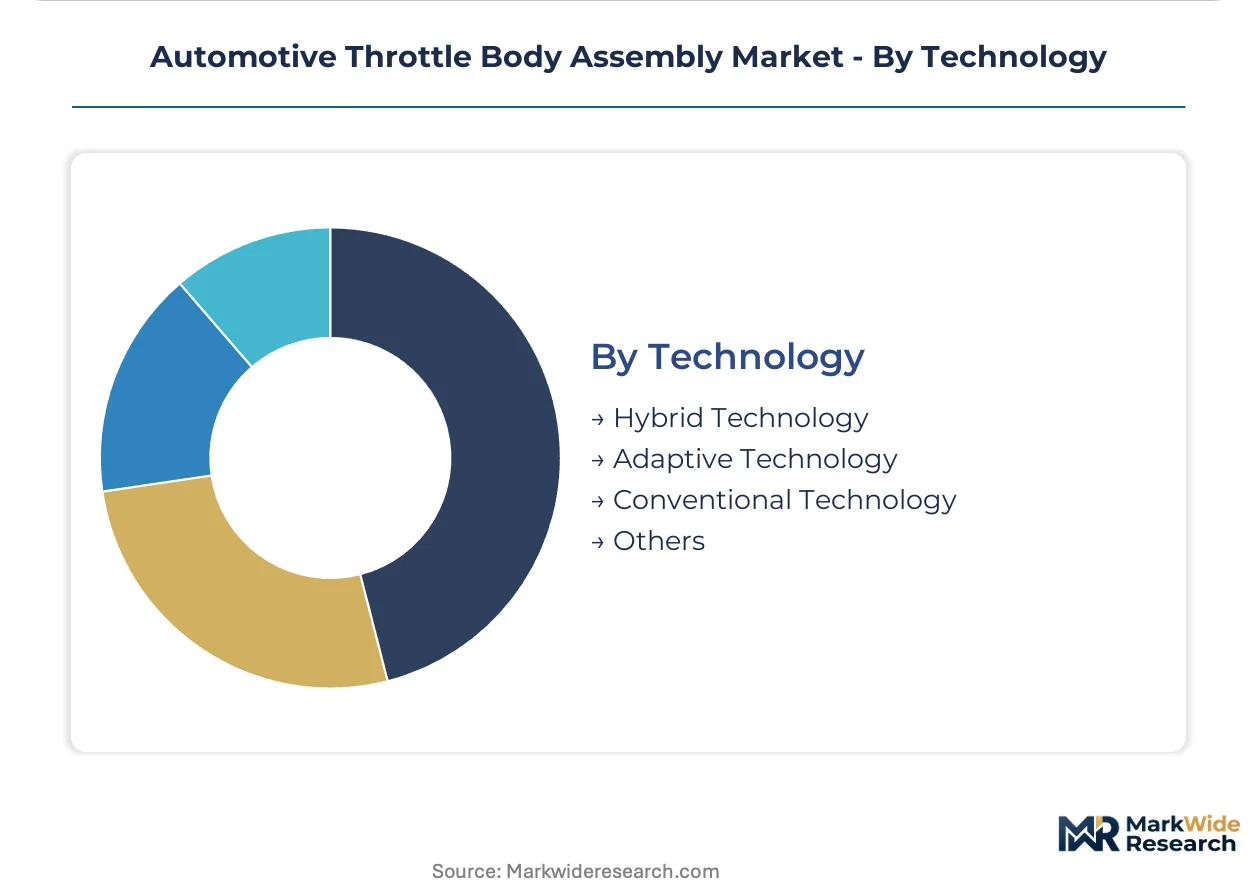
Technology:
Maturity gradients separate legacy mechanical systems from software-defined calibration architectures.
- Hybrid Technology:Throttle bodies optimized for engine-on/engine-off cycling in electrified powertrains. Honda and Hyundai specify these for dual-motor hybrid transaxles.
- Adaptive Technology:Self-learning calibration algorithms adjust airflow mapping based on sensor feedback. BMW and Mercedes-Benz integrate these with predictive cruise control systems.
- Conventional Technology:Fixed mechanical linkages without electronic feedback persist in emerging market commercial vehicles. Ashok Leyland and FAW Group maintain these specifications for cost containment.
- Others:Experimental drive-by-wire prototypes and solid-state actuator concepts remain pre-commercial. Tier-one R&D centers in Stuttgart and Tokyo evaluate these for next-generation architectures.
Conventional Technology retains the largest installed base. Hybrid Technology is climbing the fastest among growth segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision electronic throttle systems to passenger car OEMs across the European Union. Japanese suppliers ship calibrated actuator assemblies to hybrid vehicle programs in North America and Southeast Asia. Chinese manufacturing clusters now serve domestic brands that previously imported from foreign tier-ones.
Germany
Stuttgart-based OEMs source electronic throttle bodies for Euro 7 compliance from Munich manufacturing corridors. The KBA enforces type-approval testing for NOx reduction systems. Bosch GmbH and Continental AG anchor production in Baden-Württemberg and Lower Saxony.
China
SAIC Motor and Geely Auto drive localization of throttle body supply chains away from import dependency. MIIT dual carbon goals mandate fuel efficiency improvements for internal combustion engines in hybrid transition vehicles. Yangtze River Delta clusters in Shanghai and Wuhan host engineering centers from global tier-ones.
Japan
Toyota Motor and Honda Motor specify sub-0.5 percent hysteresis tolerances for export vehicle programs. METI fuel efficiency benchmarks cascade into throttle calibration requirements for domestic and overseas markets. Kansai and Nagoya production networks concentrate precision machining capabilities.
United States
Detroit Three automakers procure heavy-duty throttle bodies for commercial vehicle durability specifications. EPA tailpipe standards compel airflow measurement accuracy improvements for NOx and particulate compliance. Midwest manufacturing corridors in Michigan and Ohio process aluminum die-cast housings.
India
Hero MotoCorp and Bajaj Auto sustain demand for manual throttle configurations in cost-sensitive two-wheeler segments. BIS certification requirements govern electronic component imports for domestic vehicle assembly. Tamil Nadu and Maharashtra production clusters localize supply for motorcycle OEMs.
Automotive Throttle Body Assembly Market Competitive Environment
On the supply side, the industry is consolidating around tier-one suppliers with integrated electronics capabilities. Tier-two machined component specialists compete on aluminum casting and shaft machining for aftermarket replacement channels. Three strategic archetypes dominate: diversified powertrain conglomerates, mechatronics-integrated specialists, and regional aluminum foundry operators. Competitive moves center on backward integration into sensor manufacturing and geographic expansion through localized engineering centers.
Within the diversified conglomerate tier, Bosch GmbH, Denso Corporation, and Continental AG occupy positions that span engine management electronics through precision actuator hardware. These Stuttgart-based, Japanese, and Hanover-based entities exemplify the capability convergence that OEMs now require for 48-volt mild-hybrid platform sourcing. Their scale allows representation across passenger car, commercial vehicle, and motorcycle segments without portfolio fragmentation.
| Leading Market Players |
|---|
| Delphi Technologies |
| Hitachi Automotive Systems |
| Bosch GmbH |
| Valeo SA |
| Keihin Corporation |
| Denso Corporation |
| Magneti Marelli |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European aluminum die-cast foundries is compressing margin buffers for machined housing suppliers while amplifying pricing leverage for integrated tier-ones with captive casting operations. This utilization asymmetry between fragmented component specialists and consolidated mechatronics suppliers shapes procurement negotiations across passenger car and commercial vehicle programs.
Pricing Analysis
Electronic throttle control systems command a 40-60% premium over manual throttle configurations due to embedded sensor arrays and software calibration requirements. Pricing stratifies across premium integrated throttle-valve architectures for 48-volt mild-hybrid platforms, standard electronic units for mass-market OEM fitment, and economy mechanical replacements for aftermarket channels. Cost compression in aluminum die-cast inputs is intensifying because energy-intensive smelting operations face carbon pricing exposure. Aftermarket distributors exhibit the highest price sensitivity, while OEM platform engineering teams prioritize calibration precision over unit cost.
Supply Chain Analysis
Contract manufacturing concentration resides with Bosch GmbH, Denso Corporation, and Continental AG, which anchor precision machining and sensor integration capacity across Baden-Württemberg, Aichi Prefecture, and Lower Saxony. Geographic supply concentration centers on Germany, China, and Japan, with Yangtze River Delta clusters emerging as secondary hubs for domestic Chinese vehicle producers. Raw material dependencies draw from aluminum die-cast feedstock, rare-earth magnet materials for DC motor actuators, and ceramic-coated shaft bearings. Single-source vulnerability in Hall-effect sensor substrates presents structural risk. Distribution runs through direct platform engineering relationships with OEM procurement teams, displacing arm's-length tier-two channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification thresholds are compressing the addressable market for traditional throttle body architectures, yet hybrid transition vehicles and commercial vehicle durability specifications create defensive growth pockets for suppliers with mechatronics integration capabilities.
For Market Incumbents: Pre-empt margin erosion in passenger car electronic throttle segments by accelerating backward integration into sensor manufacturing and software calibration talent acquisition. Battery-electric platform proliferation threatens structural demand collapse; defend position through heavy-duty commercial vehicle contract expansion and ISO 26262 ASIL-rated system certification investment. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian motorcycle aftermarket channels where manual throttle configurations retain demand persistence and incumbent electronics capabilities offer limited competitive advantage. Target India's two-wheeler replacement market through localized aluminum casting partnerships with Tamil Nadu foundry networks. Pursue cost-containment positioning against premium electronic systems. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tier-two machined component specialists face structural displacement by integrated mechatronics suppliers with engine management software capabilities. Acquisition target archetype: regional aluminum foundry operators with automotive certification and capacity to support hybrid powertrain throttle programs. Monitor battery-electric vehicle penetration rates in passenger car segments as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mechatronics Capability Acquisition | Sensor integration expertise addresses Euro 7 calibration requirements for Stuttgart-based OEM procurement teams. |
| Localized Engineering Center Expansion | Shanghai and Wuhan facilities capture procurement authority consolidation among Chinese state-owned vehicle producers. |
| Commercial Vehicle Durability Certification | Extended service interval specifications command premium pricing from Daimler Truck and Volvo Group. |
| Aluminum Die-Cast Backward Integration | Captive housing production insulates margin stability from energy-intensive smelting cost volatility. |
| Aftermarket Distribution Channel Control | Direct relationships with O'Reilly Auto Parts and AutoZone provide resilient demand floor during OEM production downturns. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, and SEC filings from publicly traded tier-one suppliers. The research combined structured interviews with OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution channel managers, and aluminum foundry operations heads with bottom-up and top-down triangulation. Secondary validation drew from KBA type-approval records, MIIT fuel efficiency compliance filings, and METI benchmark documentation.
Forecast inputs encompass vehicle class segmentation, propulsion architecture transition curves, content-per-vehicle assumptions for hybrid versus conventional platforms, OEM tier sourcing concentration, and regional production cluster capacity utilization. Analytical frameworks modeled volume and value trajectories across the projection horizon through segment-level CAGR derivation calibrated to powertrain electrification thresholds and emissions regulatory phase-in schedules.
Sensitivities concentrate around battery-electric vehicle adoption velocity, aluminum input cost volatility, and REACH substance restriction timelines for sensor coating materials. Forecasts reflect documented assumptions regarding hybrid transition vehicle production persistence and commercial vehicle electrification lag. Quarterly review of OEM platform engineering procurement decisions and foundry capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
China and Saudi Arabia Automotive Market