
 Canada Passenger Vehicles Lubricants Market | 2026-2036
Canada Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Passenger Vehicles Lubricants Market Outlook
Multi-source procurement among Canadian distributors is decoupling from traditional refiner-direct contracts. Petro-Canada Lubricants Inc. leverages its domestic blending infrastructure to anchor supply security for Ontario-based fleet accounts. Imperial Oil Limited competes through integrated upstream logistics that reduce lead times to Prairie-region retail networks. Valvoline Inc. differentiates via specialized quick-lube channel partnerships that control last-mile service station access.
Canada passenger vehicles lubricants comprise refined petroleum or synthetic base stocks formulated with additive packages to reduce friction, dissipate heat, and protect powertrain components across internal combustion and hybrid drivetrains. These fluids typically meet SAE viscosity grades and API service categories that define performance under cold-start and high-temperature operating conditions. Engine oil dominates product type value contribution as turbocharged direct-injection powertrains proliferate, demanding formulations with enhanced thermal oxidation stability. Aftermarket providers lead end user volume through the country's aging vehicle parc, while online platforms capture growing share among DIY consumers seeking specification-matched products for European and Asian nameplate maintenance.
Health Canada's PMRA oversees environmental release standards for lubricant constituents, while Environment and Climate Change Canada administers VOC regulations that constrain formulation chemistry in consumer-facing products. The Canadian General Standards Board publishes CAN/CGSB specifications that provincial fleet procurement mandates frequently reference as minimum compliance thresholds. Stakeholders must monitor pending federal clean fuel regulations and provincial zero-emission vehicle mandates that could bifurcate lubricant demand between legacy internal combustion service and emerging hybrid-specific formulations.
Market Dynamics
Federal emissions guidelines are compressing lubricant viscosity specifications while Ontario and Quebec fleet operators accelerate scheduled maintenance program expansions. This regulatory-mechanical convergence is rewiring procurement relationships between refiners, distributors, and commercial vehicle operators.
Growth Catalysts
- Low-viscosity formulation mandates:Environment and Climate Change Canada VOC regulations are forcing adoption of 0W-16 and 0W-20 grades that reduce cold-start friction losses.
- Extended drain interval technology:Synthetic blend chemistry advances allow Ontario-based commercial fleets to stretch service windows from 8,000 to 15,000 kilometers.
- Turbocharged powertrain proliferation:Direct-injection gasoline engines generate higher thermal loads that demand API SP and ILSAC GF-6 compliant lubricants.
Market Restraints
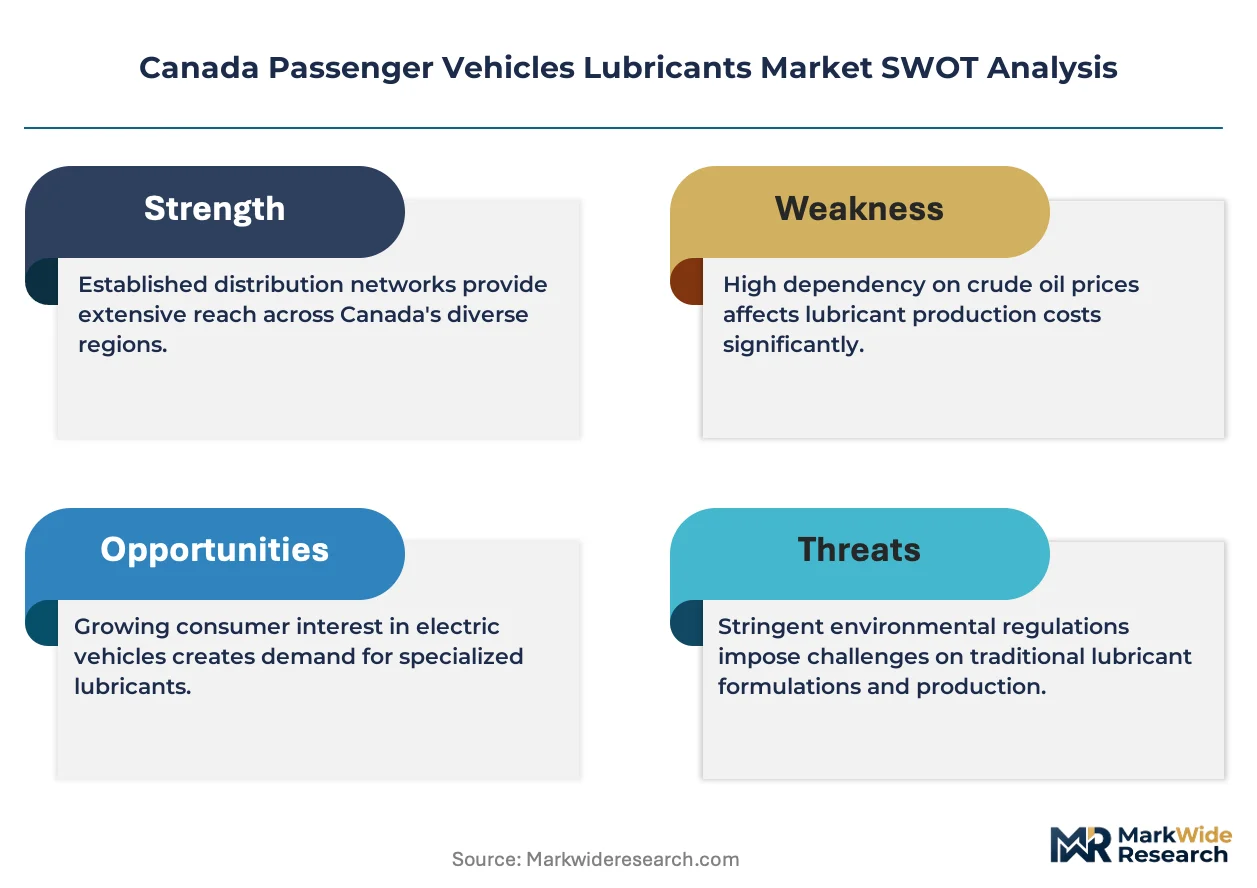
- Base oil supply concentration:Group II and III base stock production clusters in the US Gulf Coast expose Canadian blenders to cross-border pipeline and rail bottlenecks.
- Additive package cost volatility:Molybdenum disulfide and boron friction modifier prices fluctuate with mining output from South American concentrate suppliers.
- Zero-emission vehicle displacement:British Columbia and Quebec ZEV mandates threaten long-term internal combustion lubricant demand in urban commuter segments.
Strategic Opportunities
- Hybrid-specific formulation gaps:Stop-start engine cycling creates unique thermal stress patterns that existing PCMO specifications inadequately address.
- Prairie region DIY channel expansion:Saskatchewan and Manitoba retail networks remain underpenetrated by specification-matched e-commerce platforms.
- CGSB specification alignment:Provincial fleet procurement mandates referencing CAN/CGSB-3.5 create compliance-driven volume anchors for certified suppliers.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in tribology and additive synergy optimization is concentrating among retiring cohorts at domestic refiners.
- Multi-specification inventory complexity:European ACEA C-series, US API, and Asian OEM-specific standards force distributors to triple SKU counts.
- Used oil collection infrastructure gaps:Extended producer responsibility frameworks in Ontario and British Columbia require reverse logistics investments that erode margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Passenger Vehicles Lubricants Market |
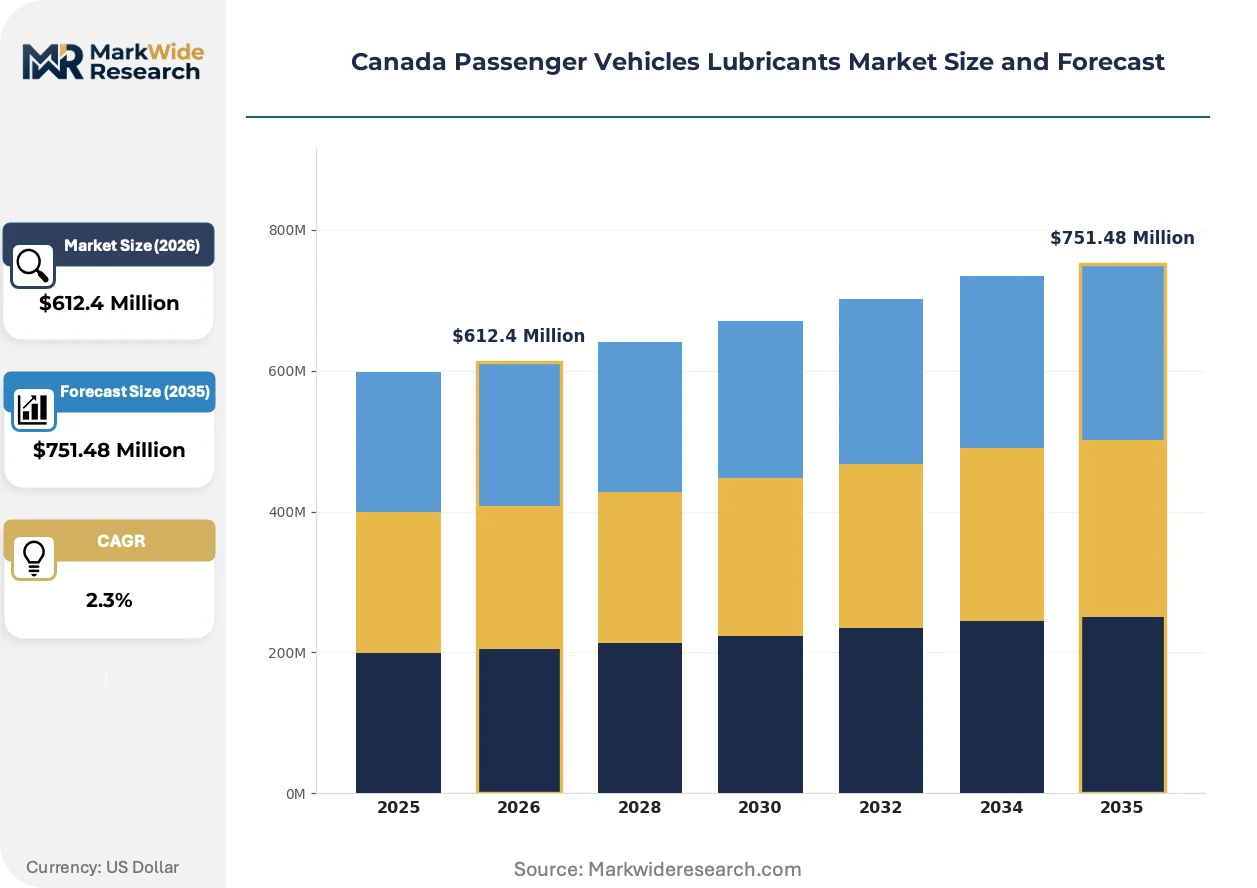
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $751.48 Million |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Service Stations Packaging Type: Bottles, Cans, Drums, Bulk Containers |
| Companies Covered | Chevron Corporation, Petro-Canada Lubricants Inc., Exxon Mobil Corporation, Valvoline Inc., Imperial Oil Limited, Royal Dutch Shell plc, TotalEnergies SE, HF Sinclair Corporation, BP plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Passenger Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and distribution architecture are diverging from legacy petroleum-centric models as electrification and digitization penetrate vehicle service ecosystems. Three distinct vectors are compressing traditional value capture mechanisms.
Polyalkylene glycol (PAG) and ester-based base stocks are absorbing thermal stress from turbocharged direct-injection engines that operate at higher peak temperatures than port-injection designs. Quick-lube chains in the Greater Toronto Area are adopting these chemistries at accelerated rates to reduce warranty claims. This absorption of thermal load is compressing demand for conventional Group I mineral oils in passenger vehicle applications.
Health Canada's PMRA is tightening environmental release standards for zinc dialkyldithiophosphate (ZDDP) and other anti-wear additives with aquatic toxicity profiles. The regulatory friction is forcing reformulation toward ashless phosphorus and sulfur compounds that maintain wear protection at reduced treat rates. British Columbia's coastal watershed protection zones are experiencing the most acute compliance pressure, driving early adoption of next-generation additive packages.
DIY consumers are migrating toward specification-matched online platforms that decode VIN-linked lubricant requirements for European and Asian nameplates. This channel rotation is displacing traditional auto parts counter relationships in Alberta and Ontario urban corridors. The behavior shift concentrates among owners of BMW, Mercedes-Benz, and Toyota hybrids seeking exact OEM approvals rather than generic API compliance.
Canada Passenger Vehicles Lubricants Market Segmentation
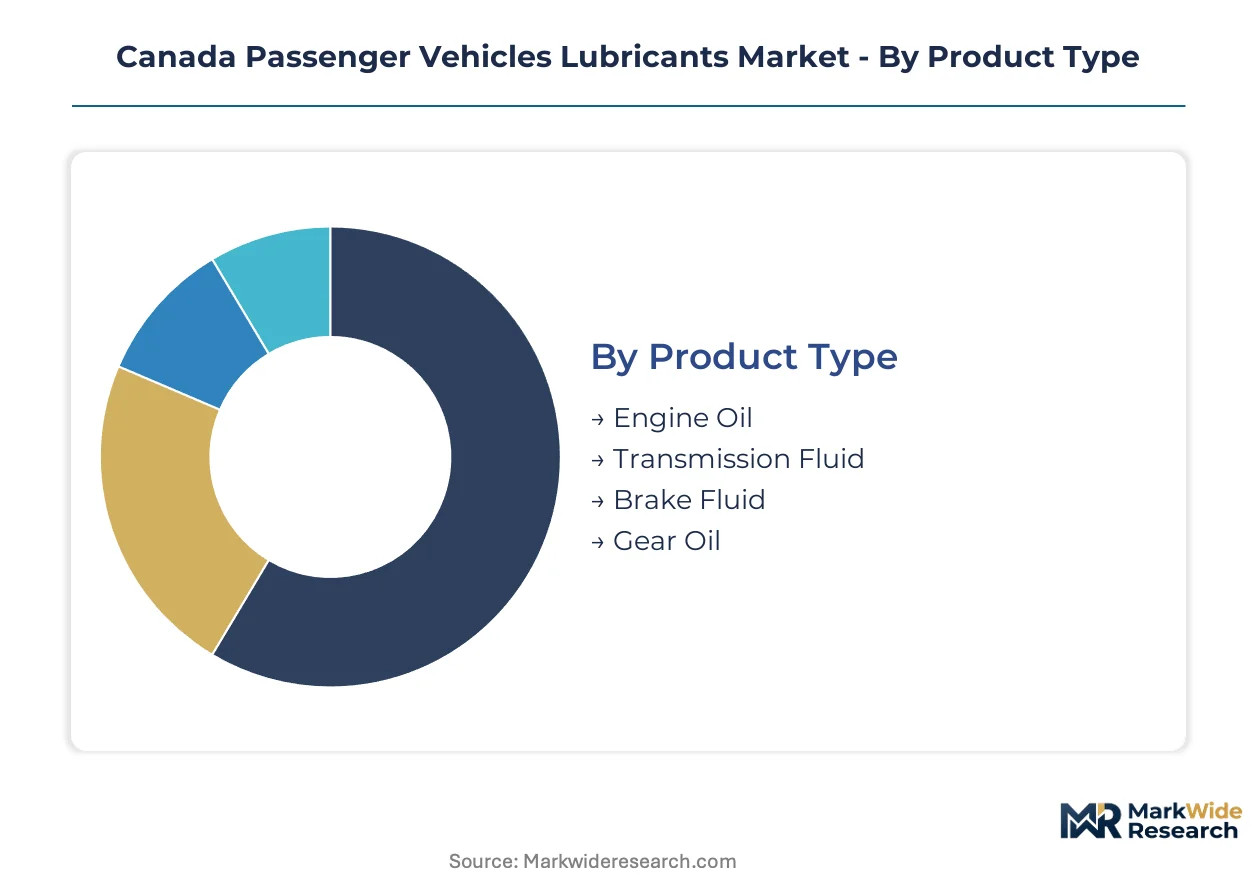
Segmentation in Canada's passenger vehicle lubricants market exposes divergent margin structures and specification requirements across product formulations and procurement channels. Understanding where synthetic blends command premium pricing versus where conventional oils retain volume reveals strategic positioning opportunities for blenders and distributors serving Ontario's fleet corridors and Prairie DIY networks.
Product Type:
Integration depth varies sharply across lubricant categories, with some fluids operating as standalone service items while others embed within sealed powertrain systems requiring specialized equipment for exchange.
- Engine Oil:Formulated from Group II, III, or IV base stocks combined with detergent-dispersant and anti-wear additive packages meeting API SP or ILSAC GF-6 specifications. Demand concentrates in Ontario's Greater Toronto Area commuter corridor where turbocharged direct-injection engines drive 0W-16 and 0W-20 grade preference under federal emissions guidelines.
- Transmission Fluid:Synthetic-based formulations with friction modifiers and oxidation inhibitors engineered for continuously variable and dual-clutch transmission architectures. Quebec fleet operators are expanding bulk procurement of low-viscosity ATF variants as extended drain interval programs reduce total cost of ownership for commercial vehicle pools.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, or DOT 5.1 specifications for corrosion inhibition and high-temperature stability.
- Gear Oil:High-viscosity base stocks fortified with extreme-pressure additives for differential and manual transmission applications in light trucks and SUVs across Prairie-region recreational vehicle segments.
Engine Oil leads volumes today; Transmission Fluid is gaining share fastest as CVT penetration climbs among Canadian passenger vehicle registrations.
End User:
Procurement authority fragments across vehicle lifecycle stages, with specification control shifting from factory fill decisions to independent service providers as vehicles age out of warranty coverage.
- OEMs:Factory-fill contracts demand exacting OEM-specific approvals beyond generic API classifications, with Toyota, Honda, and domestic Detroit Three nameplate requirements driving formulation complexity at Canadian blending facilities.
- Aftermarket Providers:Independent distributors and parts retailers serving Canada's aging vehicle parc where specification-matched products for European and Asian nameplates command shelf space priority in Alberta and Ontario urban corridors.
- Fleet Operators:Commercial vehicle pools across Ontario and Quebec implementing centralized procurement of synthetic blends with 15,000-kilometer drain intervals to compress total maintenance expenditure.
- Repair Shops:Independent service bays in British Columbia coastal markets facing elevated compliance pressure from Health Canada PMRA environmental release standards for used oil handling.
Aftermarket Providers dominate volume throughput; Fleet Operators are expanding procurement scale most aggressively as centralized maintenance programs consolidate lubricant purchasing.
Distribution Channel:
Channel economics diverge based on last-mile service integration, with platforms controlling physical installation infrastructure capturing margin that pure product retailers cannot access.
- Retail Stores:Canadian Tire, PartSource, and NAPA locations across suburban Ontario and Quebec corridors where DIY consumers seek specification-matched products for European nameplate maintenance.
- Online Platforms:VIN-linked lubricant recommendation engines capturing growing share among Alberta and Ontario hybrid owners seeking exact OEM approvals rather than generic API compliance.
- Wholesale Distributors:Multi-source procurement networks decoupling from traditional refiner-direct contracts to anchor supply security for Prairie-region retail networks.
- Service Stations:Quick-lube chains in the Greater Toronto Area adopting PAG and ester-based chemistries at accelerated rates to reduce warranty claims on turbocharged powertrains.
Retail Stores maintain volume leadership; Online Platforms are climbing the fastest as VIN-linked specification matching displaces traditional counter relationships.
Packaging Type:
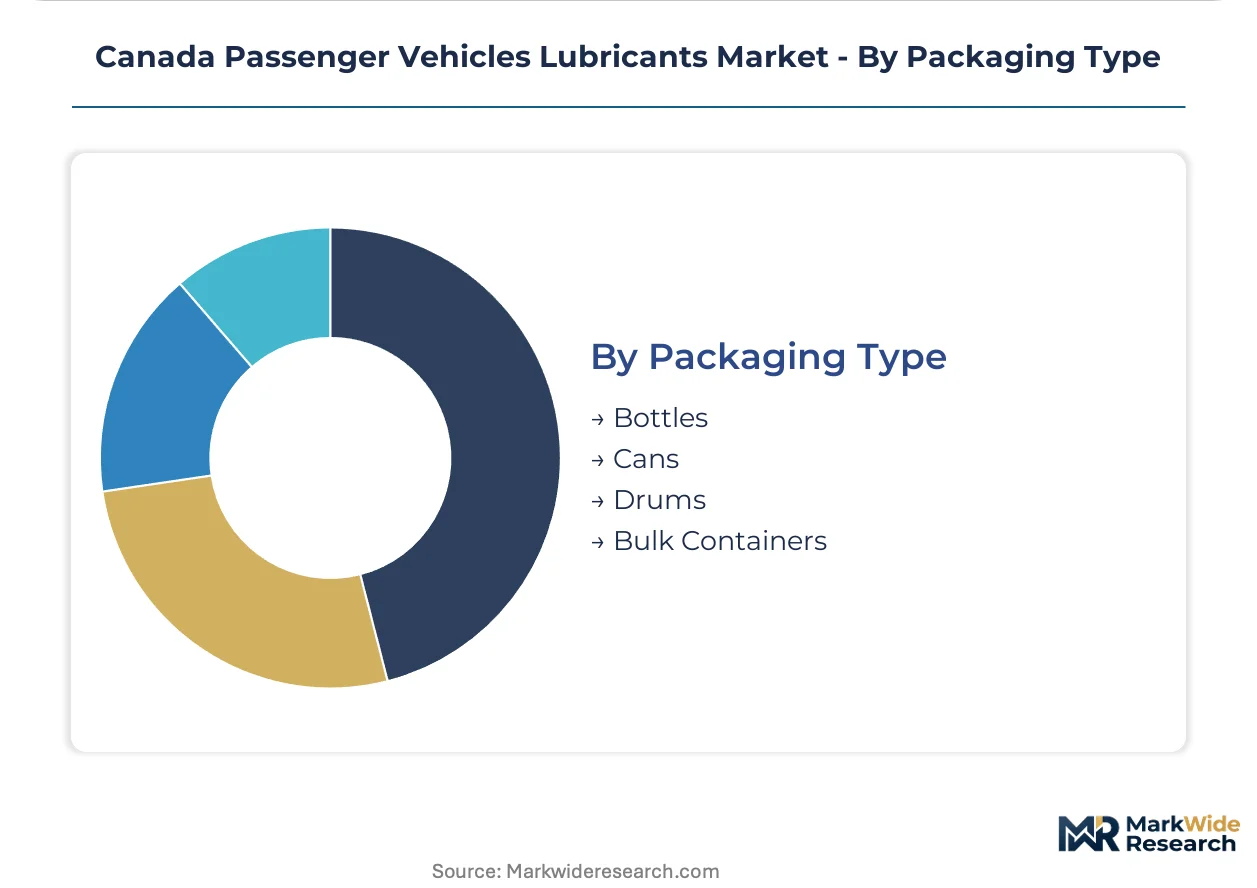
Packaging economics track procurement scale and storage infrastructure, with bulk systems penetrating fleet accounts while retail formats serve fragmented DIY demand.
- Bottles:One-liter and four-liter polyethylene containers dominating retail shelf presence for passenger car motor oil across Canadian Tire and independent automotive parts networks.
- Cans:Metal packaging formats retaining position in brake fluid and specialty lubricant segments where chemical compatibility requirements constrain plastic substitution.
- Drums:205-liter steel containers anchoring fleet and commercial account supply agreements across Ontario-based logistics and delivery vehicle operators.
- Bulk Containers:Intermediate bulk containers and tankwagon deliveries supporting centralized maintenance facilities with high-volume dispensing infrastructure and used oil collection reverse logistics.
Bottles lead unit volumes today; Bulk Containers are expanding most quickly as fleet operators consolidate lubricant procurement into centralized maintenance facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Toronto Area anchors Canadian lubricant demand through dense commuter corridors and concentrated fleet operator bases. Provincial regulatory divergence and sub-regional vehicle parc characteristics create distinct procurement environments across Canada's five major economic zones.
Ontario
Turbocharged direct-injection engine proliferation and extended drain interval adoption drive formulation demand in Ontario's automotive manufacturing heartland. Health Canada PMRA environmental release standards constrain additive chemistry for service providers operating near the Great Lakes watershed. The Windsor-to-Oshawa corridor concentrates quick-lube chain infrastructure where PAG-based chemistries reduce warranty claims on high-thermal-load powertrains.
Quebec
Commercial fleet pools in Quebec are consolidating lubricant procurement through centralized maintenance programs with 15,000-kilometer synthetic blend intervals. The province's zero-emission vehicle mandates threaten long-term internal combustion lubricant demand in Montreal's urban commuter segments. Laval and Longueuil service bay networks face elevated compliance pressure from provincial extended producer responsibility frameworks for used oil collection.
Alberta
DIY consumer migration toward VIN-linked online platforms concentrates in Calgary and Edmonton corridors where European and Asian nameplate ownership rates exceed national averages. The province's oil sands proximity supports domestic base stock supply security for regional blenders. Specification-matched e-commerce platforms capture growing share among hybrid owners seeking exact OEM approvals rather than generic API compliance.
British Columbia
Coastal watershed protection zones in British Columbia drive early adoption of next-generation ashless additive packages under Health Canada PMRA tightening. Vancouver's quick-lube chains absorb accelerated rates of ester-based thermal stress formulations for turbocharged engines. The province's ZEV mandate timeline compresses long-term lubricant demand planning for urban service providers.
Prairie Provinces
Saskatchewan and Manitoba retail networks remain underpenetrated by specification-matched e-commerce platforms relative to central Canadian corridors. Agricultural vehicle service requirements create distinct seasonal demand patterns for high-viscosity gear oils in light truck segments. Regina and Winnipeg distribution hubs anchor wholesale procurement networks decoupling from traditional refiner-direct contracts.
Canada Passenger Vehicles Lubricants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid-specific formulation gaps and digital channel integration. The Canadian market structures around integrated refiner-blenders, independent quick-lube specialists, and specification-focused distributors. Three archetypes dominate: domestic upstream-integrated suppliers leveraging geographic proximity, multinational formulators with OEM certification depth, and channel-specialized operators controlling last-mile service access. Competitive moves concentrate on strategic partnerships with fleet operators and portfolio diversification into synthetic blend chemistry.
Within the domestic integrated tier, Petro-Canada Lubricants Inc. and Imperial Oil Limited anchor supply security for Ontario-based fleet accounts through captive blending infrastructure and upstream logistics control. Among multinational formulators, Valvoline Inc. occupies a position exemplifying quick-lube channel specialization that governs service station access in dense urban corridors. These three entities represent the competitive archetypes reshaping procurement relationships between refiners, distributors, and commercial vehicle operators across Canadian provincial markets.
| Leading Market Players |
|---|
| Chevron Corporation |
| Petro-Canada Lubricants Inc. |
| Exxon Mobil Corporation |
| Valvoline Inc. |
| Imperial Oil Limited |
| Royal Dutch Shell plc |
| TotalEnergies SE |
| HF Sinclair Corporation |
| BP plc |
| Others |
Value Chain & Pricing Dynamics
Synthetic base stock substitution at Canadian blending facilities is compressing conventional Group I mineral oil margins while concentrating procurement leverage among Group II and III suppliers near the US Gulf Coast. This chemistry transition simultaneously elevates formulation costs and reshapes supplier-buyer power dynamics across Ontario fleet corridors and Prairie retail networks.
Pricing Analysis
Input-cost pass-through from South American molybdenum disulfide and boron friction modifier mining volatility feeds directly into additive package pricing. Three-tier pricing structure across premium synthetic, mid-grade synthetic blend, and economy conventional mineral oil levels stratifies by SAE viscosity grade and API certification tier. Cost compression in the economy tier is intensifying as extended drain interval technology commoditizes mid-grade synthetic blends. Fleet operators in Ontario and Quebec exhibit lowest price sensitivity due to total cost of ownership calculations, while Prairie-region DIY consumers drive hardest bargain hunting on specification-matched products.
Supply Chain Analysis
Direct-to-fleet channels handle high-volume commercial demand through tankwagon and intermediate bulk container deliveries anchored at centralized maintenance facilities. Base oil supply concentrates in the United States, South Korea, and Japan, with Canadian blenders drawing heavily from US Gulf Coast Group II and III production clusters. Raw material dependencies rest on Venezuelan crude feedstocks for Group I base stocks, Asian PAO and ester synthetic base stocks, and Chilean molybdenum concentrate for friction modifiers. Single-source vulnerability to cross-border pipeline and rail bottlenecks between the US Gulf Coast and Ontario blending plants constitutes the dominant structural risk. Distribution runs through wholesale distributor networks decoupling from refiner-direct contracts to serve fragmented retail and service station endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's passenger vehicle lubricants market functions as a regulatory compounder where Environment and Climate Change Canada VOC tightening and pending federal clean fuel regulations continuously reset formulation specifications and procurement compliance thresholds.
For Market Incumbents: Acquire hybrid-specific formulation intellectual property and captive used oil collection infrastructure to defend against zero-emission vehicle displacement threats in British Columbia and Quebec. Backward integration into Group III base stock supply agreements with US Gulf Coast producers anchors margin control against cross-border logistics volatility. Certification investment in CAN/CGSB-3.5 alignment secures provincial fleet procurement mandate eligibility. For New Entrants and Emerging Players: VIN-linked e-commerce platforms represent the most penetrable route into Alberta and Ontario DIY segments where specification-matched demand for European and Asian nameplate lubricants outpaces traditional auto parts counter service. Saskatchewan and Manitoba retail networks remain underpenetrated by digital channels relative to central Canadian corridors. A go-to-market angle targeting Toyota and BMW hybrid owners seeking exact OEM approvals rather than generic API compliance captures premium pricing power. For Investors and Strategic Acquirers: Valuations sit cheapest among independent quick-lube operators with concentrated Greater Toronto Area real estate positions and established fleet service contracts. Long-term viability through the electrification transition hinges on diversification into hybrid-specific formulations and thermal management fluids for electric vehicle battery cooling systems. The signal to watch is British Columbia and Quebec zero-emission vehicle mandate acceleration timelines as inflection indicators for internal combustion lubricant demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Specific Formulation Development | Addresses stop-start thermal stress gaps left by existing PCMO specifications in Ontario and Quebec fleets. |
| Used Oil Collection Infrastructure Buildout | Satisfies Ontario and British Columbia extended producer responsibility frameworks while capturing reverse logistics revenue streams. |
| CAN/CGSB Certification Alignment | Unlocks provincial fleet procurement mandates referencing CAN/CGSB-3.5 as minimum compliance thresholds. |
| Prairie E-Commerce Platform Expansion | Penetrates Saskatchewan and Manitoba retail networks currently underserved by specification-matched digital channels. |
| Quick-Lube Channel Partnership Deepening | Controls last-mile service station access in dense urban corridors where PAG-based chemistries reduce warranty claims. |
Study Parameters
Bottom-up fleet operator and DIY consumer demand modeling reconciled against top-down refiner and distributor supply tracking forms the analytical core of this study. Primary interviews with lubricant blending plant managers, fleet procurement directors at Ontario and Quebec commercial vehicle pools, aftermarket distributor account executives, and quick-lube chain operations heads combined with secondary validation from Environment and Climate Change Canada regulatory filings, Health Canada PMRA release standard documentation, Canadian General Standards Board specification databases, and US Energy Information Administration base oil trade flow data. Cross-referencing bottom-up volume builds with top-down production and import statistics ensures triangulation integrity.
Historical trendline analysis of synthetic blend adoption rates, extended drain interval penetration, and low-viscosity grade preference establishes baseline growth trajectories across the projection horizon. Segmentation modeling spans product type (engine oil, transmission fluid, brake fluid, gear oil), end user category (OEMs, aftermarket providers, fleet operators, repair shops), distribution channel (retail stores, online platforms, wholesale distributors, service stations), and packaging format (bottles, drums, bulk containers). CAGRs derive from elasticity-adjusted demand curves incorporating turbocharged powertrain proliferation rates and regulatory compliance cost pass-through assumptions.
Zero-emission vehicle mandate acceleration, base oil supply disruption at US Gulf Coast production clusters, and additive package raw material price volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding federal emissions guideline enforcement timelines and provincial fleet procurement mandate expansion. Periodic stress-testing of base assumptions against regulatory announcement calendars and commodity price movement is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Wheel Arch Liner Market