
 Mexico Automotive Parts Die Casting Market | 2026-2036
Mexico Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Parts Die Casting Market Foresight
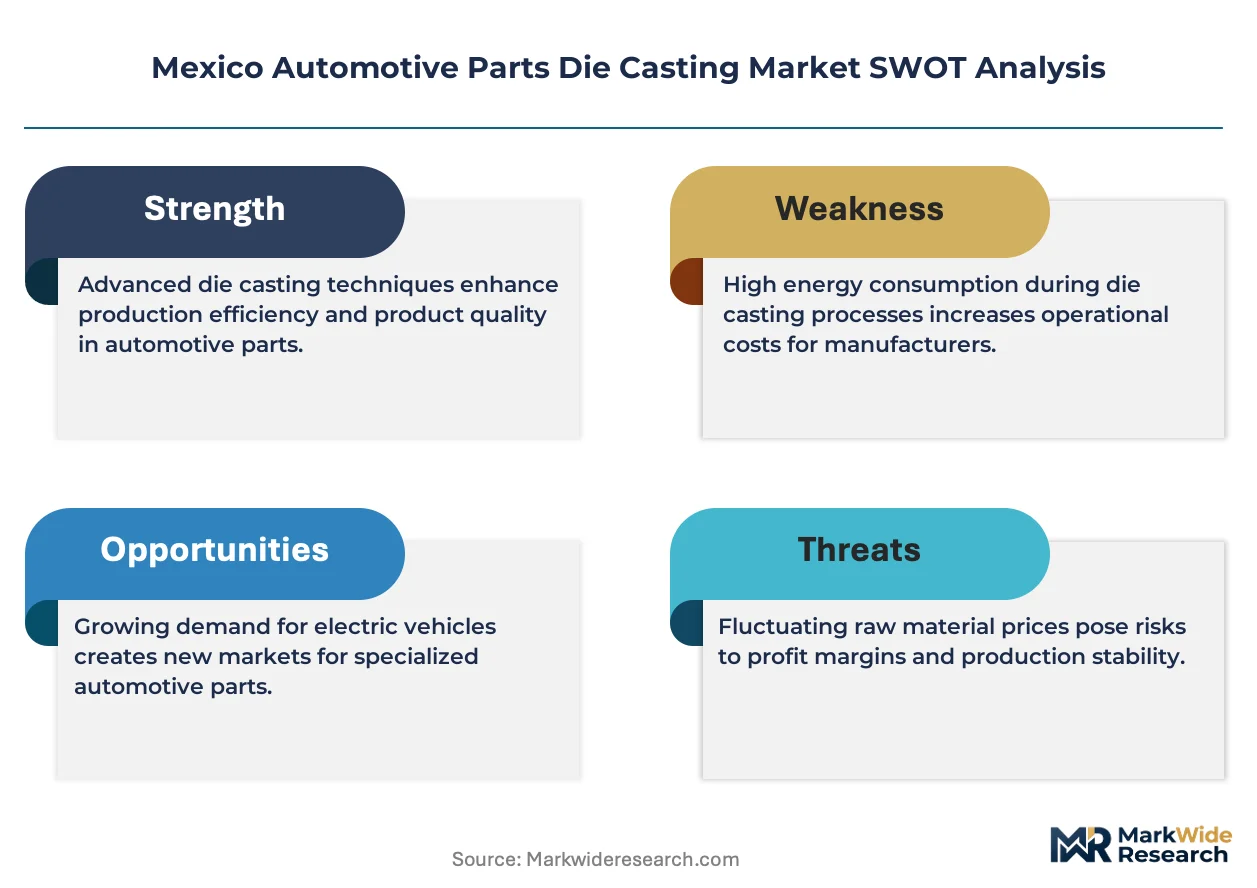
IATF 16949 certification is collapsing the supplier base into a smaller qualified tier, forcing unaccredited foundries toward aftermarket niches or exit. Nemak sustains its position through captive aluminum smelting and proximity to OEM engine plants in northern Mexico. Gibbs Die Casting Group leverages its high-pressure die-casting expertise to dominate transmission housing contracts for domestic light-truck programs. Bocar Group anchors its competitiveness through magnesium capability for electric vehicle structural components.
Automotive parts die casting is a metal-forming process wherein molten non-ferrous alloys—typically aluminum with 9-12% silicon content—are injected into hardened steel molds at pressures exceeding 1,000 bar to produce net-shape components with wall thicknesses below 3 millimeters. The process serves primarily to manufacture lightweight, dimensionally precise structural and powertrain parts that replace heavier steel stampings or forgings in vehicle assemblies. Engine Components command the largest share of current output, reflecting sustained internal-combustion production in Mexican export-oriented plants, while Electric Vehicles represents the fastest-growing application as OEMs source larger aluminum battery housings and motor end-caps from local Tier-1 die casters. Aluminum occupies the dominant material position due to its strength-to-weight ratio and recyclability, though Magnesium gains traction for seat frames and steering column brackets where gram-level weight reduction carries premium value.
SEMARNAT enforces emissions standards that constrain foundry energy intensity and particulate discharge, pushing capital investment toward electric melting and fume capture systems. NOM-001-SECRE mandates traceable mechanical properties for safety-critical chassis castings, effectively filtering out informal suppliers from OEM qualification cycles. The Federal Economic Competition Commission monitors concentration risks as major die casters consolidate capacity around Bajío automotive corridors. Stakeholders must weigh aluminum price volatility against long-term OEM contracts while monitoring whether NEV-specific casting standards emerge from Mexico's energy-transition regulatory agenda.
Market Dynamics
OEM consolidation around Guanajuato and Nuevo León is compressing supplier geography, forcing die casters to co-locate within 50 kilometers of assembly plants or forfeit Tier-1 status. This spatial lock-in is reshaping capital allocation across the Bajío corridor.
Growth Catalysts
- NOM-001-SECRE:The updated standard mandates traceable mechanical properties for safety-critical chassis castings, filtering informal suppliers and expanding qualified Tier-1 order books.
- Electric vehicle battery housings:OEMs are sourcing larger aluminum enclosures from local die casters to reduce import dependency and logistics costs for North American EV programs.
- Silicon-modified aluminum alloys:Foundries are adopting 9-12% silicon formulations that enable thinner wall sections below 3 millimeters, meeting EPA fuel-efficiency benchmarks without structural compromise.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations compress margin predictability for long-term OEM contracts indexed to spot-plus formulas.
- Captive smelter concentration:Northern Mexico hosts limited in-house aluminum supply, creating dependency on external ingot suppliers subject to energy cost spikes.
- Magnesium corrosion limitations:Seat frame and steering column applications face galvanic compatibility constraints that restrict substitution depth despite gram-level weight advantages.
Strategic Opportunities
- Querétaro aerospace corridor spillover:Precision die-casting expertise developed for automotive is transferable to aircraft structural components with margin premiums 40-60% above automotive tiers.
- SEMARNAT emissions compliance incentives:Foundries investing in electric melting and fume capture systems qualify for accelerated depreciation schedules under federal environmental programs.
- Hybrid powertrain integration:Transmission housings combining aluminum castings with integrated electric motor mounts represent uncontracted white space as OEMs dual-source ICE and PHEV variants.
Industry Challenges
- IATF 16949 certification timelines:Unaccredited foundries face 18-24 month qualification cycles that delay revenue recognition and strain working capital during transition.
- High-pressure die-casting tool steel scarcity:Hardened mold fabrication requires specialized heat treatment capacity concentrated in Monterrey and Toluca, creating bottlenecks for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Parts Die Casting Market |
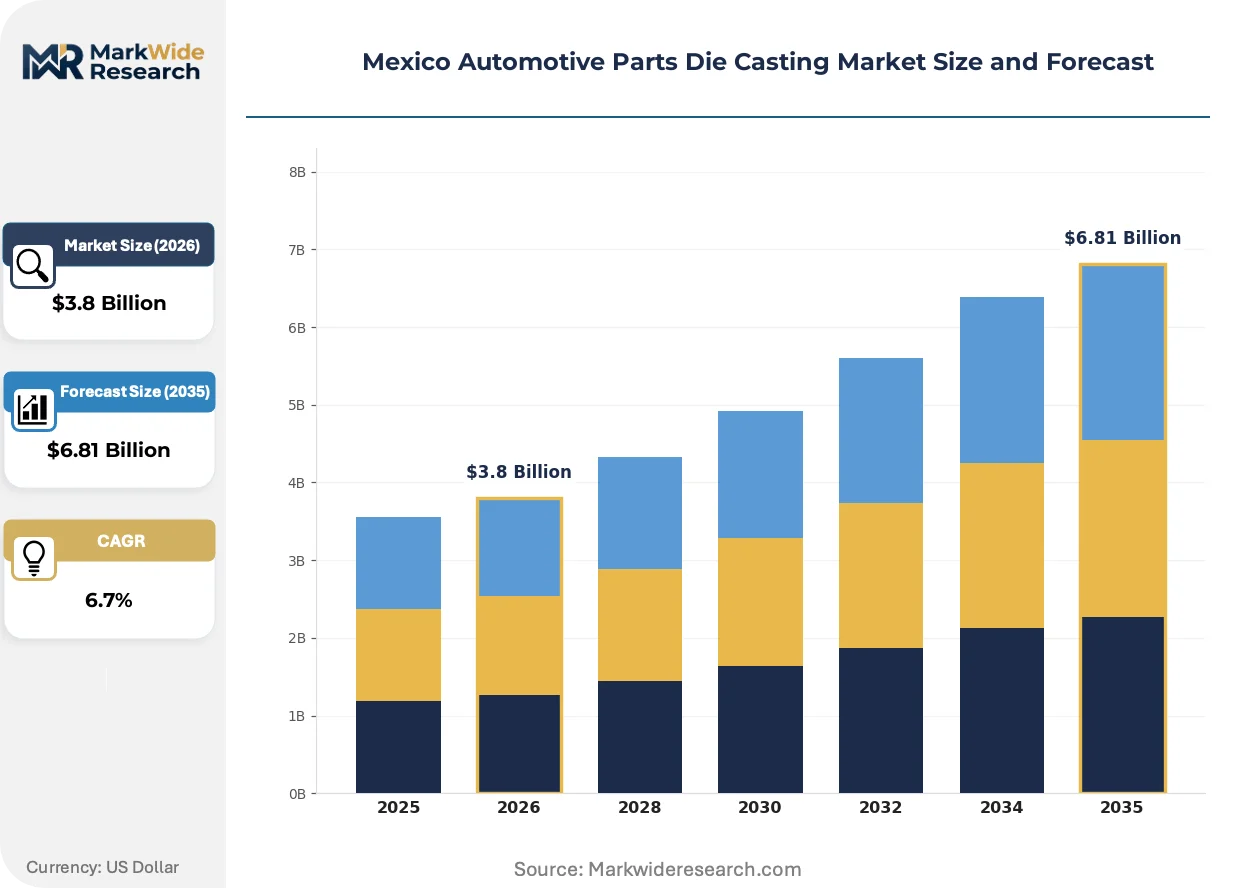
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Components, Body Parts Material: Aluminum, Zinc, Magnesium, Copper Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealers |
| Companies Covered | Sandhar Technologies Limited, Gibbs Die Casting Group, Nemak, Empire Casting Co, Endurance Group, Dynacast, Ryobi Die Casting, Cascade Die Casting Group Inc, Bocar Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Parts Die Casting Market Shifts & Advancements
Die-casting technology in Mexico is pivoting from standalone component supply toward integrated module delivery, with foundries assuming sub-assembly responsibility previously retained by Tier-1 integrators.
Thin-wall vacuum-assisted die casting is supplanting conventional high-pressure methods for battery tray applications, enabling wall thickness reduction to 2.5 millimeters while maintaining structural integrity. OEMs in Puebla and Guanajuato are qualifying this process for 2026-model-year EV platforms. The shift is compressing tool life economics and favoring foundries with in-house vacuum system maintenance capability.
SEMARNAT's 2024 update to foundry emissions protocols tightens particulate discharge limits and mandates continuous emissions monitoring for facilities above 500 tons annual aluminum throughput. Northern Mexican foundries are retrofitting baghouse systems and switching from gas-fired to electric resistance melting. The regulatory drag falls heaviest on legacy operations in Coahuila that lack capital reserves for compliance hardware.
Buyer consolidation among domestic OEMs is compressing supplier negotiation cycles from annual to quarterly price reviews, with volume commitments tied to real-time aluminum index adjustments. Tier-1 procurement teams in Aguascalientes and San Luis Potosí are unbundling tooling amortization from piece-price contracts. The behavioral shift is most visible in transmission housing categories where dual-source strategies dominate.
Mexico Automotive Parts Die Casting Market Segmentation
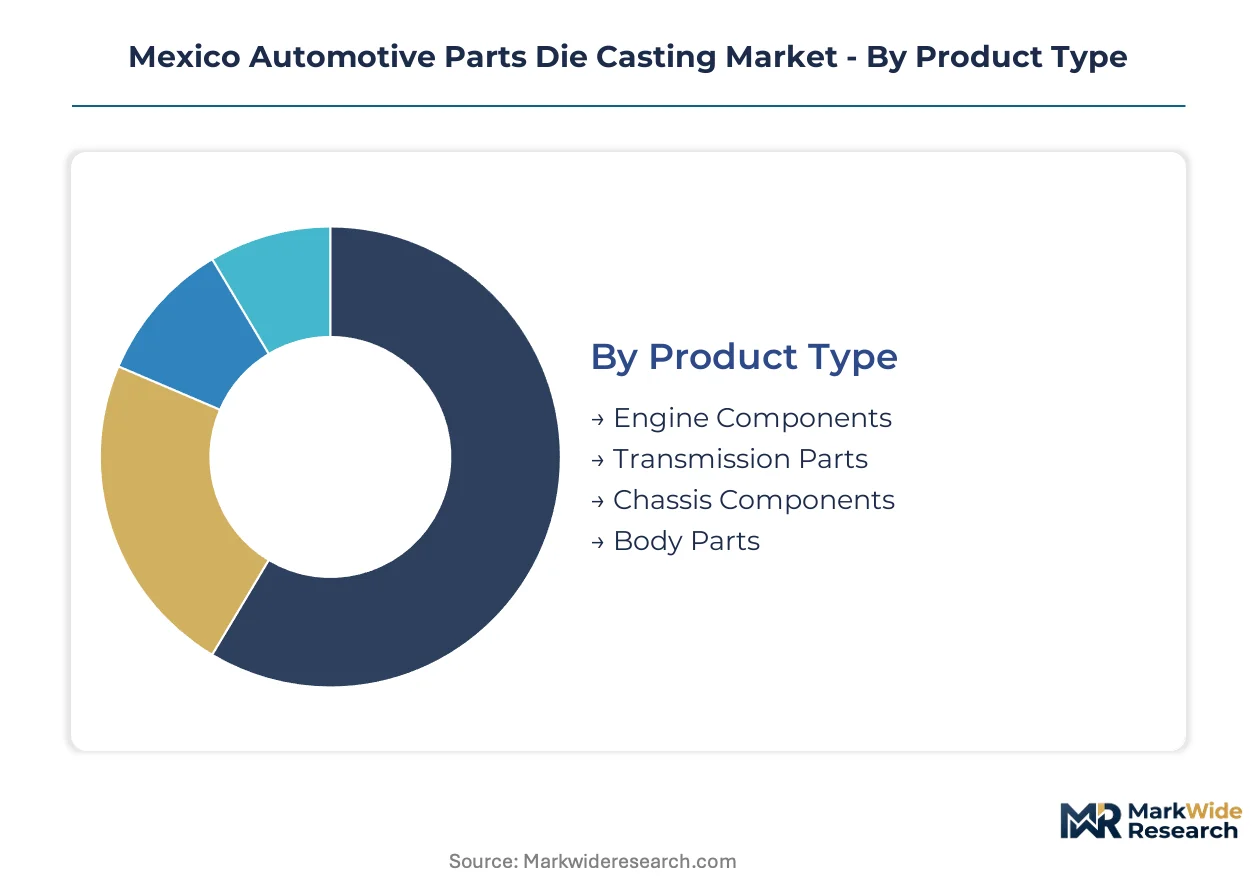
Mexico's die-casting output splits sharply between export-oriented OEM supply chains and domestic aftermarket channels. Segment boundaries determine qualification requirements, tooling amortization timelines, and margin structures across the Bajío manufacturing corridor.
Product Type:
Engine Components and Transmission Parts dominate export volumes to US and Canadian assembly plants, while Chassis Components serve mixed domestic and international demand.
- Engine Components:Cylinder heads, engine blocks, and oil pans fabricated from aluminum-silicon alloys with 9-12% silicon content for thermal fatigue resistance. Foundries in Guanajuato and Nuevo León concentrate capacity here to supply Detroit Three engine plants. NOM-001-SECRE traceability mandates filter out informal competitors from OEM qualification.
- Transmission Parts:Housings, valve bodies, and clutch carriers requiring dimensional tolerances below 0.1 millimeters for seamless assembly. High-pressure die-casting expertise developed for this category is migrating toward integrated electric motor mounts for hybrid programs.
- Chassis Components:Control arms, steering knuckles, and subframe nodes subject to impact-loading specifications.
- Body Parts:Door handles, mirror housings, and decorative trim with Class A surface requirements.
Engine Components commands the established base. The steepest expansion runs through Transmission Parts.
Material:
Cost tiers separate premium structural alloys from commodity formulations, with magnesium commanding price premiums for gram-critical applications.
- Aluminum:Dominant input across 9-12% silicon hypoeutectic formulations and A380/A383 commercial grades. Recyclability and strength-to-weight positioning sustain demand despite LME price volatility indexed into OEM contracts.
- Magnesium:AZ91D and AM60B alloys for seat frames, steering column brackets, and EV battery tray reinforcements where single-digit gram savings justify material cost premiums. Corrosion compatibility constraints limit substitution depth in multi-metal assemblies.
- Zinc:Zamak formulations for decorative and low-stress functional components.
- Copper:Limited to thermal management applications and electrical busbar housings.
Aluminum anchors volume throughput. Magnesium is climbing the fastest on EV lightweighting mandates.
Application:
Customer type splits between high-volume light-truck programs and emerging electric vehicle platforms with divergent casting specifications.
- Passenger Vehicles:Sedan and SUV platforms consuming the majority of transmission housings and engine block capacity. Mexican export plants serving US Midwest markets sustain this segment's scale.
- Electric Vehicles:Battery enclosures, motor end-caps, and thermal management housings requiring larger casting footprints and vacuum-assisted porosity control. OEMs are qualifying local suppliers to replace imported Asian battery trays.
- Commercial Vehicles:Heavy-duty transmission cases and differential housings with thicker wall sections.
- Two-wheelers:Small-displacement engine components and wheel castings for domestic motorcycle assembly.
Passenger Vehicles retains the volume base. Electric Vehicles is gaining share fastest on platform launch schedules.
End User:
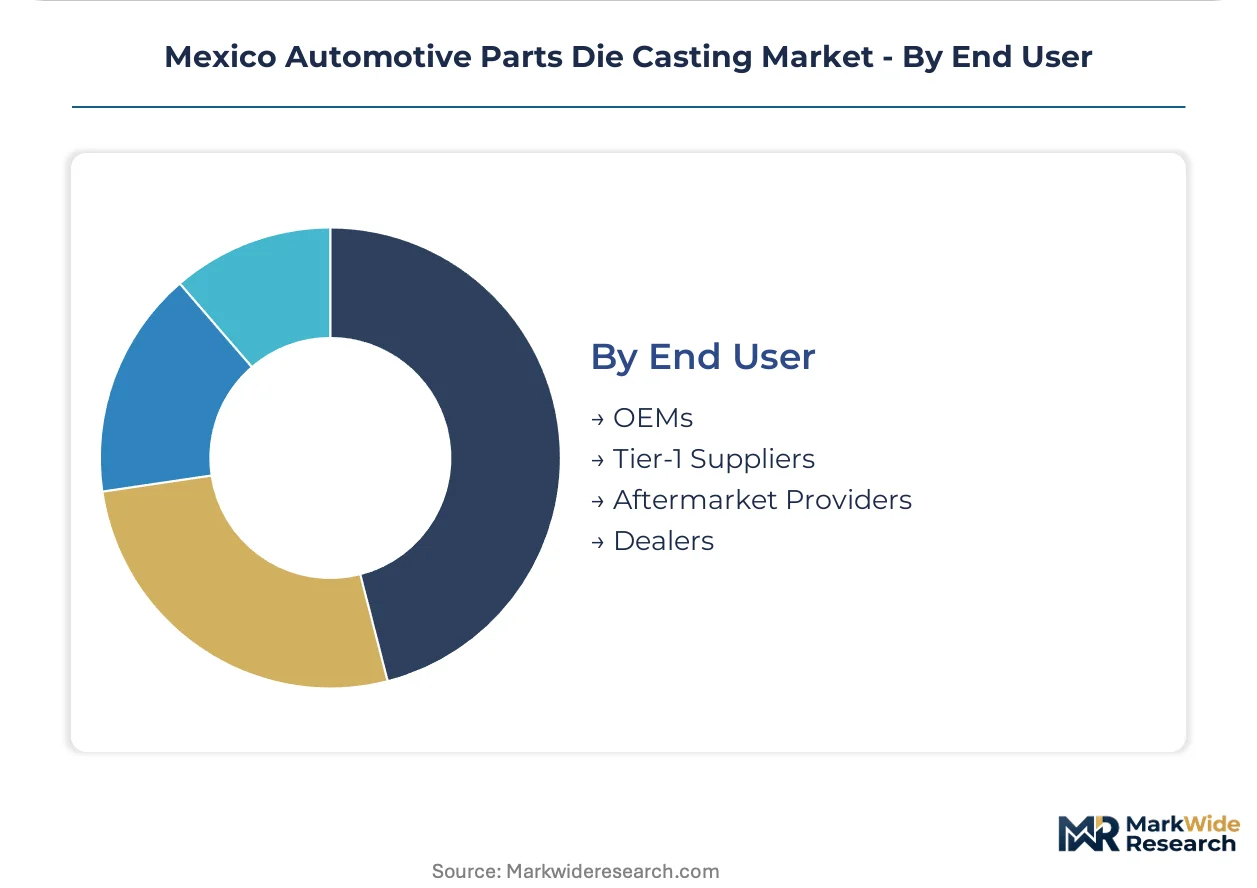
Supply concentration favors Tier-1 integrators with IATF 16949 certification, while aftermarket channels absorb non-conforming output and legacy tooling runs.
- OEMs:Direct supply relationships requiring co-location within 50 kilometers of assembly plants and real-time production sequencing. OEM consolidation around Guanajuato and Aguascalientes compresses supplier geography.
- Tier-1 Suppliers:Bosch, Continental, and Denso-tier integrators unbundling die-casting from final assembly. These intermediaries impose quarterly price reviews and dual-source requirements that strain foundry margins.
- Aftermarket Providers:Independent distributors sourcing non-warranty replacement parts.
- Dealers:Franchised service networks with limited direct casting procurement.
Tier-1 Suppliers mediate the majority of qualified volume. OEM direct sourcing is expanding most quickly as vertical integration pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams concentrate around three distinct manufacturing corridors, each shaping supplier qualification requirements and logistics contracts differently. Tier-1 die casters must co-locate within 50 kilometers of assembly plants or forfeit preferred supplier status.
Bajío Region
Guanajuato and Querétaro anchor the densest automotive cluster, with transmission housing and engine block demand flowing to Detroit Three export plants. NOM-001-SECRE traceability mandates filter informal foundries from OEM qualification cycles. Tier-1 suppliers including Nemak and Bocar Group maintain captive capacity in Silao and Apaseo el Grande to serve adjacent engine and transmission assembly operations.
Nuevo León
Monterrey's industrial base supports northern Mexico's heavy-truck and light-vehicle export platforms, with die casters specializing in high-pressure aluminum components for powertrain applications. SEMARNAT emissions protocols push foundries toward electric melting retrofits. The state's concentration of heat-treatment capacity in Apodaca and Santa Catarina creates tool steel fabrication bottlenecks for expanding die-casting operations.
Jalisco
Guadalajara's electronics-to-automotive manufacturing transition generates demand for precision magnesium castings in seat frames and steering components. The state's environmental regulator enforces particulate discharge limits that accelerate foundry consolidation. Tier-2 suppliers in El Salto and Tlaquepaque face pressure to achieve IATF 16949 certification or retreat to aftermarket channels.
Mexico City Metro
The capital's logistics infrastructure supports die-casting distribution to central Mexican OEM plants, though manufacturing migration to lower-cost corridors constrains local foundry investment. The Federal Economic Competition Commission monitors supplier concentration risks as major die casters consolidate capacity away from the metro area. Remaining operations focus on prototype and short-run specialty castings.
Northern Border States
Coahuila and Tamaulipas host legacy foundry operations serving cross-border supply chains, with Chihuahua's assembly plants driving demand for aluminum engine components. SEMARNAT's 2024 emissions update imposes continuous monitoring requirements on facilities above 500 tons annual throughput. Legacy gas-fired operations in Torreón and Monclova lack capital reserves for mandated baghouse and electric melting upgrades.
Mexico Automotive Parts Die Casting Market Competitive Landscape
Player mix skews toward vertically integrated aluminum specialists with captive smelting capacity and IATF 16949 certification. Three strategic archetypes dominate: integrated OEM-captive operations with in-house alloy supply, independent high-pressure specialists serving transmission and powertrain contracts, and magnesium-capable foundries targeting EV structural lightweighting. Competitive moves concentrate on geographic co-location with assembly plants and qualification for hybrid powertrain integration programs.
Within the integrated-captive tier, Nemak exemplifies the smelter-adjacent model through northern Mexico engine plant proximity. Gibbs Die Casting Group and Bocar Group occupy distinct specialization positions—high-pressure transmission expertise versus magnesium structural capability—each representing pathways for Tier-1 contract capture as OEMs dual-source ICE and PHEV variants. Sandhar Technologies Limited anchors the India-origin supplier presence, while Endurance Group and Ryobi Die Casting exemplify multi-national scale operations competing on qualification breadth rather than geographic concentration alone.
| Leading Market Players |
|---|
| Sandhar Technologies Limited |
| Gibbs Die Casting Group |
| Nemak |
| Empire Casting Co |
| Endurance Group |
| Dynacast |
| Ryobi Die Casting |
| Cascade Die Casting Group Inc |
| Bocar Group |
| Others |
Supply & Pricing Matrix
Capacity utilization above 85 percent in Guanajuato's die-casting cluster compresses price floors while amplifying bargaining power for IATF 16949-accredited foundries serving Detroit Three engine plants. This scale concentration enables qualified Tier-1 suppliers to index long-term contracts to LME aluminum spot-plus formulas with quarterly adjustment clauses, while informal competitors retreat to aftermarket channels with thinner margin structures.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate OEM supply agreements, with quarterly price reviews replacing annual negotiations as buyer consolidation intensifies. Price differentiation separates IATF 16949-certified foundries commanding premium piece-prices from uncertified competitors trapped in spot-market volatility. Pricing pressure stems from real-time aluminum index adjustments unbundled from tooling amortization schedules. Aftermarket distributors exhibit highest price sensitivity due to inventory holding costs and import substitution alternatives.
Supply Chain Analysis
Inbound logistics costs from Veracruz port congestion and container availability constraints on Asia-Mexico trade lanes inflate working capital cycles for tool steel and specialized alloy imports. Primary aluminum supply concentrates in Canada, Russia, and domestic Mexican smelters, while hardened mold fabrication draws from Germany, Japan, and Monterrey's heat-treatment cluster. Supply chain risk centers on single-source dependency for H13 tool steel subject to energy cost spikes. Distribution runs through Tier-1 integrator hubs co-located within 50 kilometers of OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat structure where NOM-001-SECRE traceability mandates and IATF 16949 certification timelines create switching costs that entrench qualified incumbents against informal competitors.
For Market Incumbents: Secure captive aluminum supply through backward integration into ingot production or long-term offtake agreements with Canadian smelters. Expand vacuum-assisted die-casting capacity in Querétaro to capture EV battery tray contracts before 2026 platform qualifications close. Certification investment represents the priority defensive lever against magnesium-capable entrants from Asia. For New Entrants and Emerging Players: Aftermarket remanufacturing services for legacy transmission housings present an under-served layer where IATF 16949 timelines do not constrain revenue recognition. Target Coahuila's legacy foundry base for distressed asset acquisition and SEMARNAT compliance retrofit. Go-to-market positioning should emphasize rapid prototype capability for EV motor end-caps bypassing Tier-1 procurement gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors magnesium-capable foundries with EV structural lightweighting qualifications over pure-play aluminum operators tethered to ICE powertrain decline. Five-to-ten year viability hinges on hybrid powertrain integration contracts spanning dual-source ICE and PHEV variants. Watch for NEV-specific casting standards emerging from Mexico's energy-transition regulatory agenda as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Smelting | Insulates margin predictability against LME volatility for long-term OEM contracts. |
| Vacuum-Assisted Die-Casting Expansion | Enables qualification for 2.5-millimeter wall battery trays in Guanajuato EV programs. |
| Magnesium Alloy Capability Addition | Captures gram-critical seat frame and steering column contracts from incumbent aluminum specialists. |
| IATF 16949 Certification Fast-Track | Filters informal competitors from OEM qualification cycles in Nuevo León corridor. |
| Co-Location Within 50km of Assembly Plants | Satisfies Tier-1 logistics mandates in Aguascalientes and San Luis Potosí clusters. |
Research Methodology
Cross-validation between OEM procurement director interviews and SEC 10-K filings from listed Tier-1 suppliers anchors the qualitative findings on contract structures and capacity allocation. Primary fieldwork encompassed die-casting plant managers, OEM platform engineers, aftermarket distribution heads, and SEMARNAT compliance officers across Guanajuato, Nuevo León, and Querétaro. Secondary sources integrated vehicle production databases, IHS Markit registration data, LME aluminum price series, and Mexican customs trade records. Bottom-up segment sizing triangulated against top-down OEM demand modeling.
Sensitivity analysis tested volume and value outputs across aluminum price scenarios, EV adoption trajectories, and regulatory compliance cost assumptions over the projection horizon. Segmentation dimensions modeled include product type, material grade tier, propulsion architecture, and regional production cluster. CAGRs derived from historical production trends, OEM platform launch schedules, and content-per-vehicle assumptions for hybrid and battery-electric architectures. Forecast inputs incorporated SEMARNAT emissions retrofit timelines and NOM-001-SECRE mechanical property traceability requirements.
Forecasts assume regulatory continuity in Mexican federal environmental and automotive safety regimes; material policy shifts would require re-modeling. Aluminum price volatility, IATF 16949 certification delays, and EV platform qualification failures represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Small Engine Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
France Automotive Actuators Market