
 Americas MAP Market | 2026-2036
Americas MAP Market Size, Share, and Industry Trends Forecast 2026-2036
Americas MAP Market Outlook
Brazil is rewriting regional supply dynamics as the country expands pathology infrastructure across its public hospital network. Esri leverages geospatial analytics to map diagnostic access gaps, while HERE Technologies anchors logistics optimization for equipment distribution chains. Maxar Technologies competes through high-resolution imaging integration into digital pathology workflows.
Microtome-based automated tissue preparation systems encompass mechanical slicing instruments, embedding centers, and slide staining modules engineered to micron-level precision for histopathological analysis. These systems process biopsy specimens into diagnostic-ready sections for oncology and neurology applications. Immunohistochemistry segments dominate current revenue pools given established reimbursement codes, while digital pathology platforms represent the fastest-expanding technology category as laboratories transition from analog microscopy. Automation segments concentrate margin capture among integrated system vendors rather than discrete component suppliers.
FDA 510(k) pathways and CLIA laboratory certification requirements shape product development timelines and commercial access across the United States. Brazil's ANVISA and Health Canada regulate import standards and clinical validation protocols for tissue diagnostic equipment entering their respective jurisdictions. Stakeholders must monitor evolving digital pathology reimbursement decisions and cross-border harmonization efforts between North and South American regulators.
Market Dynamics
Digital pathology platforms are compressing traditional histopathology workflows as laboratories across the Americas abandon analog microscopy for whole-slide imaging systems. This technology shift is redrawing equipment procurement priorities and vendor competitive boundaries.
Growth Catalysts
- FDA 510(k) pathway compression:Expedited clearance timelines for digital pathology software are accelerating manufacturer commercialization schedules. Device developers now target 12-18 month validation cycles rather than multi-year PMA processes.
- Brazil public hospital network expansion:Federal infrastructure investments are creating diagnostic center procurement waves across state health systems. ANVISA import standard harmonization is reducing equipment entry friction.
- Immunohistochemistry reimbursement stability:Established CPT coding in US academic medical centers sustains capital allocation toward automated staining platforms. Oncology pathology volumes anchor equipment utilization rates.
Market Restraints
- Optical component supply concentration:German and Japanese precision lens manufacturers control critical supply nodes for high-resolution imaging modules. Tariff exposure on imported optical assemblies elevates landed equipment costs.
- CLIA laboratory certification complexity:US state-level inspection variability creates compliance timeline uncertainty for multi-site laboratory networks. Validation documentation requirements extend facility commissioning periods.
- Technical workforce scarcity:Certified histotechnologist training program completion rates lag equipment installation velocity. Specialized microtome operation expertise concentrates in coastal metropolitan labor markets.
Strategic Opportunities
- Mexico border-state diagnostic corridor:Maquiladora-adjacent medical infrastructure investments are creating equipment demand clusters in Baja California and Chihuahua. Cross-border telepathology networks leverage US specialist access.
- AI-powered image analysis convergence:Machine learning classification algorithms are integrating with whole-slide scanners for automated preliminary reads. Regulatory sandbox programs in Health Canada are accelerating clinical validation pathways.
- Remote service channel development:Predictive maintenance platforms using equipment telemetry are displacing scheduled technician visits. Cloud-connected staining systems enable vendor-managed reagent inventory optimization.
Industry Challenges
- Digital-legacy system integration complexity:Laboratory information management system interoperability gaps force custom middleware development. Multi-vendor environments create data format standardization friction.
- Capital intensity of full-workflow automation:Integrated tissue processing lines require seven-figure facility investments. Mid-size independent laboratories face financing constraints for comprehensive platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas MAP Market |
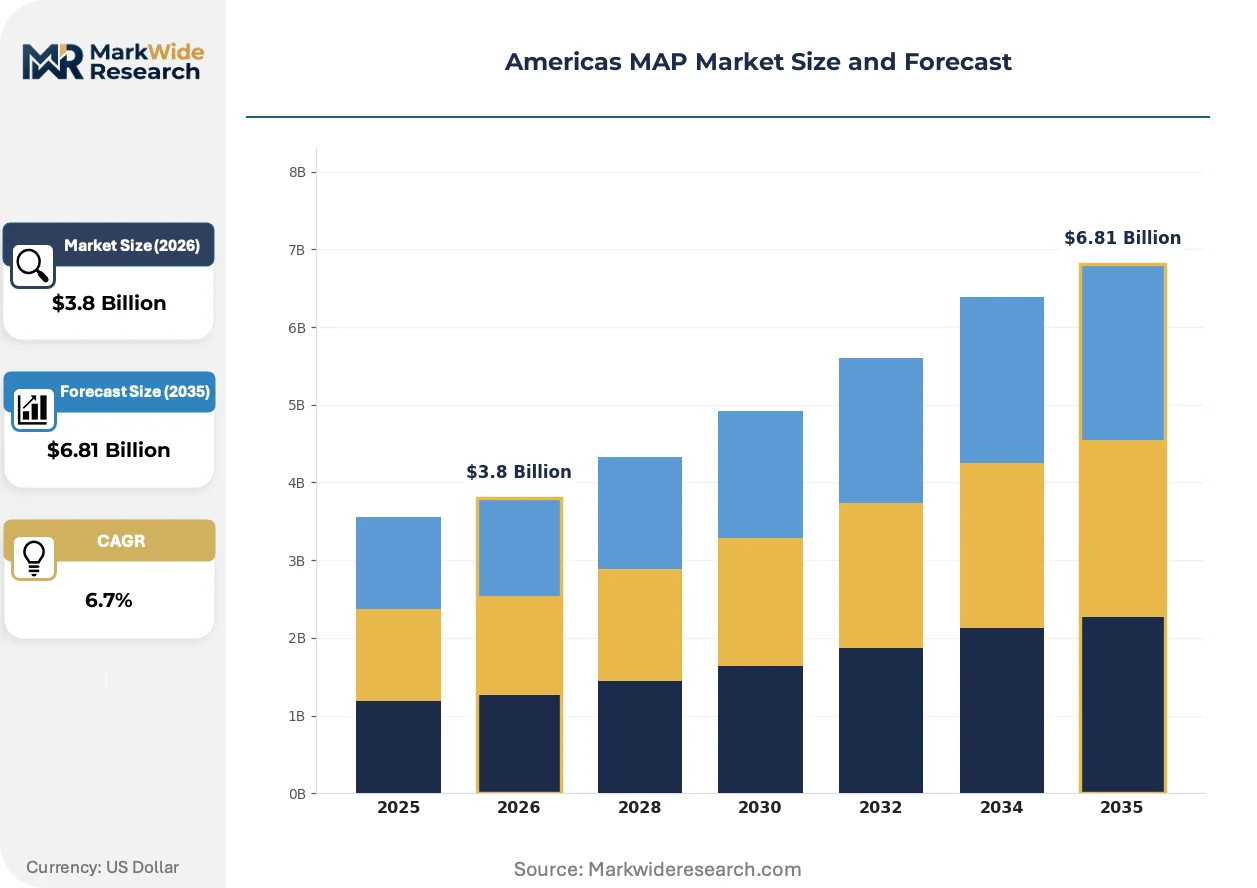
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microtome, Slide Stainer, Tissue Processors, Embedding Centers Therapy Area: Oncology, Neurology, Cardiovascular, Infection Control End User: Hospitals, Research Laboratories, Diagnostic Centers, Educational Institutions Technology: Immunohistochemistry, Fluorescence Microscopy, Digital Pathology, Automation |
| Companies Covered | Esri, HERE Technologies, Google, Apple, TomTom, Maxar Technologies, Nearmap, Intermap Technologies, Digital Map Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas MAP Market Strategic Shifts
Whole-slide imaging systems are restructuring diagnostic laboratory economics by eliminating physical slide handling and enabling remote specialist consultation. Three concurrent developments are reshaping equipment specifications and vendor value propositions.
Cloud-native pathology platforms are virtualizing slide storage and computational analysis workflows. Academic medical centers in the US Northeast corridor are deploying these systems at scale, replacing on-premise server infrastructure. This architecture is virtualizing capital expenditure models toward subscription-based operational structures while compressing IT maintenance burdens.
FDA digital health software precertification pilots are streamlining algorithm-based diagnostic tool validation. Manufacturers now prototype iterative image analysis updates without full 510(k) resubmission for each modification. Pathology AI modules face accelerated review timelines, particularly for oncology biomarker quantification applications.
Consolidated procurement by multi-site laboratory networks is displacing independent equipment purchasing decisions. Quest Diagnostics and LabCorp-scale operators now negotiate enterprise-wide platform standardization. This concentration is most visible in Texas and Florida metropolitan markets where regional laboratory rollups dominate volume aggregation.
Americas MAP Market Segmentation
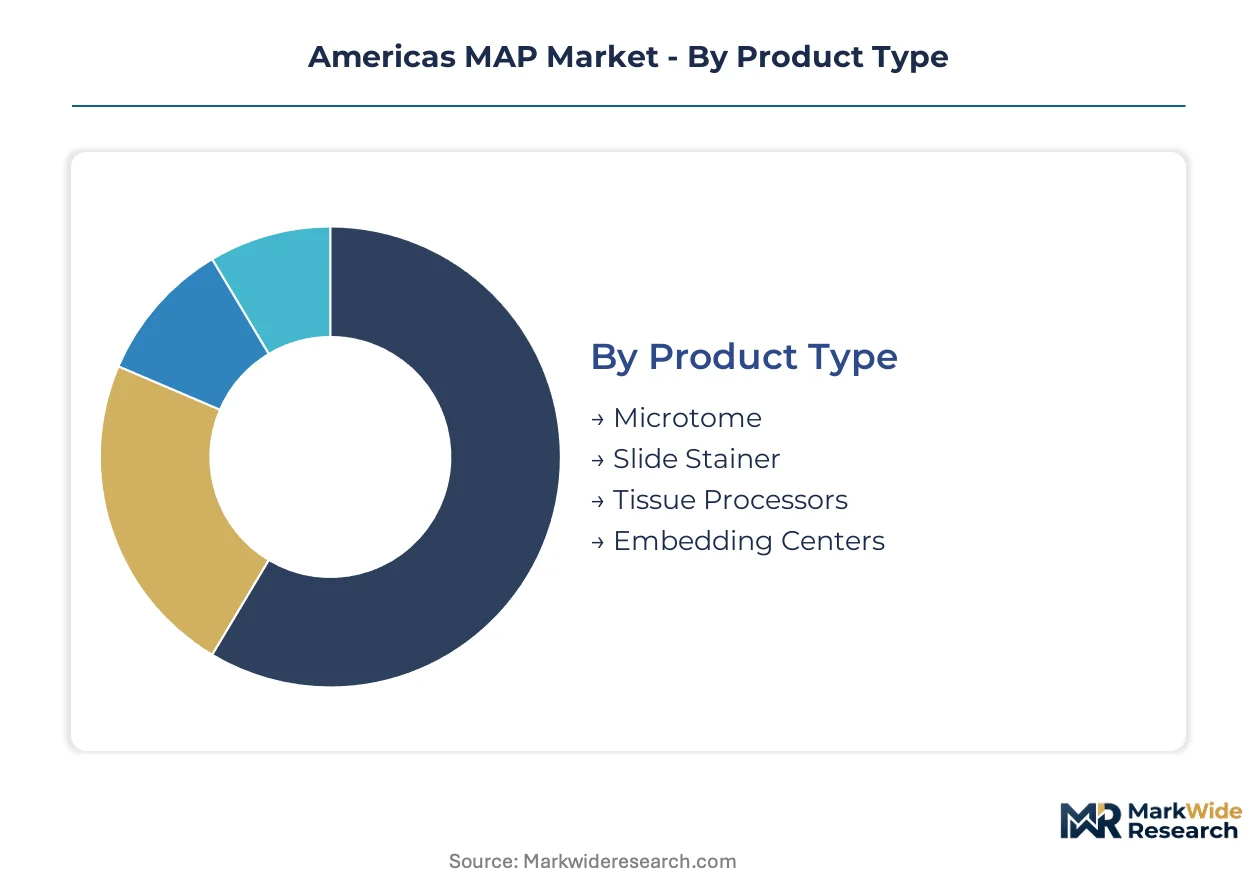
Segmentation in the Americas MAP Market reveals distinct procurement rhythms and margin profiles across equipment categories. Laboratories allocate capital differently based on workflow integration depth and reimbursement certainty.
Product Type:
Cycle times vary sharply: consumable-adjacent equipment turns over fastest while capital-intensive integrated systems depreciate over extended horizons.
- Microtome:Mechanical slicing instruments engineered to micron-level precision for tissue sectioning. Academic medical centers in the US Northeast corridor drive replacement demand as aging manual units face obsolescence against automated alternatives.
- Slide Stainer:Automated staining modules processing diagnostic-ready sections with reagent precision. Brazil's public hospital network expansion concentrates procurement waves for high-throughput units serving oncology pathology volumes.
- Tissue Processors:Specimen fixation and dehydration systems preparing samples for embedding. Mid-size independent laboratories face financing constraints for comprehensive platform upgrades.
- Embedding Centers:Paraffin block formation stations completing specimen preparation workflows. Regional laboratory rollups in Texas and Florida metropolitan markets negotiate enterprise-wide standardization.
Microtome dominates installed base. Slide Stainer is where expansion concentrates.
Therapy Area:
Reimbursement density shapes capital allocation: established CPT coding accelerates equipment deployment while emerging applications require validation investment.
- Oncology:Cancer pathology workflows commanding the largest equipment footprint across the Americas. Immunohistochemistry reimbursement stability sustains capital allocation toward automated staining platforms in US academic medical centers.
- Neurology:Nervous system tissue analysis requiring specialized sectioning protocols. Digital pathology platforms are compressing traditional histopathology workflows for remote specialist consultation.
- Cardiovascular:Cardiac tissue specimen processing for structural and ischemic disease assessment. Health Canada regulatory sandbox programs accelerate clinical validation pathways for AI-powered image analysis convergence.
- Infection Control:Pathogen identification and tissue response characterization for infectious disease management. Cross-border telepathology networks leverage US specialist access for Mexico border-state diagnostic corridors.
Oncology anchors revenue concentration. Digital-integrated neurology applications are climbing the fastest.
End User:
Customer scale determines procurement modality: consolidated networks command volume discounts while independent operators face financing constraints.
- Hospitals:Integrated health systems with embedded pathology departments requiring full-workflow automation. Capital intensity of comprehensive platform upgrades limits mid-size independent laboratory participation.
- Research Laboratories:Academic and commercial R&D facilities prioritizing experimental flexibility over throughput. Cloud-native pathology platforms virtualize capital expenditure models toward subscription-based operational structures.
- Diagnostic Centers:Standalone reference laboratories aggregating specimen volumes across physician networks. ANVISA import standard harmonization reduces equipment entry friction for Brazil's state health systems.
- Educational Institutions:Training programs producing certified histotechnologists for specialized microtome operation. Technical workforce scarcity concentrates expertise in coastal metropolitan labor markets.
Hospital networks dominate installed base. Diagnostic Centers capture expansion investment.
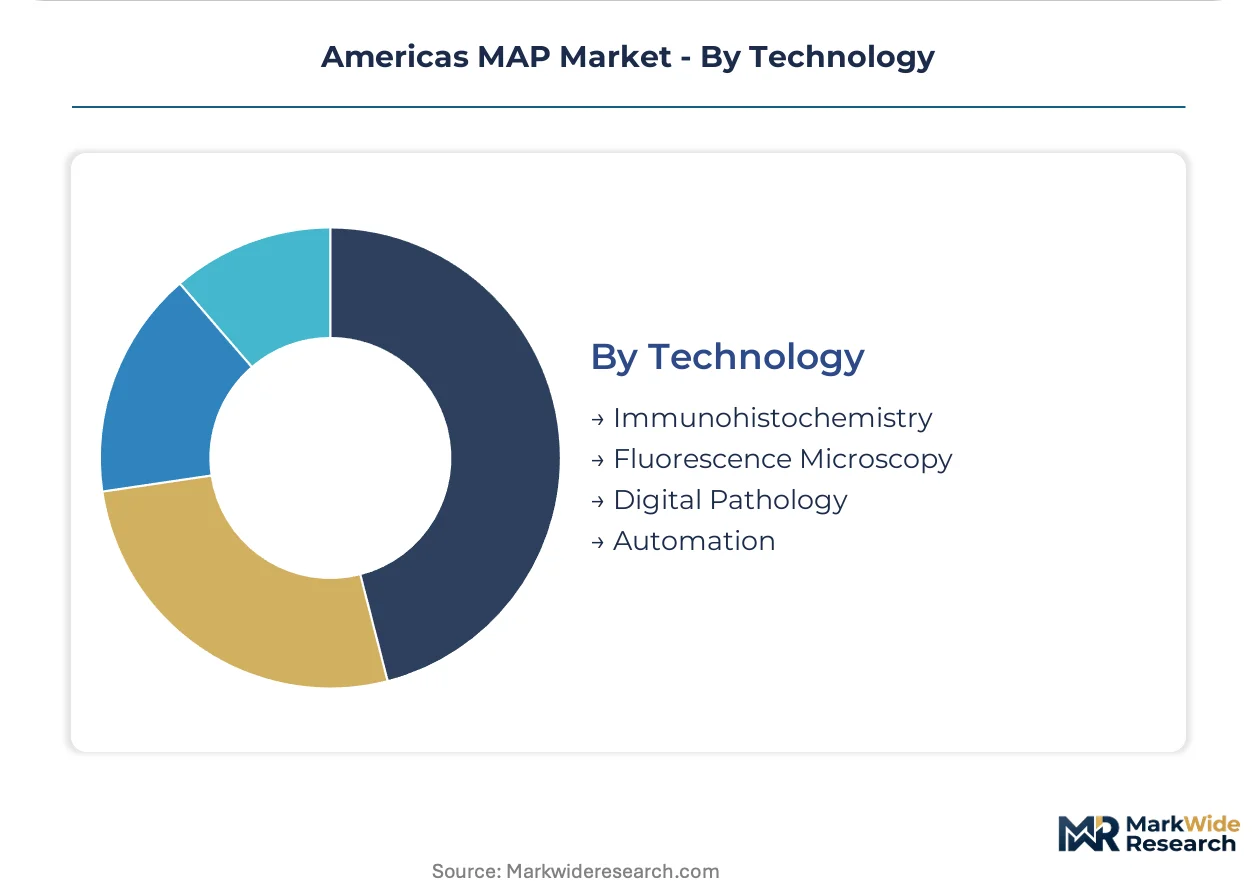
Technology:
Maturity gradients separate established reimbursement pathways from emerging platform transitions requiring regulatory navigation.
- Immunohistochemistry:Antibody-based protein detection systems with established procedural coding. Established CPT coding sustains capital allocation toward automated staining platforms.
- Fluorescence Microscopy:Specialized imaging for genetic and molecular marker visualization. Optical component supply concentration in German and Japanese precision lens manufacturers elevates landed equipment costs.
- Digital Pathology:Whole-slide imaging systems enabling remote consultation and AI integration. FDA 510(k) pathway compression accelerates manufacturer commercialization schedules.
- Automation:Robotic specimen handling and integrated workflow management. Predictive maintenance platforms using equipment telemetry displace scheduled technician visits.
Immunohistochemistry dominates installed base. Digital Pathology represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor North American commercialization velocity while ANVISA harmonization accelerates Brazilian procurement. Canada and Mexico present distinct regulatory and infrastructure expansion profiles across the forecast window.
United States
Academic medical centers in the US Northeast corridor cluster drive replacement demand for aging manual microtomes against automated alternatives. FDA 510(k) pathway compression reduces validation cycles to 12-18 months for digital pathology software developers. Boston and New York metropolitan markets concentrate enterprise procurement negotiations for multi-site laboratory networks.
Brazil
Federal infrastructure investments across state health systems create diagnostic center procurement waves for high-throughput slide stainers. ANVISA import standard harmonization reduces equipment entry friction for tissue diagnostic equipment. São Paulo and Rio de Janeiro anchor the public hospital network expansion with concentrated equipment installation velocity.
Canada
Health Canada regulatory sandbox programs accelerate clinical validation pathways for AI-powered image analysis convergence. CLIA-equivalent laboratory certification requirements shape multi-site network compliance timelines. Ontario and Quebec concentrate cloud-native pathology platform deployment at academic medical centers.
Mexico
Maquiladora-adjacent medical infrastructure investments in Baja California and Chihuahua create equipment demand clusters. Cross-border telepathology networks leverage US specialist access for border-state diagnostic corridors. Mexico City metropolitan laboratories face financing constraints for comprehensive platform upgrades.
Americas MAP Market Competitive Environment
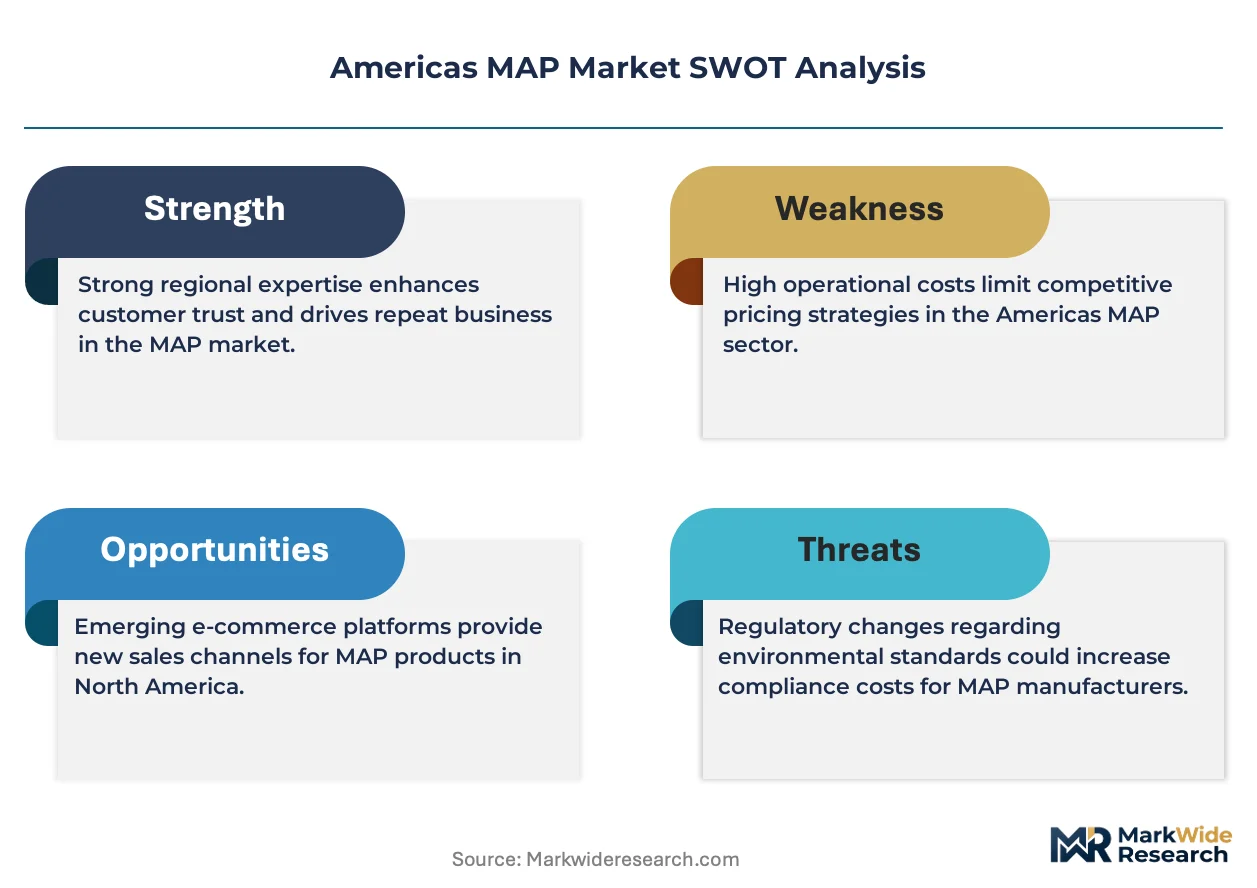
Capability concentration sits with one tier; scale advantage sits with another. The Americas MAP Market structures around integrated system vendors capturing margin from discrete component suppliers. Three archetypes dominate: geospatial analytics platforms, high-resolution imaging integrators, and logistics optimization engines. Consolidation pressures favor enterprise-wide platform standardization negotiated by multi-site networks, while independent laboratories face procurement constraints.
Among geospatial and imaging specialists, Esri, Maxar Technologies, and HERE Technologies occupy distinct positioning vectors. Esri exemplifies the geospatial analytics archetype through mapping diagnostic access gaps. Maxar Technologies anchors high-resolution imaging integration into digital pathology workflows. HERE Technologies represents logistics optimization for equipment distribution chains. Each sits within a capability tier rather than competing directly on identical specifications.
| Leading Market Players |
|---|
| Esri |
| HERE Technologies |
| Apple |
| TomTom |
| Maxar Technologies |
| Nearmap |
| Intermap Technologies |
| Digital Map Products |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on German and Japanese precision lens assemblies determines both tiered pricing spreads across equipment categories and the regional distribution of supplier relationships. Equipment vendors absorb elevated landed costs on high-resolution imaging modules or pass them through to buyers, compressing margins on mid-range systems while premium integrated platforms maintain pricing power through bundled service contracts.
Pricing Analysis
Price spreads between US Northeast corridor academic medical centers and Brazil's public hospital networks reflect divergent procurement modalities and service bundling expectations. Equipment pricing stratifies across premium, standard, and economy tiers based on automation depth and FDA 510(k) certification status. Cost compression in standard-tier microtomes is intensifying because ANVISA-harmonized import standards expose Brazilian buyers to Asian manufacturing alternatives. Mid-size independent laboratories exhibit highest price sensitivity, while consolidated multi-site networks in Texas and Florida leverage volume aggregation for preferential terms.
Supply Chain Analysis
Export-control regimes on high-precision optical components limit flows from German and Japanese manufacturers to equipment integrators serving the Americas. Supply concentration in these two countries for imaging lenses, coupled with South Korean sensor fabrication and Chinese mechanical subassembly production, creates multi-node dependency. Single-source vulnerability concentrates in micron-level lens grinding capabilities. Distribution runs through authorized dealer networks with regional service footprints rather than direct manufacturer-to-laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas MAP Market sits at a cyclical recovery phase driven by Brazil's federal diagnostic infrastructure investment wave. Equipment replacement cycles and regulatory pathway compression create favorable conditions for strategic repositioning.
For Market Incumbents: Pre-empt margin erosion in discrete component segments by deepening backward integration into optical module assembly. Consolidate service channel density in the US Northeast corridor before emerging platform vendors establish predictive maintenance relationships. ANVISA regulatory harmonization accelerates Brazilian procurement timelines, rewarding early capacity positioning in São Paulo and Rio de Janeiro metropolitan markets. For New Entrants and Emerging Players: Mexico's Baja California and Chihuahua border-state diagnostic corridors remain underpenetrated by integrated workflow vendors despite maquiladora-adjacent medical infrastructure investments. White-space opportunities concentrate in cloud-native pathology platforms for mid-size independent laboratories excluded from enterprise procurement negotiations. A telepathology-enabled go-to-market angle leverages cross-border US specialist access without requiring full CLIA laboratory certification. For Investors and Strategic Acquirers: The market sits at an expansion phase that favors platform consolidators over point-solution specialists. Long-term viability over the next decade hinges on capturing recurring revenue streams from subscription-based digital pathology deployments. Acquisition targets should demonstrate Health Canada regulatory sandbox participation or FDA digital health precertification pilot engagement. The signal to watch is Health Canada AI validation pathway acceleration as an inflection indicator for algorithm-based diagnostic tool commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Pathway Compression | Accelerated clearance timelines reduce manufacturer validation cycles to 12-18 months. |
| Brazil ANVISA Harmonization | Import standard alignment reduces equipment entry friction for state health system procurement. |
| Cloud-Native Platform Deployment | Academic medical centers in Ontario and Quebec replace on-premise server infrastructure. |
| Predictive Maintenance Channel Development | Equipment telemetry displaces scheduled technician visits for staining system vendors. |
| Cross-Border Telepathology Network | US specialist access extends into Mexico border-state diagnostic corridors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pathology department heads, diagnostic center procurement managers, biomedical equipment service technicians, and GPO contracts administrators. Secondary validation drew from FDA 510(k) clearance databases, ANVISA import registration filings, Health Canada medical device licenses, and CMS Medicare reimbursement schedules. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates across product categories.
Calibration against historical procurement cycles and regulatory approval timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type automation depth, therapy area reimbursement density, end-user scale tier, and technology maturity gradient. CAGRs were derived from equipment replacement velocity assumptions and digital pathology platform penetration curves. Forecast inputs incorporated CLIA laboratory certification completion rates and certified histotechnologist training program throughput.
Practitioners should monitor FDA digital health precertification pilot expansion and ANVISA import standard evolution for early signals of timeline compression or friction. Forecasts reflect documented assumptions about regulatory pathway efficiency and workforce training capacity. Material shifts in optical component tariff exposure or CLIA state-level inspection variability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Automotive MRO Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
France Car Rental Market
Automotive Services
GCC Car Wash Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Car Subscription Market