
 Automotive E-Tailing Market | 2026-2036
Automotive E-Tailing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive E-Tailing Market Analysis
Automotive e-commerce talent shortages in logistics coordination and digital merchandising is rotating toward platform engineering and data science roles, reshaping how online auto parts retailers scale operations. Amazon.com Inc. leverages its fulfillment network to dominate same-day and next-day delivery expectations for aftermarket components. Robert Bosch GmbH anchors its e-tailing presence through proprietary diagnostic tools that integrate with its direct-to-workshop parts platform. AutoZone Inc. competes by sustaining dense brick-and-click coverage that positions its website as an extension of local store inventory.
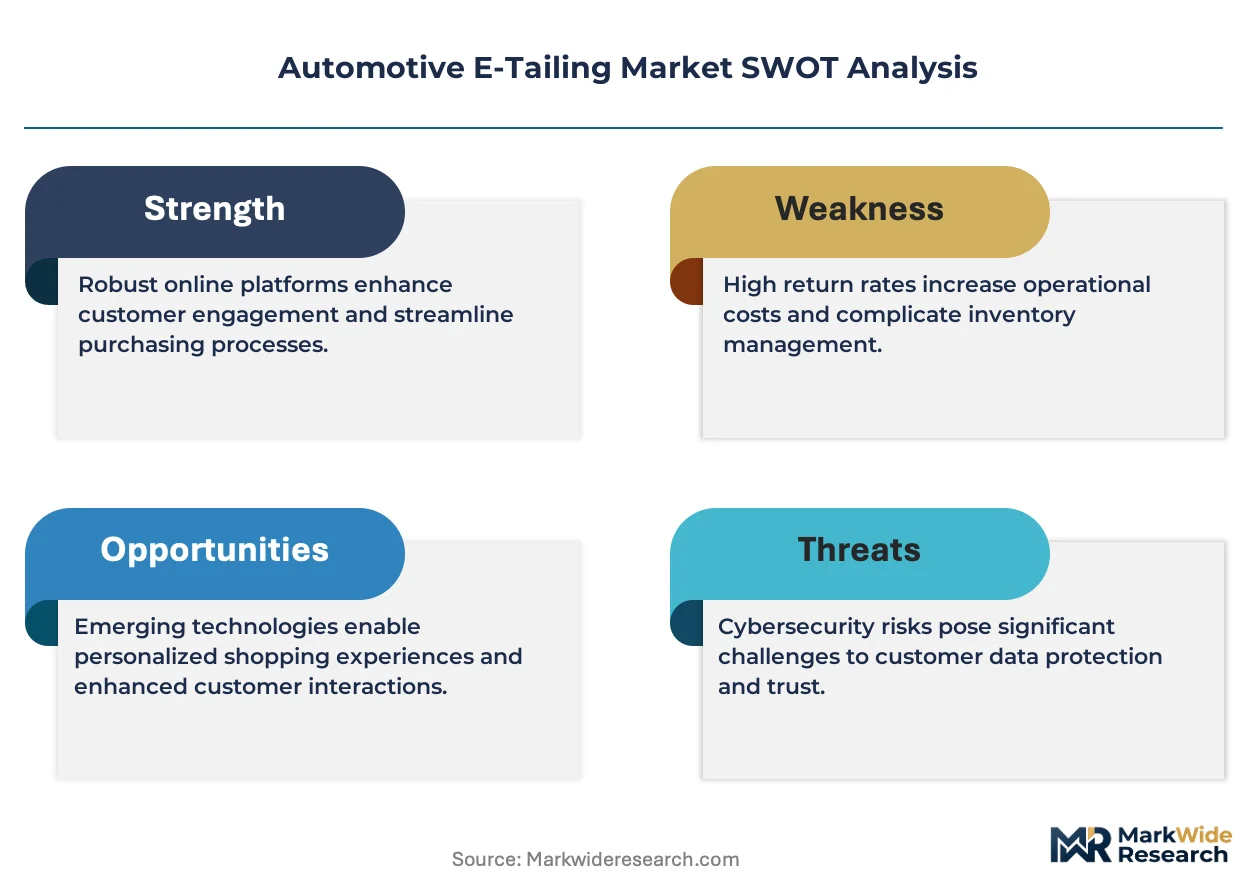
Automotive e-tailing denotes the digital sale of vehicles, parts, accessories, and related services through internet-based platforms, typically requiring real-time inventory synchronization, VIN-specific fitment verification, and secure payment gateways to complete transactions remotely. Its primary commercial purpose is to disintermediate traditional dealership and parts-counter channels while expanding geographic reach for both OEM and aftermarket suppliers. Aftermarket Products within the Service Type dimension generates outsized margin pools due to repeat purchase frequency and lower price transparency versus new vehicle sales. Online Marketplace channels in the Sales Channel segment capture the highest transaction volumes by aggregating third-party sellers, though Direct Website platforms retain superior customer lifetime value through loyalty programs and subscription services.
The EPA enforces emissions compliance for aftermarket catalytic converters and engine components sold through digital channels, while NHTSA mandates recall and safety defect disclosure for all vehicle listings. The EU Green Deal's carbon-border adjustments and F-Gas Regulation constrain cross-border shipment of certain refrigerant-based automotive climate components, redirecting procurement toward certified regional suppliers. Stakeholders must monitor evolving platform liability frameworks that increasingly hold marketplaces accountable for counterfeit parts and odometer fraud rather than treating them as neutral intermediaries.
Market Dynamics
Platform consolidation is compressing margins for standalone automotive e-commerce operators as marketplace aggregators capture transaction economics through captive logistics networks and unified payment infrastructure.
Growth Catalysts
- VIN-specific fitment engines:Machine learning models parsing vehicle identification data are eliminating return rates for complex parts categories, particularly in brake and suspension segments where dimensional tolerance errors previously drove 15-20% of disputes.
- EU Green Deal emissions mandates:Fleet operators under binding decarbonization timelines are accelerating procurement of electric drivetrain components through digital channels to meet compliance windows and avoid penalty structures.
- Germany:Dense automotive supplier clustering around Stuttgart and Munich enables same-day fulfillment for aftermarket inventory, creating network effects that pull adjacent Central European demand into German-platform orbits.
Market Restraints
- Cross-border refrigerant logistics:The EU F-Gas Regulation imposes strict quota tracking on climate-system components, fragmenting inventory pools and forcing regional warehousing duplication that inflates working capital requirements.
- Steel and aluminum input volatility:Exhaust system and wheel rim categories face margin compression when commodity prices spike, with e-tailers unable to pass through costs immediately due to price-transparency tools.
- Proprietary diagnostic integration:Workshop management systems from incumbent suppliers lock parts procurement into closed ecosystems, creating switching costs that limit platform migration for independent repair shops.
Strategic Opportunities
- Subscription-based maintenance bundles:Predictive algorithms enabling scheduled parts delivery before failure events are capturing recurring revenue streams from commercial fleet managers seeking to eliminate unscheduled downtime.
- India:Low dealership penetration in tier-two and tier-three cities is creating first-mover advantages for platforms offering vernacular-language interfaces and cash-on-delivery options for two-wheeler and entry-level passenger vehicle segments.
- Used vehicle remarketing platforms:Digital auction infrastructure connecting lease-return inventory directly to independent dealers is disintermediating traditional wholesale channels and capturing documentation-fee revenue.
Industry Challenges
- Automotive data science talent scarcity:Platforms struggle to hire engineers capable of building real-time inventory synchronization across incompatible dealer management systems and legacy warehouse software.
- Recall disclosure compliance:NHTSA mandates require instantaneous flagging of safety-defect listings, demanding automated VIN cross-referencing that many marketplace operators have not yet deployed at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive E-Tailing Market |
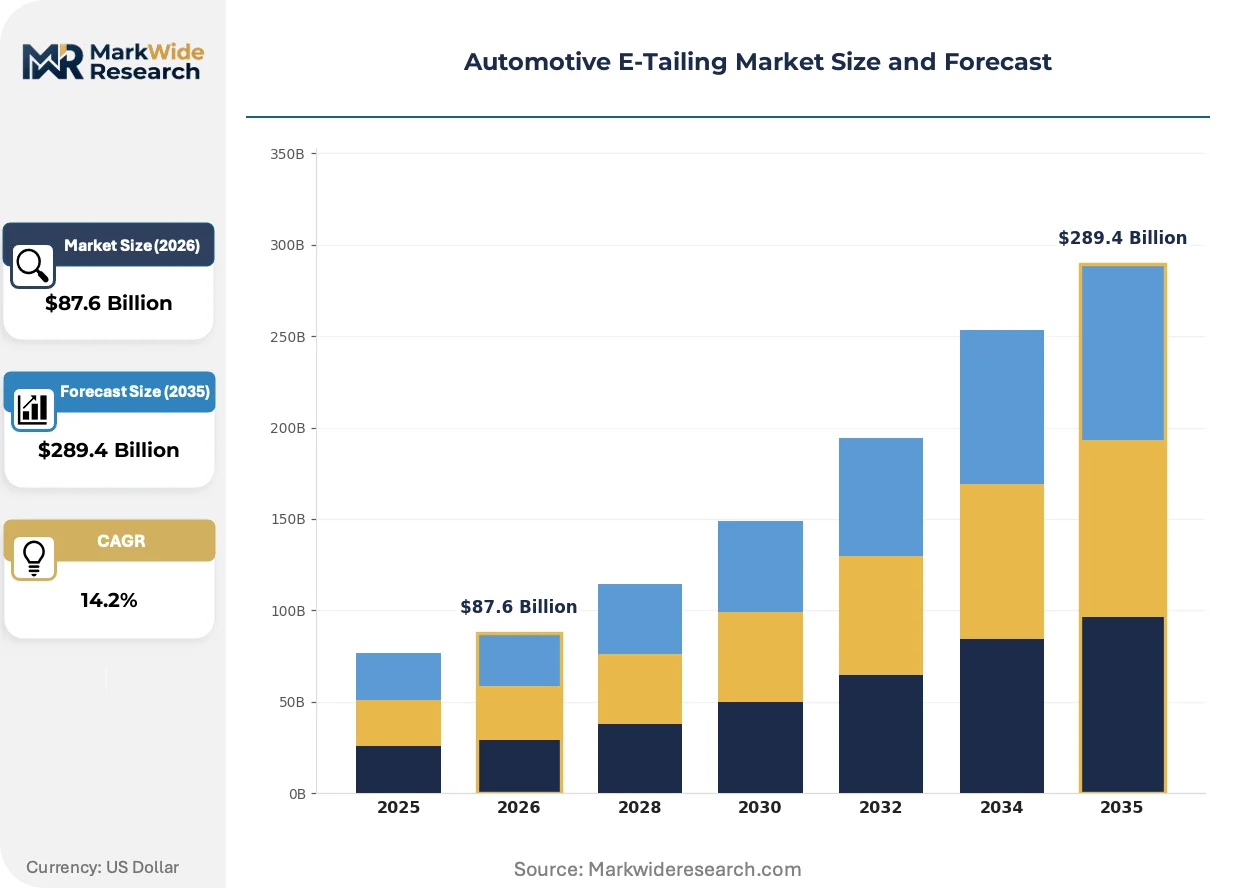
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Trucks, Motorcycles Customer Type: Individual Consumers, Fleets, Corporations, Dealerships Sales Channel: Online Marketplace, Direct Website, Mobile App, Aggregators Service Type: New Vehicle Sales, Used Vehicle Sales, Financing Options, Aftermarket Products |
| Companies Covered | O’Reilly Automotive Inc., Alibaba Group Holding Ltd, Amazon.com Inc., Robert Bosch GmbH, Wal-Mart Stores Inc., AutoZone Inc., eBay Inc., Continental AG, Advance Auto Parts Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive E-Tailing Market Emerging Trajectories
Artificial intelligence is restructuring how automotive e-commerce platforms verify compatibility, price dynamically, and fulfill orders, compressing the gap between digital transaction and physical delivery.
Generative AI-powered fitment verification is displacing static lookup tables and manual customer service interventions. Fleet procurement teams and independent workshops are adopting these tools within eighteen-month replacement cycles for their parts sourcing systems. The technology is displacing traditional catalog-based search models and compressing the competitive advantage of incumbents with legacy database investments.
The EU AI Act's risk-classification framework for automated decision-making systems is imposing documentation burdens on pricing algorithms used by major platforms. Automotive e-tailers must now maintain audit trails for dynamic pricing logic affecting consumer-facing transactions. Aftermarket parts marketplaces operating across Germany, France, and the Netherlands are restructuring their machine-learning operations to meet conformity assessment requirements before enforcement deadlines.
Workshop buyers are consolidating supplier relationships around platforms offering integrated diagnostic-to-procurement workflows, abandoning fragmented multi-vendor sourcing. Independent repair shops in Germany and the United Kingdom are migrating toward single-platform contracts that bundle technical support with parts availability guarantees. This concentration is most visible in emissions-system and advanced driver-assistance categories where technical complexity demands vendor intimacy.
Automotive E-Tailing Market Segmentation
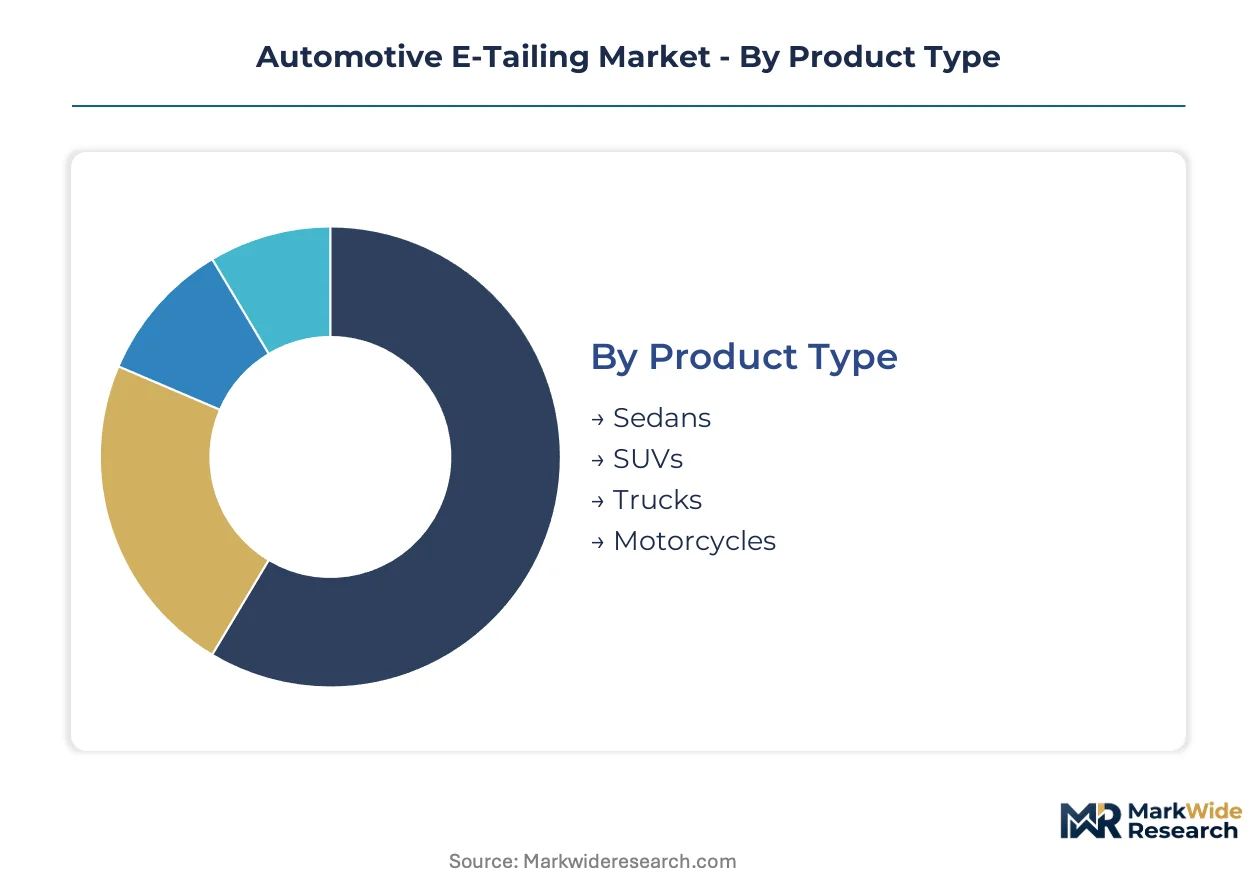
Segmentation in automotive e-tailing reveals divergent logistics requirements and margin structures across transaction types. Product dimensions dictate fulfillment infrastructure, while customer categories determine payment terms and platform interface complexity.
Product Type:
Sedans and SUVs dominate domestic digital transactions, while trucks and motorcycles show stronger cross-border velocity into adjacent Central European markets.
- Sedans:Standardized dimensions enable automated carrier assignment and reduced shipping-quote friction. Fleet replacement cycles in Germany concentrate bulk procurement through direct manufacturer portals with configured delivery windows.
- SUVs:Higher average transaction values justify white-glove delivery services and extended return windows. Consumer preference for specification customization pulls demand toward configurator-enabled direct websites rather than marketplace aggregation.
- Trucks:Commercial registration requirements and cab-chassis separation create documentation complexity that favors established dealer networks with compliance expertise.
- Motorcycles:Seasonal demand spikes and lower price points align with mobile-first discovery patterns and impulse-driven accessory attachment.
Sedans hold the largest share; momentum sits with SUVs as electrification expands model ranges and online configuration tools mature.
Customer Type:
Cost-tier segmentation separates high-touch corporate procurement from self-service individual transactions, with fleet operators occupying the premium service tier.
- Individual Consumers:Price transparency tools and financing calculators dominate the purchase journey. German consumers show highest digital closure rates due to established trust in remote vehicle transactions.
- Fleets:Binding EU emissions deadlines accelerate procurement of electric drivetrain components through digital channels. Volume commitments unlock dynamic pricing algorithms and priority fulfillment slots.
- Corporations:Procurement departments demand consolidated invoicing and telematics integration, favoring platforms with enterprise resource planning connectors.
- Dealerships:Inventory sourcing for used vehicle lots drives auction-platform participation, with documentation-fee revenue capturing margin from wholesale disintermediation.
Fleets hold the largest share; momentum sits with individual consumers as VIN-specific fitment engines reduce return anxiety.
Sales Channel:
Application-based segmentation distinguishes discovery-heavy marketplaces from transaction-optimized direct channels, with mobile interfaces capturing the steepest expansion trajectory.
- Online Marketplace:Third-party aggregation generates highest transaction volumes through competitive price visibility. Amazon's fulfillment network sets same-day delivery expectations for aftermarket components.
- Direct Website:OEM and large aftermarket suppliers retain superior customer lifetime value through subscription programs and loyalty point accumulation.
- Mobile App:Push-notification-driven promotions and one-tap reordering capture emergency parts procurement from roadside breakdown scenarios.
- Aggregators:Price-comparison engines with minimal inventory risk concentrate on lead-generation fees from financing and insurance attachments.
Online Marketplace holds the largest share; momentum sits with Mobile App as workshop buyers adopt smartphone-native procurement workflows.
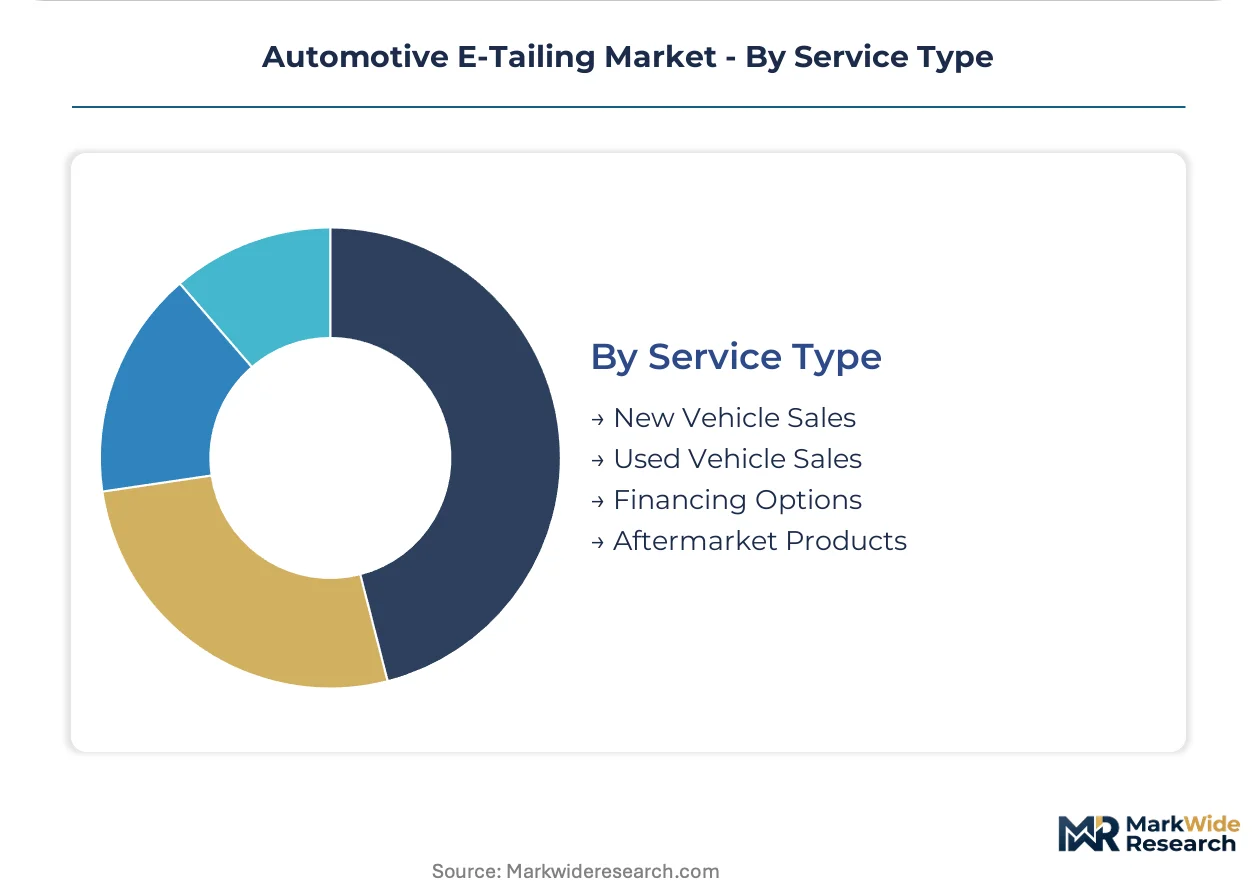
Service Type:
Maturity-based segmentation contrasts established new vehicle transactions with emerging digital formats for used inventory and predictive maintenance bundles.
- New Vehicle Sales:Configurator tools and virtual test drives compress the dealership visit to final delivery only. German platforms lead in remote contract execution with digital identity verification.
- Used Vehicle Sales:Digital auction infrastructure connecting lease-return inventory to independent dealers captures documentation-fee revenue while disintermediating traditional wholesale channels.
- Financing Options:Real-time credit decisioning and lease-versus-buy calculators integrate at point of configuration, reducing abandonment at payment stage.
- Aftermarket Products:Repeat purchase frequency and lower price transparency generate outsized margin pools. VIN-specific fitment verification eliminates dimensional tolerance errors that previously drove disputes.
Aftermarket Products holds the largest share; momentum sits with Used Vehicle Sales as remarketing platforms scale auction infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German automotive e-tailing platforms exceeds that of Indian counterparts by a factor reflecting infrastructure maturity and fleet procurement concentration. German consumers accept digital vehicle transactions with minimal friction. Indian platforms compete on cash-on-delivery flexibility and vernacular interfaces.
Germany
Fleet operators under EU Green Deal emissions deadlines drive bulk procurement of electric drivetrain components through direct manufacturer portals. The EU F-Gas Regulation imposes strict quota tracking on climate-system components, fragmenting inventory pools. Stuttgart and Munich anchor dense supplier clustering that enables same-day aftermarket fulfillment, pulling Central European demand into German-platform orbits.
United States
Aftermarket parts demand concentrates in brake and suspension categories where VIN-specific fitment engines eliminate dimensional tolerance disputes. NHTSA mandates instantaneous recall disclosure for all vehicle listings, demanding automated VIN cross-referencing infrastructure. Dallas-Fort Worth and Atlanta host fulfillment networks that compress delivery windows for independent repair shops.
China
Domestic platform operators leverage manufacturing proximity to source OEM and aftermarket inventory at compressed cost structures. MIIT certification requirements for vehicle data systems constrain cross-border platform entry. Shanghai and Shenzhen concentrate platform engineering talent and last-mile logistics innovation for electric vehicle component distribution.
India
Low dealership penetration in tier-two and tier-three cities creates first-mover advantages for platforms offering vernacular-language interfaces. BIS certification requirements for automotive components add compliance layers to cross-state shipments. Maharashtra and Karnataka host emerging platform headquarters targeting two-wheeler and entry-level passenger vehicle segments.
United Kingdom
Independent repair shops migrate toward single-platform contracts bundling technical support with parts availability guarantees. The EU AI Act's risk-classification framework imposes documentation burdens on pricing algorithms affecting consumer-facing transactions. Birmingham and Manchester concentrate aftermarket distribution infrastructure serving workshop buyers in emissions-system categories.
Automotive E-Tailing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with diagnostic-integrated platforms commanding premium positioning while marketplace aggregators capture volume economics. The vendor base organizes into three tiers: proprietary tool-integrated suppliers, logistics-dominant generalists, and brick-and-click hybrid operators. Consolidation pressure favors scale-driven players with captive fulfillment networks. Strategic moves center on platform engineering talent acquisition and diagnostic-to-procurement workflow integration.
Within the integrated diagnostic tier, Robert Bosch GmbH exemplifies proprietary tool anchoring that locks workshop procurement into closed ecosystems. Amazon.com Inc. and Alibaba Group Holding Ltd occupy positions as logistics-dominant aggregators whose fulfillment networks set delivery expectations across aftermarket categories. AutoZone Inc. represents the brick-and-click hybrid archetype, positioning digital channels as extensions of local store inventory availability.
| Leading Market Players |
|---|
| O’Reilly Automotive Inc. |
| Alibaba Group Holding Ltd |
| Amazon.com Inc. |
| Robert Bosch GmbH |
| Wal-Mart Stores Inc. |
| AutoZone Inc. |
| eBay Inc. |
| Continental AG |
| Advance Auto Parts Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for VIN-specific brake and suspension components concentrate working capital in German distributor networks, amplifying pricing power for platforms with real-time fitment verification while squeezing margin for generalist aggregators lacking dimensional tolerance databases.
Pricing Analysis
Configured-to-order pricing for electric drivetrain components commands substantial premiums over standard aftermarket catalog pricing. Three-tier pricing structure across premium diagnostic-integrated, standard fitment-verified, and economy unbranded tiers segments buyer willingness-to-pay. Pricing pressure stems from steel and aluminum commodity volatility that exhaust system manufacturers cannot immediately pass through due to price-transparency comparison tools. Individual consumers exhibit highest price sensitivity, while fleet procurement teams prioritize availability guarantees over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk for aluminum alloy wheel imports from Asian manufacturing hubs elevates working capital requirements for rim inventory stocking. Component sourcing draws from Germany, China, and Mexico for brake assemblies, suspension systems, and exhaust components. Rare earth magnet dependencies for electric motor procurement create single-source vulnerability concentrated in Chinese processing facilities. Distribution runs through regional fulfillment centers co-located with Stuttgart and Munich supplier clusters, enabling same-day delivery commitments to Central European workshop buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across incompatible dealer management systems and legacy warehouse software creates acquisition targets for integrators capable of unifying procurement workflows. Electrification-driven parts complexity is fragmenting demand into specialized fitment categories.
For Market Incumbents: Compound diagnostic-to-procurement workflow integration to lock independent repair shops into single-platform contracts. Acquire platform engineering talent scarce in automotive data science to defend against generative AI-powered fitment verification entrants. Prioritize backward integration into proprietary warehouse management systems that synchronize inventory across incompatible legacy architectures. For New Entrants and Emerging Players: CE marking fast-track for emissions-system components unlocks European market entry ahead of full conformity assessment timelines. Target tier-two and tier-three Indian cities with vernacular-language interfaces and cash-on-delivery fulfillment where dealership penetration remains minimal. Pursue mobile-first workshop procurement applications capturing emergency roadside breakdown scenarios. For Investors and Strategic Acquirers: Carve-out targets emerge from OEM captive e-commerce units seeking operational independence from parent brand constraints. Five-to-ten-year viability hinges on platform consolidation economics favoring scale-driven players with captive logistics networks. Monitor EU AI Act enforcement deadlines as inflection indicator for compliance cost restructuring across algorithmic pricing operations.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-to-Procurement Integration | Bosch and Continental bundle proprietary tool data with parts availability to lock workshop loyalty. |
| Same-Day Fulfillment Network Expansion | Amazon's captive logistics infrastructure sets delivery expectations independent repair shops now demand. |
| VIN-Specific Fitment Engine Development | Machine learning verification eliminates dimensional tolerance disputes that previously drove return rates. |
| Mobile-Native Workshop Application Launch | Smartphone procurement workflows capture emergency parts demand from roadside breakdown scenarios. |
| Subscription Maintenance Bundle Introduction | Predictive algorithms enable scheduled parts delivery before failure events for fleet managers. |
Methodological Framework
A spread of perspectives from OEM platform engineers, aftermarket distributor procurement leads, independent repair shop owners, and fleet maintenance managers converged on the working assumptions for transaction volume and margin structure. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from listed automotive retail operators. Bottom-up segment sizing triangulated against top-down market value estimates.
Segmentation dimensions modeled span vehicle class, propulsion architecture, customer type, sales channel, and service category across the analysis window. CAGRs derived from fitted growth curves applied to historical transaction data, adjusted for electrification penetration assumptions and regulatory compliance timelines. Forecast inputs incorporated EU Green Deal emissions mandate enforcement schedules and NHTSA recall disclosure infrastructure deployment rates.
The analysis sits within stated boundaries; outcomes outside sustained electrification investment and platform liability framework evolution would require recalibration. Forecasts reflect documented assumptions regarding fleet procurement digitization velocity and diagnostic tool integration adoption curves. Practitioners should keep alternative scenarios live as EU AI Act algorithmic pricing enforcement and cross-border refrigerant logistics regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Automotive Register Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Car Subscription Market
Automotive Services
Motorsports Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive MRO Market
Automotive Services
Global Car Wash Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
France Car Rental Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
United States Automotive Service Market