
 Automotive Rear End Module Market | 2026-2036
Automotive Rear End Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear End Module Market Insights
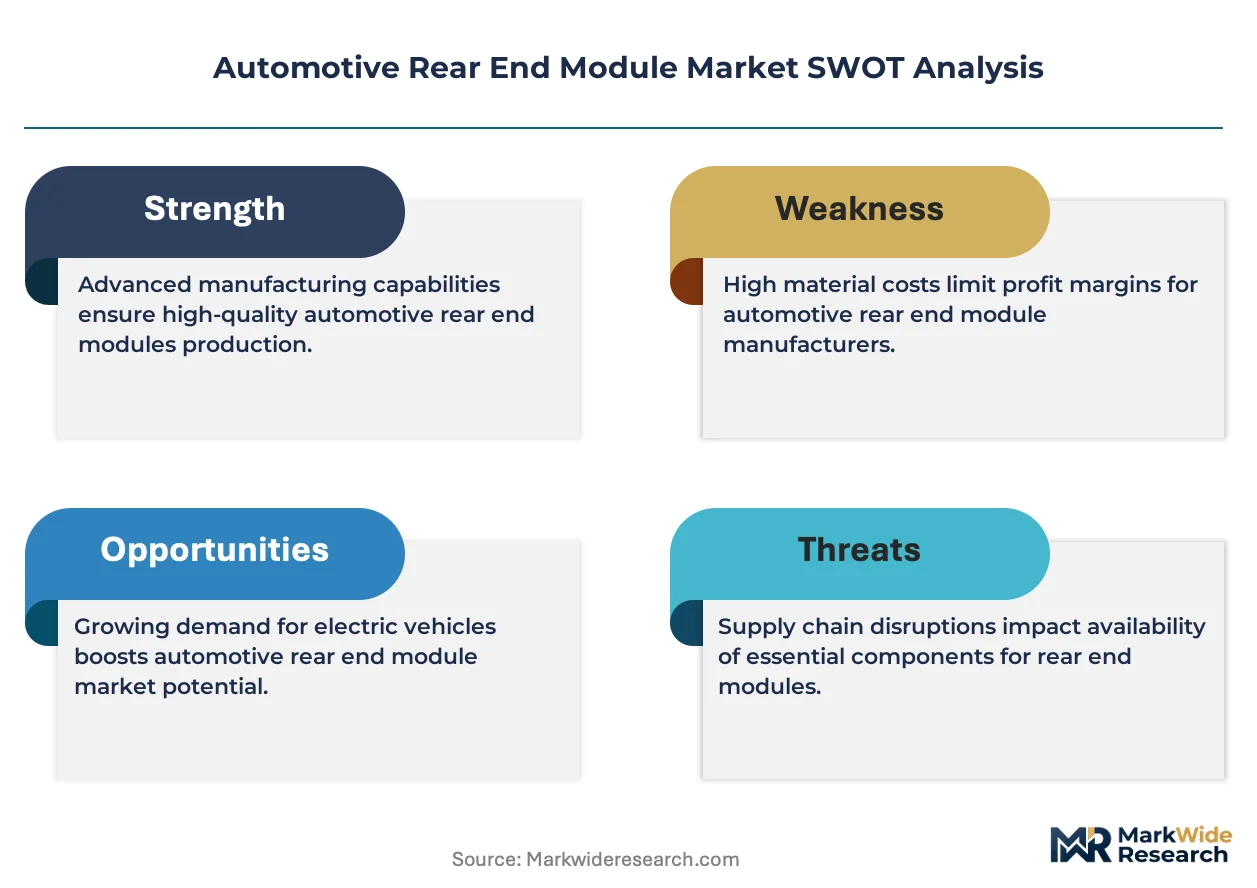
Software-defined lighting and sensor-integrated rear fascia services is shifting procurement economics from discrete parts to functional subscriptions. HELLA leverages its lamp and electronics heritage to anchor premium rear lighting module supply. Magna International sustains manufacturing scale across bumper-to-tailgate integration programs for multiple OEM platforms. ZF Friedrichshafen AG competes through mechatronic rear axle and chassis module combinations that consolidate supplier tiers.
The automotive rear end module encompasses the integrated structural and functional assembly at a vehicle's posterior, comprising bumpers, tailgates, exhaust terminations, lighting, and sensor carriers typically manufactured through injection molding, stamping, and adhesive bonding processes designed to meet crashworthiness and aerodynamic targets. Bumper Systems dominate value capture due to their sensor density and repair frequency, while Composite Materials represent the fastest-expanding technology segment as OEMs pursue mass reduction targets without sacrificing stiffness. Tailgate Assemblies concentrate margin pools in the premium Passenger Vehicles category where power-lift and hands-free access features command supplier premiums.
NHTSA rear impact standards, EU pedestrian protection regulations under the General Safety Regulation, and China's GB standards for exterior protrusions collectively dictate module geometry, material selection, and sensor placement requirements that shape engineering priorities. ECE R58 and R93 compliance for rear underrun protection further constrains heavy-duty module design across export-bound production. Stakeholders must monitor how software update capabilities in rear sensor arrays reshape aftermarket access and long-term service revenue allocation between OEMs and module suppliers.
Market Dynamics
Platform consolidation pressures and sensor integration mandates are compressing supplier tiers, forcing module makers to absorb lighting, sensing, and structural functions into unified assemblies that OEMs procure as single SKUs.
Growth Catalysts
- EU General Safety Regulation pedestrian protection mandates:Rear impact energy absorption requirements are expanding addressable content per vehicle, particularly in crossover and SUV architectures where module depth accommodates crushable foam structures.
- Injection-molded long-fiber thermoplastic adoption:Material substitution in bumper beams and tailgate inner panels reduces mass while maintaining torsional rigidity, aligning with fleet efficiency targets without retooling stamping infrastructure.
- Germany premium vehicle production clustering:Stuttgart and Munich corridor OEMs specify power-lift tailgates with capacitive gesture recognition, elevating module complexity and supplier engineering premiums.
Market Restraints
- Polypropylene compound price volatility:Feedstock linkage to propylene monomer exposes margin compression during petrochemical cycle peaks, particularly for high-impact copolymer grades used in bumper fascias.
- Tooling amortization burden:Multi-cavity injection molds for integrated lamp housings require capital deployment that smaller tier-two suppliers cannot underwrite, concentrating mold ownership among top-five module integrators.
- Homologation timeline fragmentation:Divergent NHTSA, ECE R58, and GB standard approval sequences delay platform launch synchronization, straining engineering resource allocation across regulatory jurisdictions.
Strategic Opportunities
- India premium passenger vehicle assembly expansion:Chennai and Pune plant capacity additions by European OEMs create demand for localized rear module supply with hands-free tailgate functionality previously imported as complete units.
- Over-the-air sensor calibration services:Rear parking and blind-spot arrays require post-assembly software validation, opening recurring revenue streams that decouple from physical part replacement cycles.
- Closed-loop thermoplastic recovery:EU End-of-Life Vehicle directive material recovery targets incentivize design-for-disassembly architectures that module suppliers can certify as compliance-enabling services.
Industry Challenges
- Mechatronics systems integration competency gaps:Traditional stamping and molding houses lack embedded software validation capacity for sensor-fascia integration, requiring partnership or acquisition of electronics engineering teams.
- Paint-shop thermal compatibility:E-coat bake cycles exceeding 180°C degrade certain radar-transparent polymer grades, forcing material qualification sequences that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear End Module Market |
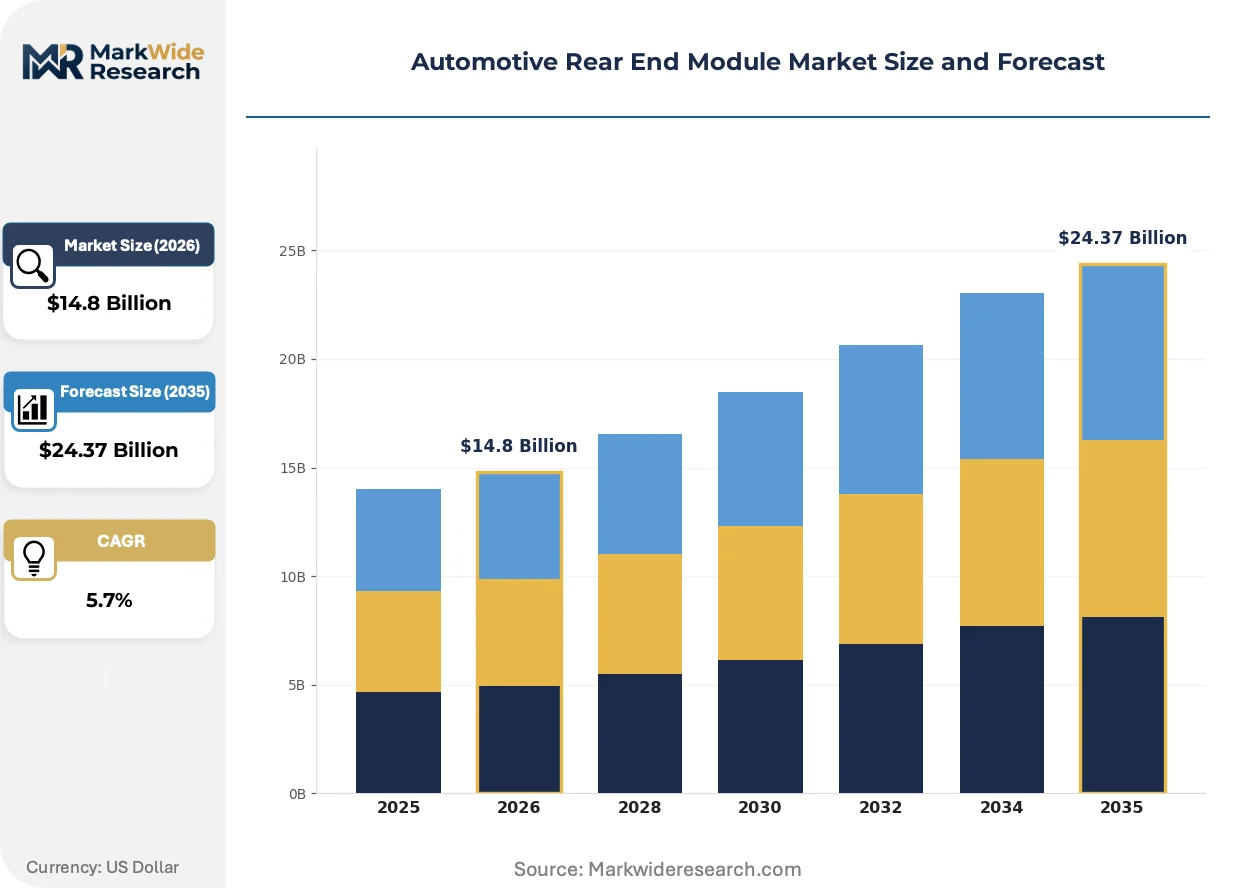
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bumper Systems, Exhaust Systems, Tailgate Assemblies, Chassis Components Technology: Advanced High Strength Steel, Composite Materials, Aluminum Alloys, Plastic Polymer Application: Passenger Vehicles, Light Commercial Vehicles, Heavy-Duty Trucks, SUVs End User: OEMs, Aftermarket Providers, Dealerships, Tier-1 Suppliers |
| Companies Covered | HELLA, Magna International, Miwa Seisakusho, ATM Automation, Hyundai MOBIS, ZF Friedrichshafen AG, American Axle & Manufacturing, GKN Automotive, NTN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear End Module Market Trends and Innovations
Digital light processing and solid-state lidar embedding are transforming rear modules from passive crash structures into active sensing platforms with software-updatable functionality.
Multi-material bonding architectures combining continuous fiber thermoplastic composites with localized metal inserts are modularizing crash management system design. Tier-one suppliers now deliver pre-validated sub-assemblies that OEMs mount as single units, compressing final assembly line complexity. This consolidation is modularizing traditional tier boundaries between bumper specialists and structural component suppliers.
ECE R58 rear underrun protection device mandates for commercial vehicles above 3.5 tonnes are forcing redesign of heavy-duty module attachment points. German and Swedish truck manufacturers have accelerated aluminum extrusion adoption in underrun bars to meet mass targets while satisfying energy absorption protocols. The regulation is compressing design cycles for export-bound platforms that must homologate across multiple jurisdictions simultaneously.
Fleet operators and leasing companies now specify total-cost-of-ownership service agreements that bundle rear sensor array maintenance with physical damage coverage. This unbundles traditional aftermarket parts revenue from OEM service networks, redirecting diagnostic and calibration income toward module suppliers with captive telematics infrastructure. The shift is most advanced in German premium fleet channels where contract duration exceeds 48 months.
Automotive Rear End Module Market Segmentation
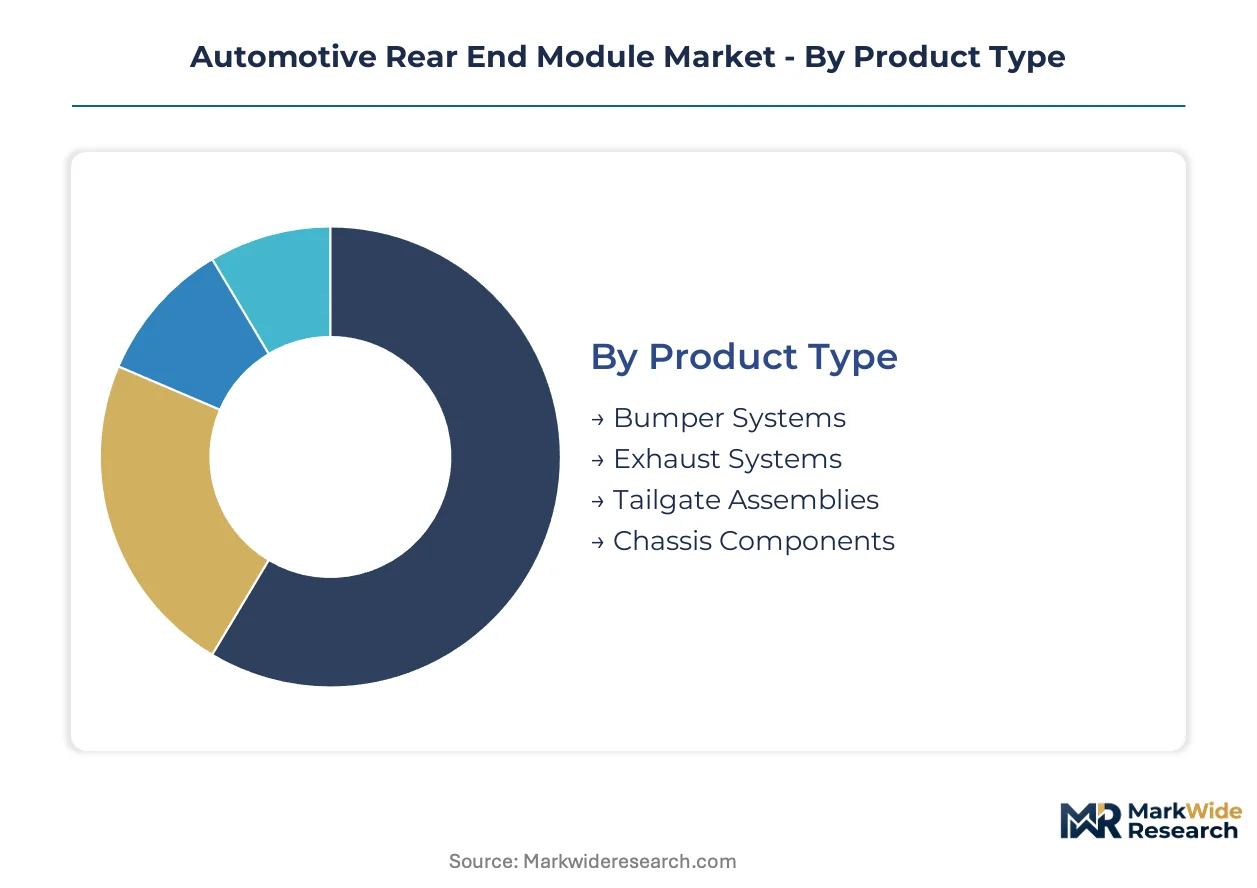
Rear end module procurement economics hinge on which segments suppliers integrate versus those OEMs source separately. Platform consolidation favors unified assemblies, fragmenting demand for standalone components.
Product Type:
Standalone bumper and tailgate programs persist where sensor density remains low, while exhaust-chassis combinations dominate integrated platform sourcing.
- Bumper Systems:These assemblies incorporate energy-absorbing foam structures, fascia panels, and increasingly dense sensor arrays for parking and pedestrian detection. Demand concentrates in crossover and SUV architectures where module depth accommodates crushable structures meeting EU General Safety Regulation pedestrian protection mandates.
- Tailgate Assemblies:Power-lift mechanisms with capacitive gesture recognition elevate engineering complexity and supplier premiums. Stuttgart and Munich corridor OEMs specify these features most intensively, anchoring margin pools in premium passenger vehicle production.
- Exhaust Systems:Termination modules integrate with rear bumper cutouts for thermal management and aesthetic finishing.
- Chassis Components:Structural rear axle carriers and subframe attachments consolidate with bumper beams in heavy-duty applications.
Volume placements concentrate in Bumper Systems; the faster expansion belongs to Tailgate Assemblies.
Technology:
Material selection tracks mass reduction targets against stiffness requirements, with thermal compatibility constraining radar-transparent grades.
- Composite Materials:Long-fiber thermoplastic substitution in bumper beams and tailgate inner panels reduces mass while maintaining torsional rigidity. This technology aligns with fleet efficiency targets without requiring retooling of stamping infrastructure, expanding most quickly as OEMs pursue platform lightweighting.
- Advanced High Strength Steel:Hot-formed grades deliver crashworthiness in underrun protection bars and structural reinforcement patches. German and Swedish truck manufacturers specify these for energy absorption compliance under ECE R58.
- Aluminum Alloys:Extrusion adoption accelerates in commercial vehicle underrun bars to satisfy mass targets alongside regulatory protocols.
- Plastic Polymer:Polypropylene compounds dominate fascia production despite feedstock price volatility linked to propylene monomer cycles.
Procurement weighting still favors Advanced High Strength Steel; Composite Materials claim the steepest adoption trajectory.
Application:
Vehicle architecture determines module depth, sensor count, and repair frequency, segmenting supplier engineering priorities.
- Passenger Vehicles:Sedan and hatchback modules prioritize aerodynamic efficiency and pedestrian impact geometry. German premium production clusters specify the most complex power-lift and hands-free access integrations.
- SUVs:Elevated rear fascias accommodate larger crush zones and higher sensor mounting positions for blind-spot monitoring. This application commands the fastest content expansion per vehicle as crossover architectures proliferate.
- Light Commercial Vehicles:Durability-focused designs emphasize repairability and standardized attachment points for fleet maintenance.
- Heavy-Duty Trucks:ECE R58 rear underrun protection mandates force redesign of module attachment points and energy absorption structures.
Supplier revenue concentrates in Passenger Vehicles; SUVs demonstrate the sharpest volume ascent.
End User:
Procurement channel structure determines whether modules arrive as complete assemblies or discrete components for line-sequenced installation.
- OEMs:Direct platform procurement of unified rear end modules compresses supplier tiers and elevates integrator scale requirements. NHTSA, ECE, and GB standard compliance sequences strain engineering resources across regulatory jurisdictions.
- Tier-1 Suppliers:These intermediaries absorb lighting, sensing, and structural functions into single-SKU assemblies for multiple OEM platforms. Multi-cavity injection mold capital requirements concentrate ownership among top-five integrators.
- Aftermarket Providers:Sensor calibration and software update capabilities reshape service revenue allocation between physical replacement and diagnostic services.
- Dealerships:Fleet operators now bundle rear sensor maintenance with damage coverage, redirecting calibration income toward module suppliers with captive telematics infrastructure.
Contract value pools deepest with OEMs; Aftermarket Providers capture the most rapid service revenue transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global rear end module engineering intensity, with Munich corridor OEMs specifying power-lift tailgates and capacitive gesture recognition that elevate supplier premiums.
Germany
Premium vehicle production clustering drives module complexity requirements. ECE R58 and R93 compliance for rear underrun protection constrains heavy-duty module design across export-bound production. Stuttgart and Munich corridor OEMs specify power-lift tailgates with capacitive gesture recognition, anchoring margin pools in engineering premiums.
United States
Crossover and SUV proliferation expands crushable foam structure content per vehicle. NHTSA rear impact standards dictate module geometry and sensor placement requirements. Detroit Three OEMs source integrated bumper-to-tailgate assemblies from tier-one integrators with captive North American stamping capacity.
China
Domestic brand upmarket migration accelerates hands-free tailgate adoption. GB standards for exterior protrusions shape material selection and energy absorption protocols. Yangtze River Delta automotive clusters concentrate injection molding capacity for radar-transparent polymer fascia grades.
Japan
Keiretsu supply relationships sustain specialized tailgate hinge and latch manufacturing. METI fuel efficiency targets drive long-fiber thermoplastic substitution in bumper beams. Nagoya-Toyota City corridor maintains captive module assembly for hybrid platform rear fascia integration.
India
European OEM assembly expansion creates localized supply demand for previously imported complete units. BIS automotive component certification timelines shape supplier qualification sequences. Chennai and Pune plant capacity additions specify hands-free tailgate functionality for premium passenger vehicle production.
Automotive Rear End Module Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the rear end module value chain. The supplier base concentrates among tier-one integrators with multi-cavity injection mold ownership and captive electronics validation capacity. Three archetypes dominate: diversified automotive suppliers with bumper-to-chassis integration breadth, lighting-electronics specialists leveraging lamp heritage into sensor-fascia combinations, and mechatronic chassis houses consolidating axle and structural functions. Competitive dynamics center on platform consolidation mandates that compress supplier tiers, and over-the-air calibration capabilities that reshape aftermarket service revenue capture.
Among diversified automotive suppliers, Magna International exemplifies scale-driven integration across multiple OEM platforms, while ZF Friedrichshafen AG anchors mechatronic rear axle and chassis module combinations. HELLA occupies a position within the lighting-electronics specialist tier, leveraging heritage in lamp and electronics manufacturing.
| Leading Market Players |
|---|
| HELLA |
| Magna International |
| Miwa Seisakusho |
| ATM Automation |
| Hyundai MOBIS |
| ZF Friedrichshafen AG |
| American Axle & Manufacturing |
| GKN Automotive |
| NTN Corporation |
| Others |
Pricing and Supply Chain Analysis
Premium German OEM procurement concentration anchors value-based pricing for integrated rear end modules, with power-lift tailgate and sensor-fascia combinations commanding engineering premiums tied to vehicle platform outcomes rather than discrete component costs.
Pricing Analysis
Value-based pricing tied to platform-level crash performance and sensor integration outcomes dominates procurement contracts. Pricing stratifies across premium, standard, and economy tiers based on sensor density and homologation complexity, with EU General Safety Regulation certification levels driving tier separation. Cost compression in polypropylene bumper fascia grades is intensifying because propylene monomer feedstock volatility exposes compound suppliers to margin squeezes. Tier-2 stamping houses exhibit highest price sensitivity, while Stuttgart corridor OEMs accept premium engineering charges for hands-free access functionality.
Supply Chain Analysis
Dual-sourcing requirements from Detroit Three and German premium OEMs mandate multi-supplier qualification for radar-transparent polymer grades and hot-formed steel reinforcement patches. Manufacturing concentrates in Germany, China, and Mexico, with Yangtze River Delta clusters feeding injection molding capacity and Stuttgart anchoring engineering validation. Supply chains rest on long-fiber thermoplastic resin systems and capacitive sensor arrays from specialized electronics houses. Single-source vulnerability in multi-cavity lamp housing tooling concentrates mold ownership risk among top-five integrators. Distribution runs through tier-one module assemblers delivering pre-validated sub-assemblies to OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation mandates are compressing supplier tiers and forcing capital-light tier-two players toward exit or acquisition, with multi-cavity injection mold ownership emerging as the decisive survival threshold.
For Market Incumbents: Deploy captive electronics validation capacity to absorb sensor-fascia integration functions that stamping-dependent competitors cannot underwrite. Deepen backward integration into long-fiber thermoplastic compounding to hedge propylene monomer price volatility. Acquire tier-two mold shops in Yangtze River Delta and Stuttgart corridors to consolidate platform-scale tooling ownership against emerging mechatronic chassis houses. For New Entrants and Emerging Players: EU General Safety Regulation pedestrian protection mandates in Germany open a window for specialized crushable foam structure suppliers without full module integration burden. Target Chennai and Pune assembly corridors where European OEM localization creates demand for hands-free tailgate mechanisms previously imported as complete units. Pursue partnership-based entry with established lighting-electronics specialists lacking structural validation capacity. For Investors and Strategic Acquirers: The window for entry favors tier-two mold shops with qualified multi-cavity capacity and latent electronics engineering teams acquirable at compressed multiples. Long-term viability hinges on captive telematics infrastructure enabling over-the-air sensor calibration revenue capture. Watch for divergence in NHTSA and ECE R58 homologation timeline synchronization as inflection signal for engineering resource strain among undercapitalized integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling amortization burden across multiple OEM vehicle architectures sharing unified rear module interfaces. |
| Sensor-Fascia Integration Investment | Captures parking and pedestrian detection content migrating from discrete tier-two suppliers into consolidated assemblies. |
| Geographic Manufacturing Footprint Expansion | Chennai and Pune capacity addresses European OEM localization requirements for premium passenger vehicle production. |
| Software-Defined Module Development | Enables over-the-air calibration revenue streams decoupled from physical part replacement cycles in fleet channels. |
| Closed-Loop Material Recovery Certification | Positions module suppliers as compliance enablers under EU End-of-Life Vehicle directive recovery targets. |
Research Methodology
Document review covered vehicle production databases, IHS Markit registration data, and regulatory filing repositories, complemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors. Primary fieldwork engaged technical R&D directors at composite material suppliers and homologation specialists familiar with ECE R58 and NHTSA rear impact protocols. Secondary validation drew from customs and trade data, SEC filings of diversified automotive suppliers, and platform consolidation announcements. Bottom-up content-per-vehicle estimates were triangulated against top-down market value projections.
Historical volume trajectories were cross-referenced against panel input from procurement executives to establish baseline assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis of platform rollout schedules and material substitution curves. Forecast inputs incorporated injection-molded long-fiber thermoplastic adoption rates and EU General Safety Regulation compliance phase-in timelines.
The model assumes a particular technology adoption path for solid-state lidar embedding and radar-transparent polymer qualification; alternative pathways for digital light processing integration would alter the outlook for lighting-electronics specialist competitive positioning. Forecasts reflect assumptions about homologation timeline convergence and propylene monomer feedstock stability. Deviation in NHTSA-ECE regulatory synchronization or paint-shop thermal compatibility breakthroughs for polymer grades would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Actuators Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Catalyst Market