
 Automotive Parts Packaging Market | 2026-2036
Automotive Parts Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Parts Packaging Market Intelligence
Reusable container pooling services is repositioning what automotive suppliers purchase, shifting capital from disposable materials to logistics-as-a-service contracts. Sealed Air Corporation leverages its inflated protective film technology to anchor high-value electronics shipments for EV battery modules. Mondi plc sustains European fiber-based supply chains through integrated kraft paper operations that compete on recyclability credentials. Greif, Inc. dominates industrial intermediate bulk container leasing, extending its asset network into just-in-time automotive component flows.
Automotive parts packaging encompasses engineered containment systems designed to protect powertrain, electrical, and body components during multimodal transit, typically incorporating corrugated fiberboard structures with 200–350 lb burst strength ratings or thermoformed plastic trays with ESD-dissipative properties. The primary commercial purpose centers on eliminating part damage, reducing warranty claims, and enabling sequenced assembly line delivery. Boxes and pallets occupy the largest volume share within product type segmentation, though custom packaging commands superior margin pools due to engineering-intensive design requirements. Plastic retains material dominance for moisture-sensitive precision components, while cardboard gains structural ground in non-critical trim and fastener applications where OEM sustainability scorecards apply procurement pressure.
FDA regulations on indirect food-contact materials influence packaging resins used in cabin-interior components, while EPA emissions frameworks shape recycled content mandates for domestic automotive packaging procurement. REACH restrictions on heavy-metal stabilizers and phthalate plasticizers directly constrain PVC and certain polyolefin formulations available to European automotive tier suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and material passport requirements that will determine which packaging formats retain fleet-wide approval across major automotive assembly networks.
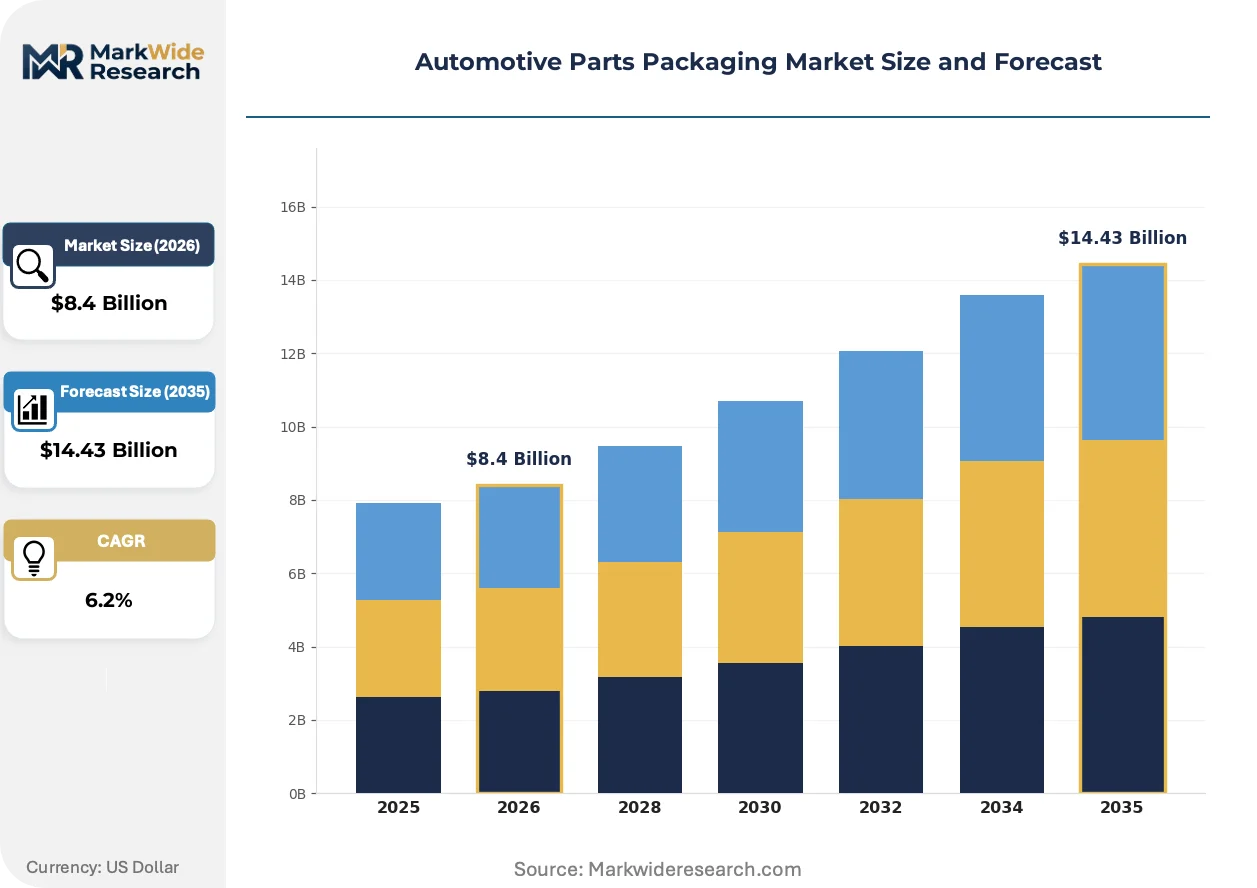
Market Dynamics
Electric vehicle battery module complexity is forcing packaging engineers to redesign protective systems for thermal runaway containment and high-voltage isolation, creating tiered performance specifications that separate qualified suppliers from commodity providers.
Growth Catalysts
- EU Green Deal packaging mandates:Fiber-based material transitions are accelerating across German and French automotive supplier networks as extended producer responsibility schemes tighten virgin plastic thresholds.
- EV powertrain component density:Battery management systems and inverter assemblies require precision-molded ESD-dissipative trays that command engineering-intensive procurement relationships.
- Sequenced assembly line delivery:Just-in-time packaging formats with embedded RFID tracking are compressing inventory carrying costs for OEMs operating lean production systems.
Market Restraints
- Recycled resin quality inconsistency:Post-consumer polypropylene feedstock variability limits structural integrity for heavy-duty automotive dunnage applications.
- REACH chemical restrictions:Phthalate plasticizer bans constrain flexible PVC formulations used in interior trim component protection across European tier supplier networks.
- Corrugated fiberboard moisture sensitivity:Humidity exposure during multimodal transit degrades burst strength ratings below OEM damage thresholds for critical powertrain parts.
Strategic Opportunities
- Returnable container pooling networks:Logistics-as-a-service contracts are capturing capital previously allocated to disposable packaging procurement in German automotive clusters.
- Bio-based barrier coatings:Cellulose-derived moisture-resistant treatments are penetrating non-critical fastener and trim applications where sustainability scorecards drive supplier selection.
- Digital product passport integration:EU material traceability requirements are creating first-mover advantages for packaging suppliers with embedded blockchain verification systems.
Industry Challenges
- Automotive packaging engineer scarcity:Specialized expertise in thermal protection modeling and vibration dampening design is concentrating among a limited pool of qualified professionals.
- Multi-certification timeline compression:Simultaneous OEM approval processes for new EV battery packaging formats are extending qualification cycles beyond program launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Parts Packaging Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Pallets, Bags, Containers Material: Plastic, Metal, Cardboard, Foam End User: OEMs, Aftermarket Providers, Distributors, Retailers Packaging Format: Bulk Packaging, Unit Packaging, Custom Packaging, Eco-Friendly Packaging |
| Companies Covered | Amcor PLC, Mondi plc, International Paper Company, Sealed Air Corporation, DS Smith plc, WestRock Company, Berry Global Group, Inc., Greif, Inc., Smurfit Kappa Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Parts Packaging Market Strategic Shifts & Innovations
Active material science development is compressing the performance gap between fiber-based and plastic protective systems, while digital tracking integration and circular service models are redefining supplier value propositions.
Thermoformed pulp fiber trays with engineered cellulose barrier coatings are expanding into precision electronics protection for EV battery management systems. Tier-1 suppliers in Germany and South Korea are adopting these formats for non-critical powertrain components. The technology is expanding into applications previously reserved for vacuum-formed PET, compressing material cost differentials while satisfying OEM sustainability procurement criteria.
REACH restrictions on heavy-metal stabilizers are eliminating certain PVC compound formulations from European automotive interior packaging. Tier suppliers must reformulate flexible protective films or switch to alternative elastomeric materials. Battery module suppliers face the tightest compliance windows as their packaging falls under both chemical safety and electrical isolation regulatory frameworks.
Outcome-based container management contracts are displacing traditional capital purchase models for high-volume automotive component flows. German OEM procurement teams now specify damage-rate guarantees rather than unit pricing, transferring performance risk to packaging service providers. This shift concentrates contract awards among suppliers with integrated pooling networks and real-time asset tracking capabilities.
Automotive Parts Packaging Market Segmentation
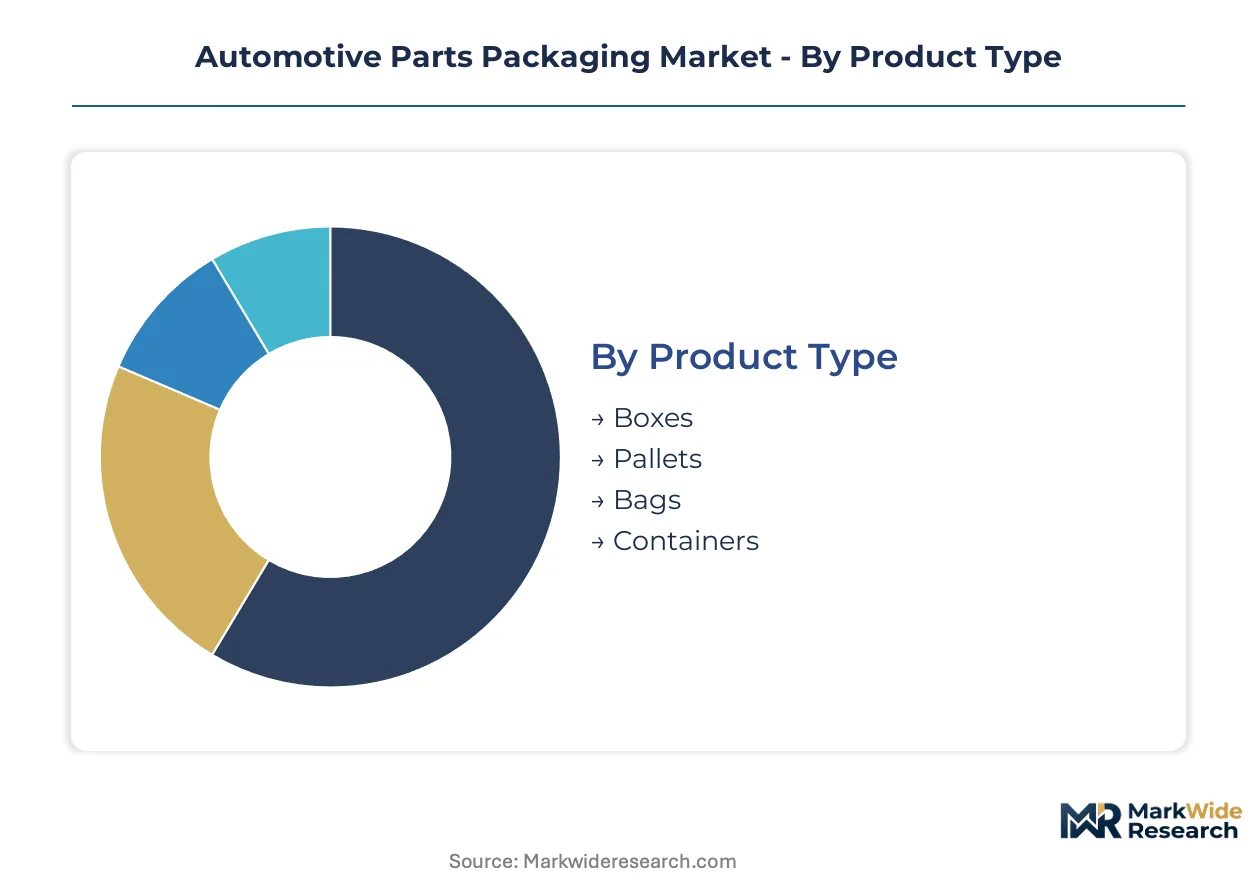
Packaging selection in automotive supply chains hinges on component value density, transit distance, and OEM sustainability mandates. Each segment category reflects distinct procurement logic—from capital-intensive reusable systems to disposable formats governed by material compliance thresholds.
Product Type:
Replacement cycles for transit hardware accelerate as EV component weights rise and sequenced delivery tolerances tighten.
- Boxes:Corrugated fiberboard structures rated at 200–350 lb burst strength dominate fastener and trim protection for German OEM assembly networks. REACH-compliant kraft grades are displacing wax-coated alternatives as EU Green Deal procurement criteria harden.
- Pallets:Plastic pooling assets with embedded RFID tags capture capital from disposable wooden units in just-in-time component flows. German tier suppliers now specify damage-rate guarantees rather than per-unit pricing for high-volume powertrain parts.
- Bags:Flexible polyethylene formats protect moisture-sensitive electronics during multimodal transit. ESD-dissipative film grades command premium positioning for battery management system shipments.
- Containers:Returnable rigid totes with collapsible sidewalls compress logistics costs for sequenced assembly line delivery. KBA-certified designs dominate German automotive cluster procurement.
Boxes sit at the top of the volume ranking, with containers climbing the fastest as pooling networks displace disposable formats.
Material:
Cost tiers separate commodity feedstocks from engineered grades with regulatory certification overhead.
- Plastic:Thermoformed PET and polypropylene trays with ESD-dissipative properties anchor precision electronics protection. Battery module suppliers in South Korea specify these formats for thermal runaway containment applications.
- Metal:Steel and aluminum stillage systems handle powertrain castings in heavy-duty closed-loop logistics. German OEMs favor galvanized steel for corrosion resistance in outdoor storage environments.
- Cardboard:Recycled-content corrugated formats compete on sustainability scorecards for non-critical trim and interior components. Humidity sensitivity limits penetration into critical powertrain applications.
- Foam:Expanded polypropylene and polyurethane inserts provide vibration dampening for precision-machined transmission components. REACH restrictions on blowing agents are forcing reformulation across European supplier networks.
Plastic holds the largest revenue share, with cardboard gaining ground fastest under fiber-based procurement mandates.
End User:
Customer type determines packaging specification authority and contract structure.
- OEMs:Direct procurement teams specify engineered formats with embedded traceability for sequenced assembly line delivery. German manufacturers lead adoption of outcome-based container management contracts.
- Aftermarket Providers:Fragmented demand favors standardized corrugated formats with lower engineering overhead. Inventory velocity requirements drive preference for disposable over returnable systems.
- Distributors:Intermediate handling nodes require hybrid formats compatible with multiple OEM packaging standards. Cross-docking efficiency prioritizes modular container dimensions.
- Retailers:End-consumer-facing protection emphasizes shelf-ready presentation for accessory and maintenance parts. Sustainability labeling influences procurement selection.
OEMs command the highest packaging spend per unit, with aftermarket providers expanding fastest as vehicle age profiles lengthen.
Packaging Format:
Margin structures diverge sharply between commodity bulk formats and engineered custom solutions.
- Bulk Packaging:Standardized corrugated gaylords and metal stillages handle high-volume commodity components. German tier suppliers optimize cube utilization for long-haul multimodal transit.
- Unit Packaging:Individual component protection with ESD and moisture barriers serves precision electronics and powertrain subassemblies. Specification complexity concentrates supply among qualified vendors.
- Custom Packaging:Engineering-intensive designs with thermal modeling and vibration analysis command premium margins. EV battery module formats require simultaneous electrical isolation and thermal runaway containment.
- Eco-Friendly Packaging:Fiber-based and bio-derived formats with blockchain traceability satisfy EU material passport requirements. German OEM sustainability scorecards drive supplier selection.
Bulk packaging leads by unit volume, with eco-friendly formats expanding most quickly under regulatory procurement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized packaging procurement through its automotive production density, while the United States leverages EV battery manufacturing expansion to reshape protective system specifications across North American supplier networks.
Germany
Sequenced assembly line delivery requirements from BMW, Mercedes-Benz, and Volkswagen compress procurement cycles for just-in-time container formats. KBA certification mandates for returnable rigid totes filter supplier participation in Baden-Württemberg and Bavaria automotive clusters. Stuttgart and Munich production corridors concentrate demand for fiber-based REACH-compliant kraft grades as EU Green Deal thresholds tighten virgin plastic procurement.
United States
EV battery gigafactory construction in Michigan, Tennessee, and Nevada generates demand for thermal runaway containment packaging with high-voltage isolation properties. EPA recycled content mandates for domestic automotive procurement shape material selection for tier suppliers serving Detroit Three assembly networks. The Southeast manufacturing corridor stretching from South Carolina to Alabama anchors specialized protective system engineering for electric powertrain components.
China
Dual carbon goals and MIIT industrial packaging standards accelerate fiber-based transitions for non-critical automotive components across Yangtze River Delta supplier networks. NMPA-equivalent material safety protocols govern cabin-interior packaging resins for vehicles destined for export markets. Shanghai and Shenzhen automotive clusters concentrate procurement of thermoformed ESD-dissipative trays for battery management system shipments.
Japan
METI circular economy roadmaps drive returnable container adoption among Toyota, Honda, and Nissan tier suppliers in Aichi and Kanagawa prefectures. JIS standards for industrial packaging performance filter supplier qualification for precision powertrain component protection. The Chubu region around Nagoya maintains dense concentration of specialized packaging engineering for hybrid and electric vehicle subassemblies.
South Korea
MFDS material safety requirements intersect with KSA industrial standards to shape packaging resin selection for automotive interior components. Battery module suppliers in Gyeonggi-do and Ulsan specify precision-molded protective systems with simultaneous electrical isolation and thermal management properties. The Seoul Capital Area concentration of Hyundai-Kia procurement teams drives adoption of RFID-embedded sequenced delivery formats.
Automotive Parts Packaging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with engineered custom formats concentrating among integrated material science firms while commodity corrugated flows fragment across regional converters. Three archetypes dominate competitive positioning: integrated paper and fiberboard producers with captive pulp supply, specialized protective film and foam compounders serving precision electronics, and pooling network operators capturing capital through logistics-as-a-service contracts. Consolidation pressure runs through capacity expansion in fiber-based barrier coatings and strategic partnerships for digital product passport integration.
Within the integrated material science tier, Mondi plc and Smurfit Kappa Group plc exemplify European fiber-based supply chain control, while Sealed Air Corporation occupies a position among protective film specialists serving high-value EV battery module shipments. Greif, Inc. anchors the pooling network archetype through industrial intermediate bulk container leasing extended into just-in-time automotive component flows.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi plc |
| International Paper Company |
| Sealed Air Corporation |
| DS Smith plc |
| WestRock Company |
| Berry Global Group, Inc. |
| Greif, Inc. |
| Smurfit Kappa Group plc |
| Others |
Cost & Logistics Intelligence
Kraft pulp price indices from European exchanges cascade through automotive packaging supply chains, compressing margins for corrugated converters while amplifying procurement leverage for OEMs with long-term fiber supply contracts. REACH-compliant material premiums and pooling network service fees stratify pricing tiers across German automotive clusters.
Pricing Analysis
Capacity additions in fiber-based barrier coating facilities are reshaping price floors for sustainable packaging formats across European supplier networks. Three-tier pricing structure across premium engineered grades, standard REACH-compliant materials, and economy virgin-plastic alternatives governs procurement. Cost compression in commodity corrugated runs through recycled-content feedstock variability, while OEM direct procurement teams show lowest price sensitivity due to damage-rate guarantee contracting.
Supply Chain Analysis
Dual-sourcing mandates from BMW, Mercedes-Benz, and Volkswagen procurement teams require Tier 1 suppliers to qualify multiple packaging vendors for critical powertrain components. Manufacturing concentrates in Germany, China, and Mexico, with raw material flows drawing from Scandinavian kraft pulp, South Korean ESD-grade resins, and domestic recycled fiber streams. Single-source vulnerability sits with specialized thermoformed pulp tooling, while distribution runs through sequenced logistics networks anchored to Stuttgart, Munich, and Wolfsburg assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber-based material transitions and logistics-as-a-service contract expansion create margin-expansion pathways for suppliers with integrated pooling networks and captive pulp supply. Premium-tier positioning in EV battery module protection commands pricing power as thermal runaway containment specifications tighten.
For Market Incumbents: Hedge resin price volatility through backward integration into recycled fiber processing or long-term kraft pulp offtake agreements with Nordic suppliers. Defend market position by accelerating KBA-certified returnable container fleet expansion before EU Green Deal thresholds harden procurement criteria for German OEM networks.
For New Entrants and Emerging Players: Capture white-space opportunity in thermoformed pulp fiber trays for non-critical EV powertrain components, where sustainability scorecards drive supplier selection but engineering barriers remain lower than battery module formats. Target aftermarket providers with standardized corrugated solutions featuring embedded RFID tracking, leveraging fragmented demand and lower certification overhead for rapid scale.
For Investors and Strategic Acquirers: Asymmetric upside sits with pooling network operators possessing real-time asset tracking capabilities and established German automotive cluster relationships. Five-to-ten-year viability favors suppliers with dual competence in fiber-based barrier coatings and digital product passport integration. Watch EV battery gigafactory construction announcements in the US Southeast as demand inflection signals for thermal protection packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Based Barrier Coating Scale-Up | REACH-compliant cellulose treatments capture share from vacuum-formed PET in electronics protection. |
| Returnable Container Pooling Network Expansion | KBA-certified asset fleets lock in long-term logistics-as-a-service contracts with German OEMs. |
| Digital Product Passport Integration | Blockchain traceability systems satisfy EU material compliance and create first-mover procurement advantages. |
| ESD-Dissipative Compound Reformulation | Phthalate-free flexible film development maintains European interior component packaging approvals. |
| Thermal Runaway Containment Engineering | Precision-molded protection systems for EV battery modules command premium tier pricing. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and pooling network operations managers with secondary validation. Trade data from European paper industry associations, EPA recycled content disclosure filings, KBA certification registries, and IHS Markit vehicle production databases anchored supply-side sizing. Bottom-up segment builds triangulated against top-down automotive production forecasts.
Historical reference periods anchored volume and value projections across the analysis window, with CAGRs derived from segmented growth rate reconciliation across product type, material, end user, and packaging format dimensions. Modeled inputs included EV battery module complexity trajectories, EU Green Deal implementation timelines, and sequenced delivery adoption curves in German manufacturing clusters.
Regulatory enforcement variance, fiber feedstock price volatility, and EV platform launch delays are the dominant revision risks to forecast assumptions. Deviation in EU extended producer responsibility scheme implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Portion Packs Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Euro Box Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Bottles Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Cooler Box Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Correx Trays Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Dispensing Trays Market