
 Sanitizer Bottles Market | 2026-2036
Sanitizer Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitizer Bottles Market Analytics
REACH compliance is recalibrating the cost-of-entry calculus for European sanitizer bottle suppliers, forcing reformulation of plastic resins and closure mechanisms. GOJO Industries leverages captive manufacturing scale to offset compliance-driven raw material premiums. Procter & Gamble sustains channel control through direct hospital procurement contracts in North America. Henkel AG & Co. KGaA anchors European market access with localized production networks that bypass cross-border regulatory friction.
Sanitizer bottles are rigid or semi-rigid containers engineered from HDPE, PET, or bio-based polymers, typically ranging from 30 mL to 5 L in nominal volume, designed to dispense alcohol-based or quaternary ammonium solutions through pump, spray, or flip-top mechanisms for hand and surface hygiene in clinical, commercial, and consumer settings. Plastic dominates material selection due to cost efficiency and drop resistance, though bio-based materials are gaining structural traction as brand owners face Scope 3 emissions targets. Pump dispenser closures command premium positioning in healthcare channels where dosing precision reduces waste, while travel-size formats compete on portability in aviation and hospitality verticals.
FDA regulates sanitizer formulations and associated packaging claims under over-the-counter drug monographs, while EPA oversees surface disinfectant container labeling for institutional applications. EMA and national competent authorities across Europe enforce medical device packaging standards where sanitizer bottles interface with clinical protocols. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which material technologies retain cost-competitive market access.
Market Dynamics
REACH compliance is forcing European sanitizer bottle suppliers to reformulate plastic resins and closure mechanisms, recalibrating cost structures while bio-based polymer alternatives gain procurement traction under Scope 3 emissions targets.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks accelerate material transitions toward recyclable and bio-based polymers across European supply chains.
- Pump-dispenser format expansion:Healthcare facilities prioritize dosing precision mechanisms to reduce waste and meet infection control compliance protocols.
- Germany, France, United Kingdom demand concentration:Hospital-grade sanitation protocol tightening drives procurement volume in these three national markets.
Market Restraints
- HDPE and PET resin cost volatility:Petrochemical feedstock price swings compress margin buffers for converters operating on fixed hospital procurement contracts.
- Cross-border regulatory friction:Divergent national interpretations of EMA medical device packaging standards create compliance complexity for pan-European suppliers.
- Glass and aluminum substitution threat:Premium cosmetic and pharmaceutical brands migrate toward perceived sustainable alternatives in consumer-facing segments.
Strategic Opportunities
- Aviation and hospitality travel-size formats:Portable sub-100 mL bottles address TSA-compliant carry-on requirements and hotel amenity replacement cycles.
- Closed-loop recycling infrastructure:EU Green Deal investment streams enable bottle-to-bottle rPET qualification for clinical-grade applications.
- Direct hospital procurement channel development:Bypassing distributor markups captures margin from consolidated healthcare purchasing organizations.
Industry Challenges
- Bio-based polymer certification timelines:Industrial compostability validation under EN 13432 delays time-to-market for novel material launches.
- Pump mechanism supply concentration:Dependency on specialized European and Asian closure component suppliers exposes finished goods producers to allocation risk.
- Legacy injection molding asset reconfiguration:Retrofitting equipment for thinner-wall lightweighting designs demands capital deployment amid uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitizer Bottles Market |
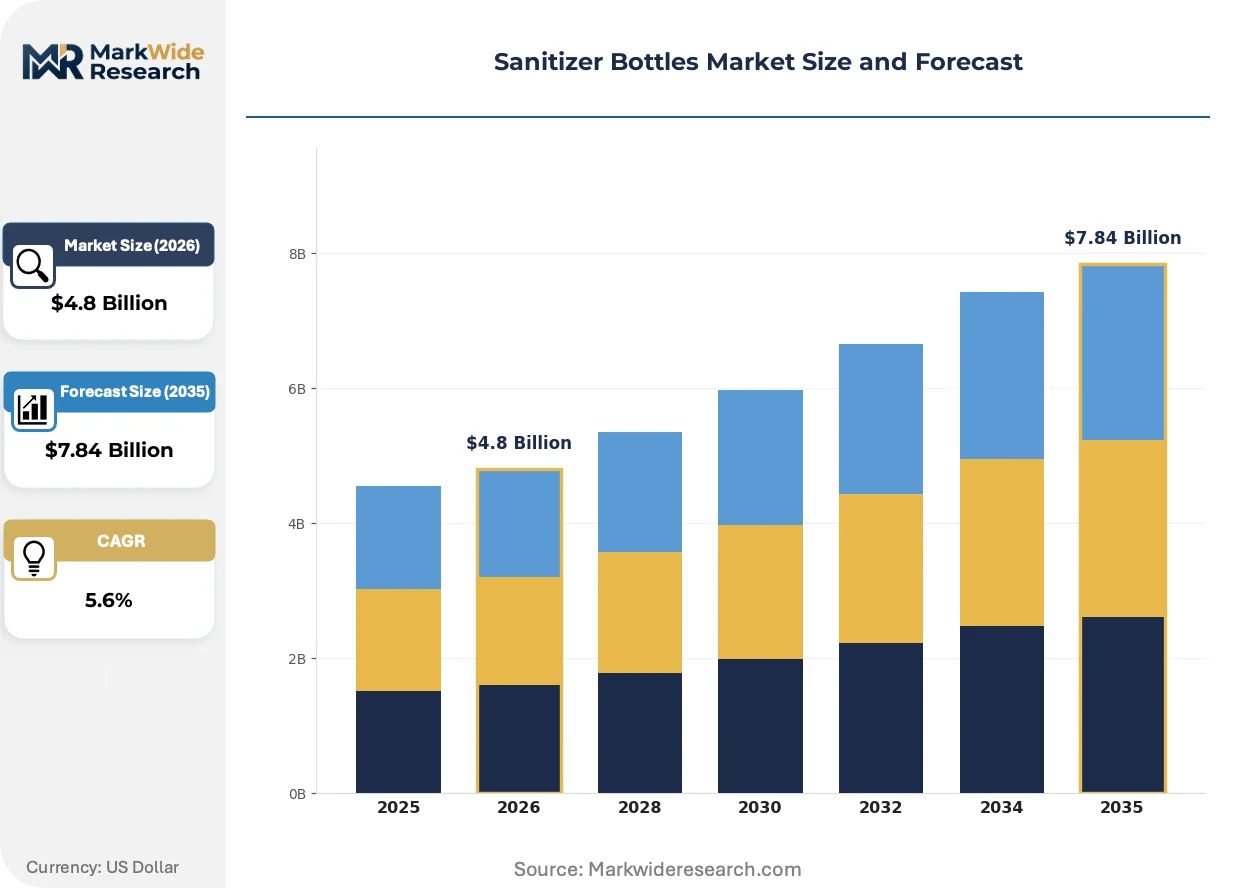
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Bottles, Bulk Containers, Travel Size, Refillable Bottles Material: Plastic, Glass, Aluminum, Bio-based Materials Closure Type: Pump Dispenser, Flip Top, Screw Cap, Spray Cap Distribution Channel: Online Retail, Supermarkets, Pharmacies, Wholesale |
| Companies Covered | GOJO Industries, Procter & Gamble Company, Reckitt Benckiser Group, 3M Company, Unilever, Henkel AG & Co. KGaA, Kimberly-Clark Corporation, Colgate-Palmolive Company, Vi-Jon Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitizer Bottles Market Evolving Landscape
Material science breakthroughs and regulatory pressure are converging to reshape sanitizer bottle design specifications, with sustainability metrics now embedded in procurement scoring rubrics alongside unit economics.
Mono-material PET bottle construction is unifying previously multi-component designs into single-polymer formats. Healthcare procurement teams in Germany and France are specifying these structures to streamline recycling streams. This unification is compressing converter technical development cycles while eliminating separation steps in municipal recovery facilities.
REACH Annex XVII restrictions on intentionally added microplastics are extending to closure mechanisms and label adhesives. European converters must reformulate pump dispenser components or face market exclusion. Suppliers with captive polymer compounding capabilities are internalizing compliance costs faster than merchant market dependent competitors.
Hospital purchasing organizations are consolidating supplier rosters and demanding audited lifecycle carbon footprints alongside unit pricing. Tier-one distributors in the United Kingdom are losing share to direct manufacturer contracts that bundle bottle supply with formulation logistics. This concentration is most visible in National Health Service supply chain reconfigurations where procurement autonomy has centralized since 2023.
Sanitizer Bottles Market Segmentation
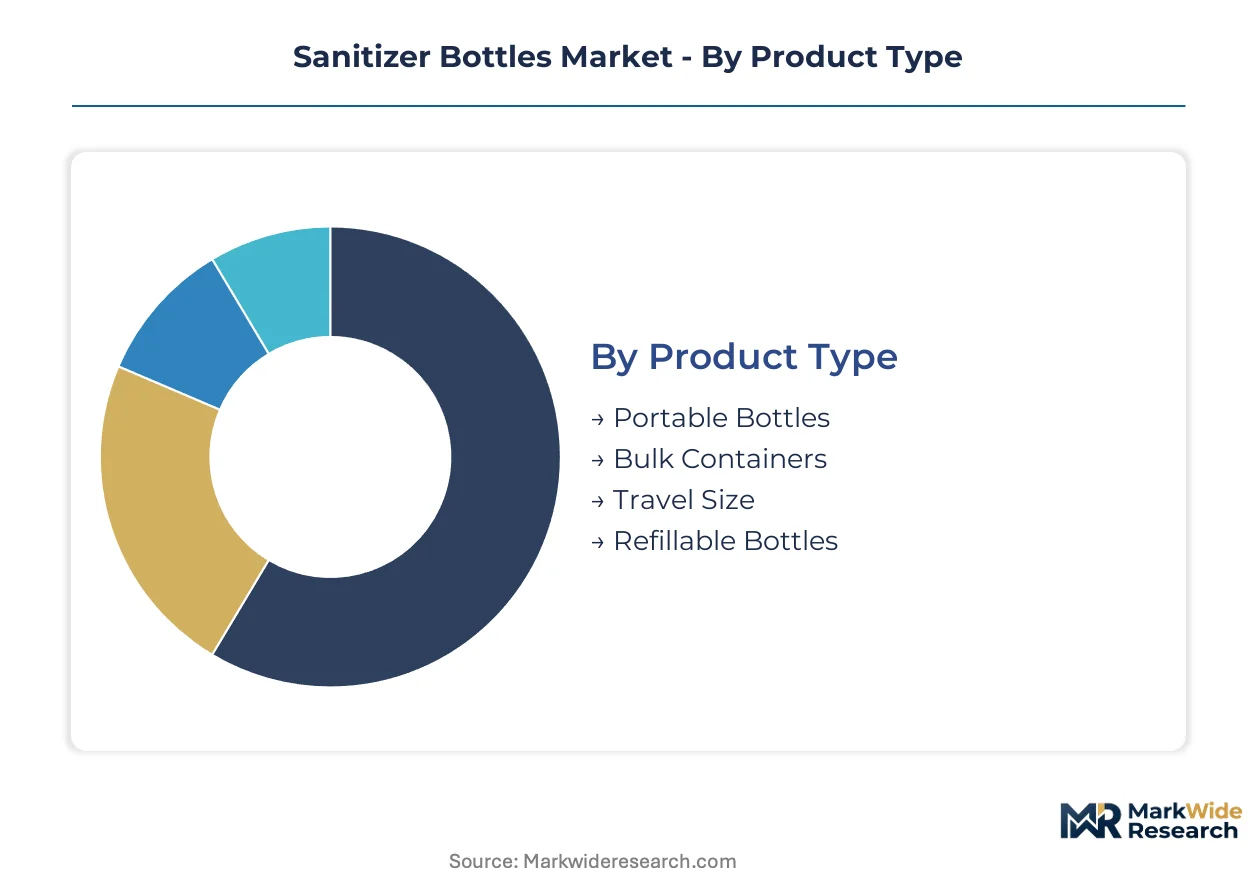
Sanitizer bottle procurement diverges sharply across clinical compliance requirements, consumer convenience preferences, and sustainability mandates. Understanding these segment boundaries reveals where converters can capture premium positioning versus commodity volume.
Product Type:
Standardization dominates portable and travel formats, while bulk and refillable designs demand customization for institutional dispensing systems and brand-specific aesthetics.
- Portable Bottles:Rigid HDPE or PET containers ranging 100-500 mL with ergonomic grip contours for healthcare worker mobility. German hospital procurement teams specify these for ward-level placement under infection control protocols. Demand concentrates in clinical settings where point-of-care accessibility reduces cross-contamination risk.
- Bulk Containers:High-capacity 1-5 L HDPE canisters with integrated handles and DIN 51 standard neck finishes for automated filling lines. French healthcare purchasing organizations favor these for central pharmacy dispensing to satellite units. Institutional cost pressures favor larger formats that minimize per-dose packaging overhead.
- Travel Size:Sub-100 mL TSA-compliant bottles with leak-proof seals for aviation and hospitality amenity programs.
- Refillable Bottles:Durable PET or bio-polymer vessels designed for 50+ use cycles in premium consumer and corporate branding applications.
Leading the category by volume: Portable Bottles. Growing fastest: Refillable Bottles.
Material:
Cost tiers separate commodity petrochemical resins from certified sustainable alternatives, with performance requirements dictating selection for specific end-use exposures.
- Plastic:HDPE and PET resins dominate through drop resistance, chemical compatibility with alcohol-based formulations, and blow-molding cost efficiency. REACH Annex XVII compliance is forcing European converters toward phthalate-free resin grades. Hospital procurement in the United Kingdom increasingly mandates recycled content minimums.
- Bio-based Materials:PLA and bio-PE derived from sugarcane or corn starch address Scope 3 emissions targets for brand owners with net-zero commitments. EN 13432 industrial compostability certification delays market entry but commands 15-30% price premiums in sustainable cosmetics. German retailers lead bio-based shelf space allocation.
- Glass:Borosilicate and soda-lime containers for premium pharmaceutical and cosmetic positioning where perceived purity outweighs fragility.
- Aluminum:Lightweight, infinitely recyclable metal bottles gaining traction in outdoor recreation and luxury hospitality verticals.
Dominating by installed base: Plastic. Steepest expansion trajectory: Bio-based Materials.
Closure Type:
Application context determines mechanism selection, with precision dosing commanding healthcare premiums and simplicity driving consumer mass market adoption.
- Pump Dispenser:Metered-dose mechanisms delivering 1.0-2.0 mL per actuation with lockable neck rings for transport security. French and German healthcare facilities specify these for hand hygiene stations to reduce formulation waste and ensure compliance with EN 1500 testing protocols. Procurement contracts bundle pump and bottle sourcing to guarantee compatibility.
- Spray Cap:Fine-mist atomizers for surface disinfectant application in clinical and food service environments. United Kingdom National Health Service tender documents increasingly require spray formats for environmental cleaning protocols. Surface sanitation protocol expansion drives format adoption beyond traditional hand hygiene.
- Flip Top:Hinged polypropylene closures for single-handed operation in high-frequency consumer use.
- Screw Cap:Standard threaded closures for bulk institutional formats and economy consumer positioning.
Highest healthcare procurement share: Pump Dispenser. Gaining share fastest: Spray Cap.
Distribution Channel:
Customer type and order scale determine channel economics, with direct institutional contracts displacing traditional distributor intermediaries in consolidated healthcare systems.
- Wholesale:Pallet-scale supply to hospital purchasing organizations and industrial cleaning contractors with negotiated annual volume commitments. German hospital alliances leverage consolidated procurement to extract 12-18% price concessions from converter direct contracts. Distributor markups face compression as manufacturers build captive logistics capabilities.
- Pharmacies:Community and hospital pharmacy chains serving individual consumers and small clinical practices with immediate availability requirements. French pharmacy regulatory framework restricts certain sanitizer formulations to pharmacy-only distribution, preserving channel relevance.
- Online Retail:Direct-to-consumer and B2B platforms enabling private label and specialty brand market entry with reduced shelf access barriers.
- Supermarkets:Mass retail shelf placement for consumer household brands with high-velocity replenishment cycles.
Largest volume throughput: Wholesale. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in Jebel Ali and Ras Al Khaimah are drawing blow-molding equipment investments from European converters seeking tariff-advantaged export platforms into African and South Asian markets.
Germany
Hospital procurement alliances in North Rhine-Westphalia and Bavaria are consolidating sanitizer bottle contracts under centralized NHS-style frameworks. ECHA REACH Annex XVII enforcement is disqualifying non-compliant converters from tender eligibility. Stuttgart's packaging cluster hosts specialized pump mechanism suppliers serving French and Dutch hospital systems.
United States
FDA OTC drug monograph compliance costs are filtering smaller converters from institutional channels toward private-label consumer retail. EPA surface disinfectant labeling requirements create dual regulatory burden for multi-application suppliers. Ohio and Illinois injection molding corridors house captive production for GOJO Industries and Kimberly-Clark direct hospital contracts.
France
ANSM medical device packaging standards are tightening documentation requirements for clinical-grade sanitizer bottles. Île-de-France hospital purchasing organizations are mandating audited lifecycle carbon footprints alongside unit pricing. Lyon-based converters are qualifying mono-material PET designs for National Health Service supply chain reconfigurations.
China
NMPA medical device classification for clinical sanitizer packaging is extending registration timelines for imported formats. Yangtze River Delta blow-molding capacity is pivoting toward bio-based PLA compounding for European export. Zhejiang province converters are absorbing HDPE resin cost volatility through state-backed raw material stabilization funds.
United Kingdom
NHS Supply Chain centralization since 2023 is displacing tier-one distributors with direct manufacturer contracts. MHRA post-Brexit regulatory autonomy is diverging from EMA medical device packaging standards in labeling requirements. Manchester and Birmingham industrial zones host contract manufacturers serving consolidated healthcare purchasing organizations.
Sanitizer Bottles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing strata. Market structure shows moderate consolidation with three to five national-scale converters capturing institutional procurement volumes. Strategic archetypes include captive manufacturing conglomerates, regional contract converters, and bio-based material specialists. Capacity expansion and backward integration into resin compounding represent dominant competitive moves.
Among diversified consumer goods conglomerates, Procter & Gamble Company and Unilever occupy positions spanning institutional and consumer channels. GOJO Industries exemplifies the captive manufacturing archetype with in-house blow-molding and formulation logistics. Henkel AG & Co. KGaA anchors European market access through localized production networks that mitigate cross-border regulatory friction.
| Leading Market Players |
|---|
| GOJO Industries |
| Procter & Gamble Company |
| Reckitt Benckiser Group |
| 3M Company |
| Unilever |
| Henkel AG & Co. KGaA |
| Kimberly-Clark Corporation |
| Colgate-Palmolive Company |
| Vi-Jon Laboratories |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Germany and France anchor European supply networks, translating captive resin compounding capabilities into pricing discipline that resists commodity volatility from merchant-market-dependent competitors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pump-dispenser assemblies sourced from Stuttgart-area mechanism specialists serving French hospital procurement deadlines. Three-tier pricing structure across premium certified-clinical, standard institutional, and economy private-label tiers separates EN 1500-compliant formats from generic consumer alternatives. Cost compression in economy tiers intensifies as Chinese blow-molders absorb HDPE resin volatility through state-backed stabilization funds. Hospital purchasing organizations exhibit lowest price sensitivity due to bundled formulation-logistics contracts, while aviation amenity buyers negotiate aggressively on sub-100 mL travel formats.
Supply Chain Analysis
EU Green Deal domestic-content mandates for recycled and bio-based polymers are reshaping sourcing toward Jebel Ali free-zone converters and Yangtze River Delta PLA compounders. Raw material flows draw from Saudi petrochemical feedstocks, Zhejiang bio-PE fermentation capacity, and Rhineland rPET qualification facilities. Single-source vulnerability concentrates in European pump mechanism suppliers exposing finished goods producers to allocation risk during demand spikes. Distribution runs through consolidated healthcare purchasing organizations in North Rhine-Westphalia and Bavaria displacing traditional tier-one distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into resin compounding and captive pump mechanism production represents the dominant competitive lever as converters race to internalize REACH compliance costs and secure supply continuity.
For Market Incumbents: Acquire specialized European pump mechanism suppliers to eliminate allocation exposure and bundle closure-bottle compatibility guarantees for French hospital tenders. Expand rPET qualification capacity in Rhineland facilities to capture NHS Supply Chain recycled-content mandates. Defend against Chinese bio-PE cost advantages by embedding lifecycle carbon auditing into direct procurement contracts. For New Entrants and Emerging Players: The mid-tier price gap between premium clinical-certified and economy private-label formats offers entry space for EN 13432-certified bio-based specialists targeting German retailer sustainability scorecards. White-space concentrates in aviation travel-size segments where TSA-compliant leak-proof engineering commands design premiums. Pursue white-label partnerships with Lyon-based converters lacking direct hospital sales capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light brand owners with pharmacy-regulatory pathway expertise in France and consolidated distributor relationships in the United Kingdom. Long-term viability hinges on material transition optionality between petrochemical and bio-based feedstocks. Monitor EN 1500 testing protocol revisions as inflection signals for pump-dispenser format demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE and bio-PE production internalizes REACH Annex XVII compliance premiums faster than merchant sourcing. |
| Mono-Material PET Design Qualification | Single-polymer construction streamlines German municipal recycling streams and satisfies healthcare procurement scoring rubrics. |
| Direct Hospital Procurement Channel Development | Bypassing distributor markups captures margin from NHS Supply Chain centralization and Bavarian purchasing alliances. |
| Aviation Travel-Size Format Engineering | TSA-compliant sub-100 mL designs address hospitality amenity replacement cycles and carry-on regulatory requirements. |
| Pump Mechanism Supply Security Investment | Stuttgart-area component captive production eliminates allocation risk during French hospital tender fulfillment peaks. |
Research Methodology
Trade databases, ECHA REACH registration filings, and hospital procurement tender records formed the secondary backbone for supply chain mapping and regulatory trajectory assessment. Primary interviews with blow-molding plant managers, healthcare GPO contracts managers, pump mechanism procurement leads, and sustainability officers at German retailers combined with secondary validation to triangulate volume estimates. Bottom-up capacity assessments across Yangtze River Delta and Rhineland production clusters were cross-checked against top-down demand modeling from NHS Supply Chain and French ANSM reporting.
Historical trendline analysis of resin cost pass-through patterns and hospital procurement contract structures anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, material grade tier, closure mechanism complexity, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted volume projections and value-chain margin compression assumptions. Forecast inputs included HDPE and bio-PE feedstock cost trajectories, EMA medical device packaging standard revision timelines, and aviation passenger traffic recovery patterns affecting travel-size demand.
Inputs from customs records and hospital procurement databases were available through the study window; gaps in real-time pump mechanism inventory data introduce uncertainty bands around allocation risk assessments. Forecasts reflect documented assumptions regarding REACH Annex XVII enforcement intensity and EU Green Deal investment flow timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
VCI Bags Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Telescope Box Market
Packaging Containers
Candle Box Market
Packaging Containers
Portion Packs Market
Packaging Containers
Cooler Box Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Bottles Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Child Resistant Bottles Market