
 Euro Box Market | 2026-2036
Euro Box Market Size, Share, and Industry Trends Forecast 2026-2036
Euro Box Market Foresight
Modular container bundling is pivoting procurement patterns across European supply chains. Smurfit Kappa Group leverages its integrated paper-based packaging network to dominate corrugated Euro box supply for FMCG clients. DS Smith Plc anchors its position through circular design capabilities and closed-loop recycling infrastructure. Mondi Plc differentiates via performance-engineered kraftliner solutions that reduce material weight without sacrificing stack strength.
A Euro box denotes a standardized reusable or single-use container engineered to European footprint dimensions, typically manufactured from corrugated board, injection-molded polypropylene, or oriented strand board, with primary load ratings between 15 kg and 50 kg depending on wall construction and flute profile. Cardboard variants retain the largest volume share but face margin compression from virgin fiber costs, while plastic Euro boxes capture accelerated replacement cycles in closed-loop automotive and pharmaceutical logistics. The E-commerce end-user segment commands premium pricing for damage-resistant, return-optimized designs, whereas the Storage application pool remains fragmented across small-format wholesalers with limited brand loyalty.
The EU Packaging and Packaging Waste Regulation (PPWR) and REACH compliance protocols administered by ECHA are tightening material traceability and recyclability verification requirements for all container classes sold within the European Economic Area. Germany's national packaging regulator, the Zentrale Stelle Verpackungsregister (ZSVR), enforces strict dual-system participation fees that directly influence total cost of ownership calculations for reusable versus single-use formats. Stakeholders must monitor how PPWR implementation timelines and national transposition variations reshape capital allocation between fiber-based and polymer-based production assets.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across European supply chains as manufacturers retool for mandatory recyclability thresholds and recycled content minimums that take effect across staggered national timelines.
Growth Catalysts
- PPWR Compliance Mandates:Germany's Zentrale Stelle Verpackungsregister enforces dual-system participation fees that tilt total cost of ownership calculations toward reusable formats, accelerating closed-loop container adoption in automotive logistics corridors.
- Automotive Closed-Loop Expansion:Parts manufacturers along the Stuttgart-Wolfsburg industrial belt are scaling reusable polypropylene container programs to meet just-in-sequence delivery requirements while reducing single-use packaging waste penalties.
- Corrugated Lightweighting:Performance-engineered kraftliner solutions are cutting material weights by 15-20% without stack strength degradation, enabling freight cost savings that offset virgin fiber price volatility for FMCG distributors.
Market Restraints
- Virgin Fiber Cost Volatility:European pulp prices swing with Nordic supply disruptions and energy input spikes, compressing margins for corrugated Euro box producers who lack integrated paper mill capacity.
- Automotive Demand Concentration:German OEM procurement power concentrates volume allocation among three dominant reusable container suppliers, creating barrier-to-entry effects for mid-tier molders in France and Italy.
- Polypropylene Substitution Ceiling:Temperature-sensitive pharmaceutical shipments face material limitations as polypropylene Euro boxes lack the thermal stability of expanded polystyrene alternatives for sub-zero cold chain legs.
Strategic Opportunities
- Spanish Pharmaceutical Logistics:Barcelona and Madrid distribution hubs show underpenetrated reusable container adoption relative to northern European benchmarks, creating whitespace for closed-loop service providers.
- Digital-Physical Integration:RFID-embedded Euro boxes combined with blockchain traceability layers are enabling outcome-based container management contracts that shift revenue from unit sales to utilization guarantees.
- E-commerce Damage-Resistant Designs:Return-optimized corrugated constructions with reinforced corners capture premium pricing from omnichannel retailers facing last-mile handling stress failures.
Industry Challenges
- Cross-Border Compliance Fragmentation:National transposition variations of PPWR timelines create certification complexity for pan-European container fleets, requiring redundant testing protocols for France's extended producer responsibility schemes versus Dutch packaging waste fund structures.
- Retrofit Capex Burden:Converting legacy injection molding lines to handle post-consumer recycled polypropylene feedstock demands furnace upgrades and quality control sensor installations that strain mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Euro Box Market |
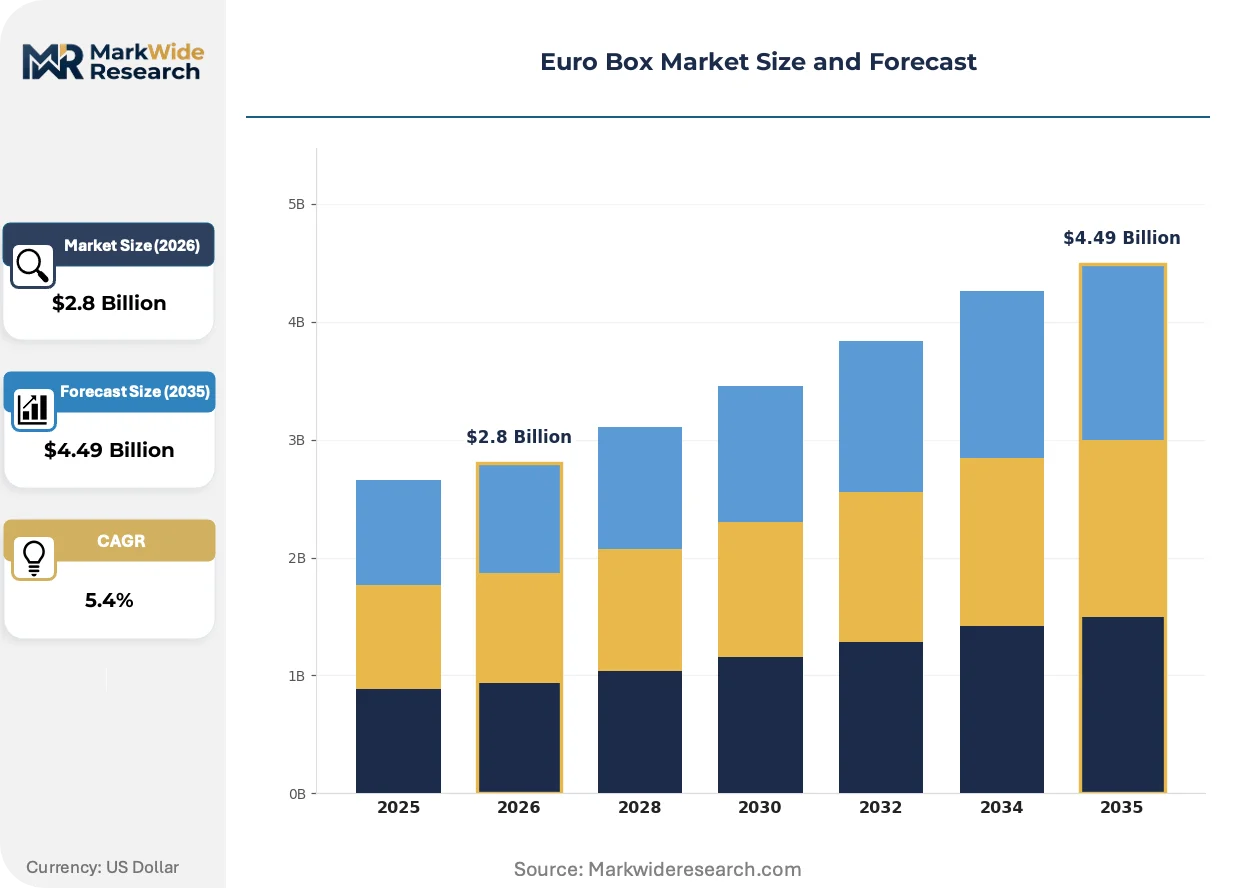
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Cardboard, Wooden, Metal End User: Retail, E-commerce, Logistics, Manufacturing Application: Storage, Shipping, Packaging, Display Size: Small, Medium, Large, Custom |
| Companies Covered | Smurfit Kappa Group, DS Smith Plc, Mondi Plc, Stora Enso Oyj, International Paper Co., WestRock Co., Georgia Pacific LLC, VPK Group, Model Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Euro Box Market Shifts & Advancements
Material science advances and digital layer integration are redefining how European logistics operators specify, track, and monetize container assets across multi-modal supply chains.
RFID-tagged Euro boxes with embedded pressure sensors are automating inventory reconciliation and damage detection at automotive inbound receiving docks. Tier-1 suppliers in Germany's Baden-Württemberg region are deploying these smart containers at scale, compressing manual inspection labor and enabling predictive replacement scheduling based on cumulative stress data rather than calendar-based rotation.
REACH compliance protocols administered by ECHA are tightening material traceability requirements for all polymer-based containers sold within the European Economic Area. Industrial consequence includes mandatory substance-of-very-high-concern screening across supply tiers, with pharmaceutical logistics operators in the Netherlands and Belgium most affected as they requalify container grades ahead of 2025 registration deadlines.
Consolidated procurement desks at major FMCG distributors are unbundling container supply from logistics service contracts, forcing molders and corrugated converters to bid equipment-only against full-service rental models. This pattern is most visible in French retail supply chains where Carrefour and Auchan central buying teams have shifted to direct container ownership with third-party pool management, compressing margins for integrated providers while opening volume opportunities for specialized manufacturers.
Euro Box Market Segmentation
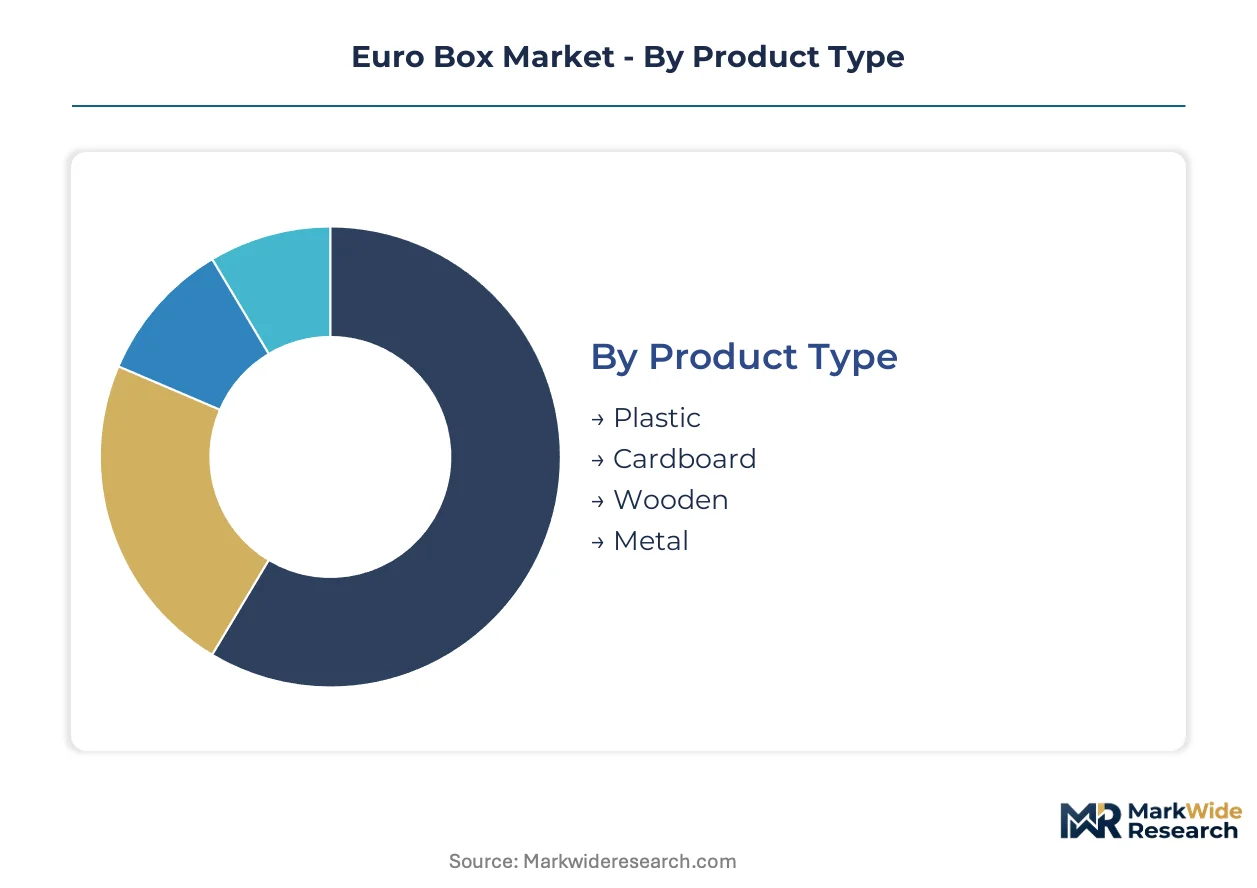
Euro box procurement patterns diverge sharply across material classes and use-case scenarios, with automotive logistics demanding durability cycles that FMCG distribution cannot justify. Standardization pressure from EU PPWR compliance is collapsing SKU proliferation in favor of interoperable formats that traverse multiple handler networks without reconfiguration.
Product Type:
Material selection tracks the reusability-versus-disposability calculus that German automotive OEMs pioneered, with virgin fiber cost volatility and polymer feedstock quality tiers fragmenting supplier capabilities across the value chain.
- Plastic:Injection-molded polypropylene containers withstand 500+ use cycles in closed-loop automotive logistics. Stuttgart-based Tier-1 suppliers are mandating RFID-embedded variants for just-in-sequence tracking, with ZSVR dual-system fees accelerating adoption versus single-use alternatives.
- Cardboard:Corrugated kraftliner constructions dominate FMCG volume through Smurfit Kappa's integrated mill network. Lightweighting programs have cut material weights by 15-20% without stack strength degradation, though Nordic pulp price swings compress margins for non-integrated converters.
- Wooden:Oriented strand board variants serve agricultural and heavy-machinery segments requiring moisture-resistant pallet stacking. Limited reusability confines demand to export-oriented German and Dutch port logistics.
- Metal:Steel and aluminum Euro boxes command premium positioning for hazardous material containment and pharmaceutical cold chain legs where structural integrity overrides weight penalties.
Most installed capacity flows through Cardboard. Expansion is steepest in Plastic.
End User:
Procurement authority centralization distinguishes volume allocation, with consolidated buying desks at French retail chains unbundling container supply from logistics contracts while automotive OEMs retain integrated rental-service models.
- Retail:Carrefour and Auchan central teams have shifted to direct container ownership with third-party pool management, compressing margins for full-service providers while opening volume for specialized manufacturers.
- E-commerce:Omnichannel retailers face last-mile handling stress failures that damage-resistant corrugated constructions with reinforced corners address, capturing premium pricing for return-optimized designs.
- Logistics:Third-party providers across the Stuttgart-Wolfsburg corridor are scaling reusable polypropylene programs to meet just-in-sequence delivery requirements while reducing single-use waste penalties.
- Manufacturing:Parts manufacturers along Germany's industrial belt deploy smart containers with embedded pressure sensors at automotive inbound receiving docks, automating inventory reconciliation.
Logistics commands the deepest contract penetration. E-commerce is climbing the fastest.
Application:
Functional specification intensity varies by stress exposure, with shipping applications demanding impact resistance that storage-oriented formats sacrifice for cube efficiency and nesting ratio optimization.
- Storage:Small-format wholesalers with limited brand loyalty dominate this fragmented pool, prioritizing nesting efficiency and warehouse footprint minimization over durability ratings.
- Shipping:Multi-modal stress exposure drives specification toward corrugated lightweighting and polymer reinforcement, with Barcelona and Madrid distribution hubs showing underpenetrated reusable adoption relative to northern benchmarks.
- Packaging:REACH compliance protocols administered by ECHA are tightening material traceability requirements, with pharmaceutical logistics operators in the Netherlands and Belgium requalifying container grades ahead of registration deadlines.
- Display:Retail-ready formats with printed graphics integration serve French and German FMCG promotional cycles, requiring food-contact-safe inks and rapid design-to-shelf turnaround.
Shipping absorbs the highest specification investment. Display is gaining share fastest.
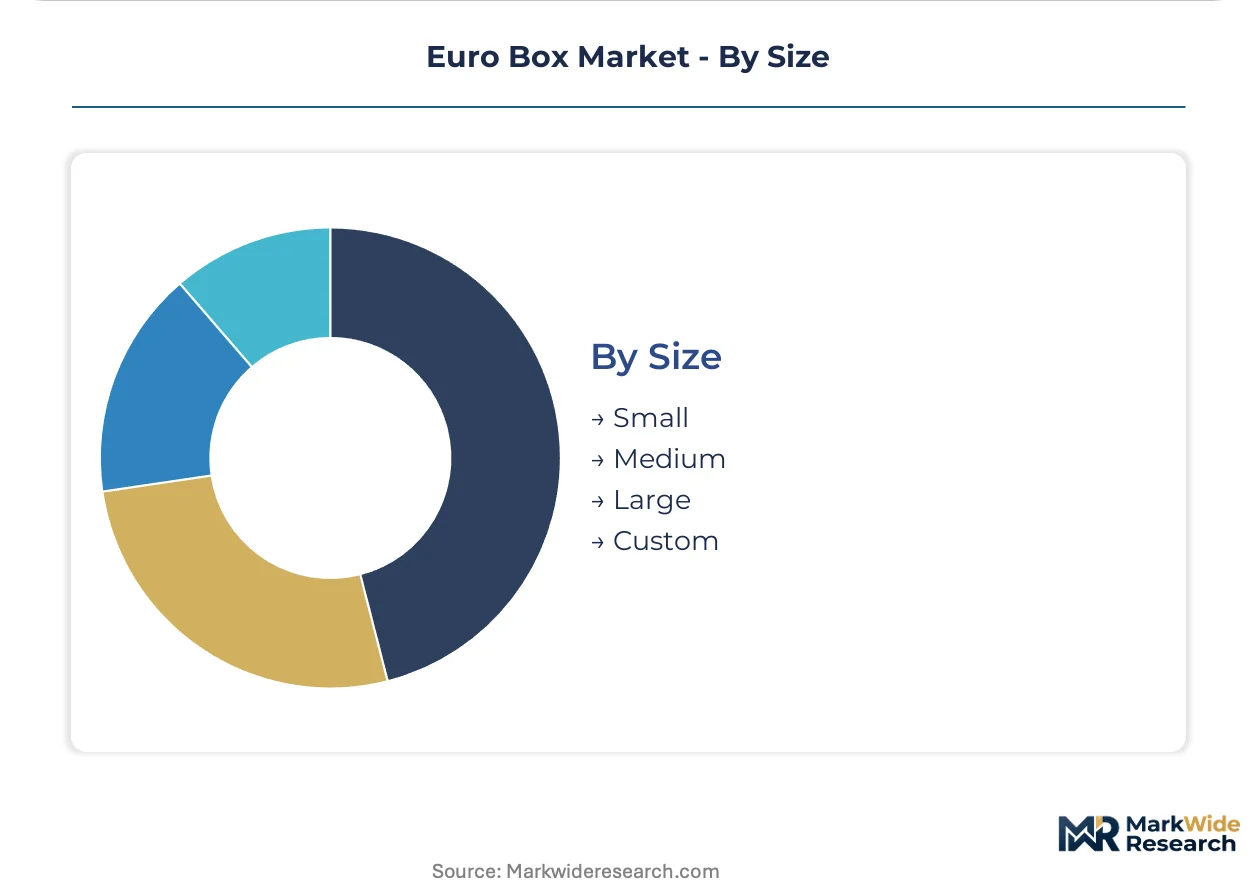
Size:
Dimensional standardization battles customization demand as EU PPWR mandates interoperability, with automotive OEMs enforcing strict footprint compliance while pharmaceutical cold chain operators require thermal insert accommodation.
- Small:Pharmaceutical vial and component shipments favor compact footprints with thermal stability limitations, as polypropylene alternatives lack expanded polystyrene performance for sub-zero legs.
- Medium:The automotive standard for just-in-sequence delivery, with German OEM procurement power concentrating volume allocation among three dominant reusable container suppliers.
- Large:Bulk agricultural and machinery parts shipments favor this format, though freight cost economics limit adoption where weight-based tariffs apply.
- Custom:E-commerce damage-resistant designs and pharmaceutical thermal insert configurations drive specification divergence, with molders converting legacy injection lines to handle post-consumer recycled feedstock.
Medium size dominates fleet deployment. Custom formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Euro Box Market traces its standardization lineage to post-war German automotive logistics, where the VDA footprint specifications first unified container dimensions for just-in-sequence assembly line delivery.
Germany
Automotive OEM procurement power concentrates reusable container allocation among dominant suppliers serving the Stuttgart-Wolfsburg industrial corridor. The Zentrale Stelle Verpackungsregister enforces dual-system participation fees that tilt total cost of ownership toward closed-loop formats. Baden-Württemberg-based Tier-1 suppliers now deploy RFID-embedded pressure-sensor containers at scale.
France
Consolidated retail procurement desks at Carrefour and Auchan have unbundled container supply from logistics service contracts. Extended producer responsibility schemes administered by the national environmental agency create certification complexity distinct from Dutch packaging waste fund structures. Île-de-France distribution hubs prioritize direct container ownership with third-party pool management.
Spain
Barcelona and Madrid pharmaceutical distribution hubs show underpenetrated reusable container adoption relative to northern European benchmarks. REACH compliance protocols from ECHA drive container grade requalification ahead of registration deadlines. The Mediterranean logistics corridor is attracting closed-loop service providers seeking whitespace expansion.
Netherlands
Pharmaceutical logistics operators in Rotterdam and Amsterdam face the strictest ECHA material traceability requirements for polymer-based containers. The Dutch packaging waste fund structure creates divergent compliance economics versus French EPR schemes. Belgian border logistics clusters are synchronizing qualification protocols to maintain pan-European fleet interoperability.
Italy
Mid-tier molders in the Emilia-Romagna automotive supply base confront barrier-to-entry effects from German OEM procurement concentration. Virgin fiber cost volatility from Nordic pulp disruptions compresses margins for corrugated converters lacking integrated mill capacity. Northern Italian packaging converters are retooling for PPWR recyclability thresholds ahead of national transposition deadlines.
Euro Box Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and material science capabilities. The vendor base organizes into three tiers: integrated paperboard producers with captive fiber supply, specialized injection molders serving closed-loop automotive programs, and regional corrugated converters competing on turnaround speed. Strategic moves center on lightweighting R&D partnerships and RFID-embedded smart container development.
Within the integrated paperboard tier, Smurfit Kappa Group and DS Smith Plc exemplify divergent approaches to circular infrastructure. Smurfit Kappa leverages its mill network dominance across European FMCG corridors, while DS Smith anchors its positioning through closed-loop recycling capabilities. Mondi Plc occupies a distinct specialization vector in performance-engineered kraftliner solutions that reduce material weight without stack strength degradation.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith Plc |
| Mondi Plc |
| Stora Enso Oyj |
| International Paper Co. |
| WestRock Co. |
| Georgia Pacific LLC |
| VPK Group |
| Model Holding AG |
| Others |
Supply & Pricing Matrix
Tooling engineer density across Stuttgart-Baden-Württemberg feeds labor-cost differentials that widen pricing-tier spreads between precision-molded automotive containers and commodity corrugated formats. ZSVR dual-system fee structures amplify these spreads by embedding compliance costs into total cost of ownership calculations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with RFID-embedded smart containers commanding premium positioning against basic corrugated alternatives. Price differentiation rests on certification grade for REACH compliance and volume scale commitments from consolidated retail buyers. Pricing pressure stems from virgin fiber cost volatility compressing margins for non-integrated converters. Small-format wholesalers in the storage segment exhibit highest price sensitivity, while automotive OEMs prioritize durability cycles over unit economics.
Supply Chain Analysis
Polypropylene resin supply rests on German petrochemical complexes and Benelux polymer producers, with Nordic pulp mills feeding kraftliner demand for corrugated production. Virgin fiber, recycled polymer feedstock, and pressure-sensor RFID components constitute critical input dependencies. Single-source vulnerability concentrates around specialized injection-molding equipment for automotive-grade containers. Distribution runs through integrated paperboard producers serving FMCG corridors and third-party pool managers handling closed-loop logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on lightweighting R&D partnerships that cut material weights without stack strength degradation, alongside premium-tier shifts toward smart container contracts with utilization guarantees.
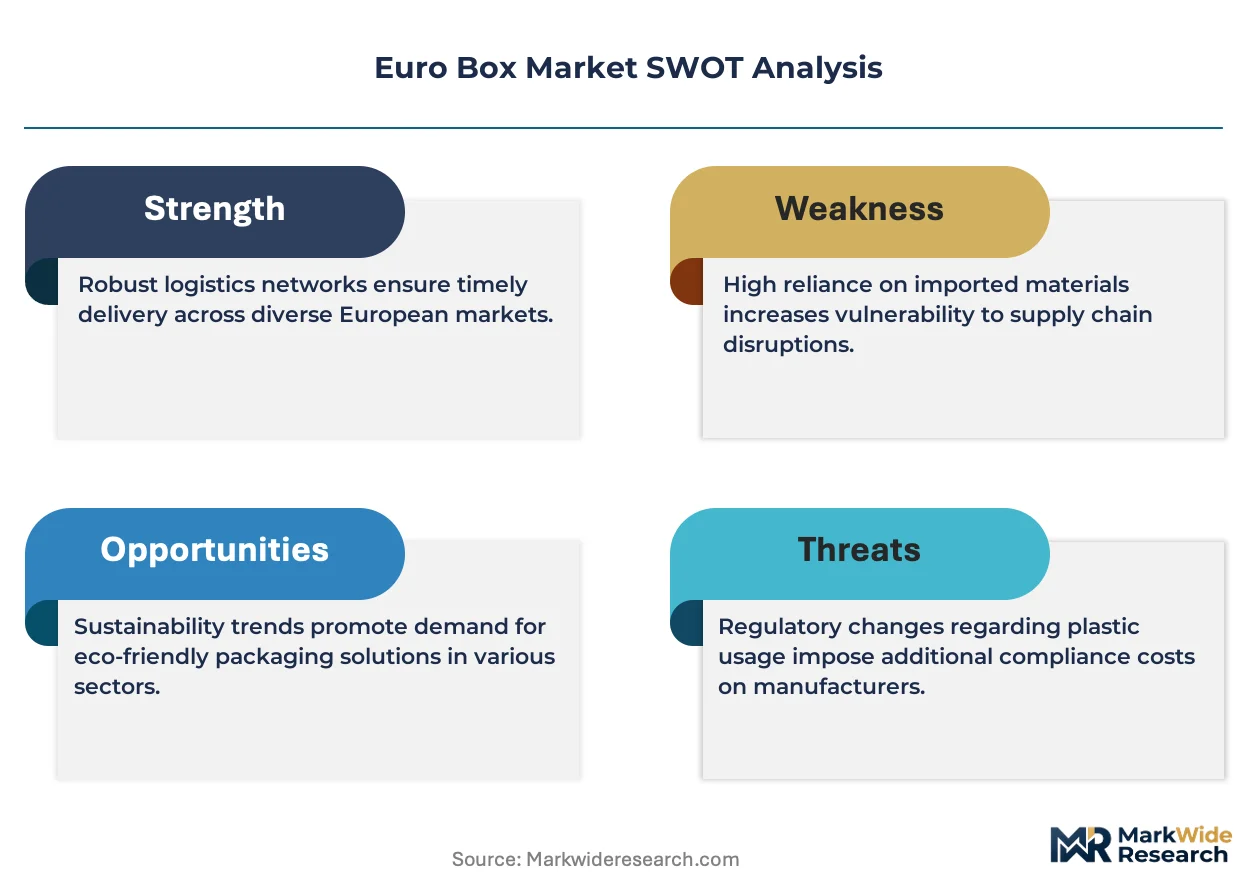
For Market Incumbents: Hedge against virgin fiber cost volatility through backward integration into captive pulp supply or long-term offtake agreements with Nordic mills. Accelerate RFID-embedded container development to defend against specialized injection molders capturing automotive closed-loop share. Prioritize certification investment for REACH compliance ahead of ECHA registration deadlines. For New Entrants and Emerging Players: Launch via direct container ownership models targeting Spanish pharmaceutical distribution hubs in Barcelona and Madrid, where reusable adoption lags northern European benchmarks. Pursue outcome-based management contracts that shift revenue from unit sales to utilization guarantees. Emphasize thermal stability engineering for pharmaceutical cold chain legs where polypropylene alternatives face material limitations. For Investors and Strategic Acquirers: Packaging waste management platforms are the most active acquirer in this space, consolidating pool management capabilities to serve unbundled retail procurement desks. Five-to-ten year viability favors targets with integrated recycling infrastructure and digital-physical container traceability layers. Watch for PPWR national transposition variations that reshape capital allocation between fiber-based and polymer-based production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting R&D Partnership | Performance-engineered kraftliner solutions from Mondi Plc cut material weights 15-20% without stack strength degradation. |
| RFID-Embedded Smart Container Launch | Baden-Württemberg Tier-1 suppliers deploy pressure-sensor containers to automate inventory reconciliation at automotive docks. |
| Backward Integration into Pulp Supply | Smurfit Kappa's integrated mill network insulates margins from Nordic pulp price volatility affecting non-integrated converters. |
| Closed-Loop Service Expansion | Whitespace capture in Spanish pharmaceutical hubs addresses underpenetrated reusable adoption relative to German benchmarks. |
| REACH Compliance Certification | Netherlands and Belgium pharmaceutical operators requalify container grades ahead of ECHA registration deadlines. |
Research Methodology
Coverage spans Germany, France, Spain, Netherlands, and Italy, with primary inputs from each market cluster. Primary interviews engaged supply chain directors at automotive OEMs, procurement leads at French retail chains, plant managers at corrugated converters, logistics operators across the Stuttgart-Wolfsburg corridor, and regulatory affairs specialists navigating PPWR implementation. Secondary validation drew from ZSVR compliance filings, ECHA substance registrations, EU customs trade data, and industry association reports. Bottom-up container volume estimates triangulated against top-down market sizing from production capacity analysis.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by material class, end-user vertical, application stress exposure, and dimensional format. CAGRs derived from polynomial trend fitting against historical shipment data, with cross-validation against macroeconomic drivers. Forecast inputs incorporated automotive production schedules, e-commerce penetration curves, and national PPWR transposition timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Nordic pulp supply disruptions or accelerated PPWR recycled content mandates. Projections reflect assumptions about ZSVR fee structures, ECHA registration deadlines, and automotive OEM procurement consolidation. A small set of triggers—virgin fiber cost spikes, German OEM supplier rationalization, and Spanish pharmaceutical hub expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Portion Packs Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
VCI Bags Market
Packaging Containers
Correx Trays Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Food Grade Bottles Market