
 Middle East Pallets Market | 2026-2036
Middle East Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Pallets Market Insights
Market Context with Strategic Players
Skilled logistics labor availability is reorganizing how pallet suppliers scale operations across the Gulf. CHEP Middle East leverages its pooling infrastructure to dominate rental network density in Saudi Arabia and the UAE. Emirates Pallet Factory LLC anchors domestic production capacity with in-house timber treatment and heat-treatment certification. Gulf Pallets Factory competes on custom fabrication for oilfield and industrial clients requiring non-standard dimensions.
Technical Definition and Structural Segments
A pallet is a flat transport structure built to ISO 6780 dimensions, typically fabricated from hardwood, softwood, or thermoplastic resins, designed to support goods in a stable fashion while being lifted by forklifts, pallet jacks, or conveyors. Wood remains the dominant material segment due to lower unit cost and repairability, though plastic pallet adoption accelerates in pharmaceutical and food-grade applications where hygiene standards and washability command premium positioning. Rackable and nestable types are gaining share in automated warehouse environments across the region, while standard block and stringer configurations retain volume leadership in general manufacturing and bulk commodity handling.
Regulatory Framework and Forward Outlook
Saudi Arabia's SFDA enforces traceability and sanitary requirements for pallets handling food and pharmaceutical products, while UAE's MOHAP and ESMA technical regulations mandate heat treatment or fumigation certification for wooden pallets entering food-contact supply chains. The SABER platform and Gulf Standardization Organization harmonization efforts are raising compliance costs for uncertified imports. Stakeholders must monitor evolving national treatment standards and decide whether to localize heat-treatment capacity or source from pre-certified regional suppliers.
Market Dynamics
Cold-chain logistics expansion across the Gulf Cooperation Council is restructuring pallet fleet requirements, with pharmaceutical distributors and perishable food networks demanding certified, trackable assets that comply with tightening sanitary regulations.
Growth Catalysts
- SFDA Traceability Mandates:Saudi Arabia's pharmaceutical regulator now requires documented pallet hygiene standards for drug distribution, forcing supply chain upgrades that favor certified rental pool providers over informal suppliers.
- Perishable Export Growth:UAE and Saudi fresh produce re-export hubs are scaling temperature-controlled warehousing, generating demand for plastic and composite pallets that withstand repeated sanitization cycles.
- Heat-Treatment Infrastructure:Regional sawmills are installing ISPM-15 compliant kilns to preempt SABER platform certification requirements, shortening lead times for compliant wooden pallet supply.
Market Restraints
- Softwood Input Volatility:European and CIS timber supply disruptions have compressed margins for domestic wooden pallet manufacturers dependent on imported raw material.
- Certification Cost Concentration:SABER and ESMA compliance expenses disproportionately burden small fabrication shops, consolidating production among capitalized operators with in-house testing laboratories.
- Plastic Resin Price Exposure:Polypropylene and HDPE pallet producers face margin compression from petrochemical feedstock volatility that wooden pallet competitors largely avoid.
Strategic Opportunities
- Oman and Bahrain Penetration:Underdeveloped domestic pallet manufacturing in these markets creates openings for UAE-based producers to establish satellite treatment and distribution facilities.
- Reverse Logistics Integration:E-commerce fulfillment networks are piloting pallet pooling arrangements that bundle asset tracking with last-mile container management, reducing empty-mile costs.
- Composite Material Convergence:Hybrid wood-plastic and compressed fiber pallets are capturing interest from food-contact applications seeking durability without full plastic cost premiums.
Industry Challenges
- Heat-Treatment Technician Scarcity:ISPM-15 certification requires specialized kiln operation expertise that remains concentrated among a limited pool of trained personnel across the Gulf.
- Multi-Jurisdiction Compliance:Divergent UAE emirate-level and Saudi national treatment standards force producers to maintain parallel certification documentation, lengthening order fulfillment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Pallets Market |
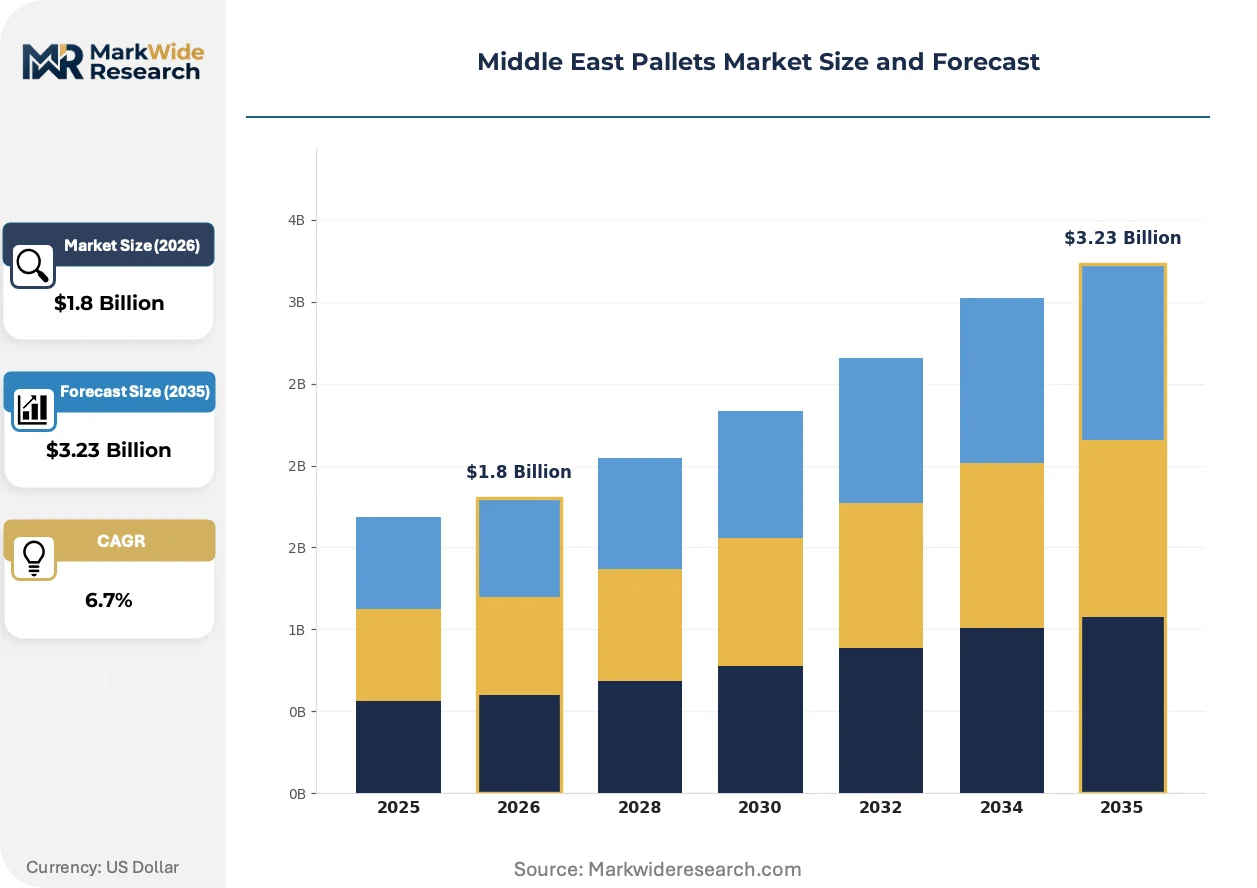
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Plastic, Metal, Composite Type: Standard, Rackable, Stackable, Nestable End User: Logistics, Retail, Manufacturing, Food & Beverage Delivery Model: Rental, Sale, Leased, Custom |
| Companies Covered | CHEP Middle East, Emirates Pallet Factory LLC, Gulf Pallets Factory, Royal Pallets Factory LLC, Al-Moajil Wooden Pallets, Palletco LLC, Delta Engineering Middle East, Wooden Pallets Factory, AlDhana Wood Industries Factory, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Pallets Market Trends and Innovations
Asset digitization and material science advances are converging to transform pallet economics in Gulf logistics networks, with implications for fleet management, regulatory compliance, and total cost of ownership calculations.
RFID-embedded and QR-coded pallets are supplanting unmarked wooden units in pharmaceutical and high-value electronics supply chains, with Dubai-based 3PLs now mandating traceable assets for contracted warehousing services. This shift compresses inventory reconciliation labor while enabling real-time location monitoring that reduces asset loss rates.
UAE's MOHAP technical regulations for food-contact materials are tightening fumigation documentation requirements, compelling importers to source exclusively from pre-certified regional suppliers rather than untreated Asian imports. Cold-chain operators are responding by consolidating procurement with rental pool providers who assume compliance liability.
Leasing arrangements are displacing outright purchase for pharmaceutical distributors operating across multiple GCC jurisdictions, as asset ownership burdens compliance staff with varying national treatment recertification schedules. This procurement pattern shift is most pronounced in Saudi Arabia's central pharmacy distribution network, where fleet standardization reduces audit complexity.
Middle East Pallets Market Segmentation
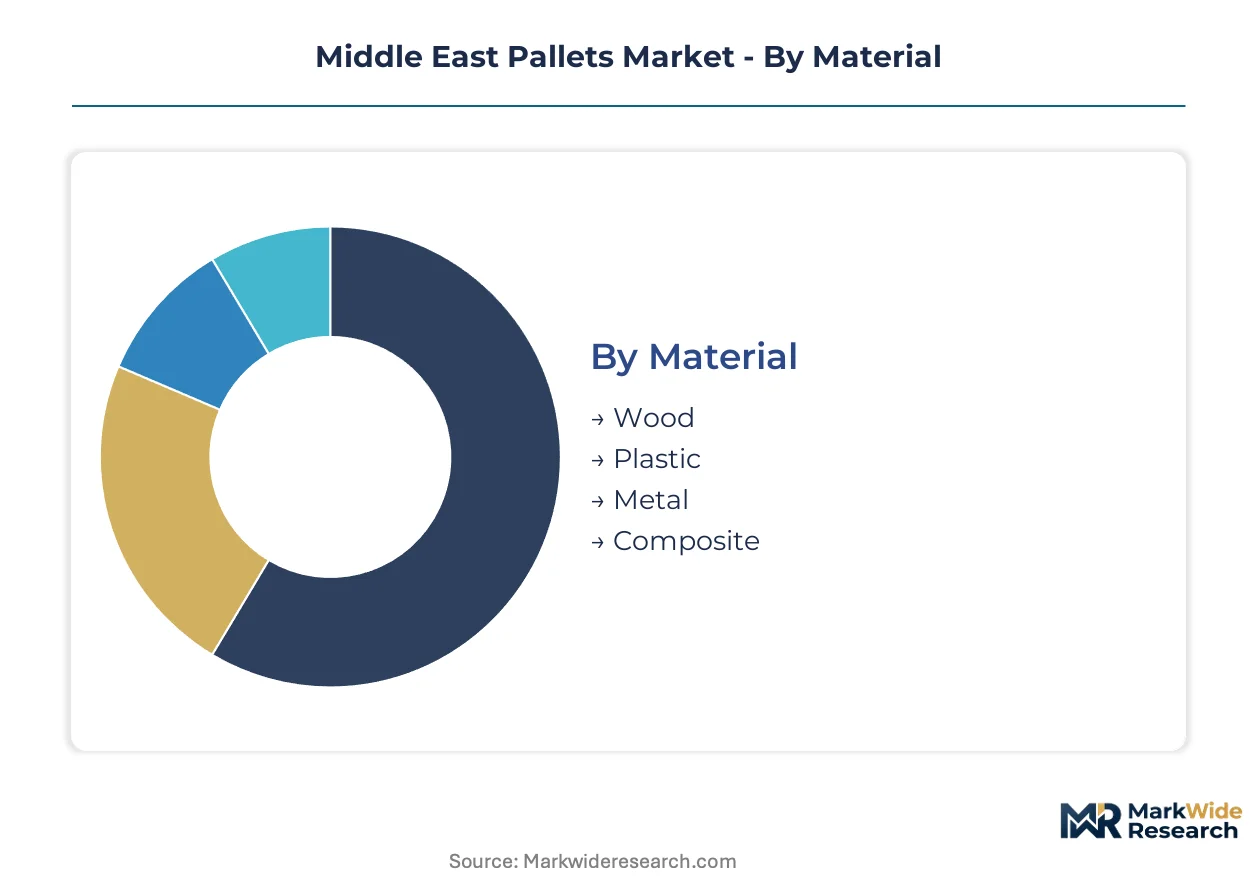
Pallet material selection in the Middle East hinges on regulatory compliance costs, cold-chain hygiene mandates, and timber import volatility. Fleet procurement decisions increasingly separate commodity bulk handling from certified pharmaceutical and food-contact applications.
Material:
Plastic and composite alternatives are exerting substitution pressure on traditional wooden pallets in sanitary-sensitive supply chains, though cost differentials preserve wood's dominance in general freight.
- Wood:Fabricated from hardwood or softwood lumber, typically conforming to ISPM-15 heat-treatment standards for cross-border movement within the GCC. Saudi Arabia's SABER conformity program and UAE's MOHAP fumigation documentation requirements are consolidating procurement among domestic mills with in-house kiln certification. Softwood input volatility from European and CIS supply disruptions compresses margins for manufacturers dependent on imported raw material.
- Plastic:Molded from polypropylene or HDPE resins, offering washability and dimensional stability that satisfies SFDA pharmaceutical traceability mandates. Cold-chain operators in Dubai and Jeddah are scaling plastic pallet fleets for perishable re-export hubs where repeated sanitization cycles degrade wooden alternatives. Petrochemical feedstock price exposure remains the primary cost constraint.
- Metal:Steel and aluminum constructions deployed in oilfield services and heavy industrial applications across the Eastern Province and Abu Dhabi industrial zones.
- Composite:Hybrid wood-plastic and compressed fiber formulations capturing interest from food-contact applications seeking durability without full plastic cost premiums.
Wood anchors the volume base while plastic gains share at the steepest rate.
Type:
Warehouse automation penetration across the UAE-Saudi corridor is reshaping pallet specification requirements, with racking compatibility and nesting density commanding procurement priority.
- Standard:Block and stringer configurations built to ISO 6780 dimensions, retaining leadership in general manufacturing and bulk commodity handling throughout the Gulf. These units dominate informal supplier networks and single-use export applications where acquisition cost outweighs durability considerations.
- Rackable:Reinforced deck structures engineered for unsupported beam racking in automated storage and retrieval systems. Dubai-based 3PLs now mandate rackable specifications for contracted pharmaceutical warehousing services, compressing demand for non-reinforced alternatives in high-bay facilities.
- Stackable:Uniform base designs enabling stable unit loads without racking infrastructure, prevalent in retail distribution centers with floor-stacking protocols.
- Nestable:Leg or post configurations allowing empty pallet insertion to reduce return freight cubic meterage, gaining traction in e-commerce fulfillment networks piloting reverse logistics integration.
Standard configurations retain the installed base while rackable designs expand most quickly in automated warehouse deployments.
End User:
Regulatory intensity varies sharply across customer categories, with pharmaceutical and food-contact operators absorbing compliance costs that general logistics providers resist.
- Logistics:Third-party providers operating multi-client warehousing and cross-dock facilities across the GCC, prioritizing fleet standardization to reduce audit complexity across varying national treatment recertification schedules.
- Retail:Hypermarket and e-commerce fulfillment networks in Riyadh and Dubai, driving demand for nestable and stackable types in last-mile container management applications.
- Manufacturing:Industrial producers in Jubail and Abu Dhabi's KIZAD zone, sourcing standard wooden pallets for inbound raw material handling and finished goods export.
- Food & Beverage:Cold-chain operators and perishable exporters subject to SFDA and MOHAP sanitary documentation requirements, consolidating procurement with certified rental pool providers who assume compliance liability.
Logistics commands the largest fleet volumes while food and beverage imposes the steepest compliance-driven specification upgrades.
Delivery Model:
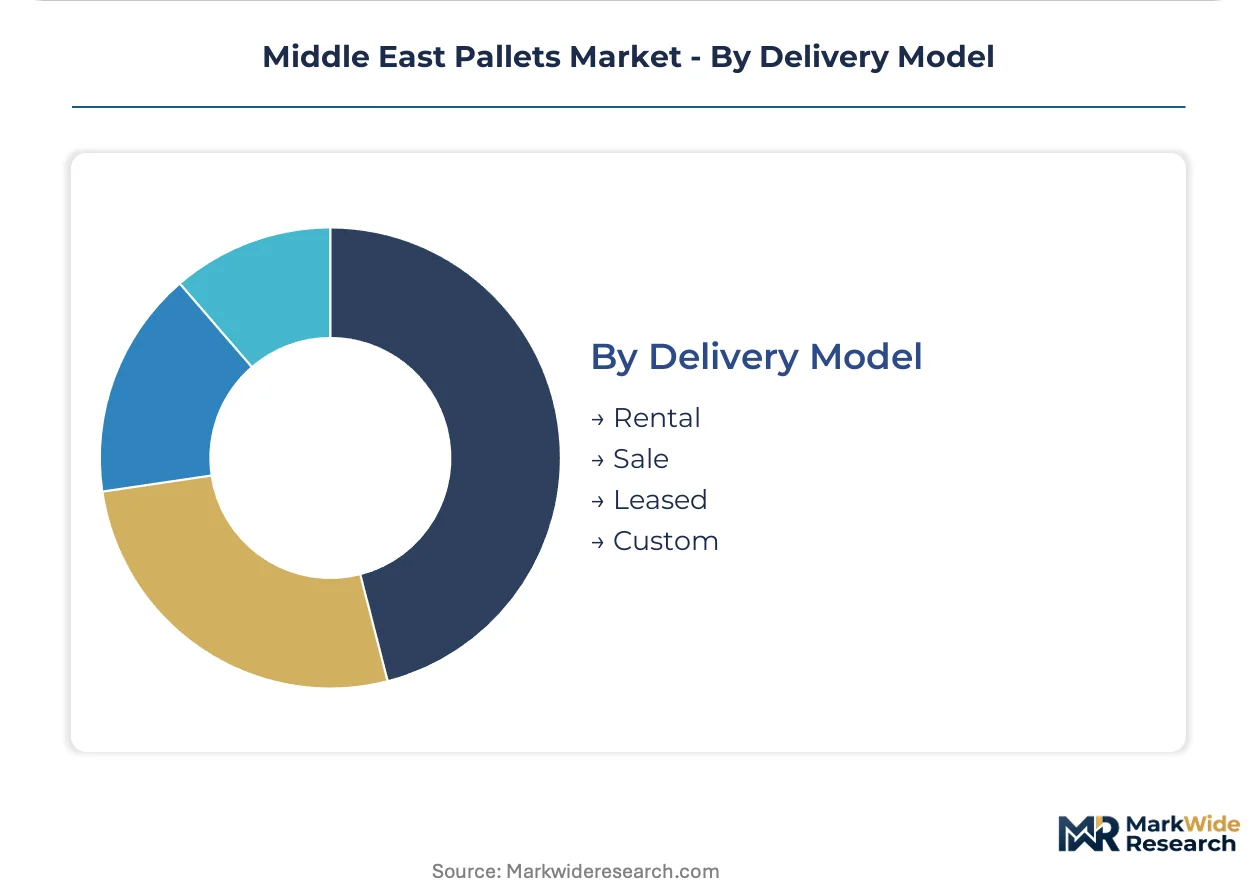
Asset ownership economics are shifting toward variable-cost structures as multi-jurisdiction compliance burdens weigh on balance-sheet-intensive procurement.
- Rental:Pooling arrangements where providers maintain certification, tracking, and maintenance responsibility. CHEP Middle East leverages this model to dominate network density in Saudi Arabia and the UAE, with pharmaceutical distributors adopting rental to avoid SABER and ESMA recertification staffing costs.
- Sale:Outright purchase for customers with stable demand patterns and in-house compliance capabilities, retaining preference among large manufacturing anchor tenants with dedicated warehousing.
- Leased:Medium-term contracts with maintenance inclusion, bridging rental flexibility and ownership control for seasonal agricultural exporters.
- Custom:Fabrication to non-standard dimensions for oilfield and industrial clients, with Gulf Pallets Factory competing on specialized engineering for project logistics.
Sale transactions retain volume leadership in manufacturing while rental climbs fastest among pharmaceutical and multi-jurisdiction logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pallet consumption patterns diverge sharply across the Gulf, with Saudi Arabia and the UAE prioritizing certified rental pools for pharmaceutical compliance while smaller markets rely on direct purchase from domestic fabricators.
Saudi Arabia
Pharmaceutical distribution networks in Riyadh and Jeddah are consolidating procurement with CHEP Middle East to satisfy SFDA traceability mandates for drug-handling assets. The SABER conformity program now requires heat-treatment documentation for all wooden pallets entering food-contact supply chains. Jubail's petrochemical industrial zone sustains demand for heavy-duty metal and custom-fabricated units in oilfield logistics applications.
United Arab Emirates
Dubai's perishable re-export hubs are scaling plastic pallet fleets to withstand repeated sanitization cycles required by MOHAP technical regulations for food-contact materials. Jebel Ali's free zone warehousing operators now mandate RFID-embedded assets for contracted pharmaceutical services. Abu Dhabi's KIZAD industrial zone anchors manufacturing demand for standard wooden configurations in bulk commodity handling.
Oman
Underdeveloped domestic pallet manufacturing creates openings for UAE-based producers to establish satellite treatment facilities serving Muscat's emerging logistics corridor. The country's national standardization body is aligning technical regulations with Gulf Standardization Organization harmonization efforts. Sohar Port's industrial zone is attracting regional fabricators seeking to preempt compliance costs for Omani-bound shipments.
Bahrain
Small-scale fabrication shops dominate local supply, though certification cost concentration is consolidating production among capitalized operators with in-house testing laboratories. The country's food safety regulator is tightening sanitary documentation requirements for wooden pallets handling imported foodstuffs. Manama's retail distribution centers are piloting nestable pallet configurations for e-commerce fulfillment networks.
Qatar
Construction-driven demand for bulk material handling sustains standard wooden pallet volumes despite pharmaceutical and food-grade segments remaining underdeveloped. The national quality infrastructure body is implementing ISPM-15 aligned treatment standards for cross-border GCC movement. Doha's logistics parks are attracting rental pool providers seeking to extend UAE-based fleet coverage northward.
Middle East Pallets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pooling network density and in-house certification capacity determining competitive position. Rental providers with balance-sheet depth absorb compliance staffing costs that burden smaller fabrication shops. Three archetypes dominate: international pooling networks with regional fleet deployment, domestic mills with captive heat-treatment infrastructure, and custom fabricators serving non-standard industrial applications. Capacity expansion and strategic partnerships with 3PL operators constitute the primary competitive moves reshaping market structure.
Among UAE-based fabricators, Emirates Pallet Factory LLC and Gulf Pallets Factory exemplify divergent strategic positions within the domestic production tier. Emirates Pallet Factory LLC anchors in-house timber treatment and heat-treatment certification capabilities that satisfy tightening SABER and ESMA requirements. Gulf Pallets Factory occupies a specialization niche serving oilfield and industrial clients requiring engineered non-standard dimensions. CHEP Middle East represents the pooling network archetype, leveraging asset tracking infrastructure and compliance liability assumption to capture pharmaceutical and multi-jurisdiction logistics procurement. Royal Pallets Factory LLC and Al-Moajil Wooden Pallets sit within the broader specialist fabricator tier competing on lead time and custom engineering for project logistics.
| Leading Market Players |
|---|
| CHEP Middle East |
| Emirates Pallet Factory LLC |
| Gulf Pallets Factory |
| Royal Pallets Factory LLC |
| Al-Moajil Wooden Pallets |
| Palletco LLC |
| Delta Engineering Middle East |
| Wooden Pallets Factory |
| AlDhana Wood Industries Factory |
| Others |
Pricing and Supply Chain Analysis
Plastic pallet substitution into pharmaceutical cold chains is simultaneously relocating procurement decisions toward certified rental providers and compressing price premiums that wooden pallet suppliers once commanded in general freight segments. This material shift redraws supply geography around heat-treatment infrastructure while forcing price differentiation across compliance tiers rather than durability alone.
Pricing Analysis
Long-term rental contracts dominate pharmaceutical and food-contact procurement, insulating CHEP Middle East and similar pooling operators from spot-market volatility that pressures small domestic fabricators. Three-tier pricing structure across ISPM-15 certified, heat-treated standard, and untreated economy levels separates compliance-grade assets from commodity handling units. Cost compression in untreated wooden tiers is intensifying because European and CIS softwood supply disruptions feed raw material volatility. General manufacturing buyers exhibit highest price sensitivity, while SFDA-mandated pharmaceutical distributors absorb premium positioning for traceable, certified fleet access.
Supply Chain Analysis
Strategic stockpiling of certified wooden pallets prevails among Saudi pharmaceutical distributors anticipating SABER platform enforcement windows, while just-in-time plastic pallet replenishment serves Dubai's perishable re-export hubs with shorter inventory cycles. Primary supply draws from domestic UAE and Saudi mills with captive heat-treatment capacity, supplemented by Turkish and Southeast Asian untreated imports for economy segments. Raw material feeds from European softwood forests, CIS hardwood reserves, and regional petrochemical complexes for polypropylene resin. Single-source vulnerability concentrates in ISPM-15 certified kiln operators, where technician scarcity limits rapid capacity expansion. Distribution runs through Jebel Ali and Jeddah anchoring warehouse clusters, with satellite facilities penetrating Muscat and Manama corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset digitization and compliance platform interoperability are transforming pallet economics toward subscription-based fleet management, with SABER and ESMA system integration creating network effects that favor pooled infrastructure over fragmented ownership.
For Market Incumbents: Secure heat-treatment technician pipelines through vocational partnerships with Saudi technical institutes and UAE logistics academies, locking in certification capacity that emerging competitors cannot replicate rapidly. Consolidate backward integration into polymer compounding or timber import forwarding to defend margin position against petrochemical feedstock volatility and European softwood supply disruptions. For New Entrants and Emerging Players: Gulf Standardization Organization harmonization fast-tracks offer regulatory arbitrage for UAE-based producers establishing satellite treatment facilities in Oman and Bahrain before domestic certification mandates tighten. Target Oman's Sohar Port industrial zone and Bahrain's retail distribution corridor as penetrable geographies with underdeveloped domestic manufacturing. Lead with composite material formulations that bridge wooden cost structures and plastic washability for food-contact applications seeking intermediate positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional logistics platforms seeking pallet fleet standardization to reduce multi-jurisdiction compliance staffing costs across GCC operations. Long-term viability centers on rental pool operators with balance-sheet depth to absorb SABER and ESMA recertification infrastructure investments over a decade horizon. Acquisition target archetype: domestic mills with in-house ISPM-15 kilns and established 3PL channel relationships. Signal to monitor: MOHAP and SFDA mandate expansion into additional product categories beyond pharmaceuticals and perishables.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captures SABER compliance demand as Saudi pharmaceutical distributors consolidate procurement with certified domestic suppliers. |
| RFID-Enabled Asset Tracking Integration | Enables real-time location monitoring that Dubai-based 3PLs now mandate for contracted warehousing services. |
| Satellite Facility Deployment in Oman | Preempts Gulf Standardization Organization harmonization by establishing treatment infrastructure before Omani certification mandates tighten. |
| Composite Material Product Line Launch | Addresses food-contact applications seeking durability without full polypropylene cost premiums in perishable export hubs. |
| Reverse Logistics Partnership with E-commerce Networks | Bundles pallet pooling with last-mile container management to reduce empty-mile costs in Riyadh and Dubai fulfillment corridors. |
Research Methodology
Initial hypotheses were tested against primary input from logistics procurement directors, pharmaceutical supply chain managers, heat-treatment kiln operators, and wooden pallet fabrication shop owners and refined through secondary validation against customs trade data, Gulf Standardization Organization technical regulations, SABER platform documentation, and ESMA certification records. Bottom-up demand modeling across material, type, end-user, and delivery model segments was cross-checked with top-down macroeconomic indicators to ensure triangulation integrity.
Variance-decomposition across the analysis window isolates volume drivers from price effects, with segmentation dimensions covering material substitution dynamics, automation-driven type specification shifts, regulatory intensity by end-user category, and rental penetration rates by delivery model. CAGRs were derived from logistic growth curve fitting anchored to base-year calibration points. Industry-specific forecast inputs include ISPM-15 certification capacity buildout schedules and pharmaceutical cold-chain warehouse square footage expansion.
Underlying assumptions cover sustained SABER and ESMA enforcement intensity, with deviation risk concentrated in European timber supply disruption duration and petrochemical feedstock price volatility. Revision becomes warranted when regulatory harmonization timelines accelerate or composite material cost curves intersect plastic pricing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market