
 Europe Punnet Trays Market | 2026-2036
Europe Punnet Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Punnet Trays Market Foresight
Discount retailers across Central Europe are reorganizing procurement specifications toward lighter-weight, stackable tray designs that cut logistics costs. Smurfit Kappa Group leverages its integrated paperboard supply chain to dominate fiber-based formats for soft fruit. Huhtamaki Oyj competes through thermoformed plastic expertise anchored in Nordic berry export corridors. Mondi Group differentiates via barrier-coated paper solutions that target retailers seeking plastic reduction without shelf-life compromise.
Europe punnet trays are rigid or semi-rigid containers, typically 150–500 grams capacity, thermoformed from PET, PP, or molded from recycled paper pulp, designed to protect, display, and ventilate delicate fresh produce during cold-chain distribution. Paperboard punnets now lead material growth as PPWR compliance deadlines harden, while plastic trays retain share in modified-atmosphere applications for extended-shelf-life berries. Medium-size trays occupy the largest volume position across retail pre-pack formats, though custom sizes are accelerating among premium organic lines that use distinctive branding geometry.
EMA, EFSA, and the EU Packaging and Packaging Waste Regulation collectively shape material compliance, food-contact safety thresholds, and extended producer responsibility obligations across European tray converters. REACH chemical restrictions and F-Gas Regulation cooling standards further tighten specifications for trays destined for controlled-atmosphere supply chains. Stakeholders must monitor PPWR recycled-content mandates and national deposit-return scheme expansions to align capital allocation with compliance trajectories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing a material pivot across European tray converters, with recycled-content mandates and extended producer responsibility obligations restructuring capital allocation toward fiber-based and recyclable designs.
Growth Catalysts
- PPWR Compliance Deadlines:Recycled-content mandates and recyclability targets are pulling converters toward paperboard and molded fiber investments, expanding addressable volume for compliant suppliers.
- Almería Export Cluster:Spain's greenhouse concentration generates sustained demand for high-throughput berry packaging, driving standardized punnet specifications across Mediterranean fresh produce corridors.
- Modified-Atmosphere Technology:Barrier-coated paper and advanced thermoforming techniques are extending shelf life for soft fruit, opening premium retail placement opportunities.
Market Restraints
- Recycled Pulp Cost Volatility:European recovered paper markets face supply tightness from export competition and collection infrastructure gaps, compressing converter margins on fiber-based formats.
- REACH Chemical Restrictions:Food-contact safety thresholds for adhesives, coatings, and barrier layers are lengthening qualification timelines and limiting supplier flexibility for rapid formulation changes.
- Plastic Substitution Limits:High-moisture produce categories and extended cold-chain routes retain structural dependence on thermoformed PP and PET, capping fiber penetration in performance-critical segments.
Strategic Opportunities
- Polish Retail Modernization:Discount-format expansion across Central Europe is creating demand for lightweight, stackable tray designs optimized for automated distribution centers.
- Deposit-Return Scheme Alignment:National DRS expansions in Germany, Sweden, and the Netherlands reward mono-material and easily separable packaging structures, favoring converters with design-for-recycling capabilities.
- Digital Printing Convergence:Variable-data printing on paperboard punnets enables batch-level traceability and dynamic branding, capturing premium organic lines seeking differentiation.
Industry Challenges
- Thermoforming Tooling Lead Times:Custom mold fabrication for proprietary tray geometries stretches 16-24 weeks, constraining speed-to-market for seasonal produce launches and private-label transitions.
- Cross-Border EPR Administration:Fragmented national producer responsibility schemes across EU member states multiply compliance overhead for converters serving multi-country retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Punnet Trays Market |
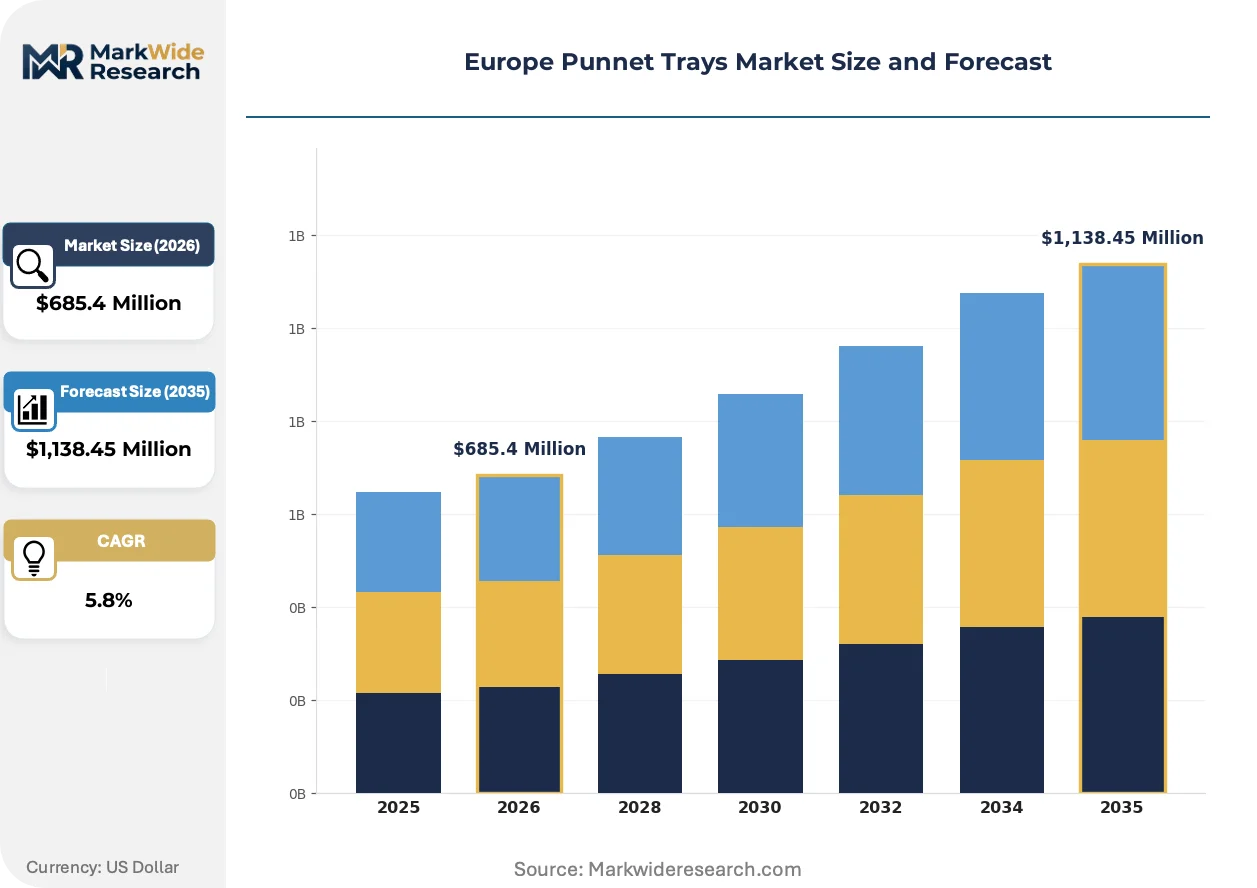
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Styrofoam, Paperboard, Aluminum Application: Fruits, Vegetables, Baked Goods, Confectionery Size: Small, Medium, Large, Custom End User: Retailers, Food Processors, Wholesalers, Distributors |
| Companies Covered | Smurfit Kappa Group, Coveris Holdings S.A., LC Packaging International BV, Sirane Group, J-Tech Systems, Infia Srl, Quinn Packaging Ltd., Mondi Group, Huhtamaki Oyj, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Punnet Trays Market Shifts & Advancements
Material science advances and regulatory compression are converging to redefine tray performance standards, with sustainability metrics now embedded in procurement specifications alongside cost and throughput.
Fiber-based molded pulp technology is displacing conventional plastic formats in berry and soft-fruit applications across Nordic and German retail channels. Aldi Nord and Lidl are accelerating adoption through standardized sourcing protocols. The shift is compressing demand for virgin PET thermoforming in segments where moisture sensitivity permits paper substitution.
REACH chemical restrictions and F-Gas Regulation cooling standards are tightening specifications for trays destined for controlled-atmosphere supply chains. Barrier coating formulations face accelerated scrutiny for food-contact compliance. Berry exporters serving UK and Scandinavian markets are qualifying alternative coating chemistries to maintain shelf-life performance under evolving safety thresholds.
Discount retailers are consolidating procurement around lighter-weight, stackable tray geometries that cut cube utilization in refrigerated transport. German and Polish distribution networks are driving this specification shift most aggressively. Private-label fresh produce lines are capturing volume share from branded alternatives, concentrating buying power among fewer retail technical teams.
Europe Punnet Trays Market Segmentation
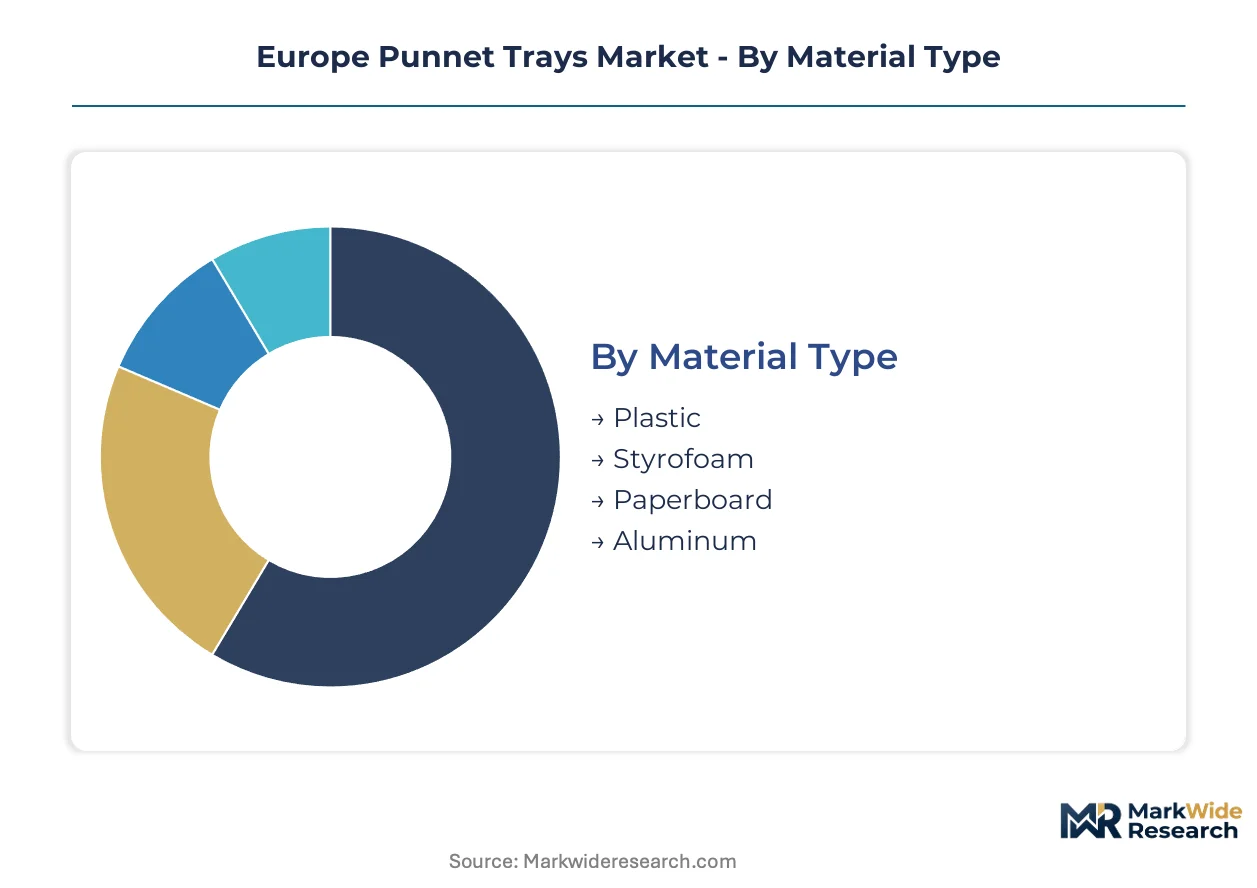
Punnet tray procurement splits sharply across material and application dimensions, with regulatory pressure and channel economics driving divergent specification requirements. Retailers, food processors, and export clusters each impose distinct performance thresholds that reshape converter priorities.
Material Type:
Channel mix determines material allocation: discount retailers push fiber-based formats through centralized procurement, while modified-atmosphere exporters retain plastic dependence for shelf-life extension.
- Plastic:Thermoformed PET and PP structures dominate berry export corridors from Spain's Almería cluster, where moisture barriers and controlled-atmosphere compatibility are non-negotiable. REACH chemical restrictions on food-contact coatings are lengthening qualification timelines for virgin and recycled resin grades.
- Paperboard:Molded fiber and barrier-coated paperboard formats are capturing volume in German and Nordic retail channels as PPWR compliance deadlines harden. Smurfit Kappa's integrated supply chain position enables rapid scale-up of recyclable designs for soft-fruit private-label lines.
- Styrofoam:Expanded polystyrene retains niche use in cost-sensitive vegetable bulk packaging, though national bans in France and pending restrictions elsewhere are compressing addressable volume.
- Aluminum:Premium confectionery and gift-fruit applications specify aluminum for barrier performance and aesthetic differentiation, with limited penetration beyond high-value seasonal segments.
By volume, plastic leads. By growth pace, paperboard is expanding most quickly.
Application:
Cost-tier stratification separates commodity produce from premium-positioned categories, with packaging investment scaling directly with per-unit product value.
- Fruits:Berry packaging generates the highest specification intensity, combining modified-atmosphere requirements with retail-facing display geometry. Spanish and Moroccan export volumes drive standardized tray formats across Mediterranean supply chains.
- Vegetables:Tomato and pepper packaging in Dutch and Belgian greenhouse corridors emphasizes stackability and cube efficiency for automated distribution centers, with lighter-weight designs cutting transport costs.
- Baked Goods:Bakery punnets prioritize grease resistance and moisture management, with fiber-based formats gaining traction in artisan and organic retail channels.
- Confectionery:Premium chocolate and seasonal gift applications demand structural rigidity and print quality, sustaining higher-margin specialty tray production.
By volume, fruits dominate. By margin contribution, confectionery sits highest.
Size:
Customer-type segmentation separates standardized retail pre-packs from bespoke formats serving premium organic and private-label differentiation strategies.
- Medium:250–400 gram capacities anchor retail berry and cherry tomato assortments across European supermarket chains, with format standardization enabling automated packing line efficiency.
- Small:Single-serve and snack-size punnets are climbing fastest in convenience retail and foodservice channels, particularly for premium berry varieties targeting on-the-go consumption.
- Large:Family-size formats serve wholesale club and discount retail channels in Germany and Poland, with stackability specifications optimized for palletized distribution.
- Custom:Proprietary geometries differentiate organic and premium private-label lines, though thermoforming tooling lead times of 16–24 weeks constrain speed-to-market.
By volume, medium leads. By specification intensity, custom formats command the steepest premium.
End User:
Supply concentration varies sharply: retailer procurement centralization contrasts with fragmented food processor and distributor demand patterns.
- Retailers:Aldi Nord, Lidl, and Carrefour are consolidating specifications toward lighter-weight, recyclable designs, with technical teams dictating format standards across national markets.
- Food Processors:Berry packers in Huelva and Murcia require high-throughput punnet solutions with automated denesting and filling compatibility, driving standardization even for export-grade product.
- Wholesalers:Rungis and Birmingham wholesale markets sustain demand for durable, reusable-optimized formats with higher structural margins.
- Distributors:Cold-chain logistics providers specify stackability and ventilation geometry for mixed-load refrigerated transport across cross-border corridors.
By procurement volume, retailers lead. By growth in specification intensity, food processors are pulling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German discount retailers and Spanish export clusters concentrate procurement power across Europe, with national regulations fragmenting compliance requirements for tray converters serving multi-country supply chains.
Germany
Aldi Nord and Lidl dominate standardized fiber-format procurement through centralized technical specifications. The national deposit-return scheme expansion rewards mono-material designs, pulling converters toward easily separable paperboard structures. Bavarian distribution networks optimize pallet cube utilization through lighter-weight stackable geometries.
Spain
Almería's greenhouse concentration generates sustained demand for high-throughput berry packaging with modified-atmosphere compatibility. EFSA food-contact safety thresholds lengthen qualification timelines for barrier coating formulations. Huelva and Murcia packers drive automated denesting specifications across Mediterranean export corridors.
Netherlands
Rotterdam cold-chain logistics providers specify ventilation geometry for mixed-load refrigerated transport across cross-border corridors. The Dutch extended producer responsibility scheme multiplies compliance overhead for converters serving German retail chains. Westland greenhouse clusters emphasize cube efficiency for automated distribution centers.
Poland
Discount-format expansion creates demand for lightweight tray designs optimized for automated distribution centers. Polish retail modernization concentrates buying power among fewer technical procurement teams. Warsaw logistics corridors specify stackability for palletized distribution to German markets.
France
National bans on expanded polystyrene compress addressable volume for cost-sensitive vegetable bulk packaging. ANSM food-contact restrictions accelerate scrutiny of barrier coating chemistries. Rungis wholesale market sustains demand for durable formats with higher structural margins.
Europe Punnet Trays Market Competitive Landscape
Player mix skews toward integrated paperboard suppliers and specialized thermoformers, with consolidation pressure intensifying as PPWR compliance deadlines harden. Tiered structure separates scale-driven integrated producers from regional specialists serving export corridors. Strategic archetypes include fiber-format integrators with captive pulp supply, thermoforming specialists anchored in berry export clusters, and barrier-coating innovators targeting plastic-reduction mandates. Dominant competitive moves center on backward integration into recycled pulp supply and design-for-recycling capability investments.
Among Ireland-based integrated packaging groups, Smurfit Kappa Group exemplifies the fiber-format archetype through its paperboard supply chain position. Finnish thermoforming specialists Huhtamaki Oyj occupy a position within Nordic berry export corridors. Austria-based Mondi Group represents barrier-coated paper solutions targeting retailers seeking plastic reduction without shelf-life compromise.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Coveris Holdings S.A. |
| LC Packaging International BV |
| Sirane Group |
| J-Tech Systems |
| Infia Srl |
| Quinn Packaging Ltd. |
| Mondi Group |
| Huhtamaki Oyj |
| Others |
Supply & Pricing Matrix
Capacity utilization at Almería berry packers and German discount distribution centers sets price floors across fiber-based and plastic tray tiers, compressing margins for converters caught between volatile recycled pulp markets and fixed retail procurement contracts.
Pricing Analysis
Cost-plus contracts with recovered paper indexation dominate fiber-format procurement between Smurfit Kappa and Aldi Nord technical teams. Three-tier pricing structure across premium barrier-coated, standard molded fiber, and economy uncoated levels tracks certification grade and volume scale. Pricing pressure stems from export competition for European recovered paper feedstock. Discount retailers exhibit highest price sensitivity; berry exporters serving UK markets show lowest.
Supply Chain Analysis
Sixteen-to-twenty-four week thermoforming tooling lead times constrain converter responsiveness to seasonal produce launches. Supply concentrates in Germany, Spain, and Poland for tray manufacturing, with molded fiber production anchored in Nordic pulp corridors. Raw material dependencies span recovered paper pulp, virgin PET resin, and barrier coating chemistries. Single-source vulnerability runs through specialized mold fabrication. Distribution runs through retailer-controlled automated distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national extended producer responsibility schemes and divergent retailer sustainability specifications creates niche opportunities for converters with design-for-recycling capabilities.
For Market Incumbents: Secure backward integration into recycled pulp supply to defend margin position against export-driven feedstock competition. Capture channel control through long-term technical specification partnerships with Aldi Nord and Lidl procurement teams.
For New Entrants and Emerging Players: Anchor in Polish retail modernization corridors where discount-format expansion outpaces incumbent converter capacity. Target custom-format organic lines with digital printing-enabled batch traceability as entry wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fiber-format suppliers with captive pulp supply and multi-year retail contracts. Five-to-ten year viability favors converters with barrier-coating R&D pipelines. Watch PPWR recycled-content mandate enforcement timelines as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp | Secures feedstock supply against Asian export competition under REACH compliance. |
| Barrier-Coating R&D Investment | Extends fiber-format penetration into modified-atmosphere berry applications. |
| Design-for-Recycling Certification | Aligns with German deposit-return scheme expansion and mono-material rewards. |
| Digital Printing Capability Addition | Captures premium organic private-label demand for batch-level traceability. |
| Polish Distribution Center Proximity | Reduces logistics costs for Central European discount retail supply contracts. |
Research Methodology
Operator-level perspectives from tray converter plant managers, retail category buyers at Aldi Nord and Lidl, berry packer operations directors, and EMA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EFSA food-contact safety guidance, recovered paper trade data, and SEC disclosures from listed packaging groups. Bottom-up volume modeling triangulated against top-down market sizing across material type, application, and end-user segments.
Sensitivity analysis tested forecast robustness across recycled pulp price scenarios and PPWR compliance deadline variations over the projection horizon. The analytical framework segmented by material type, application, size, and end-user, with regional regulatory clusters as cross-cutting dimension. CAGRs derived from trend extrapolation of converter capacity additions and retail procurement volume commitments, with Almería export throughput and German discount private-label expansion as primary demand inputs.
Decision-makers should treat outputs as directional under base assumptions of stable EFSA food-contact thresholds and no major national deposit-return scheme expansions beyond Germany, Sweden, and Netherlands; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Pump Dispenser Market
Packaging Containers
Candle Box Market
Packaging Containers
Portion Packs Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Assembly Trays Market
Packaging Containers
VCI Bags Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Tamper Evident Pots and Tubs Market