
 Electric Brake Booster Market | 2026-2036
Electric Brake Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Brake Booster Market Analytics
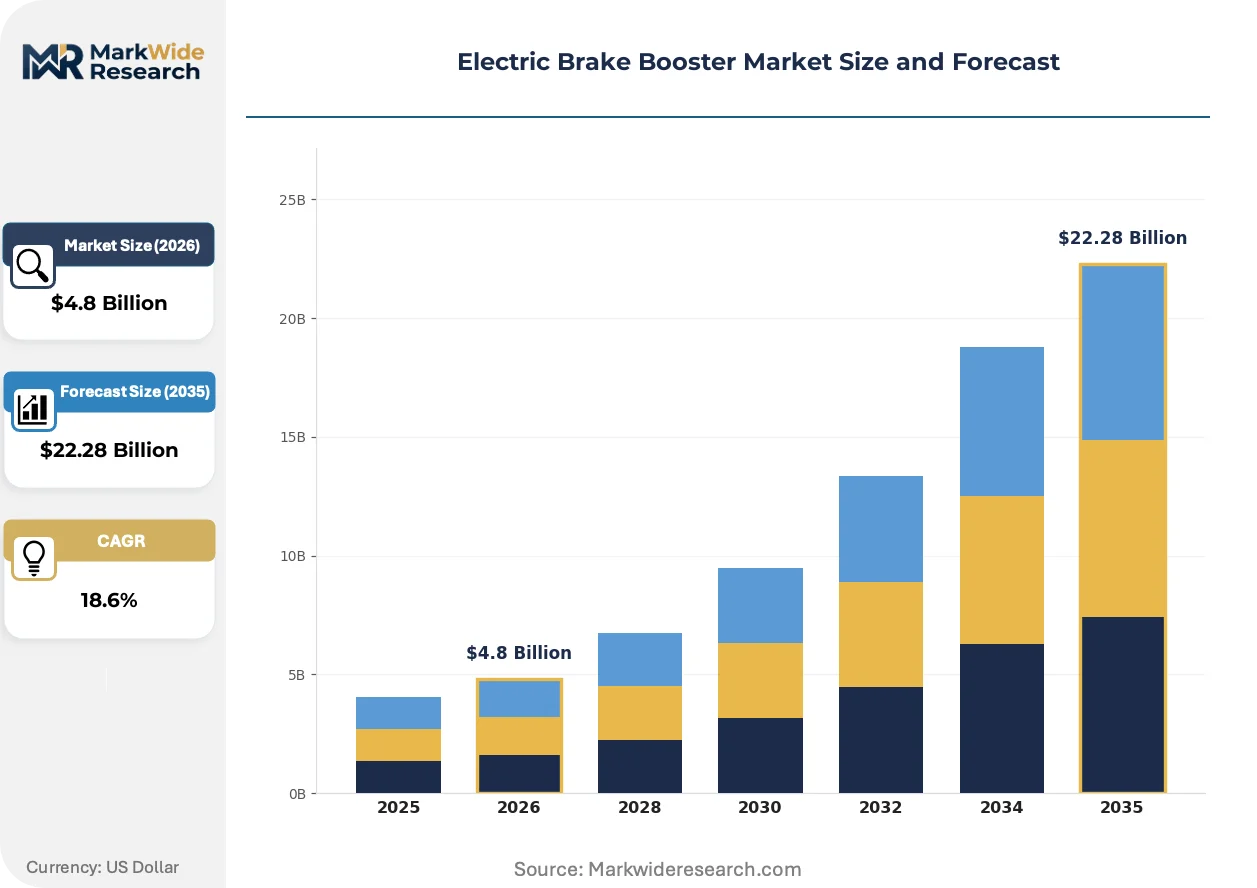
The electric brake booster market is pivoting on a widening split between premium integrated brake-by-wire systems and commodity electromechanical boosters serving cost-sensitive platforms. Continental AG leverages its iBooster platform to dominate the premium tier across German and Chinese OEM programs. Robert Bosch GmbH anchors the volume segment with scalable motor-pump architectures designed for compact electric vehicles. Aisin Seiki Co. Ltd. competes through hydraulic-electronic hybrid designs that sustain compatibility with legacy vehicle electrical systems.
An electric brake booster replaces engine vacuum with an electromechanical actuator to amplify driver pedal force, typically integrating a brushless DC motor, pedal simulator, and electronic control unit within a housing rated for pressures exceeding 15 MPa. OEM demand for vacuum brake boosters persists in internal combustion segments, yet electro-hydraulic boosters command the fastest expansion as they enable regenerative braking coordination and autonomous emergency braking protocols. Passenger cars occupy the dominant application slot, while heavy duty vehicles represent a concentrated margin pool where failure-tolerant redundant architectures justify premium pricing.
NHTSA Federal Motor Vehicle Safety Standards and EU ECE R13-H braking regulations mandate minimum stopping distances and fault-response protocols that directly shape electric booster validation requirements. China's MIIT New Energy Vehicle准入 rules require domestic suppliers to certify brake energy recovery systems, tightening market access for non-compliant imports. Stakeholders must monitor how software-defined vehicle architectures redistribute braking control between domain controllers and dedicated booster ECUs.
Market Dynamics
The electric brake booster market pivots on NHTSA and EU braking mandates that are forcing OEMs to abandon vacuum-dependent architectures in favor of electromechanical systems capable of supporting autonomous emergency braking and regenerative energy recovery.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Stopping-distance mandates for passenger vehicles compel automakers to integrate electromechanical boosters with faster response times than vacuum systems.
- Regenerative braking coordination:Battery electric platforms require brake-by-wire architectures that seamlessly blend friction and motor braking without driver perception of transition points.
- EU pedestrian safety regulations:Automated emergency braking mandates in urban environments demand booster systems with millisecond-level activation speeds.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies for brushless DC motors concentrate in China's processing infrastructure, exposing tier-one suppliers to export restriction risks.
- High-voltage electrical architecture costs:48V and 800V vehicle systems require reinforced insulation and isolation components that inflate unit economics versus legacy 12V boosters.
- Internal combustion residual demand:Vacuum brake boosters persist in light truck and commercial segments where engine-based vacuum remains cost-effective.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic manufacturing incentives for advanced braking systems create localized supply opportunities for export to Southeast Asian EV assembly plants.
- Commercial vehicle redundancy requirements:Fail-operational brake architectures for autonomous trucking represent an uncaptured margin pool where dual-motor designs command substantial premiums.
- Software-defined vehicle convergence:Domain controller integration allows brake booster ECUs to consolidate functions, reducing per-vehicle electronic content cost while maintaining safety integrity.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise for brake control systems remains concentrated among a limited pool of automotive software suppliers.
- Legacy platform integration friction:Retrofitting electromechanical boosters onto existing vehicle electrical architectures requires extensive harness redesign and validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Brake Booster Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Brake Boosters, Electric Brake Boosters, Electro-Hydraulic Boosters, Others End User: OEMs, Aftermarket Providers, Commercial Vehicles, Passenger Vehicles Technology: Hydraulic Systems, Electronic Control, Mechanical Systems, Pump Technology Application: Passenger Cars, Light Commercial Vehicles, Heavy Duty Vehicles, Motorcycles |
| Companies Covered | Continental AG, Robert Bosch GmbH, Aisin Seiki Co. Ltd., ZF Friedrichshafen AG, Hyundai Mobis, Mando Corporation, Hitachi Astemo, Nissin Kogyo, FTE automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Brake Booster Market Evolving Landscape
Brake system electrification is compressing development cycles and redistributing engineering priorities across traditional tier-one hierarchies. Three concurrent developments are restructuring how braking performance is specified, procured, and validated.
Electro-hydraulic brake boosters is electrifying the transition path for mass-market electric vehicles. These systems retain hydraulic actuation for wheel cylinders while replacing vacuum dependence with motor-driven pressure generation. Compact EV platforms from multiple OEMs are adopting this architecture as an intermediate step toward full brake-by-wire. The technology is electrifying supplier R&D budgets toward motor-inverter integration rather than pneumatic valve refinement.
EU ECE R13-H braking regulations are tightening validation protocols for vehicles equipped with energy recovery systems. The framework now requires documented fault-response sequences when regenerative braking degrades unexpectedly. European passenger car programs face compressed homologation timelines as they adapt to these expanded test matrices. German and French certification bodies are expanding laboratory capacity to handle the surge in brake-by-wire validation requests.
Fleet procurement of brake systems is consolidating around total-cost-of-ownership metrics rather than unit price. Commercial vehicle operators in North America now specify predictive maintenance interfaces and over-the-air diagnostic capability as standard requirements. This behavioral shift favors suppliers with integrated telematics platforms over component-only vendors. Long-haul trucking corridors through Texas and California are emerging as testbeds for outcome-based brake performance contracts.
Electric Brake Booster Market Segmentation
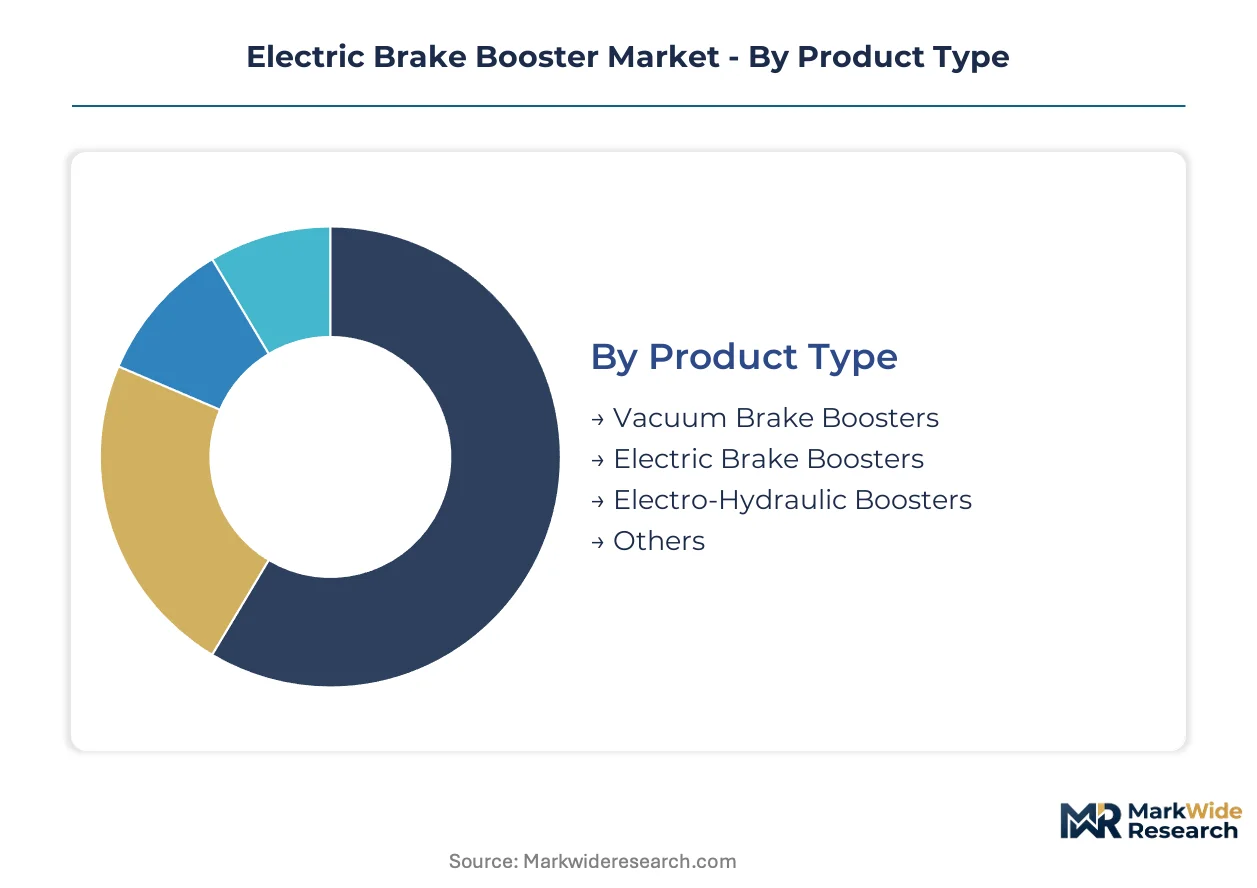
Electric brake booster architectures fragment across pressure generation methods, customer procurement patterns, and vehicle duty cycles. Each segmentation axis reveals distinct margin structures, certification requirements, and supplier concentration patterns that shape competitive positioning.
Product Type:
Supply concentration in brushless DC motor manufacturing tilts competitive advantage toward electromechanical architectures over legacy vacuum-dependent systems.
- Vacuum Brake Boosters:Engine-dependent pneumatic amplification using diaphragm chambers and check valves. Demand persists in Detroit Three light truck programs and emerging market internal combustion platforms where vacuum port availability eliminates motor cost premiums.
- Electric Brake Boosters:Motor-driven pedal force multiplication with integrated pedal simulators and ECUs rated for 15 MPa+ hydraulic pressures. German and Chinese OEM passenger EV programs anchor volume demand as NHTSA stopping-distance mandates accelerate phase-out of vacuum architectures.
- Electro-Hydraulic Boosters:Hybrid designs retaining hydraulic wheel cylinder actuation while replacing vacuum dependence with electric pressure generation. Compact EV platforms adopt this intermediate architecture to leverage existing brake line infrastructure during brake-by-wire transitions.
- Others:Pneumatic-electric hybrid boosters for specialty commercial applications and experimental solid-state braking actuators under laboratory evaluation.
Today's leader: Electric Brake Boosters. Tomorrow's challenger: Electro-Hydraulic Boosters.
End User:
Procurement patterns diverge sharply between vehicle manufacturer integration mandates and aftermarket replacement cycles driven by wear rates rather than technology refresh.
- OEMs:Direct supplier relationships governed by ASIL-D functional safety requirements and multi-year platform sourcing agreements. Battery electric vehicle launches in Germany, China, and the United States concentrate specification authority among integrated brake system architects.
- Aftermarket Providers:Independent distribution channels serving collision repair and wear-item replacement with remanufactured vacuum boosters dominating current revenue. Electromechanical booster aftermarket infrastructure remains underdeveloped due to diagnostic complexity and proprietary software lock-in.
- Commercial Vehicles:Fleet procurement concentrated in long-haul trucking corridors through Texas and California where predictive maintenance interfaces and over-the-air diagnostic capability have become standard requirements.
- Passenger Vehicles:Individual owner replacement demand driven by brake pedal feel degradation and warning lamp activation, with cost-sensitive consumers favoring remanufactured units over new electromechanical systems.
OEMs command specification authority. Aftermarket Providers capture replacement volume.
Technology:
Engineering talent scarcity in ISO 26262 certification concentrates competitive advantage among suppliers with captive functional safety expertise.
- Hydraulic Systems:Pressurized fluid transmission through master cylinders and wheel circuits with ABS modulation valves. Mature supply base in Stuttgart and Detroit industrial clusters supports cost-optimized architectures for mass-market platforms.
- Electronic Control:Brushless DC motor drives with inverter-integrated ECUs executing pedal interpretation algorithms and regenerative blending strategies. Chinese MIIT New Energy Vehicle准入 rules mandate brake energy recovery certification, tightening access for non-compliant control system imports.
- Mechanical Systems:Linkage and pivot-based force multiplication without electrical assistance. Motorcycle and low-speed electric vehicle segments sustain residual demand where regulatory stopping-distance requirements remain permissive.
- Pump Technology:Motor-driven hydraulic pressure generation enabling brake-by-wire decoupling of pedal input from wheel actuation. Premium German OEM programs specify pump-based architectures for autonomous emergency braking latency requirements.
Electronic Control defines current roadmaps. Pump Technology enables next-generation decoupling.
Application:
Vehicle mass and duty cycle severity create tiered performance requirements that stratify supplier participation across application segments.
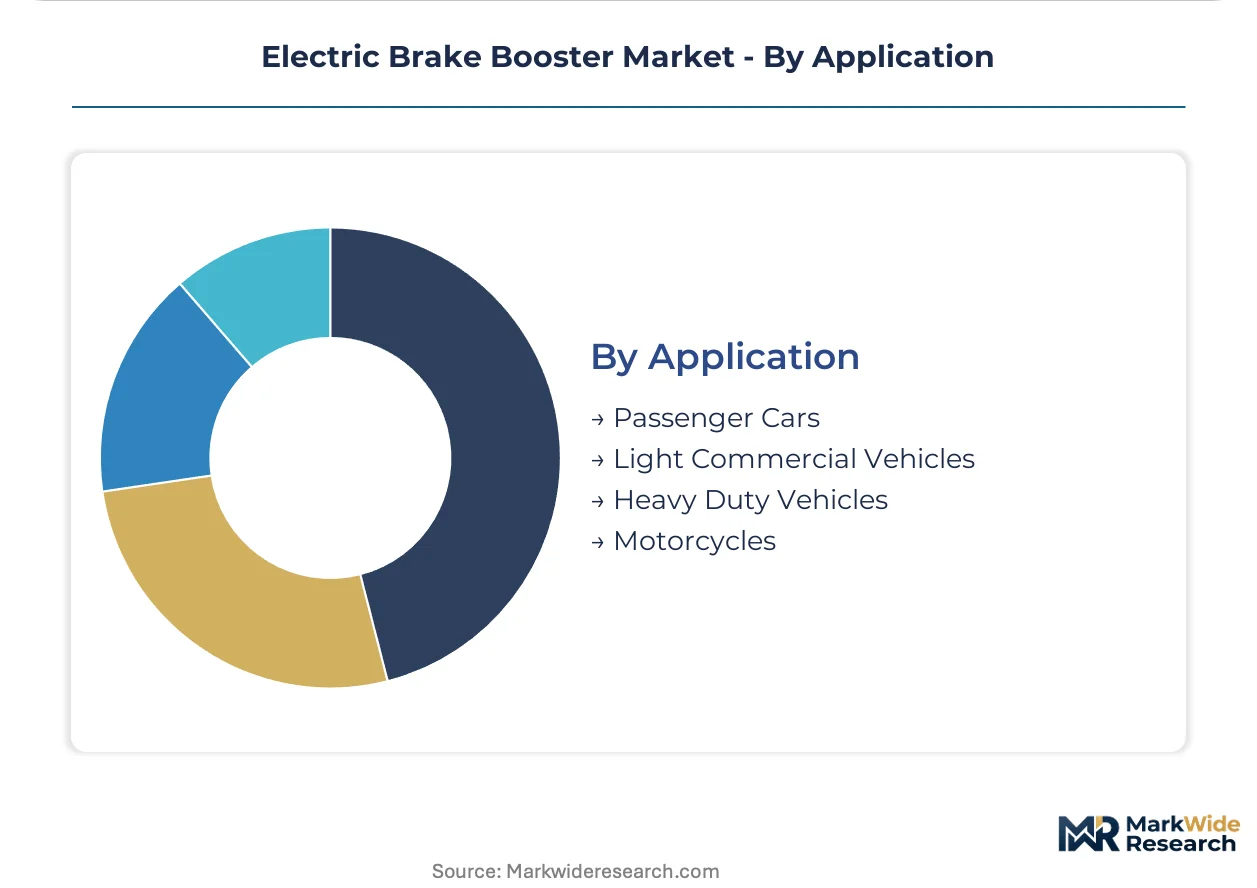
- Passenger Cars:Light-duty platforms prioritizing pedal feel refinement and regenerative energy recovery efficiency. Chinese and German OEM battery electric programs specify integrated brake-by-wire systems with sub-100-millisecond emergency braking activation.
- Light Commercial Vehicles:Delivery van and utility truck applications balancing payload capacity with urban stop-and-go durability requirements. North American fleet operators now specify telematics-integrated boosters for predictive maintenance contracts.
- Heavy Duty Vehicles:Long-haul trucking and refuse collection platforms requiring redundant actuator architectures and extended service intervals. Fail-operational dual-motor designs command substantial premiums in autonomous freight pilot programs.
- Motorcycles:Two-wheeler applications constrained by packaging volume and cost ceilings below passenger car thresholds. Mechanical and basic hydraulic boosters dominate; electromechanical penetration remains limited to premium electric motorcycle platforms.
Passenger Cars absorb development investment. Heavy Duty Vehicles deliver margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Shanghai, and Detroit anchor electric brake booster development clusters. These concentrations of mechatronics expertise and tier-one supplier infrastructure shape regional competitive positioning. Each geography deploys distinct regulatory levers to accelerate vacuum-to-electric transitions.
China
Domestic EV production scaling and MIIT New Energy Vehicle准入 certification requirements drive demand concentration. The ministry mandates brake energy recovery system validation for market access, tightening import compliance. Shanghai and Shenzhen industrial corridors host integrated motor-inverter manufacturing clusters serving BYD and NIO programs.
Germany
Premium OEM brake-by-wire specifications and KBA homologation protocols set performance benchmarks. EU ECE R13-H regulations mandate documented fault-response sequences for regenerative braking degradation. Stuttgart and Wolfsburg supplier parks concentrate electromechanical booster R&D for Volkswagen Group and Mercedes-Benz platforms.
United States
NHTSA Federal Motor Vehicle Safety Standard stopping-distance mandates accelerate vacuum system phase-out. The regulator's emergency braking activation requirements favor electromechanical response latency. Detroit Three supplier integration and Silicon Valley autonomous vehicle testing clusters drive divergent architecture demands.
Japan
Keiretsu supplier relationships and METI carbon neutrality roadmaps coordinate electrification timelines. The ministry's automotive component efficiency targets pressure legacy vacuum booster retirement. Toyota City and Hiroshima industrial basins sustain hybrid-electric brake system development alongside full battery electric transitions.
South Korea
Hyundai-Kia Group platform consolidation and KATRI certification requirements concentrate specification authority. The national automotive testing institute's brake performance protocols align with UN ECE harmonization efforts. Seoul metropolitan area and Ulsan manufacturing complexes anchor motor-pump integration supply chains.
Electric Brake Booster Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure. Integrated brake system architects with captive motor manufacturing and inverter integration capabilities command premium positioning in German and Chinese OEM programs. Three archetypes dominate: full-system integrators owning electromechanical and hydraulic domains; motor-pump specialists supplying scalable architectures to volume platforms; and hybrid-technology providers bridging legacy electrical compatibility. Consolidation through strategic component sourcing agreements and geographic co-location with OEM assembly plants represents the dominant competitive dynamic.
Among German-based full-system integrators, Continental AG and ZF Friedrichshafen AG occupy positions defined by brake-by-wire platform ownership and multi-decade OEM relationships. Robert Bosch GmbH represents the motor-pump specialist archetype with scalable electromechanical architectures designed for cost-sensitive compact electric vehicles. These three entities anchor the competitive structure through their respective concentration in integrated system design, component scalability, and global manufacturing footprint.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Aisin Seiki Co. Ltd. |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Mando Corporation |
| Hitachi Astemo |
| Nissin Kogyo |
| FTE automotive |
| Others |
Value Network & Pricing Analysis
ASIL-D certification tiers separate premium brake-by-wire systems from commodity electromechanical boosters, with that bifurcation concentrating supply chain investment in German and Chinese motor-inverter clusters while forcing price-sensitive platforms toward electro-hydraulic hybrid architectures.
Pricing Analysis
Bundled system integration versus unbundled component supply splits the market. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification investment, motor-inverter integration depth, and after-sales diagnostic capability. Pricing pressure stems from rare earth magnet cost volatility and 800V architecture insulation requirements. Fleet procurement in North American long-haul corridors shows lowest price sensitivity due to total-cost-of-ownership contracting, while emerging market aftermarket channels favor remanufactured vacuum boosters.
Supply Chain Analysis
Mechatronics engineering scarcity in Stuttgart, Shanghai, and Detroit manufacturing basins concentrates brushless DC motor production. Neodymium and dysprosium processing draws from China's rare earth infrastructure, while hydraulic valve bodies source from mature Stuttgart and Detroit industrial clusters. Single-source vulnerability in rare earth magnet supply exposes tier-one suppliers to export restriction risks. Distribution runs through OEM direct supply agreements with multi-year platform commitments and aftermarket remanufacturing networks serving collision repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
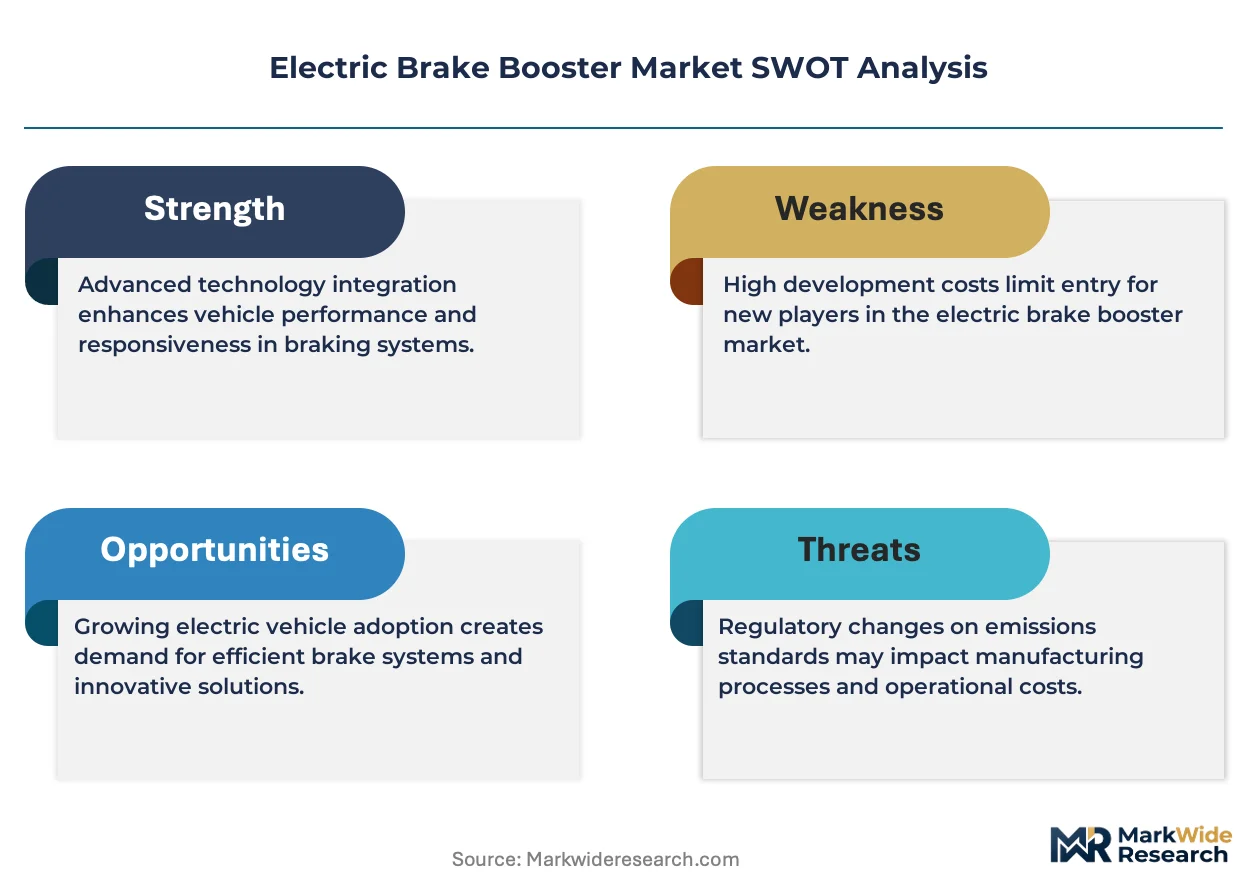
Geographic-arbitrage opportunities concentrate in India's PLI scheme for automotive components, where domestic manufacturing incentives for advanced braking systems undercut Chinese export costs while maintaining access to Southeast Asian EV assembly plants.
For Market Incumbents: Anchor ASIL-D certification expertise through captive functional safety engineering teams to defend against software-defined vehicle architectures redistributing braking control to domain controllers. Deepen backward integration into brushless DC motor manufacturing to offset rare earth magnet supply concentration in Chinese processing infrastructure. Prioritize geographic co-location with BYD and NIO assembly plants in Shanghai and Shenzhen corridors.
For New Entrants and Emerging Players: Aftermarket diagnostic tooling for electromechanical boosters represents an underserved buyer archetype with limited incumbent investment. White-space targets include remanufacturing capacity for collision repair networks and predictive maintenance interfaces for commercial vehicle fleets. India's PLI scheme offers the most penetrable geography for localized supply base establishment. Go-to-market through fleet telematics partnerships bypasses OEM specification lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 26262 certification expertise concentrates among limited automotive software suppliers. Long-term viability favors integrated brake system architects with captive motor-inverter capabilities over component-only vendors. Acquisition target archetype: mid-cap electro-hydraulic specialists with legacy electrical compatibility IP. Signal to watch: brake-by-wire validation backlog at German and French certification bodies indicating demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Inverter Integration Investment | Captive manufacturing of brushless DC drives reduces rare earth supply exposure for tier-one suppliers. |
| ASIL-D Certification Expansion | Functional safety engineering capacity at KBA and MIIT accelerates brake-by-wire homologation timelines. |
| Geographic Manufacturing Footprint | PLI scheme localization in India creates export base for Southeast Asian EV assembly plants. |
| Software-Defined Vehicle Partnership | Domain controller integration consolidates braking ECU functions with Silicon Valley autonomous vehicle clusters. |
| Predictive Maintenance Platform | Telematics-integrated boosters enable outcome-based contracts with Texas and California long-haul fleets. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, tier-one supplier procurement patterns, and regulatory filing databases — were reconciled through structured primary interviews with brake system architects, functional safety engineers, and fleet procurement managers. Secondary validation drew from NHTSA FMVSS documentation, EU ECE R13-H homologation records, and MIIT New Energy Vehicle准入 certification databases. Bottom-up vehicle production forecasts and top-down braking content per vehicle estimates were triangulated to anchor market sizing.
Cross-referencing historical brake system adoption curves against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include booster architecture type, vehicle propulsion system, OEM tier positioning, and regional regulatory cluster. CAGRs were derived from production volume trajectories and content-per-vehicle escalation curves. Industry-specific forecast inputs incorporated NHTSA stopping-distance mandate compliance timelines and EU pedestrian safety regulation phase-in schedules.
Underlying measurement precision varies by segment; passenger car brake-by-wire volumes carry tighter precision than commercial vehicle redundant architectures due to OEM platform disclosure granularity. Forecasts reflect documented assumptions regarding electrification penetration rates and regulatory enforcement intensity. Rare earth export restriction scenarios or accelerated software-defined vehicle convergence would warrant strategic pause and re-evaluation of competitive positioning assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Engine Bearings Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Oil Filter Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Air Filter for Automotive Market