
 Spain Passenger Vehicles Lubricants Market | 2026-2036
Spain Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Passenger Vehicles Lubricants Market Analytics
A shortage of tribology-trained formulators is unwinding capacity expansion plans among domestic blenders. Repsol leverages its integrated refining footprint in Tarragona to secure base stock supply. CEPSA anchors its position through control of Andalusian distribution networks. ExxonMobil Corporation competes on synthetic product specialization for high-performance segments.
Spain passenger vehicles lubricants encompass refined petroleum-derived or synthetic base oils blended with additive packages containing detergents, dispersants, anti-wear agents, and viscosity index improvers, formulated to reduce friction, dissipate heat, and prevent component degradation in internal combustion and hybrid powertrains. Engine oil dominates volume flows as the most frequently consumed category across the vehicle parc, though demand for transmission fluid is accelerating with the spread of dual-clutch and continuously variable transmissions among Spanish SUV and crossover owners. Retail channels occupy the largest share of final sales, while online platforms represent the fastest-growing route as independent garages and DIY consumers shift procurement patterns.
Spain's lubricant sector operates under REACH chemical registration requirements, EU F-Gas Regulation constraints on fluorinated greenhouse gases, and national implementation of the EU Green Deal's decarbonization targets, which collectively pressure formulators toward biodegradable and lower-SAPS additive chemistries. The country's national chemical regulator enforces CLP hazard classification and labeling standards that affect import tolerances and domestic blending specifications. Stakeholders must monitor how Madrid's vehicle emissions zones and Catalonia's low-emission traffic restrictions reshape drain-interval expectations and product upgrade cycles.
Market Dynamics
Fleet operators in Madrid and Barcelona are extending oil drain intervals as they adopt newer engine architectures, compressing volume demand per vehicle while forcing formulators toward higher-performance synthetic grades to maintain revenue per unit.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance and fluorinated gas restrictions are redirecting formulation strategies toward lower-viscosity biodegradable grades, opening premium positioning for compliant blenders.
- Hybrid powertrain penetration:Dual-clutch and continuously variable transmissions among Spanish SUV owners are accelerating transmission fluid demand beyond traditional engine oil replacement cycles.
- Catalonia aftermarket density:The concentrated passenger car parc in Barcelona and surrounding provinces sustains high service bay throughput for independent garages and quick-lube chains.
Market Restraints
- Base stock supply concentration:Domestic blenders depend on integrated refiners in Tarragona and limited import channels, creating vulnerability to upstream allocation decisions.
- Technical talent scarcity:A shortage of tribology-trained formulators is unwinding capacity expansion plans among regional blenders seeking to launch synthetic product lines.
- Drain interval extension:OEM-recommended service intervals for newer Spanish-registered vehicles now stretch beyond 30,000 kilometers in some segments, directly compressing lubricant volume per vehicle.
Strategic Opportunities
- Andalusian distribution networks:Control of southern Spanish logistics corridors offers leverage to capture underserved independent garages beyond the Madrid-Barcelona axis.
- Online platform expansion:Digital procurement channels represent the fastest-growing route as DIY consumers and small independent garages shift away from traditional distributor relationships.
- Lower-SAPS additive chemistry:Madrid's vehicle emissions zones and Catalonia's low-emission traffic restrictions are reshaping drain-interval expectations toward products compatible with gasoline particulate filters.
Industry Challenges
- Tribology expertise gap:Spanish technical universities produce limited lubricant-specific graduates, forcing blenders to recruit from competing industries or import talent.
- CLP hazard classification timelines:ECHA-mandated labeling revisions require reformulation cycles that compress product development windows and strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Passenger Vehicles Lubricants Market |
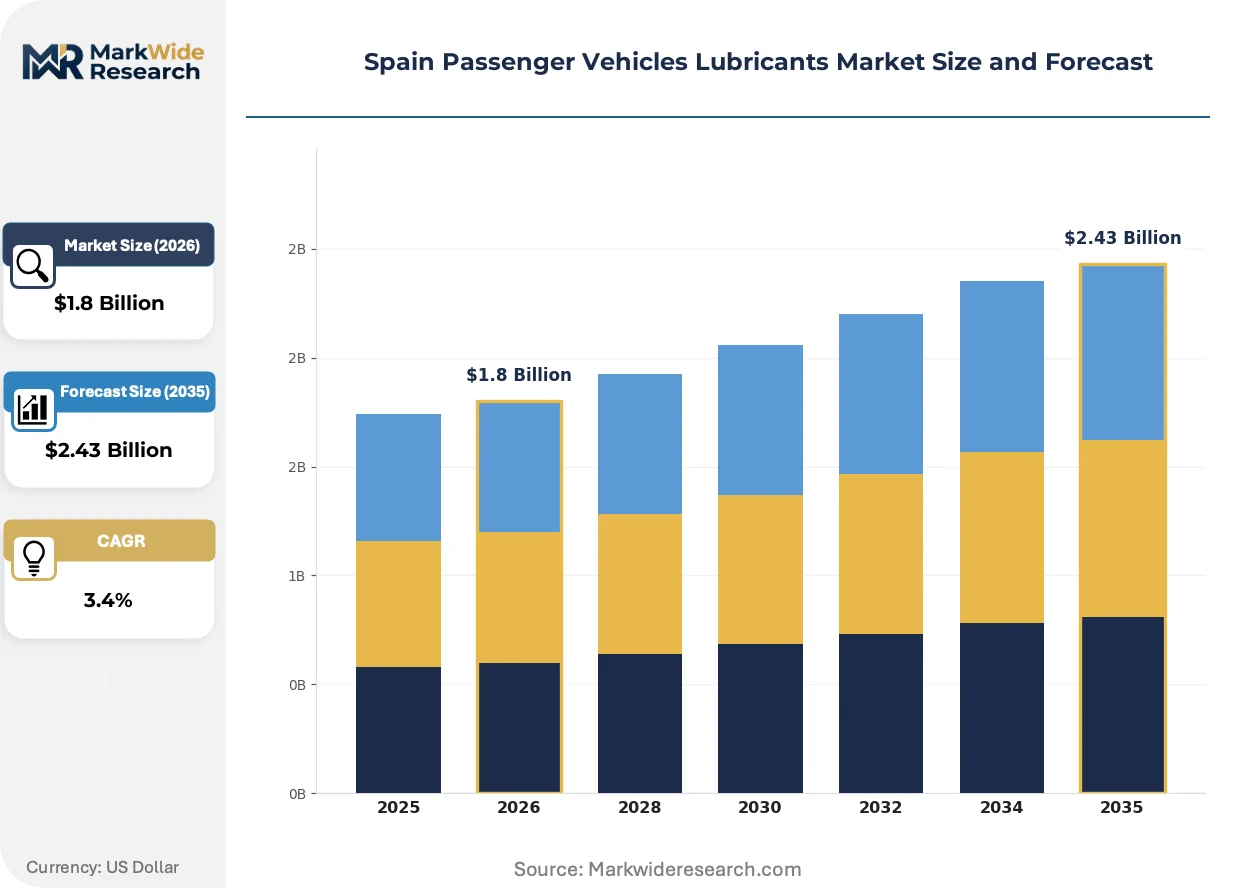
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Distribution Channel: Wholesale, Retail, Online, Direct Sales Vehicle Type: Passenger Cars, SUVs, Crossovers, Vans Application: Performance Enhancement, Maintenance, Engine Protection, Fuel Efficiency |
| Companies Covered | Royal Dutch Shell Plc, ExxonMobil Corporation, Repsol, FUCHS, Eni SpA, CEPSA, TotalEnergies, Chevron Corporation, BP PLC (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and procurement channels are undergoing parallel transformation as Spanish operators balance performance requirements against tightening environmental constraints and evolving fleet composition.
Synthetic base stocks with tailored viscosity profiles are decomposing the historical dominance of Group I and Group II mineral oils in mid-tier service fill applications. Fleet operators managing mixed-age vehicle pools in Madrid are adopting these grades selectively, prioritizing newer Euro 6-compliant units. This transition is compressing margin structures for blenders lacking backward integration into base stock supply.
REACH chemical registration requirements and ECHA's CLP hazard classification standards are forcing additive package redesigns across the Spanish blending sector. The industrial consequence is extended product qualification timelines and reformulation costs that favor larger formulators with dedicated regulatory affairs teams. High-performance synthetic segments serving luxury and performance vehicle owners in Barcelona are responding fastest, absorbing premium pricing for compliant chemistries.
Independent garages across Catalonia are consolidating their supplier relationships around fewer distributors offering bundled technical support and inventory management. Traditional route-based sales coverage is yielding to digital portals with same-day delivery commitments in dense urban corridors. This channel compression is most visible in Barcelona's metropolitan ring, where workshop density supports logistics economies that smaller provincial markets cannot replicate.
Spain Passenger Vehicles Lubricants Market Segmentation
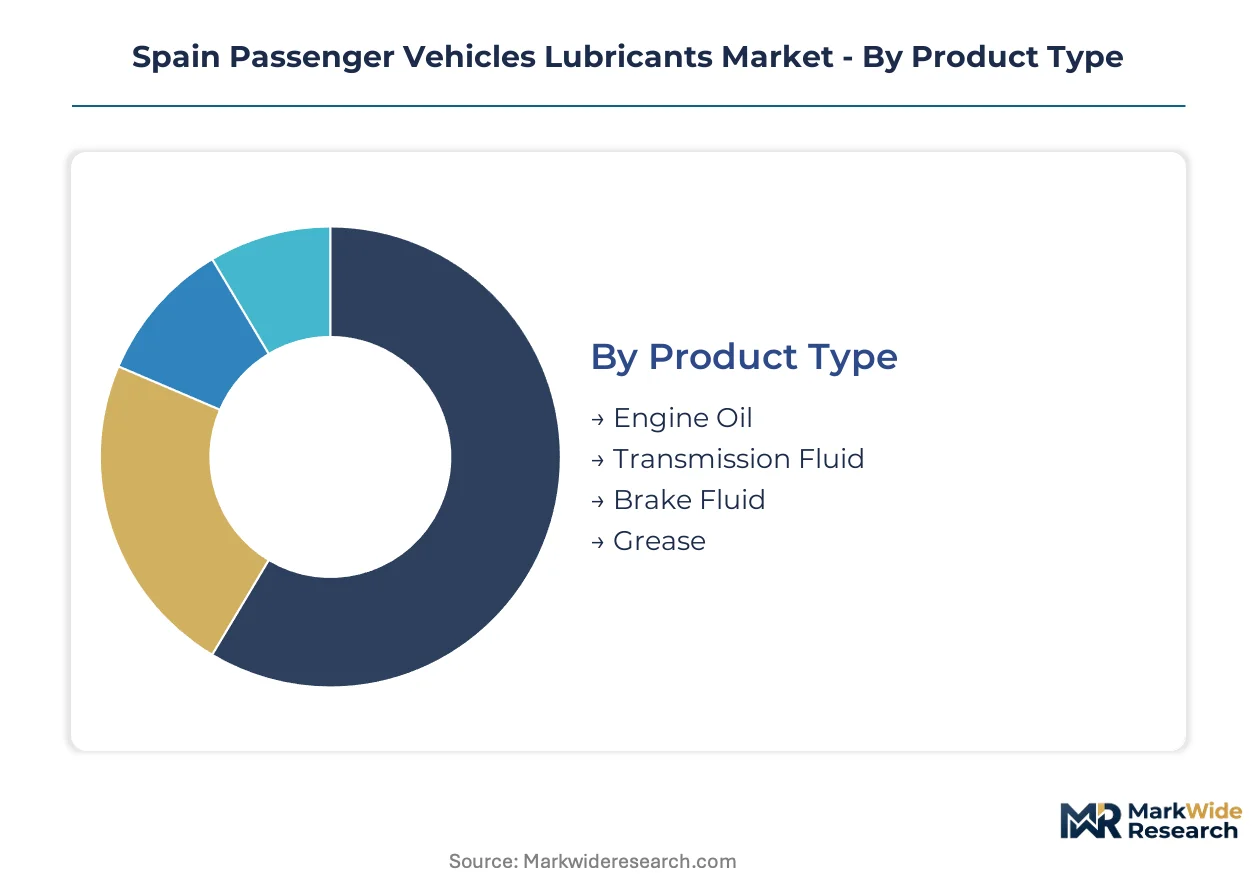
Segmentation in Spain's passenger vehicle lubricants market reveals how formulation requirements diverge across powertrain architectures and procurement channels. Understanding these divides exposes where synthetic upgrade cycles concentrate and which customer groups drive margin expansion.
Product Type:
Engine Oil faces the most acute substitution pressure from extended drain intervals and electrification trends, forcing formulators to defend volume through premium synthetic positioning.
- Engine Oil:Petroleum-derived or synthetic base stocks blended with detergents, dispersants, and anti-wear agents to reduce friction and dissipate heat in internal combustion powertrains. Demand concentrates in Catalonia's dense aftermarket service bay network, where Madrid's emissions zones and Barcelona's low-emission traffic restrictions accelerate replacement cycles for gasoline particulate filter-compatible formulations. Fleet operators extending intervals to 30,000 kilometers compress volume per vehicle while upgrading to higher-performance grades.
- Transmission Fluid:Specialized lubricants formulated for dual-clutch and continuously variable transmissions with precise viscosity profiles and friction modification. Spanish SUV and crossover owners in Barcelona's metropolitan ring drive the steepest demand acceleration as these transmission architectures penetrate the parc faster than national averages.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT specifications for thermal stability and corrosion inhibition. Workshops in Madrid's fleet corridors prioritize higher-grade formulations for newer braking systems.
- Grease:Thickened lubricants for chassis, wheel bearings, and ancillary components requiring water resistance and mechanical stability. Independent garages in Andalusia source these for aging vehicle pools less frequently serviced at quick-lube chains.
Engine Oil retains volume leadership; Transmission Fluid holds the steepest expansion curve.
Distribution Channel:
Channel selection in Spain reflects customer scale and technical support requirements, with procurement patterns diverging sharply between consolidated fleet buyers and fragmented independent operators.
- Wholesale:Bulk supply relationships serving quick-lube chains and multi-site garage groups with inventory management and technical backing. Catalonia's workshop consolidation around fewer distributors favors this channel in Barcelona's dense urban corridors.
- Retail:Counter sales through automotive parts stores and service stations to DIY consumers and small independent garages. This channel occupies the largest share of final sales nationally, anchored by Repsol's retail footprint and CEPSA's Andalusian network control.
- Online:Digital procurement portals with same-day delivery commitments gaining share fastest among independent garages shifting away from traditional distributor relationships. Barcelona's logistics economies support this channel's expansion where workshop density justifies fulfillment infrastructure.
- Direct Sales:Manufacturer-to-fleet arrangements for large operators with centralized procurement and specification control. Madrid's fleet corridors see concentrated activity as operators standardize lubricant grades across mixed-age vehicle pools.
Retail commands transaction volume leadership; Online channels gain share most rapidly.
Vehicle Type:
Powertrain diversification across Spain's passenger vehicle parc segments lubricant demand by service interval sensitivity and formulation sophistication requirements.
- Passenger Cars:The core volume base spanning compact to executive segments with varying OEM service specifications. Catalonia's dense parc sustains high throughput for standard drain intervals, though Madrid's emissions zones accelerate upgrade cycles for newer Euro 6-compliant units.
- SUVs:Higher-displacement powertrains and all-wheel-drive systems demanding specialized lubricants with enhanced thermal stability and load-carrying capacity. Spanish owners in Barcelona's metropolitan ring drive disproportionate demand for premium synthetic grades.
- Crossovers:Blended vehicle architectures with transmission and engine lubrication needs spanning car and SUV specifications. This segment's expansion tracks consumer preference shifts toward elevated ride height without full SUV operating costs.
- Vans:Commercial-duty cycles with severe service conditions requiring robust detergent packages and extended-drain-capable formulations. Fleet operators in Madrid's logistics corridors prioritize these specifications for utilization intensity.
Passenger Cars anchor volume; SUVs generate the most rapid specification upgrade cycles.
Application:
Functional positioning of lubricant formulations determines pricing architecture and technical validation requirements across Spain's aftermarket.
- Performance Enhancement:High-viscosity-index synthetics targeting luxury and performance vehicle owners seeking measurable output gains. Barcelona's premium vehicle concentration supports above-average adoption of these positioned formulations.
- Maintenance:Standard service-fill products meeting OEM minimum specifications for warranty compliance and baseline component protection. This application captures routine drain interval volume across Spain's independent garage network.
- Engine Protection:Additive-rich formulations emphasizing wear reduction and deposit control for high-mileage or severe-duty engines. Madrid's fleet operators specify these for vehicles operating beyond standard duty cycles.
- Fuel Efficiency:Lower-viscosity grades engineered to reduce parasitic losses and support emissions compliance. REACH and EU F-Gas Regulation alignment redirects formulator R&D toward this application as OEMs face tightening efficiency mandates.
Maintenance applications dominate transaction volume; Fuel Efficiency formulations climb the specification ladder fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia and Madrid consume lubricants differently from Spain's southern regions, with the northeast favoring premium synthetic grades for newer Euro 6 fleets while Andalusia sustains demand for conventional mineral oils serving aging vehicle pools.
Catalonia
Barcelona's dense passenger car parc and concentrated independent garage network drive the highest service bay throughput in Spain. The regional government's low-emission traffic restrictions accelerate replacement cycles for gasoline particulate filter-compatible formulations. Workshop consolidation in the metropolitan ring favors distributors offering bundled technical support and same-day digital delivery.
Madrid
Fleet operators in the capital's logistics corridors extend oil drain intervals beyond 30,000 kilometers as they adopt newer engine architectures. The municipal vehicle emissions zones enforce stricter compliance standards that reshape product upgrade cycles toward lower-SAPS additive chemistries. Centralized procurement among large fleet buyers concentrates demand for extended-drain-capable synthetic grades.
Andalusia
Aging vehicle pools in Seville and Málaga sustain demand for mineral-based engine oils and chassis greases less frequently serviced at quick-lube chains. CEPSA's control of regional distribution networks anchors supply relationships with independent garages. The absence of stringent emissions zones permits longer retention of conventional formulation specifications compared to northern Spain.
Basque Country
Industrial automotive suppliers in Bilbao and San Sebastián generate specialized demand for high-performance lubricants serving manufacturing equipment and test fleets. The regional government's industrial decarbonization programs align with EU Green Deal targets, pressuring formulators toward biodegradable base stocks. Proximity to French border markets creates cross-border procurement patterns for premium synthetic products.
Valencia
The port city's vehicle import and distribution hub status concentrates pre-delivery service fill demand for OEM-specified lubricants. Regional fleet operators balance mixed-age vehicle pools between conventional and synthetic grades. Logistics economies from the Mediterranean shipping corridor support bulk supply relationships with quick-lube chains expanding along the Levante coast.
Spain Passenger Vehicles Lubricants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic refiners leveraging captive base stock supply against multinational formulators competing on synthetic product breadth. Repsol and CEPSA anchor the integrated tier through Tarragona refining and Andalusian distribution control respectively. International oil majors occupy the specialist tier with focused synthetic portfolios. Capacity expansion and online platform development constitute the dominant competitive moves as blenders respond to channel compression.
Within the integrated tier, Repsol exemplifies backward integration into base stock supply, while CEPSA anchors southern Spanish distribution density. Among multinational specialists, ExxonMobil Corporation and FUCHS occupy positions emphasizing high-performance synthetic formulations. Royal Dutch Shell Plc represents the scale-driven archetype with portfolio breadth spanning mineral through fully synthetic grades. These three company groupings illustrate how competitive positioning diverges between supply security and technical specialization vectors.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Repsol |
| FUCHS |
| Eni SpA |
| CEPSA |
| TotalEnergies |
| Chevron Corporation |
| BP PLC (Castrol) |
| Others |
Value Network & Pricing Analysis
Synthetic base stock substitution for Group I and Group II mineral oils is simultaneously shifting supply geography toward integrated refiners in Tarragona and compressing pricing economics for blenders lacking backward integration into captive base stock production.
Pricing Analysis
Long-term offtake agreements between Madrid fleet operators and integrated refiners dominate volume procurement, while spot purchases serve Barcelona's independent garage network with volatile exposure to base stock allocation decisions. Three-tier pricing structure across premium synthetic, mid-tier synthetic blend, and economy mineral grades differentiates on API certification level and volume scale commitments. Pricing pressure stems from drain interval extension beyond 30,000 kilometers as Euro 6 engine architectures penetrate the Spanish parc. Fleet buyers with centralized procurement exhibit lowest price sensitivity; DIY consumers through retail channels show highest elasticity.
Supply Chain Analysis
Strategic stockpiling of additive packages characterizes larger blenders responding to ECHA-mandated CLP reformulation cycles, while just-in-time base stock delivery dominates smaller regional operators with limited working capital flexibility. Supply concentrates in Spain's Tarragona refining cluster, with secondary sourcing from Belgian and German base stock exporters. Formulation draws from Group III/IV base oils, polyalphaolefin synthetics, and detergent-dispersant additive packages. Single-source vulnerability to Repsol's Tarragona allocation decisions constitutes the primary structural risk. Distribution runs through CEPSA-controlled Andalusian corridors and Catalonia's consolidated distributor networks serving quick-lube chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against electrification-driven volume compression as hybrid powertrains and extended drain intervals substitute for traditional engine oil consumption cycles.
For Market Incumbents: Fortify position through captive control of Tarragona base stock supply and accelerated REACH-compliant formulation certification ahead of ECHA labeling revisions. CEPSA's Andalusian distribution density offers a template for channel consolidation against online platform encroachment. Prioritize synthetic product line expansion to offset per-vehicle volume erosion from 30,000-kilometer service intervals. For New Entrants and Emerging Players: ECHA fast-track registration for lower-SAPS additive chemistry opens regulatory arbitrage against incumbent reformulation lag. Target Andalusia's underserved independent garage network beyond Madrid-Barcelona logistics corridors. Digital procurement portals with same-day delivery commitments offer the most penetrable go-to-market angle where workshop density supports fulfillment infrastructure. For Investors and Strategic Acquirers: EU F-Gas Regulation alignment with REACH compliance deadlines reshapes the acquisition landscape toward blenders with dedicated regulatory affairs capacity and synthetic formulation expertise. Mid-term viability centers on formulators capable of serving gasoline particulate filter-compatible demand from Madrid's emissions zones and Catalonia's low-emission restrictions. Watch ECHA CLP enforcement intensity as the signal indicating consolidation pressure on sub-scale blenders lacking reformulation bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Supply | Repsol's Tarragona refining footprint secures formulation cost stability against allocation volatility. |
| Lower-SAPS Additive Chemistry Certification | ECHA CLP compliance opens premium positioning for Madrid emissions zone-compatible formulations. |
| Online Platform Expansion | Digital procurement with same-day delivery captures Barcelona garage network consolidation. |
| Andalusian Distribution Network Control | CEPSA's southern logistics corridors anchor relationships with aging vehicle pool service demand. |
| Synthetic Product Line Capacity Addition | Extended drain interval compression forces revenue defense through higher-margin grade substitution. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, EU trade statistics, and Spanish automotive registration databases through structured interviews with lubricant formulators, fleet procurement managers, and aftermarket distribution channel heads. Bottom-up volume estimates from Catalonia, Madrid, and Andalusia service bay throughput triangulate against top-down base stock consumption data from Tarragona refining disclosures.
Segmentation dimensions modeled span product type, distribution channel, vehicle architecture, and regional regulatory cluster across the projection horizon. CAGRs derive from vehicle parc aging curves, powertrain penetration assumptions, and drain interval extension trajectories. Forecast inputs incorporate OEM service specification evolution and EU F-Gas Regulation implementation timelines affecting formulation chemistry requirements.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued Madrid-Catalonia emissions zone expansion; material deviation in regulatory stringency or electrification pace would warrant model refresh. Revision becomes warranted when hybrid powertrain penetration crosses thresholds that fundamentally alter per-vehicle lubricant consumption coefficients.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Oil Filter Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Ball Bearing Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automotive Parking Heater Market