
 Auto Dimming Mirror Market | 2026-2036
Auto Dimming Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Dimming Mirror Market Intelligence
Electrochromic engineering talent scarcity is redrawing competitive boundaries in automotive mirror supply. Gentex Corporation leverages its captive glass-coating expertise to sustain North American OEM relationships. Magna International anchors its position through integrated electronics manufacturing across multiple vehicle platforms. Valeo SA competes by specializing in full-mirror-module architectures for European premium brands.
An auto dimming mirror employs electrochromic gel sandwiched between conductive glass layers that darkens proportionally to detected headlight glare, typically achieving 80-95% reflectance reduction within two seconds to eliminate driver distraction. The device serves primarily as a safety-critical cockpit component in passenger vehicles. Electrochromic technology leads value generation due to its established reliability and lower power draw versus LCD alternatives. OEM end users capture the dominant margin pool as factory-installed smart mirrors command pricing premiums over aftermarket retrofits. Digital mirrors represent the fastest-expanding product category, though regulatory homologation requirements in multiple jurisdictions constrain near-term volume.
NHTSA Federal Motor Vehicle Safety Standard 111 governs rear visibility and indirectly mandates minimum mirror performance thresholds in the United States. ECE Regulation 46 shapes European market access by specifying field-of-view and reflectance requirements for mirror systems. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces parallel visibility standards that Japanese suppliers like Murakami Corporation must satisfy for domestic OEM qualification. Stakeholders should monitor divergence between camera-monitor system permissibility and traditional mirror requirements as regulators evaluate full digital replacements.
Market Dynamics
Electrochromic gel chemistry expertise concentrates among a handful of glass-coating specialists, creating supply bottlenecks as automakers accelerate smart mirror specifications across EV lineups. This talent scarcity redistributes margin capture toward captive coating operations.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 111:Minimum rear visibility thresholds indirectly mandate performance benchmarks that OEMs address through factory-installed auto dimming systems rather than aftermarket alternatives.
- EV cockpit electronics premiumization:Chinese domestic producers specify intelligent mirror modules as standard equipment, normalizing advanced glare reduction across mid-tier vehicle segments.
- Electrochromic power efficiency:Sub-watt operational draw versus LCD alternatives preserves battery range in electrified powertrains, aligning with automaker efficiency targets.
Market Restraints
- Conductive glass substrate concentration:Precision float-glass production for electrochromic applications clusters among Japanese and German suppliers, exposing mirror manufacturers to input volatility.
- ECE Regulation 46 homologation timelines:Field-of-view and reflectance certification for digital mirror variants extends development cycles by 12-18 months versus conventional electrochromic units.
- Camera-monitor substitution threat:Full digital replacements eliminate physical mirror hardware entirely, compressing addressable market scope if regulatory permissibility expands.
Strategic Opportunities
- India passenger vehicle safety mandate expansion:Proposed amendments to Central Motor Vehicles Rules would mandate anti-glare devices in premium segments where penetration currently lags.
- Electrochromic-LiDAR housing convergence:Mirror module architectures integrate sensor enclosures, creating new value pools in ADAS-equipped vehicles.
- Direct OEM module supply contracts:Bypassing tiered electronics distributors captures margin and deepens platform-specific engineering relationships.
Industry Challenges
- Vacuum deposition technician scarcity:Thin-film coating expertise for electrochromic layers commands wage premiums that compress supplier operating margins.
- Legacy 12V electrical architecture integration:Smart mirror power and data requirements conflict with existing vehicle harness designs, forcing costly mid-cycle platform modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Dimming Mirror Market |
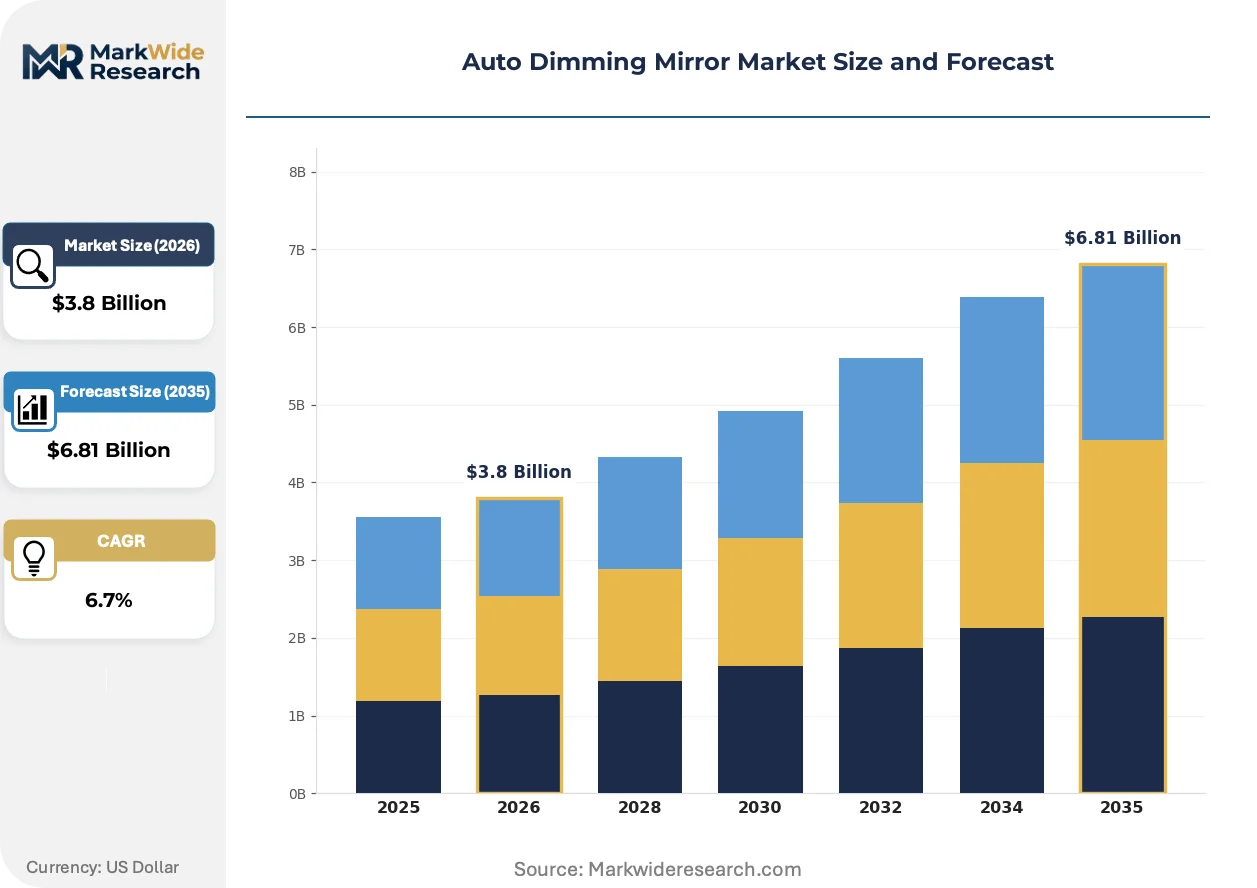
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Mirrors, Side View Mirrors, Digital Mirrors, Electrocchromatic Mirrors Technology: Photochromic, Electrochromic, LCD, LED End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Budget Vehicles Feature: Automatic Dimming, Anti-Glare, Integrated Navigation, Built-in Displays |
| Companies Covered | Gentex Corporation, Magna International Inc., Ficosa International, Valeo SA, Samvardhana Motherson Group, Murakami Corporation, Honda Lock Mfg. Co. Ltd., SL Corporation, Ichikoh Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Dimming Mirror Market Strategic Shifts & Innovations
Mirror system architectures are fragmenting into distinct technology stacks as automakers balance regulatory compliance against cockpit digitization roadmaps. This divergence creates parallel development tracks with incompatible supply bases.
Electrochromic gel technology is decomposing the traditional mirror value chain by separating optical performance from electronic control. Tier 1 suppliers now source coated glass from captive specialists while retaining module assembly and software integration. European premium brands accelerate this unbundling to preserve proprietary user-interface development. The separation compresses margins for undifferentiated assemblers while rewarding coating expertise holders.
Japan's Ministry of Land, Infrastructure, Transport and Tourism is evaluating camera-monitor system permissibility through amended safety standards that would permit full digital replacement of rear-view mirrors. This regulatory opening threatens electrochromic unit volumes if adopted. Domestic suppliers like Murakami Corporation are dual-developing both technologies to maintain OEM qualification regardless of outcome. The uncertainty forces parallel R&D investment without guaranteed returns.
Fleet procurement of safety equipment now specifies outcome-based performance metrics rather than component-level sourcing. Rental and commercial vehicle operators contract for guaranteed glare-reduction response times and failure rates. This shifts supplier relationships toward long-term service agreements with penalty clauses. North American fleet management companies lead this transition, pressuring mirror manufacturers to warranty electronic subsystems beyond traditional hardware lifecycles.
Auto Dimming Mirror Market Segmentation
Segmentation in auto dimming mirrors reveals how regulatory frameworks, powertrain electrification, and cockpit digitization reshape procurement priorities across distinct customer and technology categories. Understanding these divides exposes where margin pools concentrate and where substitution threats loom.
Product Type:
NHTSA Federal Motor Vehicle Safety Standard 111 and ECE Regulation 46 impose divergent homologation requirements that privilege certain mirror architectures over others in their respective jurisdictions.
- Rearview Mirrors:Interior-mounted units employing electrochromic gel between conductive glass substrates achieve 80-95% reflectance reduction within two seconds. Demand concentrates in Chinese EV lineups where domestic producers specify intelligent glare reduction as standard equipment across mid-tier segments.
- Side View Mirrors:Exterior units face stricter durability standards for temperature cycling and moisture ingress. European premium brands drive specifications here, integrating heating elements and blind-spot indicators that complicate electrochromic layering.
- Digital Mirrors:Camera-monitor systems eliminate physical glass entirely. Japan's Ministry of Land, Infrastructure, Transport and Tourism is evaluating amended safety standards that would permit full digital replacement, threatening electrochromic volumes if adopted.
- Electrochromatic Mirrors:Self-dimming technology using tungsten oxide and viologen-based gels dominates factory-installed applications. Sub-watt operational draw preserves battery range in electrified powertrains.
Established volume favors rearview mirrors; emerging adoption favors digital mirrors.
Technology:
Power efficiency and response latency separate technologies suitable for battery-electric vehicles from those confined to internal combustion architectures.
- Electrochromic:Gel-based systems darken proportionally to detected glare through redox reactions at the electrode-gel interface. Chinese domestic EV producers normalize this specification across vehicle tiers, creating the dominant demand pool.
- Photochromic:Silver halide-embedded glass darkens under UV exposure without electronic control. Slower response times relegate this technology to aftermarket retrofits and budget segments where OEM integration is absent.
- LCD:Liquid crystal shutters enable rapid switching but draw higher power than electrochromic alternatives. Limited penetration in range-sensitive EV applications constrains addressable market scope.
- LED:Active matrix displays overlay mirror functions with full information content. Regulatory homologation timelines extend development cycles by 12-18 months versus conventional units.
Cost tier separation positions electrochromic for premium-mid volume; LCD and LED climb fastest in technology-forward fleets.
End User:
Procurement authority and specification control determine whether advanced features reach production vehicles or remain aftermarket accessories.
- OEMs:Factory-installed smart mirrors command pricing premiums through integrated ADAS interfaces and proprietary software stacks. Direct module supply contracts bypass tiered electronics distributors to capture margin.
- Aftermarket Providers:Retrofit units compete on installation simplicity and compatibility with legacy 12V architectures. Fleet procurement of safety equipment now specifies outcome-based performance metrics with penalty clauses for failure rates.
- Vehicle Assemblers:Contract manufacturers without captive electronics engineering rely on tier 1 suppliers for complete mirror-module architectures.
- Budget Vehicles:Cost-constrained segments in India and Southeast Asia currently underpenetrate for anti-glare devices, though proposed amendments to Central Motor Vehicles Rules would mandate fitment in premium domestic segments.
Margin concentration favors OEMs; volume expansion favors budget vehicle mandate compliance.
Feature:
Feature bundling separates safety-mandated baseline configurations from discretionary premium offerings that drive average selling price differentiation.
- Automatic Dimming:Core electrochromic functionality responds to forward-facing light sensors. NHTSA visibility thresholds indirectly mandate this performance benchmark in US-bound vehicles.
- Anti-Glare:Supplementary coatings and polarization layers address edge-case lighting conditions. German and Japanese glare-reduction standards reshape product specifications for export markets.
- Integrated Navigation:Heads-up display overlays within mirror glass compete with dashboard and windshield projection systems for cockpit real estate.
- Built-in Displays:Full video integration enables rear camera feed and telematics readouts. Electrochromic-LiDAR housing convergence creates new value pools in ADAS-equipped vehicles.
Regulatory compliance favors automatic dimming; feature differentiation favors built-in displays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standard 111 anchors United States market access requirements, while divergent regulatory timelines across Germany, Japan, China, and India fragment procurement specifications for mirror system suppliers.
United States
Fleet management companies and premium OEMs drive factory-installed smart mirror specifications. NHTSA visibility thresholds mandate performance benchmarks that favor integrated electrochromic systems over aftermarket alternatives. Michigan and Ohio automotive clusters concentrate Tier 1 module assembly operations serving Detroit-based OEMs.
Germany
European premium brands specify exterior mirror modules with heating elements and blind-spot integration. ECE Regulation 46 shapes field-of-view and reflectance certification requirements. Stuttgart and Munich engineering centers develop proprietary user-interface stacks that accelerate value chain unbundling.
China
Domestic EV producers normalize intelligent glare reduction as standard equipment across mid-tier segments. The country's national automotive safety regulator evaluates amended visibility standards alongside rapid electrification targets. Shanghai and Shenzhen electronics corridors concentrate coating specialists and module integrators.
Japan
The Ministry of Land, Infrastructure, Transport and Tourism assesses camera-monitor system permissibility for full digital mirror replacement. Murakami Corporation and domestic suppliers dual-develop both electrochromic and digital technologies. Aichi and Tokyo metropolitan areas host captive glass-coating operations and OEM qualification facilities.
India
Proposed amendments to Central Motor Vehicles Rules would mandate anti-glare devices in premium passenger vehicle segments. Current underpenetration in cost-constrained tiers creates mandate-driven expansion potential. Maharashtra and Tamil Nadu automotive belts concentrate vehicle assembly and emerging electronics manufacturing.
Auto Dimming Mirror Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in mirror system supply. Captive glass-coating operations and module assembly capabilities separate the upper tier from undifferentiated assemblers below. Three archetypes dominate: coating-integrated specialists, full-module architects, and electronics-integrated diversified suppliers. Competitive moves concentrate on direct OEM contract capture and electrochromic-LiDAR housing convergence for ADAS-equipped vehicles.
Within the coating-integrated tier, Gentex Corporation and Murakami Corporation exemplify captive expertise strategies that preserve margin capture. Magna International occupies a position among diversified automotive suppliers leveraging cross-platform electronics manufacturing. Valeo SA anchors the European full-module architecture segment serving premium brand specifications.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International Inc. |
| Ficosa International |
| Valeo SA |
| Samvardhana Motherson Group |
| Murakami Corporation |
| Honda Lock Mfg. Co. Ltd. |
| SL Corporation |
| Ichikoh Industries |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day electrochromic gel coating lead times concentrate margin capture among Japanese and German glass specialists, compressing assembler pricing power while amplifying premiums for captive coating operations serving OEM direct contracts.
Pricing Analysis
Factory-to-dealer price spreads between German electrochromic modules and Chinese domestic EV specifications reach three-to-one multiples. Premium-mid-economy pricing differentiation rests on certification grade and after-sales service bundling. Cost compression in undifferentiated assembler tiers is intensifying because conductive glass substrate concentration limits supplier alternatives. Fleet procurement managers exhibit highest price sensitivity; European premium OEMs show least.
Supply Chain Analysis
Precision float-glass production for electrochromic applications creates chokepoints as Japanese and German suppliers control conductive substrate output. The supply chain draws from Japan, Germany, and China for coated glass, electrochromic gel chemistries, and sensor integration components. Single-source vulnerability in vacuum deposition technician pools threatens coating capacity expansion. Distribution runs through Tier 1 module integrators to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-monitor system regulatory permissibility threatens physical mirror hardware demand, forcing incumbents to defend electrochromic positions while building parallel digital capabilities.
For Market Incumbents: Consolidate coating expertise through captive glass operations or exclusive supply agreements with Japanese and German substrate specialists. Deepen OEM platform engineering relationships to embed electrochromic-LiDAR housing convergence ahead of digital substitution timelines. Digital mirror regulatory approval in Japan signals the threat trajectory. For New Entrants and Emerging Players: Lead with aftermarket retrofit solutions for India's cost-constrained vehicle tiers as proposed Central Motor Vehicles Rules amendments create mandate-driven demand windows. Target fleet procurement contracts specifying outcome-based glare-reduction performance with penalty clauses that incumbent assemblers struggle to warranty. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive electronics parents where mirror modules represent non-core revenue pools with stranded coating expertise. Long-term viability hinges on dual-technology portfolios spanning electrochromic and digital architectures. Watch Japan's Ministry of Land, Infrastructure, Transport and Tourism camera-monitor rulings as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochromic-LiDAR Housing Convergence | Mirror module architectures capture ADAS sensor integration value pools in premium EV lineups. |
| Direct OEM Module Supply Contracts | Bypassing tiered electronics distributors captures margin and deepens platform-specific engineering relationships. |
| Dual-Technology R&D Investment | Parallel electrochromic and digital development maintains OEM qualification regardless of regulatory outcomes. |
| India Market Entry Positioning | Proposed Central Motor Vehicles Rules amendments create mandate-driven premium segment expansion opportunities. |
| Fleet Service Agreement Structuring | Outcome-based performance contracts with penalty clauses shift supplier relationships toward long-term recurring revenue. |
Research Approach
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, NHTSA safety standard filings, and ECE Regulation documentation. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads inform demand-side validation. Bottom-up unit economics triangulate against top-down market sizing across electrochromic gel chemistry, module assembly, and digital mirror system categories.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derive from production volume trajectories, technology substitution curves, and regulatory mandate timelines. Industry-specific inputs include NHTSA Federal Motor Vehicle Safety Standard 111 compliance thresholds and Japan's camera-monitor system evaluation progress.
The analysis sits within stated boundaries; outcomes outside sustained EV electrification targets or accelerated digital mirror regulatory permissibility would require recalibration. Practitioners should keep alternative scenarios live as ECE Regulation 46 homologation timelines and Chinese domestic EV specification trends evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Railway Interior Lighting Market