
 Automotive Cabin Air Filter Market | 2026-2036
Automotive Cabin Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cabin Air Filter Market Analytics
Filter bundling with HVAC maintenance packages is shifting buyer choice from standalone component purchases toward scheduled service contracts. Mann+Hummel leverages its vertical integration across nonwoven media and filter housing production to control cost positions in OEM supply. Freudenberg Filtration Technologies anchors its position through specialized R&D in multi-layer composite media for electric vehicle cabin systems. Robert Bosch GmbH extends its channel reach via direct ties to European and Asian vehicle assemblers.
An automotive cabin air filter is a pleated, nonwoven or composite media barrier installed within a vehicle's ventilation system to capture particulate matter, pollen, volatile organic compounds, and exhaust intrusion, typically rated between 15 and 30 grams per square meter basis weight with efficiency thresholds calibrated to ISO 5011 or equivalent test protocols. Its primary commercial purpose is to protect occupant respiratory health while preserving HVAC evaporator coil cleanliness and airflow efficiency. HEPA filters command premium positioning due to rising consumer sensitivity to ultrafine particulate retention, while carbon filters compete on odor and gas-phase contaminant adsorption in urban fleet applications. Electrostatic filters occupy a developing niche where lower pressure drop benefits electric vehicle thermal management constraints.
The EPA maintains emission and material safety oversight that indirectly governs filter substrate chemistry, while the EU Green Deal and F-Gas Regulation shape refrigerant-linked HVAC system redesigns that cascade into filter form-factor requirements. ISO 5011 and SAE J726 provide the test velocity and dust-loading benchmarks that manufacturers must meet for aftermarket certification and OEM qualification. Stakeholders should monitor how China GB standards and evolving California Air Resources Board interior air quality guidelines will harmonize or diverge on ultrafine particle counting methods.
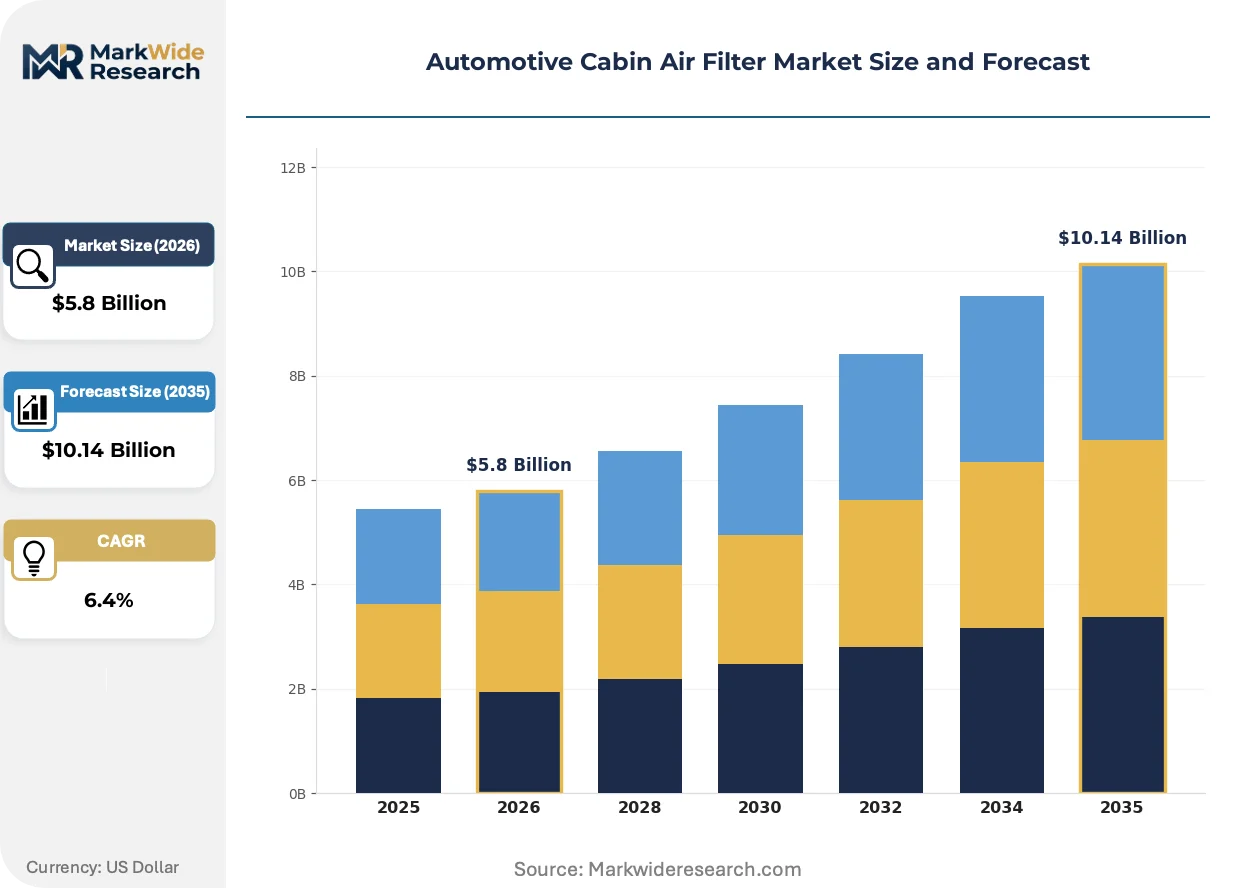
Market Dynamics
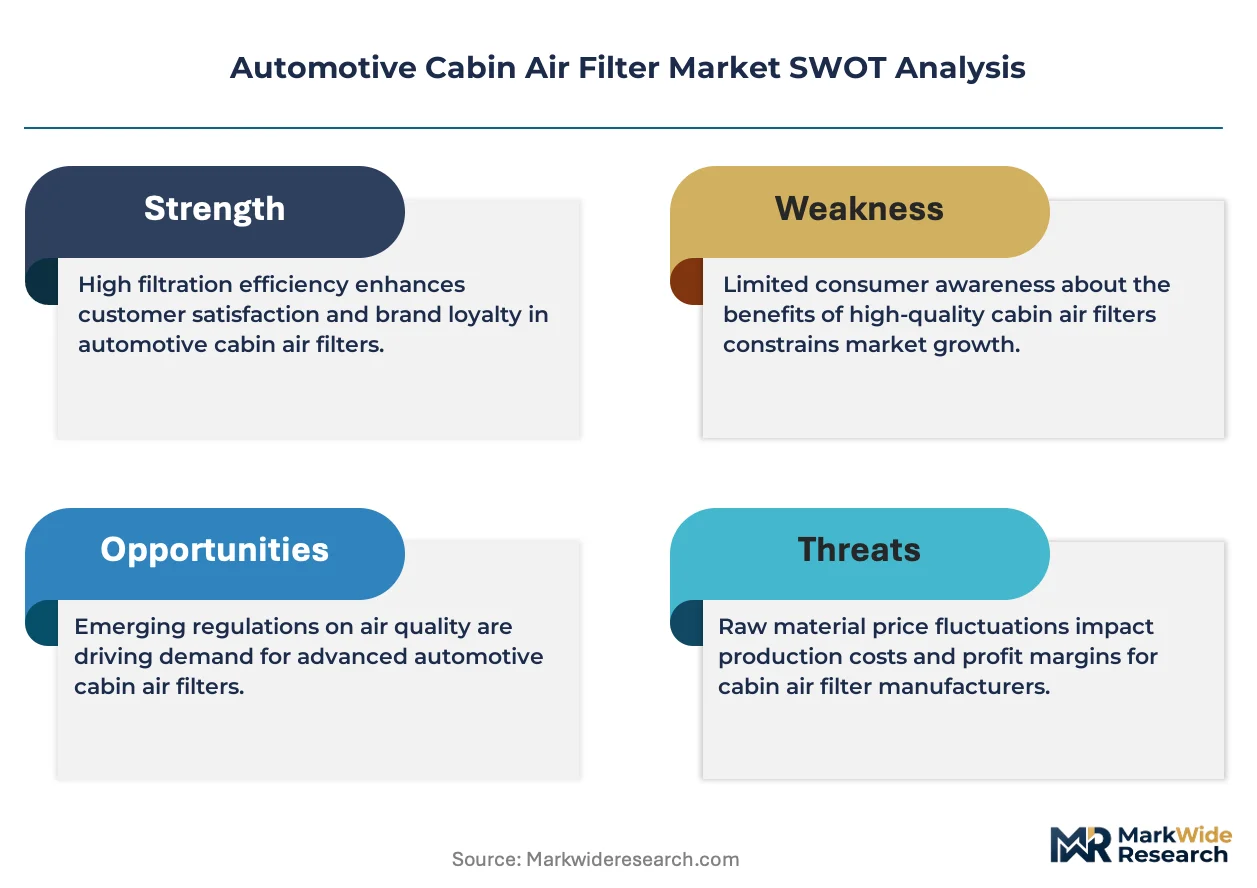
HEPA-grade filtration mandates from EPA and EU regulators are compressing material substitution timelines, forcing nonwoven suppliers to recalibrate meltblown capacity toward higher-efficiency media while OEMs redesign HVAC module form factors to accommodate thicker pleat packs.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phaseout timelines accelerate HVAC system redesigns, creating synchronized filter replacement cycles across European vehicle fleets as thermal management architectures consolidate.
- Electric vehicle thermal constraints:Battery-electric powertrains demand lower pressure-drop media to preserve range, pulling electrostatic and nanofiber-laminated filters into mainstream specification.
- China GB standards evolution:Draft interior air quality protocols targeting ultrafine particle counting are compelling domestic OEMs to pre-certify HEPA-grade systems ahead of formal adoption.
Market Restraints
- Polypropylene resin volatility:Meltblown nonwoven feedstock costs fluctuate with crude-oil derivatives, squeezing margin on standard-grade pleated media.
- German supplier concentration:Captive meltblown capacity clusters among three major filtration conglomerates, limiting second-source options for tier-two module assemblers.
- ISO 5011 test velocity limitations:Current protocols understate real-world urban particulate loading, creating certification gaps that delay aftermarket product launches.
Strategic Opportunities
- India aftermarket underpenetration:Independent repair channels in Delhi and Mumbai lack standardized filter replacement protocols, opening direct-to-workshop distribution models.
- Carbon-HEPA composite convergence:Dual-function media addressing gas-phase and particulate capture simultaneously reduces module count in premium EV cabin systems.
- Subscription maintenance bundling:OEM service networks in the United States pilot scheduled filter replacement tied to telematics-triggered HVAC performance alerts.
Industry Challenges
- Multi-layer lamination expertise:Composite media production requires precision coating and calendering skills scarce outside established European and Japanese supplier bases.
- SAE J726 harmonization delays:Divergent dust-loading protocols between North American and Asian test houses extend qualification timelines for cross-regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cabin Air Filter Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Carbon Filters, Electrostatic Filters, Particulate Filters End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers Installation Type: In-Garage, DIY, Professional, Mobile Services |
| Companies Covered | Donaldson Company, Inc., Freudenberg Filtration Technologies, Mann+Hummel, Hengst SE, Sogefi SpA, Robert Bosch GmbH, MAHLE GmbH, K&N Engineering, Inc., DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cabin Air Filter Market Evolving Landscape
Active filtration media are converging with sensor-integrated HVAC modules, creating demand for smart filter cartridges that communicate contaminant load status to vehicle telematics platforms and trigger predictive replacement workflows.
Nanofiber-laminated meltblown composites are unifying particulate and gas-phase capture in single-pleat architectures. Tier-one HVAC module suppliers in Germany and Japan are qualifying these media for 2027 platform releases. This unification is compressing the traditional separation between HEPA and activated-carbon supply chains, forcing material houses to develop hybrid coating competencies or cede position to integrated competitors.
REACH chemical safety dossiers are tightening substrate chemistry disclosure requirements for nonwoven binders and additives. ECHA substance evaluation timelines now extend 18-24 months for novel fluoropolymer treatments common in oleophobic filter media. European OEMs are responding by accelerating qualification of silicone-based alternatives ahead of potential restriction scenarios.
Fleet operators are consolidating filter procurement through national leasing and rental companies rather than fragmented dealer service networks. This buyer concentration in the United States and United Kingdom is compressing price negotiation cycles and favoring suppliers with direct national account coverage. The shift is most visible in urban ride-hail and corporate fleet segments where utilization rates drive 15,000-mile replacement intervals versus retail consumer 30,000-mile averages.
Automotive Cabin Air Filter Market Segmentation
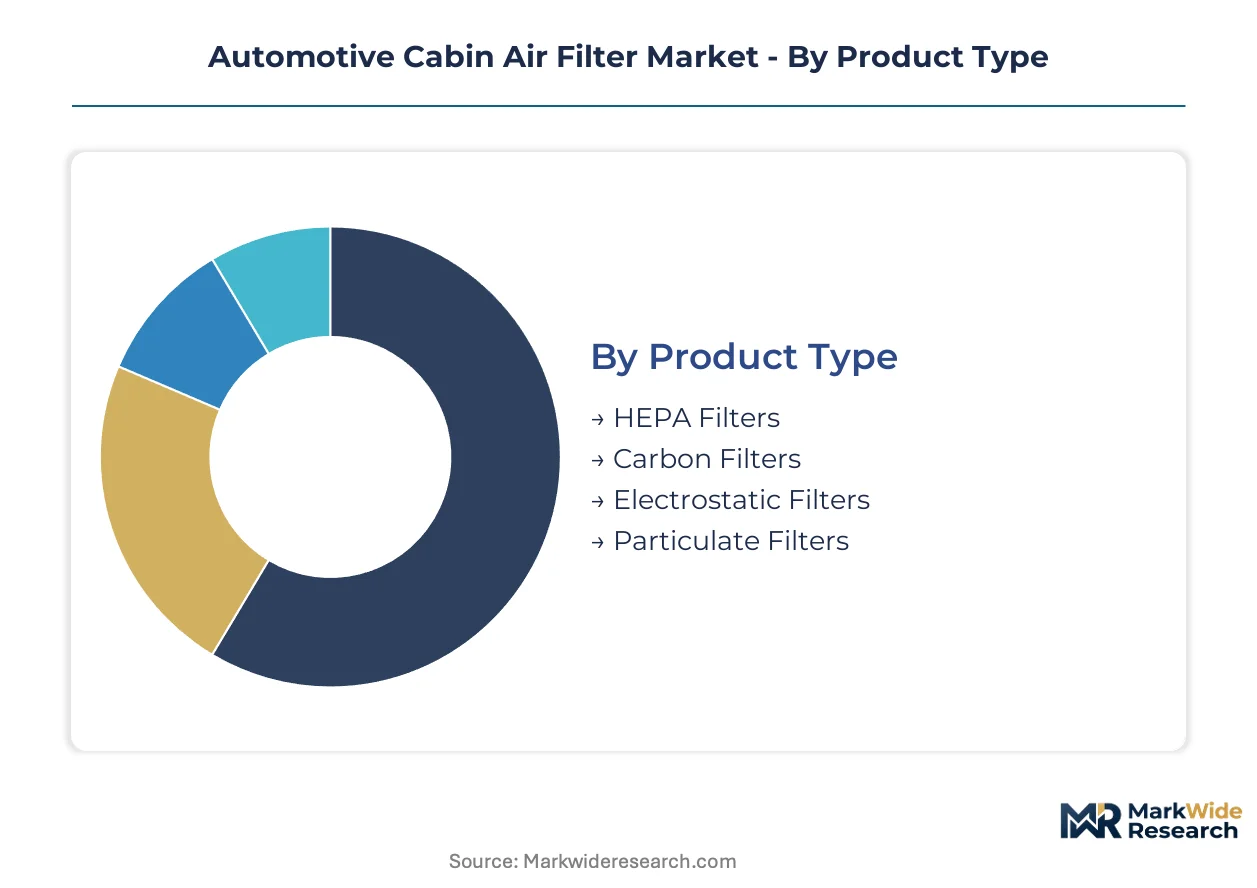
Automotive cabin air filter segmentation reflects divergent technical requirements across propulsion types and purchasing behaviors. Filter media specifications, installation protocols, and channel economics vary sharply between electric vehicle thermal constraints and legacy internal combustion fleet maintenance patterns.
Product Type:
Integration depth separates standalone particulate barriers from multi-functional composite systems serving HVAC modules.
- HEPA Filters:Pleated meltblown nonwoven media rated to 99.97% efficiency at 0.3 microns, constructed with 25-40 gram per square meter basis weight. Demand concentrates in Germany and China where OEMs pre-certify systems ahead of EPA and EU interior air quality mandates. Premium positioning reflects consumer respiratory sensitivity and regulatory compression timelines.
- Carbon Filters:Activated-carbon impregnated substrates adsorbing volatile organic compounds and exhaust intrusion, typically laminated to particulate layers. Urban fleet applications in Delhi and Mumbai drive replacement frequency due to ambient pollution loading. Gas-phase capture requirements are displacing standalone particulate solutions in premium cabin systems.
- Electrostatic Filters:Charged fiber media achieving lower pressure drop for battery-electric vehicle thermal management constraints. Nanofiber-laminated variants are qualifying for 2027 platform releases in Japan.
- Particulate Filters:Standard cellulose or synthetic nonwoven barriers capturing pollen and coarse dust, dominant in economy vehicle segments and emerging market aftermarket channels.
Particulate filters lead volumes today; HEPA configurations are gaining share fastest.
End User:
Procurement scale and technical specification authority determine margin structure across the value chain.
- OEMs:Direct sourcing relationships with tier-one HVAC module suppliers, specifying media efficiency and form-factor for platform-level integration. Design-in cycles span 36-48 months with qualification protocols tied to ISO 5011 and SAE J726 benchmarks.
- Aftermarket Providers:Independent repair networks and parts distributors serving replacement demand through standardized catalog coverage. Channel expansion programs in the United States and Germany emphasize scheduled maintenance bundling.
- Fleet Operators:National leasing and rental companies consolidating procurement through direct supplier relationships, compressing price negotiation cycles with 15,000-mile replacement intervals versus retail 30,000-mile averages.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing filter cartridges as part of complete HVAC module supply agreements.
OEMs dominate value capture; fleet operators are expanding procurement fastest.
Distribution Channel:
Channel selection correlates with buyer technical sophistication and replacement urgency requirements.
- Online Retail:E-commerce platforms serving DIY installers with catalog-filtered compatibility databases and subscription replenishment programs. Growth reflects telematics-triggered predictive replacement workflows in United States pilot programs.
- Specialty Stores:Dedicated automotive parts retailers offering technical consultation and same-day availability for professional installers. Concentrated in Germany and United States urban corridors.
- Direct Sales:Manufacturer-to-workshop relationships bypassing distributor markups, emerging in India aftermarket underpenetration zones.
- Wholesalers:Regional distribution networks serving fragmented independent repair channels with consolidated logistics and inventory pooling.
Specialty stores anchor volume today; online retail is climbing the fastest.
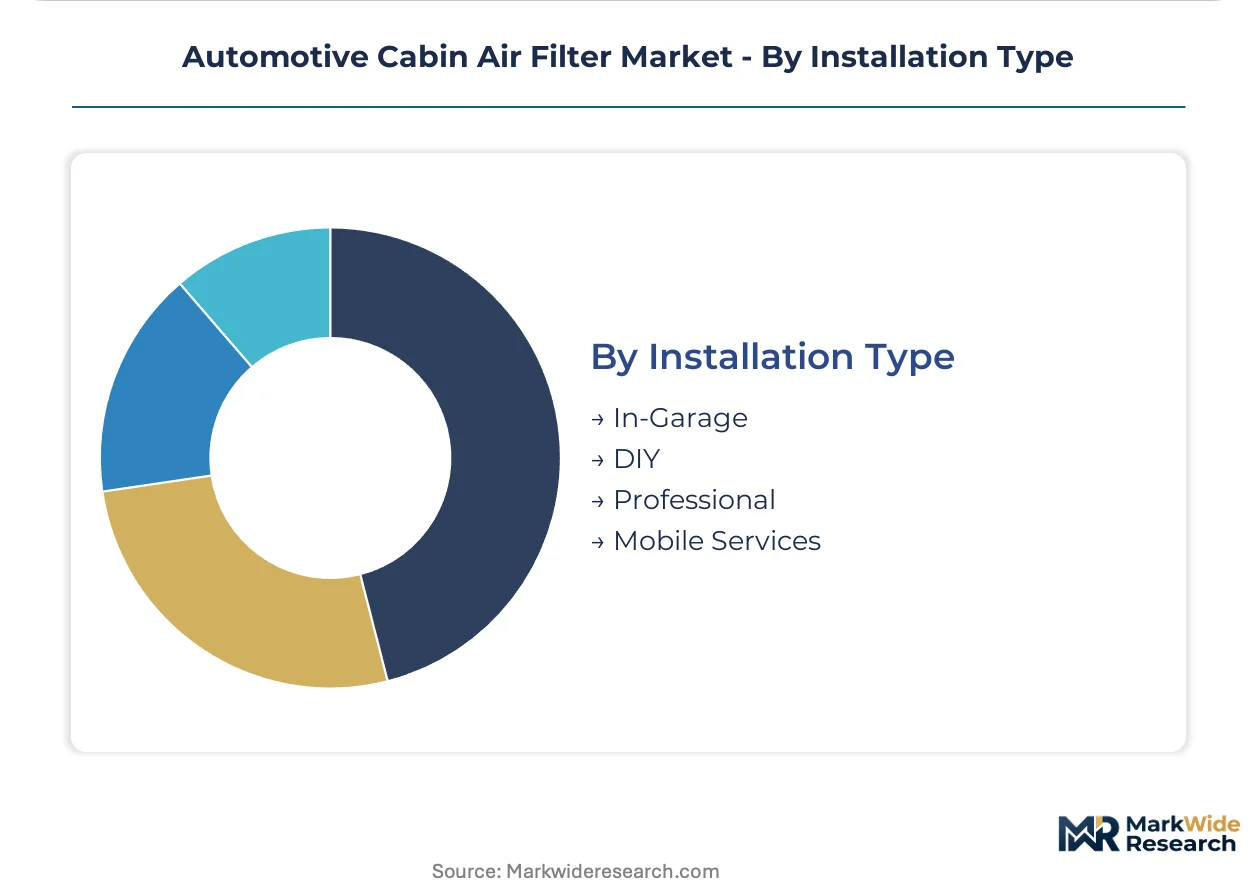
Installation Type:
Service modality selection reflects labor cost structures and vehicle accessibility constraints.
- In-Garage:Fixed-location service bays with lift access and specialized HVAC diagnostic equipment, standard for complex cabin system architectures. Dominant in Germany OEM service networks.
- DIY:Consumer self-installation supported by tool-free access designs in economy vehicle segments. Online tutorial content and compatibility verification tools reduce purchase friction.
- Professional:Certified technician service through dealer and independent repair channels, required for warranty-preserving replacement in premium vehicle segments.
- Mobile Services:On-location filter replacement via van-based technicians, expanding in United States urban ride-hail fleet segments with high utilization rates.
Professional installation leads volumes today; mobile services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive cabin air filtration standards through its dense OEM supplier networks. The industry now distributes manufacturing and certification capacity across four additional industrial centers.
Germany
Mann+Hummel and Freudenberg anchor meltblown nonwoven production for HEPA-grade systems serving BMW, Mercedes-Benz, and Volkswagen platforms. The EU F-Gas Regulation accelerates HVAC module redesigns that cascade into synchronized filter replacement cycles. Stuttgart and Mannheim host the densest clusters of tier-one HVAC module suppliers qualifying nanofiber-laminated media for 2027 electric vehicle releases.
China
Draft GB standards for interior air quality pre-certification are compelling domestic OEMs to adopt HEPA-grade filtration ahead of formal adoption. MIIT's dual carbon goals pressure battery-electric vehicle thermal management designs toward lower pressure-drop media. Shanghai and Shenzhen concentrate electrostatic filter development for BYD, NIO, and XPeng supply chains.
United States
Fleet operators consolidate procurement through national leasing companies, compressing price cycles with 15,000-mile replacement intervals. EPA emission oversight indirectly governs filter substrate chemistry through material safety protocols. Michigan and Tennessee anchor OEM service network expansion for scheduled maintenance bundling programs.
Japan
DENSO Corporation's HVAC module supply agreements drive specification authority for nanofiber-laminated composites in 2027 platform releases. METI's energy efficiency guidelines shape thermal management constraints favoring electrostatic media. Nagoya and Tokyo-Yokohama clusters specialize in precision coating and calendering for multi-layer laminations.
India
Independent repair channels in Delhi and Mumbai lack standardized replacement protocols, opening direct-to-workshop distribution models. BIS certification requirements for automotive components are tightening import substitution incentives for domestic filter media production. Pune and Chennai emerging as assembly points for HVAC module suppliers serving Maruti Suzuki and Tata Motors.
Automotive Cabin Air Filter Market Competitive Landscape
The competitive structure tilts toward vertically integrated filtration conglomerates with captive meltblown capacity. Three major German suppliers control the majority of high-efficiency nonwoven media production, limiting second-source options for tier-two module assemblers. Strategic archetypes include integrated material-to-module houses, specialized composite media developers, and channel-focused aftermarket distributors. Competitive moves concentrate on backward integration into nonwoven feedstock and direct national account coverage for fleet procurement consolidation.
Among Germany-based filtration specialists, Mann+Hummel, Freudenberg Filtration Technologies, and Hengst SE occupy positions exemplifying the integrated material-to-module archetype. These entities represent upstream control over meltblown capacity and downstream HVAC module supply relationships. Robert Bosch GmbH anchors a distinct position through channel reach extension into European and Asian vehicle assemblers. The aftermarket vector includes K&N Engineering, Inc., which sits within the performance-oriented replacement segment. DENSO Corporation exemplifies the Asia-Pacific integrated supplier model with specification authority tied to complete thermal system supply.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Freudenberg Filtration Technologies |
| Mann+Hummel |
| Hengst SE |
| Sogefi SpA |
| Robert Bosch GmbH |
| MAHLE GmbH |
| K&N Engineering, Inc. |
| DENSO Corporation |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation through national leasing companies in the United States and United Kingdom compresses price negotiation cycles and forces suppliers to absorb polypropylene resin volatility or cede volume to integrated competitors with captive meltblown capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction patterns, with HEPA-grade certification and carbon-HEPA composite functionality commanding spreads over cellulose-based particulate barriers. Price differentiation stems from ISO 5011 qualification tier and volume scale in fleet procurement contracts. Pricing pressure stems from polypropylene feedstock cost volatility squeezing margin on standard-grade pleated media. Fleet operators exhibit highest price sensitivity due to 15,000-mile replacement intervals, while premium OEM channels absorb certification premiums with lower elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German meltblown nonwoven production concentrated among Mann+Hummel, Freudenberg, and Hengst SE, limiting second-source options for tier-two HVAC module assemblers. Manufacturing gravity centers on Germany, China, and Japan, with emerging assembly points in Pune and Chennai serving domestic OEM requirements. Raw material dependencies rest on polypropylene resin, activated carbon substrates, and nanofiber coating chemicals. Tariff exposure on imported nonwoven media threatens margin structures for regional assemblers lacking backward integration. Distribution runs through OEM service networks, national fleet accounts, and fragmented independent repair channels with diverging technical specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by HEPA-grade pre-certification mandates ahead of formal EPA and EU interior air quality adoption compressing substitution timelines toward premium specifications.
For Market Incumbents: Deepen captive meltblown capacity control to defend against polypropylene cost volatility and tier-two module assembler price aggression. Accelerate nanofiber-laminated composite qualification for 2027 electric vehicle platform releases to anchor specification authority before second-source options emerge. Channel control through direct national fleet account coverage protects margin against leasing company procurement consolidation. For New Entrants and Emerging Players: Independent repair channels in Delhi and Mumbai represent the most penetrable buyer archetype lacking standardized replacement protocols and integrated supplier relationships. Direct-to-workshop distribution models bypass entrenched wholesaler markups in this underpenetrated aftermarket zone. Carbon-HEPA composite convergence for premium electric vehicle cabin systems offers specification entry points before incumbent hybrid coating competencies mature. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized composite media developers possessing precision coating and calendering capabilities scarce outside established European and Japanese supplier bases. Long-term viability favors acquisition targets with REACH-compliant silicone-based substrate chemistry ahead of potential fluoropolymer restriction scenarios. The signal to watch is SAE J726 harmonization progress between North American and Asian test houses as inflection indicator for cross-regional product launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Meltblown Nonwoven Production | Captive polypropylene media supply insulates margin from crude-oil derivative volatility affecting standard-grade pleated filters. |
| Nanofiber-Laminated Composite Qualification | 2027 platform releases in Germany and Japan reward early certification with specification lock-in for electric vehicle thermal constraints. |
| Direct National Fleet Account Coverage | Leasing company procurement consolidation in the United States and United Kingdom demands bypass of traditional distributor markups. |
| REACH-Compliant Silicone-Based Substrate Development | ECHA substance evaluation timelines for fluoropolymer treatments create competitive exposure for non-compliant material houses. |
| Telematics-Triggered Predictive Replacement Pilot Programs | OEM service networks in Michigan and Tennessee test subscription bundling that shifts buyer choice from standalone components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-one HVAC module procurement officers, OEM platform engineers, aftermarket distributor operations heads, and fleet leasing company category managers with secondary validation against vehicle production databases, IHS Markit registration data, EPA emission filings, and EU F-Gas Regulation implementation trackers. Bottom-up filter unit economics and top-down HVAC system value chain assessments were cross-referenced for triangulation.
Historical reference periods anchored volume and value outputs to established replacement cycle patterns and OEM platform launch cadences across the modeling period. Segmentation dimensions modeled include filter media grade tier, propulsion architecture thermal constraint, OEM versus aftermarket channel, and regional regulatory cluster. CAGRs were derived from unit shipment trajectories and average selling price evolution calibrated to material cost pass-through assumptions and certification premium sustainability.
Underlying measurement precision varies by segment; HEPA-grade and electrostatic filter categories carry tighter precision than standard particulate barriers due to more concentrated supplier reporting. Forecasts reflect assumptions regarding EPA and EU regulatory adoption timelines, polypropylene resin cost trajectories, and electric vehicle thermal management architecture standardization that could revise outlooks if divergent scenarios materialize. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
China Automotive Seats Market