
 Decorative Car Accessories Market | 2026-2036
Decorative Car Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Car Accessories Market Analysis
REACH is recalibrating the cost-of-entry calculus for European suppliers of decorative car accessories, forcing reformulation of plastics and synthetic leather to meet restricted substance thresholds. Robert Bosch GmbH leverages its automotive electronics heritage to integrate ambient lighting modules that comply with evolving material standards. 3D Carbon Automotive Corp. specializes in exterior aerodynamic add-ons that navigate varying national type-approval requirements across EU member states. Continental AG anchors its position through in-house polymer compounding that sustains supply chain control over REACH-compliant feedstocks.
Decorative car accessories encompass aftermarket and OEM-affiliated products designed to alter vehicle aesthetics, comfort, or perceived value through non-structural modifications to interior and exterior surfaces. Manufacturing spans injection-molded ABS plastics, thermoformed polyurethane leather, compression-molded rubber floor mats, and LED-embedded lighting strips with IP67 ingress protection ratings for exterior applications. Seat covers and floor mats in leather and fabric materials occupy the largest revenue pool, reflecting their universal fitment across vehicle classes and shorter replacement cycles. Exterior enhancements in lighting applications represent the fastest-growing margin segment, driven by LED technology cost reductions and consumer preference for distinctive nighttime vehicle signatures.
The US EPA regulates volatile organic compound emissions from interior adhesives and coatings under automotive sector guidelines, while China's SAMR enforces GB standards for plasticizer content in vehicle cabin materials. Japan's METI promotes JIS-compliant recycled polymer utilization, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory fragmentation between these jurisdictions to determine where localized production or standardized global platforms deliver superior returns.
Market Dynamics
Aftermarket personalization demand among younger vehicle owners is compressing product development cycles and forcing suppliers to balance mass customization economics with regulatory compliance across fragmented national standards.
Growth Catalysts
- LED Cost Compression:Semiconductor manufacturing scale has reduced LED module pricing, enabling ambient lighting penetration into mid-market vehicle segments previously restricted to premium tiers.
- REACH Material Standards:European ECHA enforcement is accelerating compliant polymer formulation adoption, creating first-mover advantages for suppliers with pre-certified feedstock relationships.
- China Bundle Economics:Domestic automakers in Shanghai and Guangzhou provinces are integrating accessory packages into new vehicle financing, expanding addressable volume for seat cover and floor mat suppliers.
Market Restraints
- Petrochemical Feedstock Volatility:ABS and polyurethane precursor prices fluctuate with crude oil benchmarks, compressing margin predictability for injection-molding specialists without long-term supply contracts.
- Type-Approval Fragmentation:EU member states maintain divergent national certification pathways for exterior lighting modifications, forcing redundant testing expenditure for cross-border suppliers.
- Synthetic Leather Substitution:Plant-based alternatives from agricultural waste streams are capturing sustainability-conscious buyers in Nordic markets, threatening conventional PVC and PU leather volumes.
Strategic Opportunities
- India Aftermarket Expansion:Vehicle parc growth in Maharashtra and Tamil Nadu states is outpacing organized retail penetration, creating whitespace for branded accessory distribution networks.
- Recycled Polymer Mandates:Japan METI JIS-compliant recycled content requirements are generating certified material premiums for suppliers with verified post-consumer feedstock chains.
- Direct-to-Consumer Platforms:Configurator-enabled e-commerce is disintermediating traditional automotive retail, allowing specialized lighting and aerodynamic suppliers to capture full margin on made-to-order production.
Industry Challenges
- Polymer Compounding Expertise Scarcity:REACH-compliant formulation chemistry requires specialized technical talent that concentrates among incumbent European compounders, constraining new entrant capability building.
- IP Licensing Complexity:LED control software and vehicle communication protocols involve proprietary automotive OEM interfaces, creating negotiation friction for independent module suppliers.
- Legacy System Integration:Aftermarket lighting modules must interface with vehicle CAN bus architectures that vary by manufacturer and model year, multiplying SKU complexity and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Car Accessories Market |
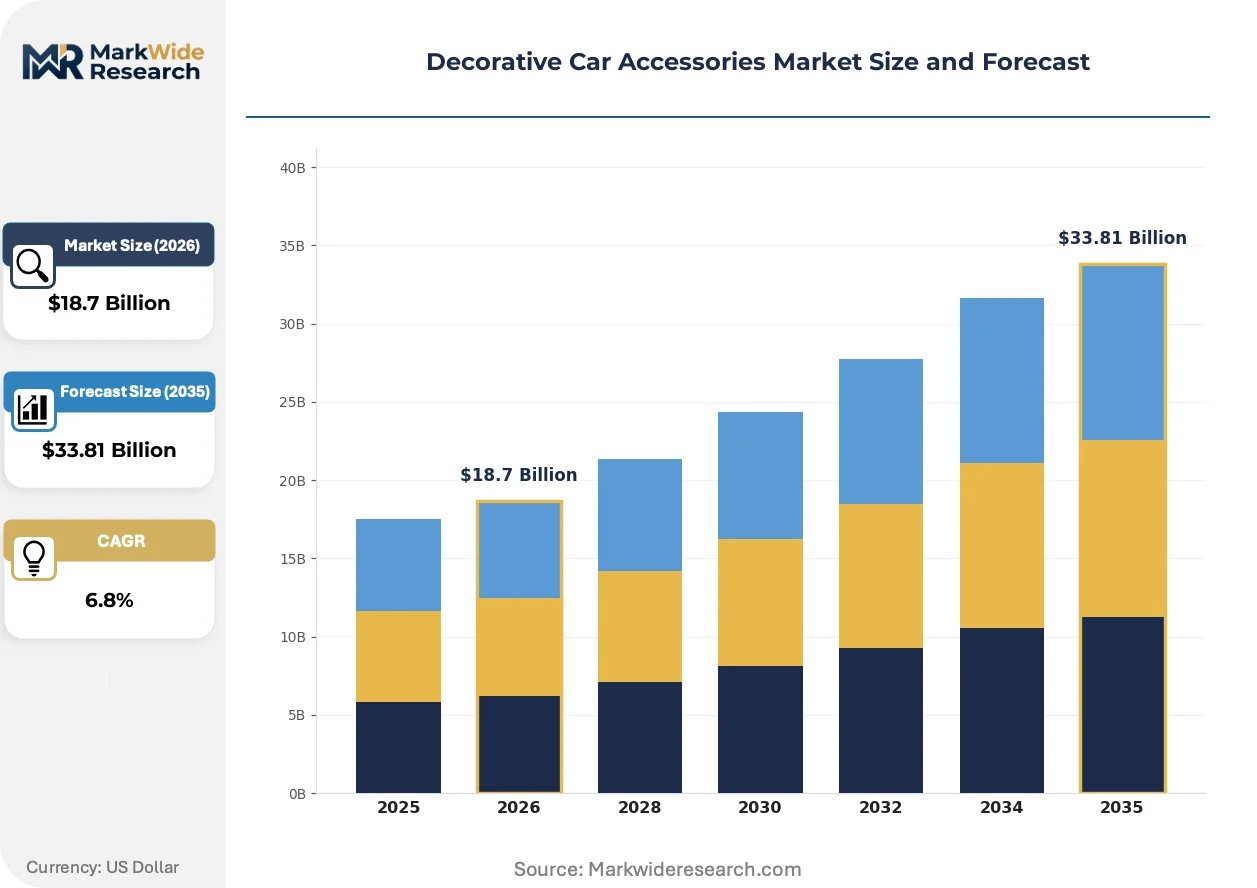
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Covers, Steering Wheel Covers, Floor Mats, Dashboard Covers Material: Leather, Fabric, Rubber, Plastic Application: Interior Styling, Exterior Enhancements, Protection, Lighting Customer Type: Car Enthusiasts, General Consumers, Fleet Owners, Corporate Clients |
| Companies Covered | Denso Corporation, Aisin Seiki Co. Ltd., Robert Bosch GmbH, Federal-Mogul Corp., Tenneco Inc., Continental AG, Magna International, 3D Carbon Automotive Corp., Delphi Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Car Accessories Market Emerging Trajectories
Digital manufacturing and connected vehicle architectures are converging to transform decorative accessories from static components into software-defined, personalized interfaces. This shift is compressing hardware commoditization timelines while opening recurring revenue models.
Smart ambient lighting systems with addressable RGB LEDs and smartphone-controlled color mapping are integrating vehicle interior personalization with driver biometric data. Younger owners in urban China and Germany are adopting these modules at twice the rate of conventional static lighting. The technology is integrating hardware sales with subscription-based pattern libraries, shifting supplier economics toward recurring revenue.
REACH substance restrictions on phthalates and heavy metal stabilizers in automotive plastics are forcing reformulation of legacy PVC and ABS compounds across European supply chains. Compounders with in-house regulatory laboratories are capturing specification authority from downstream molders. Seat cover manufacturers serving German OEMs are most affected, accelerating partnerships with certified polymer suppliers to maintain qualification status.
Configurator-driven purchasing is displacing traditional retail browsing for exterior aerodynamic and lighting accessories. Specialty suppliers in California and Guangdong are deploying augmented reality visualization tools that reduce return rates and enable premium pricing for made-to-order production. This behavioral shift is most visible among sport compact vehicle owners aged 25-34, who prioritize Instagram-compatible aesthetic differentiation over brand heritage.
Decorative Car Accessories Market Segmentation
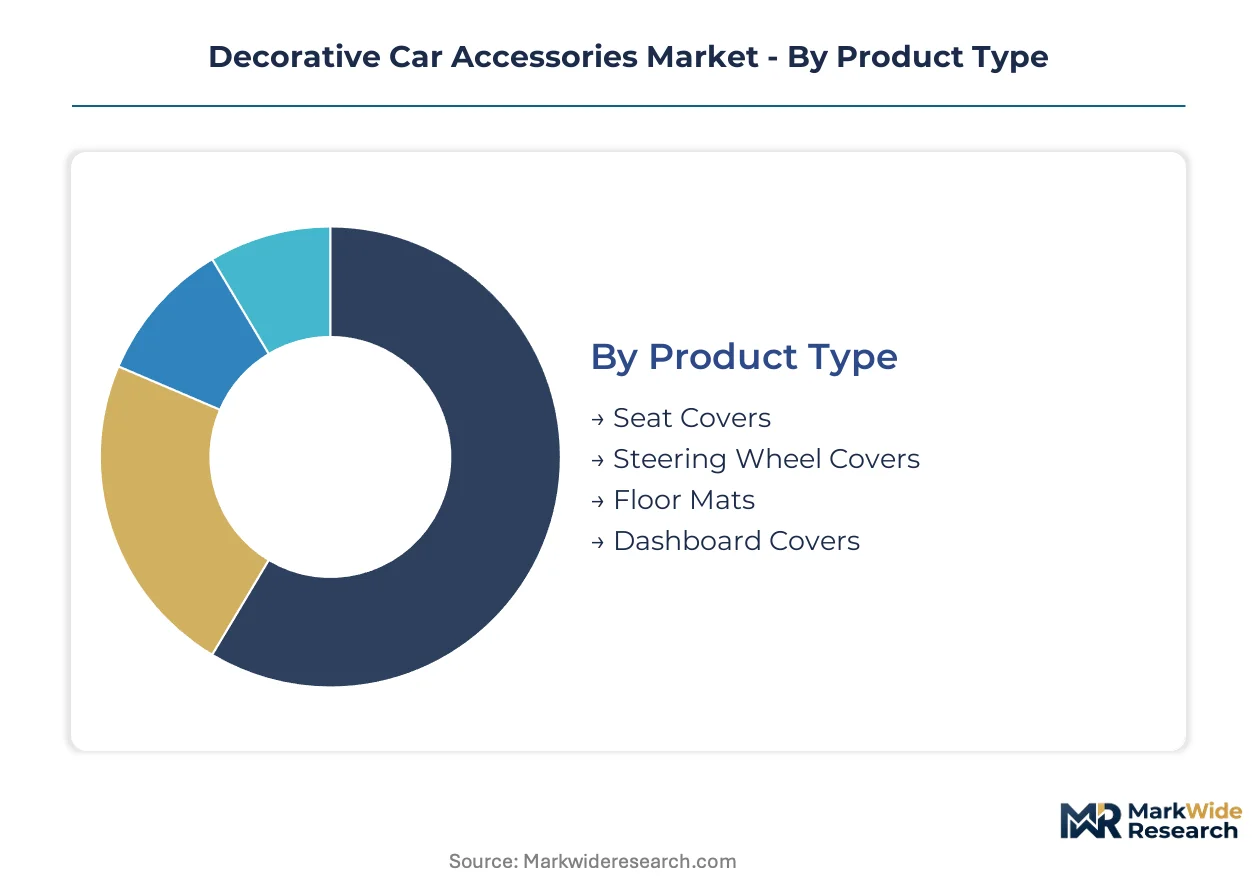
Segmentation in decorative car accessories reveals distinct procurement logics across buyer groups, with material specifications and regulatory exposure varying sharply between mass-market replacement cycles and enthusiast-driven customization projects. Understanding these fault lines enables suppliers to align formulation investments with margin profiles rather than treating the market as a uniform replacement-parts opportunity.
Product Type:
Replacement frequency and installation complexity separate buyers in this category, with universal-fit items commanding volume economics and vehicle-specific upgrades extracting customization premiums.
- Seat Covers:Thermoformed polyurethane and genuine leather constructions dominate OEM-affiliated channels, with Chinese domestic automakers bundling these into financing packages for new vehicle sales in Shanghai and Guangzhou provinces. REACH-compliant phthalate-free formulations are becoming non-negotiable for European qualification status.
- Floor Mats:Compression-molded rubber and carpeted textile variants represent the highest replacement velocity among all accessory categories, driven by wear-contamination cycles rather than aesthetic obsolescence. Injection-molding specialists without long-term petrochemical supply contracts face margin compression from ABS precursor volatility.
- Steering Wheel Covers:Wrap-on synthetic leather and stitched genuine leather options serve DIY installation preferences among cost-conscious vehicle owners.
- Dashboard Covers:Vacuum-formed ABS and suede-fabric overlays address UV degradation concerns in high-sunlight climates, with fitment precision determining return rates in e-commerce channels.
Floor mats lead volumes today; seat covers are gaining share fastest through OEM bundle economics.
Material:
Regulatory jurisdiction determines viable feedstock options, with European REACH enforcement and Japanese METI recycled-content mandates creating divergent compliance pathways for multinational suppliers.
- Leather:Genuine hides and synthetic PVC/PU alternatives occupy divergent price tiers, with plant-based substitutes from agricultural waste streams capturing sustainability-conscious buyers in Nordic markets. German OEM qualification programs now require ECHA-compliant heavy-metal-free stabilizer packages.
- Fabric:Woven polyester and nylon constructions serve price-sensitive replacement demand, with shorter fashion cycles than leather equivalents driving repeat purchase frequency among younger vehicle owners.
- Rubber:Natural and synthetic polymer blends dominate floor mat applications, with oil-resistant formulations commanding fleet procurement specifications.
- Plastic:Injection-molded ABS and thermoformed PVC span the broadest application range, from dashboard trim to exterior aerodynamic add-ons requiring IP67 ingress protection ratings.
Plastic spans the widest application footprint; leather commands the steepest premium expansion trajectory.
Application:
Functional purpose versus aesthetic intent separates procurement decision-makers, with protection-oriented buyers prioritizing durability certification and styling-oriented buyers emphasizing configurability and visual differentiation.
- Interior Styling:Seat covers, dashboard overlays, and ambient lighting modules alter cabin aesthetics without structural modification. Smart RGB LED systems with smartphone-controlled color mapping are expanding fastest among urban owners in China and Germany.
- Exterior Enhancements:Aerodynamic add-ons and lighting modifications require navigation of fragmented EU national type-approval pathways, forcing redundant testing expenditure for cross-border suppliers.
- Protection:Floor mats, mud flaps, and paint protection films address functional wear prevention rather than aesthetic transformation, with fleet procurement dominating volume.
- Lighting:LED-embedded strips and addressable ambient modules represent the highest-margin application segment, with semiconductor cost compression enabling mid-market penetration previously restricted to premium tiers.
Interior styling anchors current revenue pools; lighting is climbing the fastest on technology cost reduction and younger-owner personalization demand.
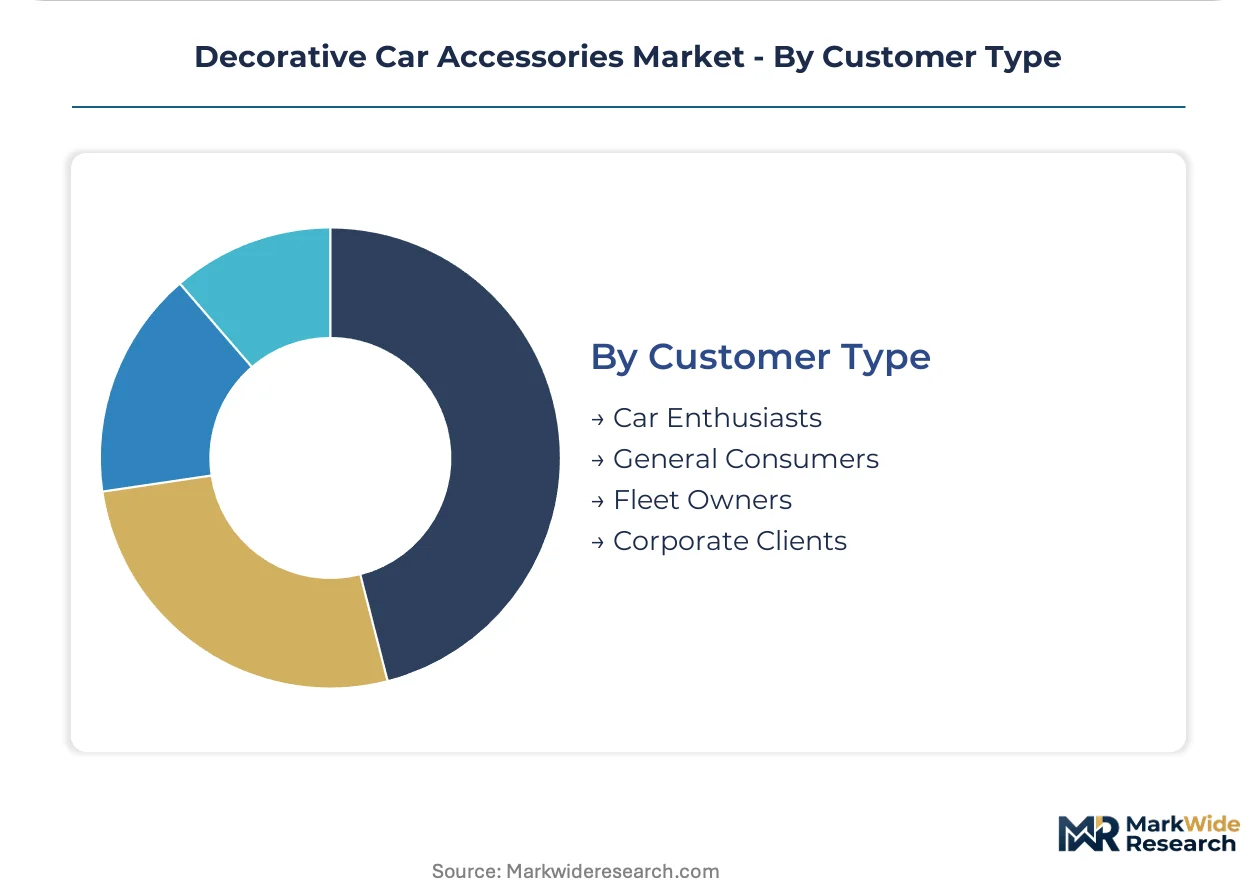
Customer Type:
Technical sophistication and purchase frequency diverge sharply across this category, with enthusiasts accepting installation complexity for customization returns while fleet buyers prioritize standardized specifications and warranty alignment.
- Car Enthusiasts:Configurator-enabled direct purchasing and augmented-reality visualization tools drive made-to-order production of aerodynamic and lighting accessories, with Instagram-compatible aesthetic differentiation prioritized over brand heritage.
- General Consumers:Mass-market retail and e-commerce platforms serve replacement-cycle demand for seat covers and floor mats, with return-rate sensitivity shaping supplier investment in fitment precision.
- Fleet Owners:Volume procurement contracts emphasize durability certification and standardized installation protocols across vehicle parc uniformity requirements.
- Corporate Clients:Branded vehicle programs and executive fleet specifications create demand for premium leather configurations with OEM warranty alignment.
General consumers dominate transaction volumes today; car enthusiasts are expanding most quickly through direct-to-platform purchasing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding expertise concentrates in Germany's industrial belt, while electronics manufacturing scale dominates East Asian production clusters. Regulatory divergence between REACH enforcement in Europe and GB standards in China is fragmenting supplier compliance strategies across these geographies.
China
Domestic automakers in Shanghai and Guangzhou provinces bundle accessory packages into new vehicle financing, expanding addressable volume for seat cover and floor mat suppliers. SAMR enforces GB standards for plasticizer content in vehicle cabin materials, tightening material specifications for interior components. The Pearl River Delta anchors manufacturing clusters for LED-embedded lighting modules serving both domestic and export markets.
Germany
ECHA enforcement of REACH substance restrictions on phthalates and heavy metal stabilizers is accelerating compliant polymer formulation adoption across automotive supply chains. Robert Bosch GmbH leverages its automotive electronics heritage to integrate ambient lighting modules that meet evolving material standards. The Baden-Württemberg region hosts specialized compounders with in-house regulatory laboratories capturing specification authority from downstream molders.
United States
EPA regulation of volatile organic compound emissions from interior adhesives and coatings shapes aftermarket product development for seat covers and dashboard overlays. Configurator-enabled e-commerce platforms in California are deploying augmented reality visualization tools for exterior aerodynamic and lighting accessories. The Southeast manufacturing corridor concentrates injection-molding capacity for compression-molded rubber floor mats serving fleet procurement channels.
Japan
METI promotes JIS-compliant recycled polymer utilization, creating certified material premiums for suppliers with verified post-consumer feedstock chains. Vehicle parc maturity sustains replacement-cycle demand for interior styling components among owner demographics prioritizing durability certification. The Nagoya industrial zone anchors supply relationships between tier-1 automotive suppliers and specialty compounders.
India
Vehicle parc growth in Maharashtra and Tamil Nadu states outpaces organized retail penetration, creating whitespace for branded accessory distribution networks. Central pollution control directives on interior material emissions are beginning to shape procurement specifications for fleet operators. The Delhi-Mumbai industrial corridor attracts regional headquarters for multinational suppliers targeting aftermarket expansion.
Decorative Car Accessories Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base fragments between electronics-integrated module producers, polymer compounders with regulatory certification capabilities, and configurator-enabled direct-to-consumer platforms. Three archetypes dominate: automotive tier-1 diversifiers extending into ambient lighting, specialized aerodynamic fabricators navigating type-approval complexity, and compounders controlling REACH-compliant feedstock supply. Consolidation pressure concentrates among injection-molding specialists seeking backward integration into polymer formulation, while technology licensing agreements multiply around LED control software and vehicle communication protocols.
Within the tier-1 diversifier archetype, Robert Bosch GmbH and Continental AG exemplify electronics-integrated positioning anchored in European automotive supply chain relationships. 3D Carbon Automotive Corp. occupies a specialist fabrication position focused on exterior aerodynamic applications. These three entities represent contrasting strategic postures: diversified technology conglomerates versus focused aftermarket specialists versus integrated material suppliers.
| Leading Market Players |
|---|
| Denso Corporation |
| Aisin Seiki Co. Ltd. |
| Robert Bosch GmbH |
| Federal-Mogul Corp. |
| Tenneco Inc. |
| Continental AG |
| Magna International |
| 3D Carbon Automotive Corp. |
| Delphi Automotive |
| Others |
Supply Flow & Price Mechanics
Polymer compounding chemists in Germany's Baden-Württemberg region command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy levels. Labor-cost differentials between European REACH-certified formulators and Asian injection-molding specialists compress margins at mid-tier positions while sustaining premium capture for compliant feedstock suppliers.
Pricing Analysis
Bundled accessory packages through OEM financing channels in China extract volume commitments that compress per-unit pricing for seat cover and floor mat suppliers, while unbundled aftermarket sales through configurator platforms enable premium capture for lighting and aerodynamic specialists. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with REACH-compliant formulations commanding material premiums over conventional PVC and ABS compounds. Price erosion runs through mid-market injection-molded plastics as petrochemical feedstock volatility transfers cost uncertainty downstream. Fleet procurement contracts demonstrate highest price sensitivity due to standardized specifications and warranty alignment requirements, while car enthusiasts in urban China and Germany exhibit lowest sensitivity for Instagram-compatible aesthetic differentiation.
Supply Chain Analysis
Single-source vulnerability sits with German compounders controlling REACH-certified phthalate-free formulation expertise, creating bottleneck risk for downstream molders seeking European qualification status. Manufacturing concentrates in China, Germany, and the United States, with the Pearl River Delta anchoring LED module assembly and the Southeast US corridor housing rubber floor mat compression molding. Raw material dependencies span ABS and polyurethane precursors tethered to crude oil benchmarks, semiconductor components for addressable RGB systems, and natural rubber feedstocks subject to climate volatility. Tariff exposure on cross-border automotive components multiplies SKU complexity for suppliers navigating fragmented EU national type-approval pathways. Distribution runs through tier-1 automotive supplier networks for OEM-affiliated channels, with direct-to-consumer platforms disintermediating traditional retail for enthusiast-driven customization segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Decorative Car Accessories Market functions as a stable compounder anchored by replacement-cycle demand for interior protection components and technology-driven upgrade cycles for connected lighting systems. Vehicle parc expansion in emerging economies and regulatory compliance mandates in mature markets generate predictable revenue streams across economic cycles.
For Market Incumbents: Lock in polymer compounding partnerships with ECHA-pre-certified feedstock suppliers to defend qualification status against REACH enforcement acceleration. Secure capacity reservations for semiconductor components serving addressable RGB LED architectures before allocation constraints tighten. Channel control through configurator-enabled direct platforms captures full margin from enthusiast segments while insulating against retail disintermediation.
For New Entrants and Emerging Players: Enter via aftermarket distribution whitespace in India's Maharashtra and Tamil Nadu states, where vehicle parc growth outpaces organized retail penetration. Target the lighting application segment, where semiconductor cost compression enables mid-market penetration with lower capital intensity than interior component manufacturing. Pursue augmented-reality visualization partnerships with California and Guangdong specialty suppliers to reduce return rates and establish platform relationships.
For Investors and Strategic Acquirers: Tier-1 automotive diversifiers are the most active acquirer in this space, seeking electronics-integrated module capabilities and REACH-compliant formulation expertise. Acquisition targets with verified post-consumer feedstock chains and JIS-compliant recycled polymer utilization command certified material premiums in Japan's replacement-cycle market. The signal to watch is LED control software licensing friction with proprietary OEM vehicle communication protocols, which indicates consolidation pressure among independent module suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH compliance investments by Robert Bosch GmbH and Continental AG secure feedstock specification authority. |
| Direct-to-Consumer Platform Launch | Configurator-enabled e-commerce by California and Guangdong specialists captures full margin on made-to-order production. |
| Recycled Polymer Certification Program | JIS-compliant feedstock chains generate material premiums for suppliers serving Japan's METI mandates. |
| Smart Lighting Module Development | Addressable RGB LED systems with smartphone control expand fastest among urban owners in China and Germany. |
| Regional Distribution Network Expansion | Branded accessory penetration in India's Maharashtra and Tamil Nadu states addresses vehicle parc growth outrunning retail infrastructure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads with secondary validation. Secondary sources included vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from diversified automotive suppliers. Bottom-up segment sizing and top-down macroeconomic triangulation were cross-checked for consistency.
Segment-weighting across product type, material composition, application purpose, and customer archetype dimensions drove analytical framework construction over the projection horizon. CAGRs were derived from installed base modeling and replacement-cycle velocity assumptions, with LED technology cost curves and REACH compliance cost pass-through rates incorporated as industry-specific forecast inputs.
Inputs from Tier 1 procurement officers and aftermarket distributors were available through the study window; gaps in real-time semiconductor allocation data and proprietary OEM vehicle communication protocol specifications introduce uncertainty bands around lighting segment projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Heated Steering Wheel Market