
 Europe Automotive Wrap Films Market | 2026-2036
Europe Automotive Wrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Wrap Films Market Intelligence
The EU Green Deal is expanding pressure on automotive suppliers to eliminate PVC-intensive coatings and adopt lower-VOC alternatives. Avery Dennison Corporation leverages its polymer science portfolio to develop bio-based pressure-sensitive adhesives for fleet applications. Hexis S.A.S. anchors its position through cast film production in France, supplying premium color-change wraps to vehicle customizers across the continent. 3M Company competes through controlled distribution networks that limit gray-market diversion of its high-performance 1080 series.
Automotive wrap films comprise multi-layer polymeric sheets—typically calendered or cast vinyl with pigmented or metallized face stocks, pressure-sensitive adhesive layers, and release liners—engineered for conformability to complex vehicle geometries and removability without substrate damage. Cast vinyl dominates margin pools due to thinner gauges, superior conformability around compound curves, and longer outdoor durability guarantees. Printable wraps sustain faster growth as commercial fleet operators demand variable, campaign-specific graphics with shorter refresh cycles than traditional paint permits.
REACH compliance through ECHA restricts phthalate plasticizers and certain stabilizers in vinyl formulations, compelling reformulation investments among compounders. The EU F-Gas Regulation indirectly shapes supply chains by limiting fluorinated greenhouse gases used in manufacturing certain specialty films. France's ANSM and Germany's KBA enforce type-approval standards that affect wrap film claims regarding light transmission and reflectivity. Stakeholders must monitor evolving Extended Producer Responsibility frameworks that will soon assign end-of-life collection costs directly to film manufacturers rather than installers.
Market Dynamics
REACH compliance through ECHA is forcing vinyl compounders to eliminate phthalate plasticizers and heavy-metal stabilizers, triggering a wave of reformulation investments that is redrawing competitive positioning across the European supply base. This regulatory compression is accelerating substitution toward bio-based pressure-sensitive adhesives and recyclable polymeric substrates.
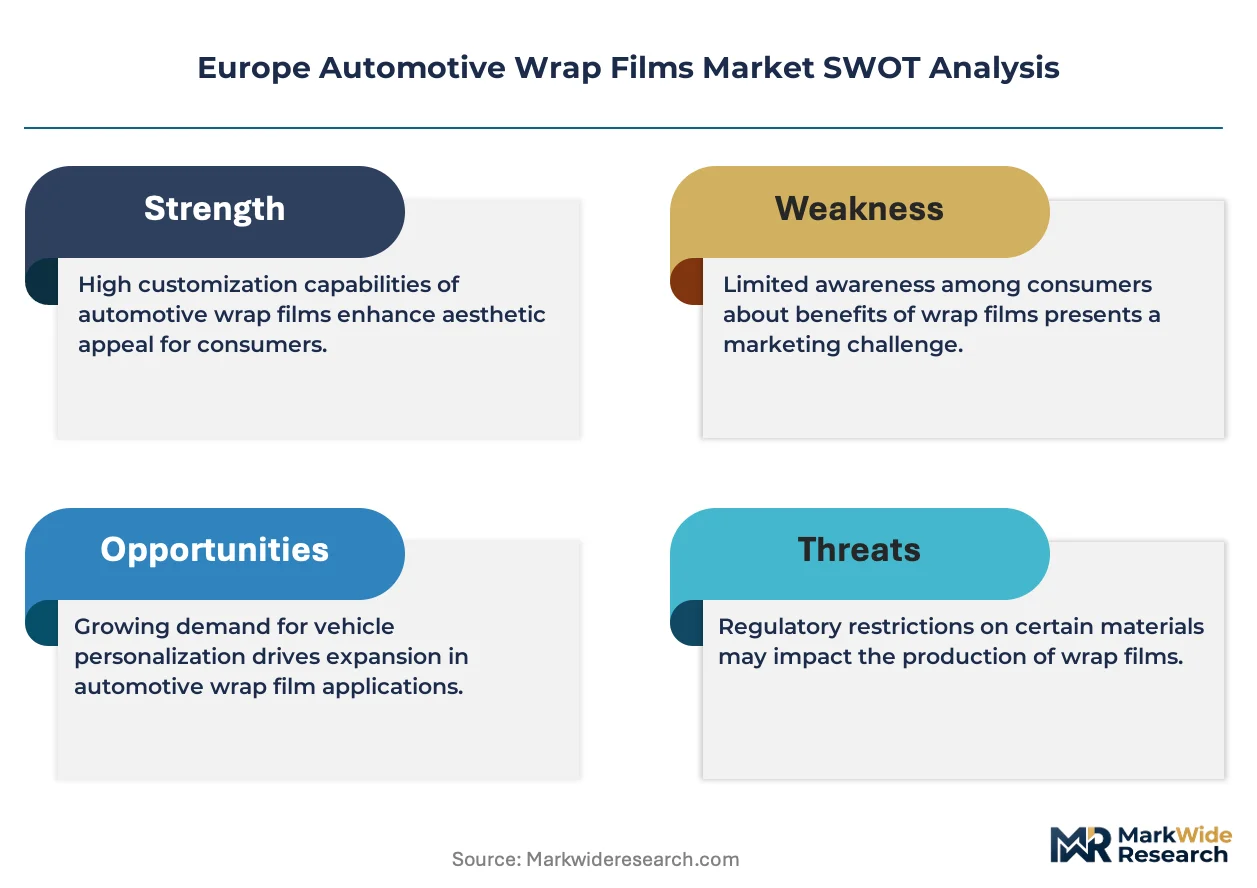
Growth Catalysts
- Fleet Branding Mandates:Commercial vehicle operators in Germany and France are standardizing wrap films for brand consistency across distributed logistics networks, creating durable recurring demand.
- EU Green Deal Circular Economy Requirements:Procurement specifications now prioritize recyclable substrates, redirecting volume toward cast vinyl with verified end-of-life pathways.
- Climate Durability Premium:Southern European markets command extended outdoor performance guarantees, sustaining margin pools for advanced UV-stabilized formulations.
Market Restraints
- Petrochemical Feedstock Volatility:PVC resin and plasticizer costs fluctuate with crude oil indices, compressing compounder margins during energy price spikes.
- Specialty Adhesive Supply Concentration:Pressure-sensitive adhesive production clusters in Germany and Belgium, creating geographic vulnerability for southern European converters.
- Fluorinated Gas Manufacturing Limits:The EU F-Gas Regulation restricts certain specialty film production processes, constraining supply of high-performance metallized face stocks.
Strategic Opportunities
- Underpenetrated Eastern European Fleets:Polish and Romanian logistics operators remain below western adoption rates for commercial vehicle wraps, offering expansion headroom.
- Short-Run Digital Print Integration:Campaign-specific graphics with sub-12-month refresh cycles are displacing permanent paint for seasonal promotions.
- Extended Producer Responsibility Pre-Positioning:Early compliance with France's evolving EPR frameworks will secure preferred supplier status before mandatory collection cost assignments.
Industry Challenges
- Specialized Installation Labor Scarcity:Complex compound-curve application requires certified technicians; training pipeline gaps constrain service capacity in high-growth markets.
- Reformulation Certification Timelines:ECHA substance evaluation delays new adhesive approvals, extending product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Wrap Films Market |
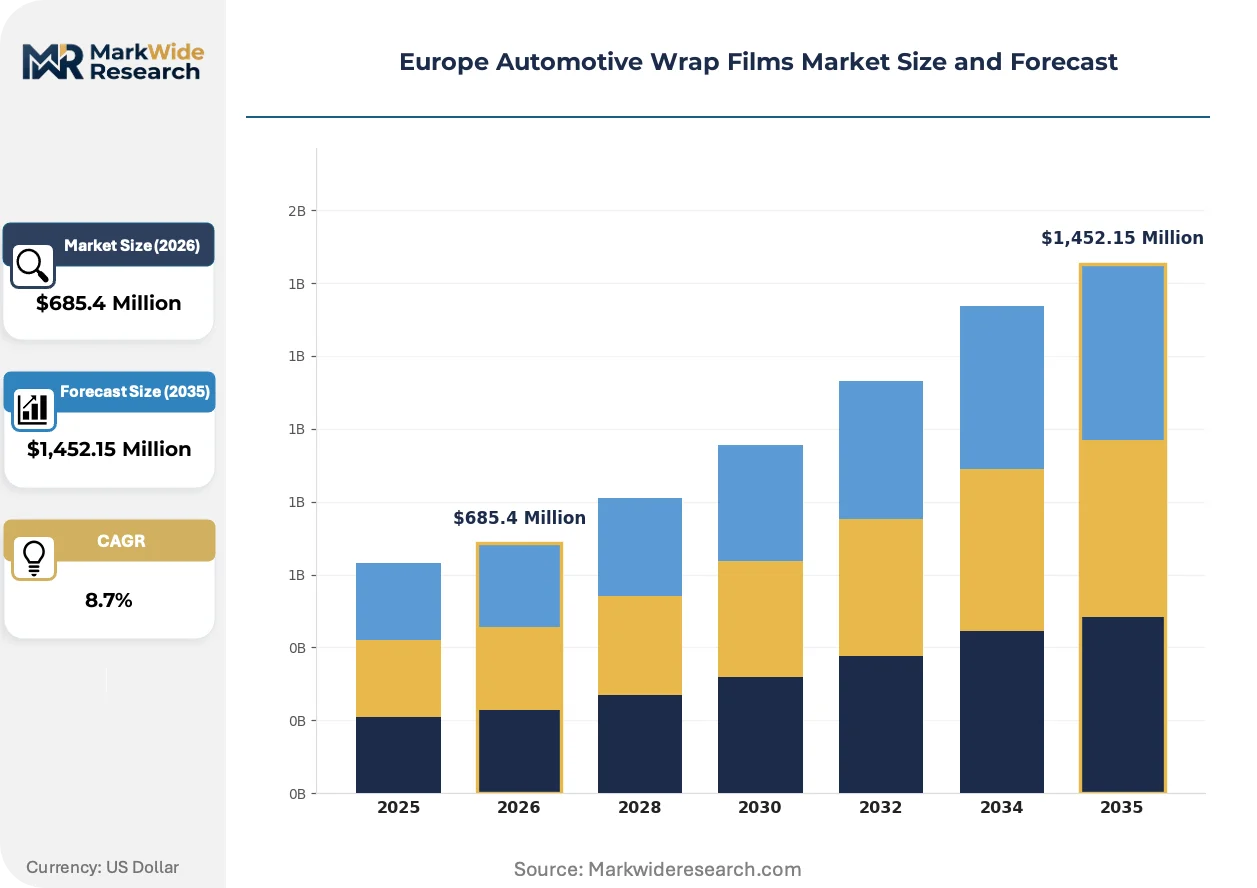
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Polymeric, Cast, Printable Application: Car Racing, Commercial Vehicles, Fleet Vehicles, Personal Vehicles End User: Private Owners, Businesses, Vehicle Customizers, Dealerships Installation Type: DIY, Professional, Mobile Service, In-House |
| Companies Covered | Fedrigoni S.P.A., Arlon Graphics LLC, Avery Dennison Corporation, Henkel AG & Co. KGaA, Kay Premium Marking Films (KPMF), 3M Company, Hexis S.A.S., Spandex, ORAFOL Europe GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Wrap Films Market Strategic Shifts & Innovations
Material science advances and regulatory compression are converging to transform how automotive wrap films are formulated, specified, and deployed across European commercial and consumer segments.
Cast vinyl technology is expanding into premium color-change applications for vehicle customizers seeking thinner gauges with superior conformability around complex geometries. Specialist installers across Spain and Italy are adopting these formulations to meet climate durability requirements that calendered alternatives cannot satisfy. The technology is expanding into margin pools previously captured by permanent paint refinishing.
The EU F-Gas Regulation is limiting fluorinated greenhouse gases in manufacturing certain specialty films, compelling compounders to redesign metallized face stock production. German film producers are investing in alternative deposition technologies to maintain optical performance. Southern European markets with intense UV exposure face the tightest supply constraints as reformulation cycles extend.
Fleet procurement patterns are compressing refresh cycles from multi-year paint commitments to campaign-specific wrap contracts. Major logistics operators in the United Kingdom now specify 6-12 month graphic rotations for seasonal marketing. This behavioral shift is concentrating volume among converters with digital print infrastructure and rapid-turn installation networks.
Europe Automotive Wrap Films Market Segmentation
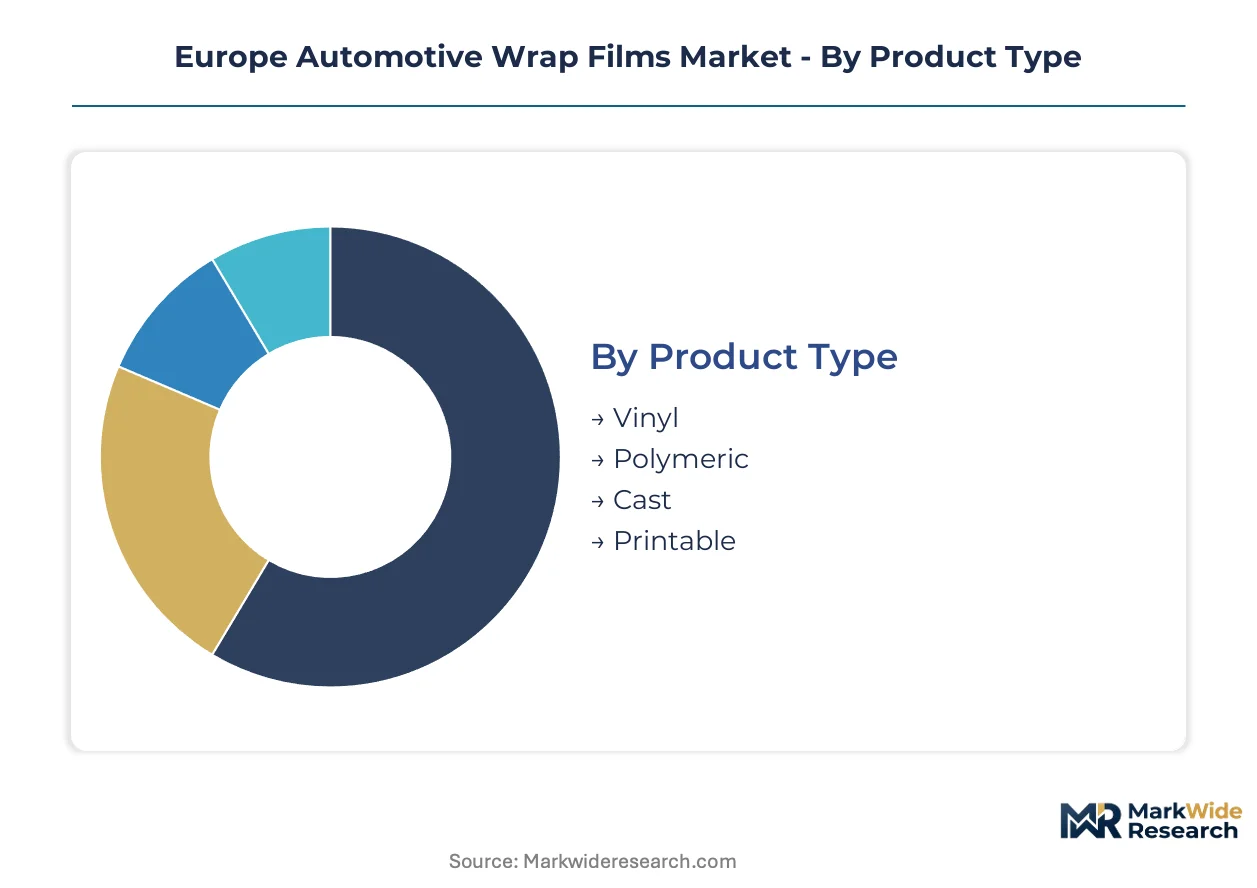
Segmentation in automotive wrap films reveals how capital deployment, technical capability, and regulatory exposure fragment across distinct demand pools. Manufacturers must align formulation investments with specific durability requirements and installation channel economics.
Product Type:
Cast vinyl commands the steepest capital requirements due to solvent casting lines and climate-controlled curing infrastructure. Calendered alternatives run on lower-cost extrusion equipment but sacrifice margin potential.
- Vinyl:Polyvinyl chloride formulations with plasticizer systems dominate volume throughput across European converters. German compounders supply calendered grades to price-sensitive fleet operators in Poland and Romania where UV exposure remains moderate.
- Cast:Solvent-cast production yields thinner gauges with superior conformability around compound curves and extended outdoor durability. French producers anchor supply for Southern European customizers facing intense Mediterranean UV loads.
- Polymeric:Non-PVC alternatives including TPU and polyolefin substrates address REACH-phthalate restrictions. Belgian compounders pilot bio-based pressure-sensitive adhesive pairings for EU Green Deal compliance.
- Printable:White-pigmented face stocks optimized for solvent, latex, and UV inkjet deposition enable variable fleet graphics. United Kingdom logistics networks drive demand for 6-12 month campaign refresh cycles.
Cast formulations absorb the bulk of installed capacity; printable grades are expanding most quickly.
Application:
Commercial vehicle specifications diverge sharply from consumer segments on durability guarantees and regulatory documentation.
- Fleet Vehicles:Distributed logistics operators standardize wrap specifications across national networks. German parcel carriers mandate 5-year color retention guarantees, concentrating volume among ECHA-registered suppliers with validated UV stabilizer packages.
- Commercial Vehicles:Light commercial vans and trucks deploy partial wraps for brand consistency without full respray costs. French last-mile delivery networks in Paris and Lyon drive seasonal graphic rotations.
- Car Racing:Motorsport applications prioritize weight reduction and rapid graphic changes over multi-year durability. Italian racing teams around Monza and Imola source ultra-thin cast grades for aerodynamic neutrality.
- Personal Vehicles:Consumer color-change wraps remain discretionary, sensitive to economic cycles. Spanish vehicle owners in Madrid and Barcelona favor premium metallic finishes with 3-5 year removability assurances.
Fleet vehicles command the dominant share of procurement volume; commercial vehicle applications are climbing the fastest.
End User:
Business procurement patterns sustain recurring revenue streams that individual consumers cannot match.
- Businesses:Corporate fleet managers negotiate multi-year supply agreements with installation service bundling. United Kingdom logistics operators specify campaign-specific graphics with dedicated converter relationships.
- Vehicle Customizers:Specialist installers serving enthusiast markets command premium pricing for complex compound-curve application. Italian and Spanish customizers in Milan and Barcelona drive demand for color-shifting and textured finishes.
- Private Owners:Individual consumers purchase through retail channels or direct-to-installer transactions. German private owners prioritize OEM-grade color matching and documented removability.
- Dealerships:Franchise and independent dealers apply protective and cosmetic wraps to inventory vehicles. French dealer networks around Lyon leverage mobile installation services for on-lot application.
Businesses absorb the dominant procurement volume; vehicle customizers are gaining share fastest.
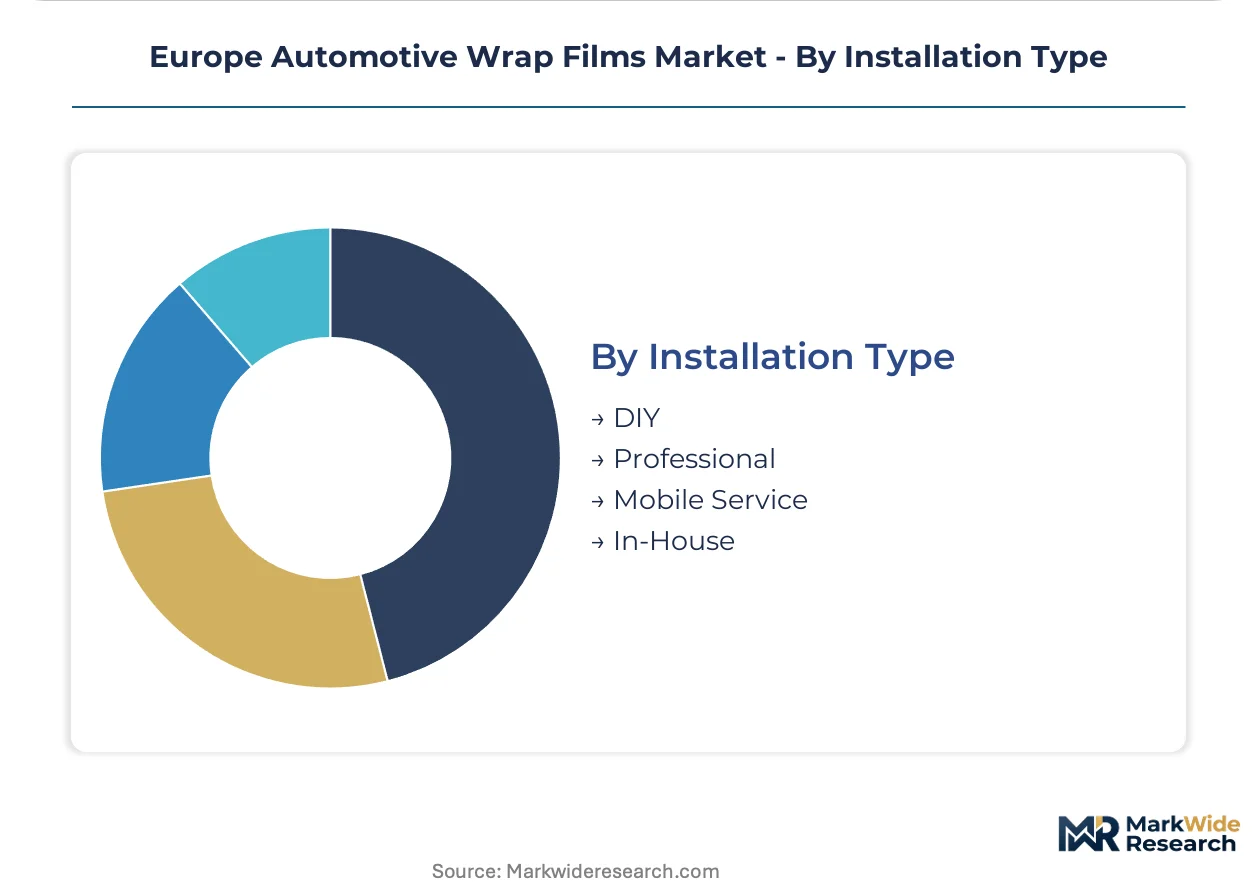
Installation Type:
Service model selection determines geographic reach, labor cost structure, and warranty liability allocation.
- Professional:Fixed-location installation centers with climate-controlled bays deliver highest-quality outcomes for premium cast applications. German certified technicians command 18-24 month training pipelines, constraining service capacity expansion.
- Mobile Service:On-site application units reduce vehicle downtime for fleet operators with distributed assets. United Kingdom mobile networks serve logistics hubs in Birmingham and Manchester without depot return requirements.
- In-House:Large fleet operators maintain captive installation capability for volume efficiency. French postal services deploy internal teams for standardized livery application across regional depots.
- DIY:Consumer self-application channels move lower-grade calendered products through retail and e-commerce. Polish and Romanian markets show higher DIY penetration due to labor cost differentials.
Professional installation commands the bulk of value capture; mobile service models are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European automotive wrap film demand through its dense logistics infrastructure and fleet operator concentration. German parcel carriers and Dutch freight networks generate sustained procurement volume for premium cast formulations. Southern European customizers in Milan and Barcelona drive color-change applications with stringent climate durability requirements.
Germany
Fleet operators across the Rhine-Ruhr and Bavaria standardize wrap specifications for brand consistency in parcel and freight logistics. The KBA enforces type-approval standards affecting light transmission and reflectivity claims on commercial vehicles. Cologne and Düsseldorf host certified installation networks serving distributed logistics depots with climate-controlled application bays.
France
Last-mile delivery networks in Paris and Lyon deploy seasonal graphic rotations for campaign-specific marketing. ANSM regulates wrap film safety claims alongside evolving Extended Producer Responsibility frameworks assigning end-of-life collection costs. The Lyon corridor concentrates converter capacity supplying premium cast grades to Southern European markets.
United Kingdom
Logistics operators in Birmingham and Manchester specify 6-12 month refresh cycles through digital print infrastructure. Post-Brexit regulatory divergence from REACH creates compliance complexity for cross-border film shipments. Mobile installation services serve fleet hubs without requiring vehicle returns to fixed depots.
Italy
Vehicle customizers in Milan and around Monza source ultra-thin cast grades for motorsport applications prioritizing weight reduction. Intense Mediterranean UV exposure commands extended outdoor performance guarantees exceeding Northern European specifications. The Po Valley industrial corridor supports specialist installers serving enthusiast markets with complex compound-curve applications.
Spain
Private owners in Madrid and Barcelona favor premium metallic finishes with documented 3-5 year removability assurances. Climate durability requirements intensify margin pressure for UV-stabilized formulations resistant to thermal cycling. The Barcelona-Tarragona corridor anchors converter capacity serving Iberian Peninsula demand.
Europe Automotive Wrap Films Market Key Industry Players
The competitive structure tilts toward diversified materials conglomerates with polymer science capabilities and specialized film converters with regional installation networks. Consolidation pressures concentrate among ECHA-registered suppliers capable of validated UV stabilizer packages for fleet procurement. Three archetypes dominate: integrated adhesive-compounders controlling upstream formulation, pure-play cast film specialists with climate-controlled curing infrastructure, and distribution-anchored converters bundling installation services. Capacity expansion and strategic partnerships represent the dominant competitive moves as compounders secure bio-based adhesive supply agreements.
Among diversified materials conglomerates, Avery Dennison Corporation and 3M Company exemplify archetypes with polymer science portfolios spanning pressure-sensitive adhesive development. Hexis S.A.S. occupies a position within the specialized cast film tier, representing French production capabilities serving premium color-change applications. These three entities anchor distinct strategic vectors: adhesive innovation, controlled distribution networks, and regional manufacturing proximity to Southern European climate durability demand.
| Leading Market Players |
|---|
| Fedrigoni S.P.A. |
| Arlon Graphics LLC |
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| Kay Premium Marking Films (KPMF) |
| 3M Company |
| Hexis S.A.S. |
| Spandex |
| ORAFOL Europe GmbH |
| Others |
Cost & Logistics Intelligence
Fleet procurement mandates for REACH-compliant cast vinyl across Germany and France are compelling compounders to absorb reformulation costs while defending margin pools through performance-based guarantees. This demand-side specification tightening forces supply responses that stratify pricing across certification tiers and geographic delivery zones.
Pricing Analysis
Performance guarantees anchor value-based pricing in automotive wrap films, with German parcel carriers paying premiums for 5-year color retention assurances backed by ECHA-registered UV stabilizer packages. Pricing stratifies across premium cast grades, standard calendered formulations, and economy DIY products based on certification tier and installation service bundling. Cost compression in calendered segments intensifies as Polish and Romanian converters source lower-grade PVC from non-registered suppliers. Fleet operators show lowest price sensitivity due to total-cost-of-ownership calculations, while private owners in Southern Europe exhibit highest elasticity to metallic finish premiums.
Supply Chain Analysis
Certified technician scarcity across German and Belgian installation networks constrains service capacity expansion and extends lead times for complex compound-curve applications. Manufacturing concentrates in France for solvent-cast production, Germany for adhesive compounding, and Belgium for polymeric substrate piloting. Raw material flows draw from petrochemical feedstocks in the Netherlands, specialty plasticizers subject to REACH restrictions, and metallized face stocks facing EU F-Gas Regulation constraints. Single-source vulnerability runs through German pressure-sensitive adhesive production clusters. Distribution runs through converter networks bundling installation services rather than direct film sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cast vinyl technology is displacing calendered formulations and permanent paint refinishing as fleet operators compress refresh cycles and climate durability requirements intensify across Southern Europe.
For Market Incumbents: Acquire mobile installation service networks to secure captive distribution channels against pure-play converters. Bio-based pressure-sensitive adhesive capabilities represent essential defensive positioning as ECHA substance evaluations extend reformulation timelines. Backward integration into solvent casting infrastructure in France protects margin pools from Southern European climate-grade supply constraints. For New Entrants and Emerging Players: Capture Polish and Romanian fleet operators below Western adoption saturation through price-competitive calendered offerings with simplified application protocols. Eastern European logistics networks present the most penetrable white space. Partner with regional distributors possessing existing commercial vehicle service relationships to bypass certified technician bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with ECHA-registered compounders possessing validated UV stabilizer packages given Extended Producer Responsibility cost assignments approaching in France. Long-term viability favors suppliers with demonstrated end-of-life collection pathway compliance. Monitor ANSM regulatory bulletins as inflection signals for mandatory collection cost timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solvent Casting | French production proximity secures Southern European climate-grade premium positioning. |
| Bio-Based Adhesive Partnership | Belgian compounder alliances accelerate EU Green Deal compliance ahead of ECHA deadlines. |
| Mobile Installation Network Acquisition | United Kingdom logistics hub coverage reduces fleet operator vehicle downtime requirements. |
| EPR Pre-Compliance Investment | France's evolving collection cost frameworks reward early end-of-life pathway certification. |
| Digital Print Infrastructure Expansion | United Kingdom campaign-specific refresh cycles concentrate volume among rapid-turn converters. |
Research Approach
Independent corroboration across primary interviews with fleet procurement managers, certified installation technicians, and ECHA regulatory consultants, plus secondary validation through REACH substance databases, EU F-Gas Regulation filings, and customs trade records, underwrites the qualitative findings. Bottom-up demand modeling from converter shipment data triangulates against top-down market sizing from automotive production and fleet registration statistics.
Historical reference periods spanning pre-pandemic baseline through post-REACH implementation establish the forecast anchor across the analysis window. Segmentation dimensions include product type hierarchy, fleet versus consumer application splits, professional versus mobile installation channels, and country-specific regulatory compliance tiers. CAGRs derive from elasticity-adjusted demand projections incorporating petrochemical feedstock volatility and certified technician supply constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation delays, EU F-Gas Regulation enforcement intensity, and Extended Producer Responsibility implementation timelines. Material deviation in these regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Global Automotive Carpeting Market