
 Automotive Navigation & Infotainment Systems Market | 2026-2036
Automotive Navigation & Infotainment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Navigation & Infotainment Systems Market Analytics
Software-defined vehicle architecture is fragmenting the traditional hardware-centric infotainment stack into layered, updatable platforms. Continental AG leverages its integrated cockpit domain controller portfolio to anchor high-volume European OEM programs. Harman International differentiates through premium audio-visual integration and over-the-air software services that sustain recurring revenue streams. Robert Bosch GmbH competes on manufacturing scale across sensor fusion and display module production.
Automotive navigation and infotainment systems combine GPS positioning, cloud-connected mapping engines, voice recognition interfaces, and vehicle network integration to deliver real-time guidance, media streaming, and telematics within the vehicle cabin. These systems process location data through embedded or tethered processors, rendering outputs on central stack displays, head-up displays, or instrument clusters to reduce driver cognitive load while maintaining situational awareness. Embedded navigation commands the highest margin pools where map data licensing and hardware bundling create sticky OEM relationships, while smartphone integration grows fastest as consumers prioritize familiar app ecosystems and lower replacement costs. Head-up display penetration accelerates in premium segments where augmented reality overlays merge navigation guidance with forward camera feeds.
The U.S. NHTSA distraction guidelines and Europe's ECE R79 framework constrain touchscreen interaction complexity, forcing voice recognition and haptic feedback investments that inflate R&D budgets but create compliance moats. Japan's METI promotes connected vehicle standards through its SIP-adus program, accelerating V2X integration requirements that reshape infotainment system boundary definitions. Stakeholders must monitor regulatory divergence between touchscreen interaction limits and autonomous vehicle HMI exemptions that could abruptly resegment hardware and software spending priorities.
Market Dynamics
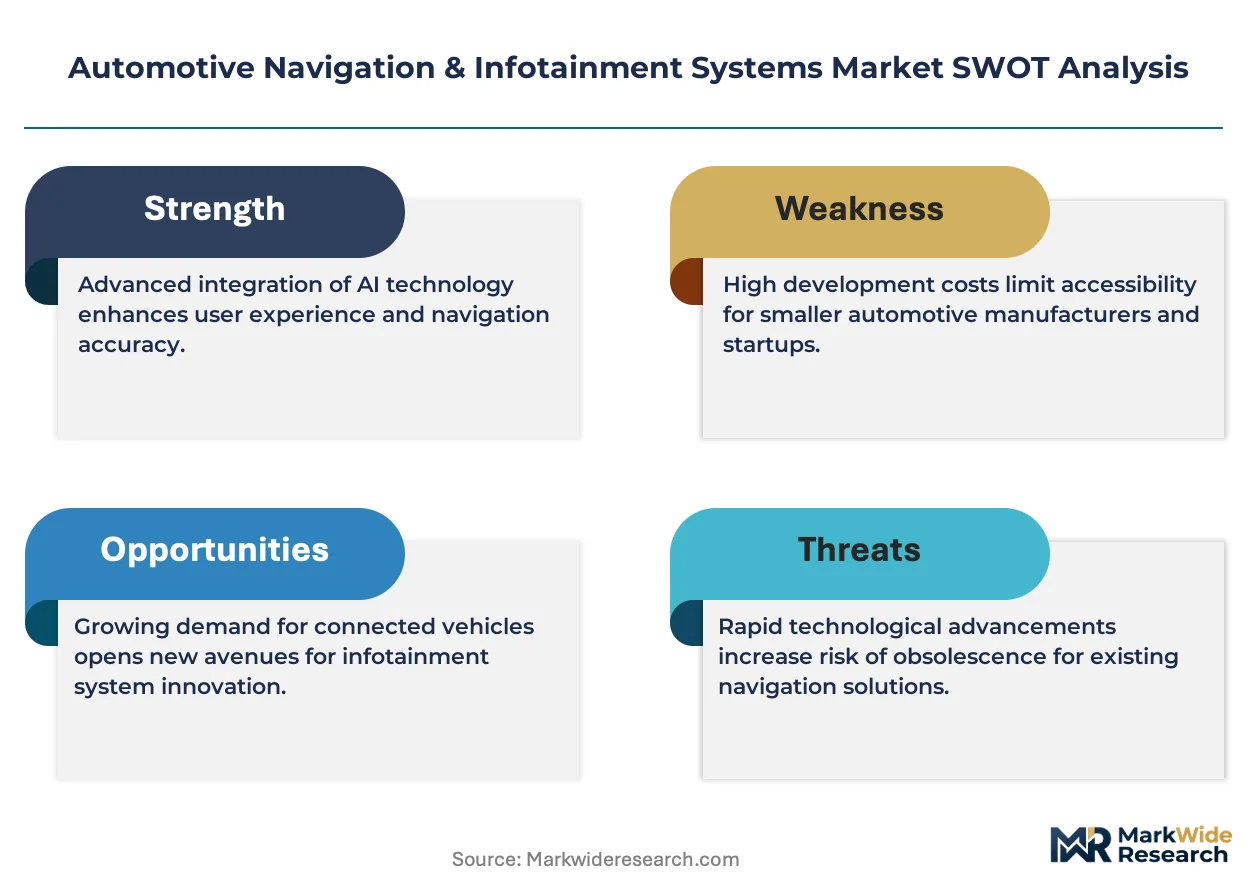
Software-defined vehicle architectures are decoupling infotainment hardware from software stacks, enabling over-the-air updates that extend system lifecycles and shift revenue models toward recurring services.
Growth Catalysts
- ECE R79 Driver Distraction Framework:Europe's regulation mandates voice-first interfaces and haptic feedback systems, forcing R&D investment that creates compliance barriers for new entrants.
- Head-Up Display Augmentation:AR navigation overlays merging camera feeds with guidance graphics command premium pricing in luxury vehicle segments.
- German Automotive Manufacturing Corridor:Concentrated OEM headquarters and tier-1 supplier engineering centers accelerate embedded navigation adoption cycles.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate automotive-grade SoC fabrication, exposing programs to single-source risks.
- Map Data Licensing Costs:Proprietary geographic information systems impose recurring royalty structures that compress hardware margins.
- Smartphone Mirroring Substitution:Apple CarPlay and Android Auto provide zero-cost navigation alternatives that disincentivize embedded system upgrades.
Strategic Opportunities
- India's PLI Scheme for Automotive Electronics:Production-linked incentives attract component localization for export-oriented manufacturing.
- V2X Integration Mandates:Japan's METI SIP-adus program redefines infotainment boundaries to include vehicle-to-infrastructure communication protocols.
- Voice Recognition and Generative AI Convergence:Natural language processing engines enable conversational cabin control that differentiates premium tiers.
Industry Challenges
- Functional Safety Certification Timeline:ISO 26262 ASIL-D validation for safety-critical display systems extends development cycles by 12-18 months.
- Legacy Vehicle Network Integration:CAN bus and Ethernet backbone coexistence demands protocol translation layers that inflate software complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Navigation & Infotainment Systems Market |
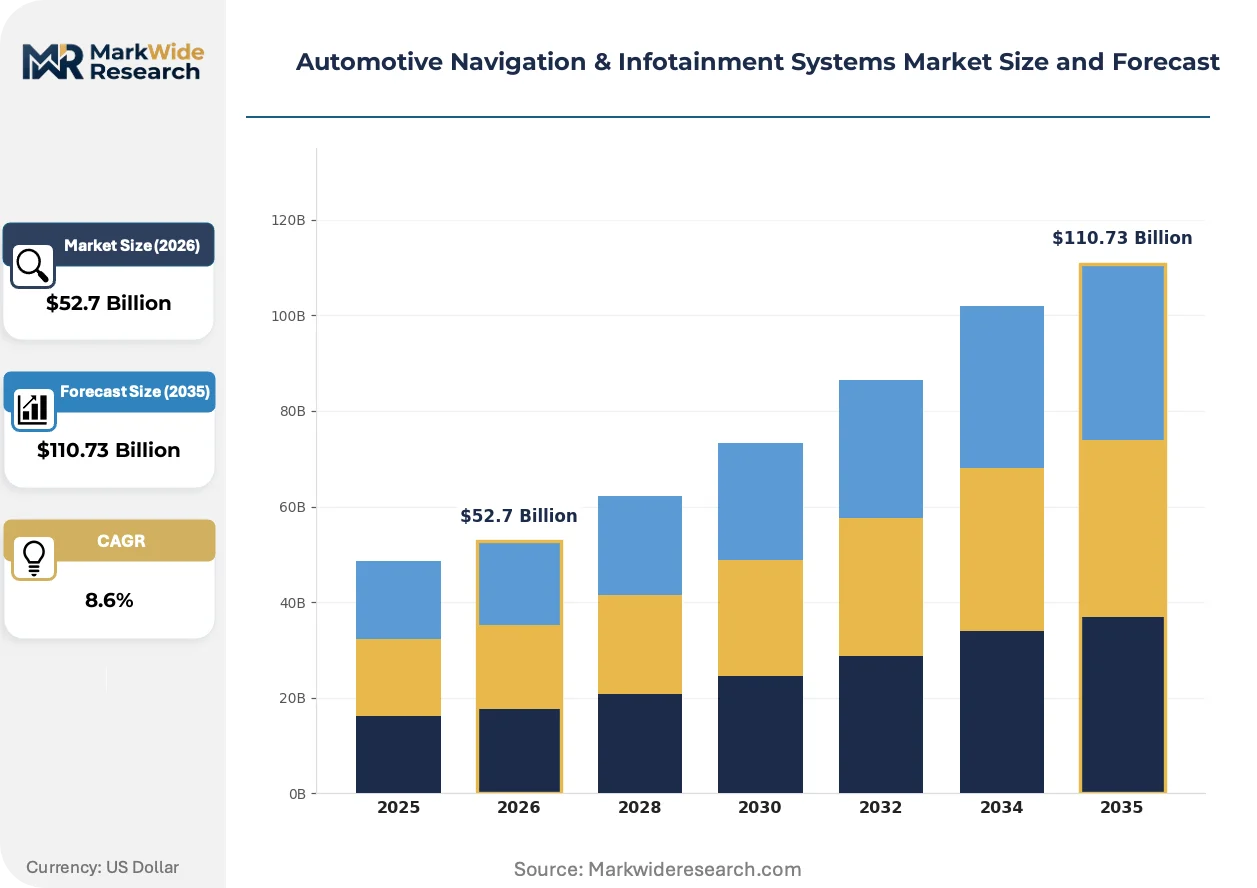
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Display, Embedded Navigation, Portable Navigation, Smartphone Integration Technology: GPS, Cloud-Based Mapping, Bluetooth, Voice Recognition End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Feature: Real-Time Traffic Updates, Offline Navigation, Multi-Language Support, Vehicle Diagnostics |
| Companies Covered | Continental AG, Harman International, Robert Bosch GmbH, Panasonic Corporation, Denso Corporation, Alpine Electronics, Pioneer Corporation, Garmin Ltd., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Navigation & Infotainment Systems Market Evolving Landscape
Interface virtualization and regulatory fragmentation are redefining how navigation and infotainment systems are architected, procured, and monetized across vehicle programs.
Hypervisor-based cockpit domain controllers are virtualizing multiple operating environments on unified compute hardware. Premium OEMs in Germany and Japan are deploying these consolidated stacks to reduce ECU count and wiring mass. This consolidation is virtualizing the traditional tier-1 supply relationships by enabling direct software vendor contracts.
NHTSA distraction guidelines in the United States are converging with ECE R79 enforcement patterns, creating transatlantic interface design standards. The industrial consequence is mandatory eye-tracking and gesture recognition R&D spending. Head-up display manufacturers face the steepest compliance burden as regulators scrutinize augmented reality overlay density.
Fleet operators and mobility service providers are unbundling infotainment from vehicle purchase decisions, treating cabin systems as configurable service tiers. Subscription-based navigation and media packages are displacing perpetual licenses in commercial vehicle segments. This shift is most visible in North American last-mile delivery fleets where driver retention depends on familiar app ecosystems.
Automotive Navigation & Infotainment Systems Market Segmentation
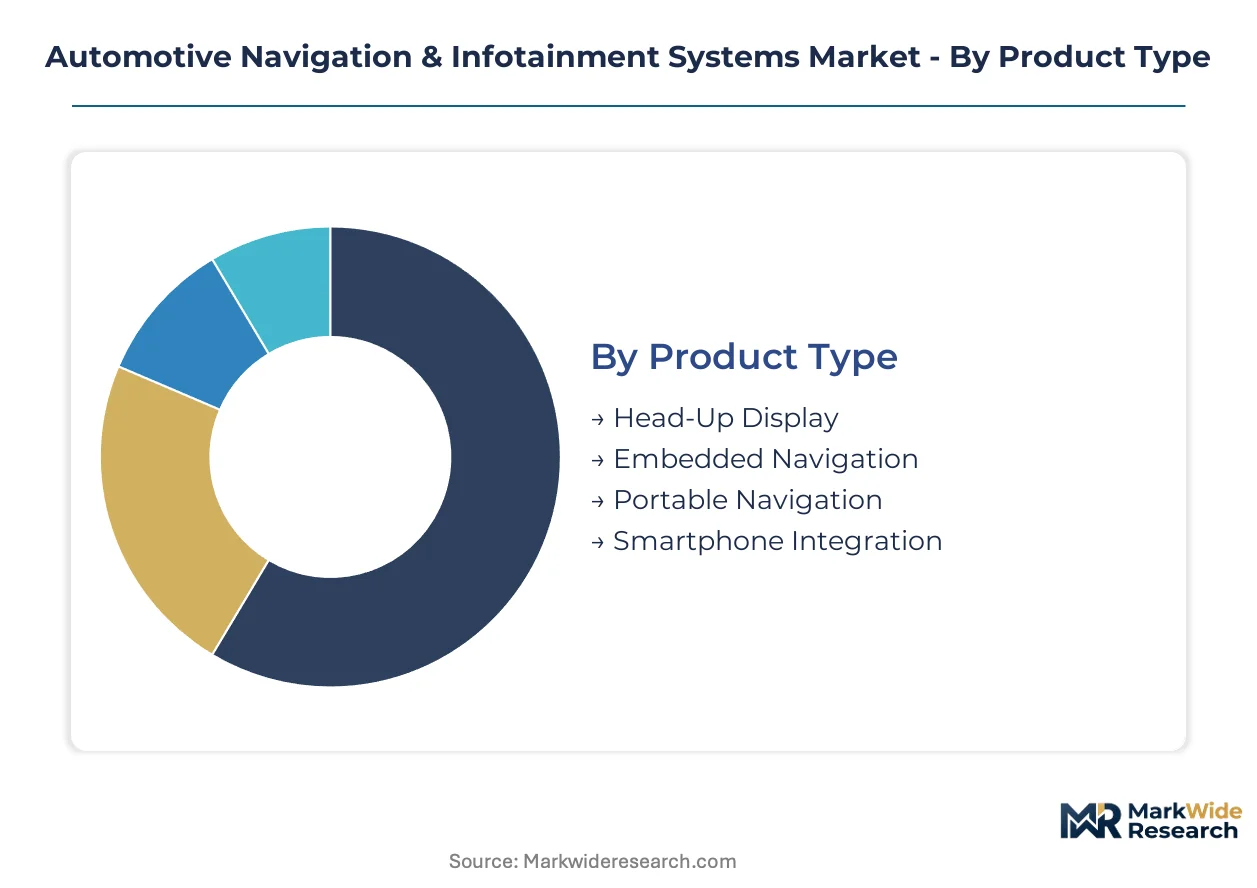
Segmentation in automotive navigation and infotainment systems reveals how software-defined architectures are fragmenting traditional hardware bundles into discrete, monetizable capabilities. Each dimension exposes different competitive dynamics: product type separates premium embedded systems from zero-cost smartphone alternatives, while technology choices determine recurring revenue potential versus one-time hardware margins.
Product Type:
Mature hardware categories coexist with emerging service-oriented formats as OEMs balance upfront revenue against lifecycle monetization.
- Embedded Navigation:Factory-integrated systems bundle proprietary map data with vehicle network protocols, generating sticky OEM relationships through hardware-software coupling. German premium manufacturers anchor demand here, though ECE R79 compliance costs inflate R&D investment thresholds.
- Head-Up Display:Windshield-projected augmented reality overlays merge camera feeds with navigation guidance, commanding substantial price premiums in luxury segments. NHTSA distraction guidelines impose strict overlay density limits that constrain feature expansion.
- Smartphone Integration:Apple CarPlay and Android Auto leverage familiar consumer app ecosystems at zero incremental hardware cost.
- Portable Navigation:Standalone GPS devices persist in commercial fleet applications where device standardization across mixed vehicle ages matters.
Embedded navigation retains volume leadership; smartphone integration holds the steepest expansion curve.
Technology:
Cost tier stratification separates foundational positioning infrastructure from premium connectivity and interface layers.
- Cloud-Based Mapping:Continuously updated routing engines enable real-time traffic optimization and predictive destination suggestions. Japanese OEMs prioritize this capability through METI SIP-adus program alignment, though data connectivity costs compress margins in price-sensitive segments.
- Voice Recognition:Natural language processing engines reduce touchscreen dependency to satisfy ECE R79 distraction mandates. Generative AI convergence is accelerating capability investment among tier-1 suppliers.
- GPS:Satellite positioning remains the foundational location layer across all system architectures.
- Bluetooth:Short-range wireless protocols enable smartphone tethering for audio streaming and hands-free calling.
GPS underpins universal system architectures; cloud-based mapping is gaining share fastest.
End User:
Customer type determines procurement scale, integration complexity, and service monetization potential across the value chain.
- OEMs:Vehicle manufacturers specify embedded systems during platform development, locking in multi-year supply agreements with tier-1 integrators. German automotive engineering corridors concentrate specification authority for European programs.
- Fleet Operators:Commercial vehicle buyers treat infotainment as configurable service tiers rather than capital investments, accelerating subscription navigation adoption in North American last-mile delivery segments.
- Aftermarket Providers:Independent installers serve vehicle age extension and retrofit demand outside factory warranty periods.
- Individual Consumers:Retail purchasers prioritize smartphone mirroring compatibility and familiar app ecosystems over proprietary embedded features.
OEMs dominate specification authority; fleet operators are climbing the fastest.
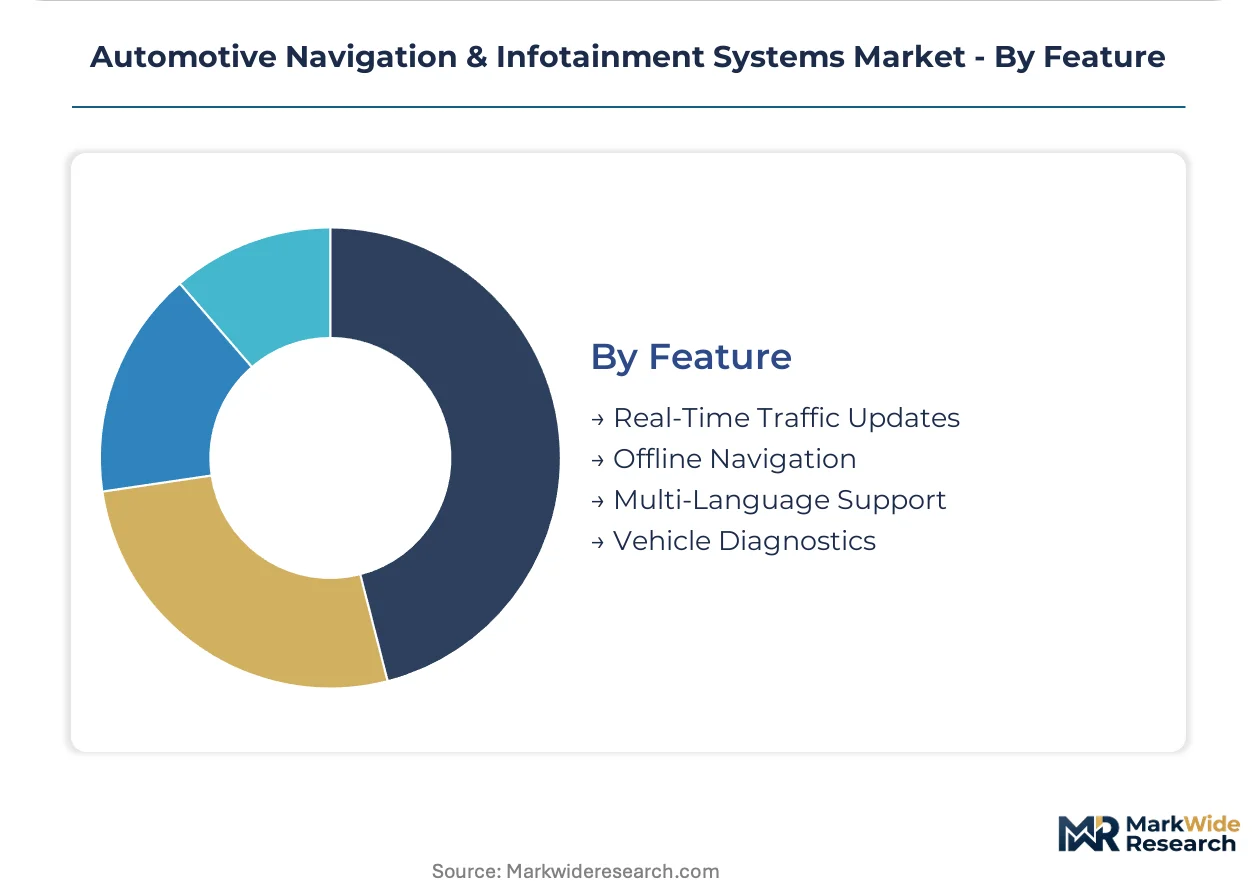
Feature:
Application-critical capabilities separate must-have compliance features from discretionary premium additions.
- Real-Time Traffic Updates:Dynamic routing adjustments based on congestion data reduce journey times and fuel consumption. Cloud connectivity requirements create recurring revenue structures for map data providers.
- Vehicle Diagnostics:Integration with CAN bus and Ethernet backbones enables predictive maintenance alerts and remote troubleshooting. ISO 26262 ASIL-D certification extends development timelines for safety-critical display implementations.
- Offline Navigation:Local map storage ensures routing capability in connectivity dead zones without data roaming costs.
- Multi-Language Support:Localization packages enable single hardware SKUs across diverse export markets.
Real-time traffic updates retain volume leadership; vehicle diagnostics holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-1 suppliers export cockpit domain controllers to North American and Asian OEM assembly plants, while Japanese electronics manufacturers ship head-up display modules to European premium vehicle programs.
Germany
ECE R79 driver distraction mandates accelerate voice-first interface adoption across Bavarian and Baden-Württemberg engineering centers. Stuttgart's automotive cluster concentrates embedded navigation R&D investment from Continental AG and Robert Bosch GmbH. Ingolstadt and Munich anchor premium OEM specification authority for augmented reality head-up display programs.
United States
NHTSA distraction guidelines reshape touchscreen interaction limits for Detroit Three vehicle programs. Michigan's automotive corridor hosts tier-1 integration facilities serving domestic OEM embedded navigation procurement. Silicon Valley software vendors supply cloud-connected mapping engines to supplement hardware-centric tier-1 portfolios.
Japan
METI SIP-adus program mandates V2X protocol integration into infotainment system boundaries. Nagoya's Chubu region concentrates Denso Corporation and Panasonic Corporation manufacturing scale for head-up display export programs. Tokyo-based OEMs prioritize generative AI convergence in voice recognition cabin control systems.
China
Domestic EV manufacturers specify hypervisor-based cockpit domain controllers for software-defined vehicle architectures. MIIT connected vehicle standards accelerate local supplier qualification for embedded navigation programs. Yangtze River Delta electronics clusters supply display modules to European and North American tier-1 integrators.
South Korea
Hyundai Motor Group and Kia Corporation procurement drives embedded navigation adoption across premium vehicle tiers. MFDS automotive electronics certification aligns with ISO 26262 functional safety requirements for display systems. Seoul Capital Area engineering centers develop over-the-air update platforms for extended system lifecycles.
Automotive Navigation & Infotainment Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Tier-1 integrators anchor OEM specification authority through multi-year platform agreements, while component specialists capture niche margin pools in display modules and audio subsystems. Three archetypes dominate: diversified automotive electronics conglomerates, cockpit domain controller pure-plays, and smartphone ecosystem extenders. Competitive moves concentrate on strategic partnerships for software stack integration and geographic expansion into India's PLI-subsidized manufacturing zones.
Among German-based diversified suppliers, Continental AG and Robert Bosch GmbH occupy positions anchoring high-volume European OEM programs through integrated hardware-software portfolios. Harman International exemplifies the premium-tier archetype, differentiating through audio-visual integration and recurring service revenue models. These three represent distinct strategic postures: manufacturing scale, compliance-driven system integration, and consumer electronics brand extension into automotive cabin environments.
| Leading Market Players |
|---|
| Continental AG |
| Harman International |
| Robert Bosch GmbH |
| Panasonic Corporation |
| Denso Corporation |
| Alpine Electronics |
| Pioneer Corporation |
| Garmin Ltd. |
| Visteon Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta display module clusters feed tier-1 integrators across Germany, Japan, and North America, concentrating capacity leverage among a handful of panel manufacturers who dictate terms to cockpit domain controller assemblers downstream. This geographic chokepoint amplifies pricing power for high-resolution automotive-grade screens while compressing margins for system integrators lacking captive supply arrangements.
Pricing Analysis
Next-generation augmented reality head-up displays command substantial premiums over current-generation central stack screens, while prior-generation portable navigation units face steep price erosion from smartphone mirroring substitution. Three-tier pricing structure across premium AR-HUD, standard embedded navigation, and economy smartphone-integration levels stratifies the market by certification grade and content-per-vehicle complexity. Cost compression in the standard tier is intensifying because ECE R79 compliance mandates inflate R&D recovery requirements. Fleet operators exhibit highest price sensitivity due to configurable service-tier procurement models, while German premium OEMs remain least sensitive given embedded system bundling with vehicle platform economics.
Supply Chain Analysis
Automotive-grade SoC fabrication draws from Taiwan, South Korea, and select United States foundries, creating concentrated dependency on advanced semiconductor nodes for cockpit domain controllers. Raw material inputs span high-brightness display substrates, rare-earth phosphors for HUD projection systems, and copper-laminated substrates for multi-layer PCBs. Single-source vulnerability pervades 7-nanometer and below automotive chip fabrication, where capacity allocation favors consumer electronics during supply crunches. Distribution runs through tier-1 system integrators who consolidate hardware-software bundles for OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Japanese OEM platform engineering teams who consolidate specification authority across multi-year vehicle programs, fragmenting tier-1 supplier negotiating leverage. This consolidation demands differentiated strategic postures from market participants.
For Market Incumbents: Pre-empt smartphone mirroring substitution by accelerating voice-first interface differentiation through generative AI convergence, while securing captive display module supply via backward integration into Yangtze River Delta manufacturing partnerships. ECE R79 compliance investment creates defensive moats against emerging entrants lacking ASIL-D certification experience. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automotive electronics manufacturing corridor, where production-linked incentives offset initial scale disadvantages against established German and Japanese suppliers. Target aftermarket retrofit demand for legacy vehicle voice recognition upgrades, leveraging cloud-based mapping APIs to bypass proprietary embedded navigation licensing costs. For Investors and Strategic Acquirers: Long-term, this sits as a software-recurring-revenue play because over-the-air update platforms displace perpetual hardware licenses across the analysis window. Acquisition candidates with cockpit domain controller hypervisor expertise and established OEM platform relationships warrant priority evaluation. Monitor V2X mandate implementation velocity in Japan's METI SIP-adus program as inflection indicator for infotainment system boundary redefinition.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Hypervisor-based cockpit consolidation enables direct software vendor contracts that virtualize traditional tier-1 relationships. |
| Battery Supply Agreement | EV platform electrification shifts infotainment power budgets and thermal management requirements for display systems. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts component localization for export-oriented embedded navigation production. |
| Platform Standardization | OEM consolidation onto unified compute hardware reduces ECU count and wiring mass across vehicle programs. |
| Charging Infrastructure Partnership | Route optimization integration with charging network APIs extends embedded navigation value beyond basic guidance. |
Research Methodology
Desk research of automotive production databases, IHS Markit registration data, and regulatory filing repositories preceded structured interviews with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distribution specialists, and dealership operations managers. Bottom-up triangulation across vehicle program content-per-vehicle estimates and top-down validation against regional production forecasts anchored market sizing. Secondary sources included SEC 10-K disclosures from listed automotive electronics suppliers and customs records for display module trade flows.
Assumptions held fixed include ECE R79 enforcement patterns, NHTSA distraction guideline stability, and semiconductor fabrication capacity allocation norms; variables stress-tested encompass V2X mandate acceleration, smartphone mirroring penetration ceilings, and generative AI integration timelines. Segmentation dimensions spanned product type, technology layer, end-user archetype, and vehicle class across the projection horizon. CAGRs derived from logistic growth curve fitting against historical adoption S-cycles for comparable automotive electronics categories, with infotainment content-per-vehicle trajectories and OEM platform refresh cadences as primary inputs.
Stress conditions across semiconductor supply disruption severity, regulatory divergence between touchscreen limits and autonomous HMI exemptions, and fleet operator subscription adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from macroeconomic, technological, or policy shifts. Cross-checking against IHS Markit vehicle production forecasts and tier-1 supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Automotive Embedded Telematics Market