
 Japan Commercial Telematics Market | 2026-2036
Japan Commercial Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Commercial Telematics Market Intelligence
Small and mid-size fleet operators is collapsing as the dominant buyer archetype while large enterprise logistics providers capture disproportionate platform investment. Denso Corporation leverages its Tier-1 automotive supply relationships to embed telematics hardware at the factory level. Panasonic Corporation anchors its position through ruggedized device manufacturing and cloud integration capabilities. Toyota Motor Corporation extends its mobility ecosystem into commercial fleet data services through captive dealer networks.
Japan commercial telematics encompasses GPS-enabled vehicle monitoring, cellular data transmission, and cloud-based analytics platforms that optimize fleet utilization, driver safety, and regulatory compliance through real-time telemetry collection and predictive maintenance algorithms. Fleet management services dominate current revenue pools while insurance telematics represents the fastest-expanding segment as Japanese non-life insurers mandate usage-based risk models. GPS technology leads deployment volumes though cellular connectivity is displacing older protocols as 5G infrastructure reaches Japan's expressway corridors.
METI's connected vehicle data governance frameworks and Japan's Ministry of Land, Infrastructure, Transport and Tourism commercial vehicle safety mandates shape product certification requirements and platform interoperability standards. JIS standards for automotive electronics further constrain hardware specifications and software integration protocols. Stakeholders must monitor how impending amendments to Japan's Road Transport Vehicle Law redefine data retention obligations and cross-border fleet data transfer permissions.
Market Dynamics
The Japan Commercial Telematics Market pivots on METI's data governance frameworks forcing platform standardization across fleet operators while 5G infrastructure deployment along expressway corridors accelerates cellular protocol migration.
Growth Catalysts
- 5G Infrastructure Rollout:Japan's Ministry of Internal Affairs and Communications spectrum allocation enables real-time video telematics and edge computing applications along the Tomei and Meishin expressway corridors.
- Commercial Vehicle Safety Mandates:Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates drive-by-wire logging and driver monitoring systems for heavy-duty trucks operating intercity routes.
- Insurance Telematics Adoption:Japanese non-life insurers now mandate usage-based risk models for commercial fleet policies, creating embedded hardware demand across logistics providers.
Market Restraints
- Semiconductor Supply Concentration:Automotive-grade GPS and cellular module fabrication concentrates in Taiwanese foundries, exposing Japanese telematics hardware assemblers to geopolitical supply volatility.
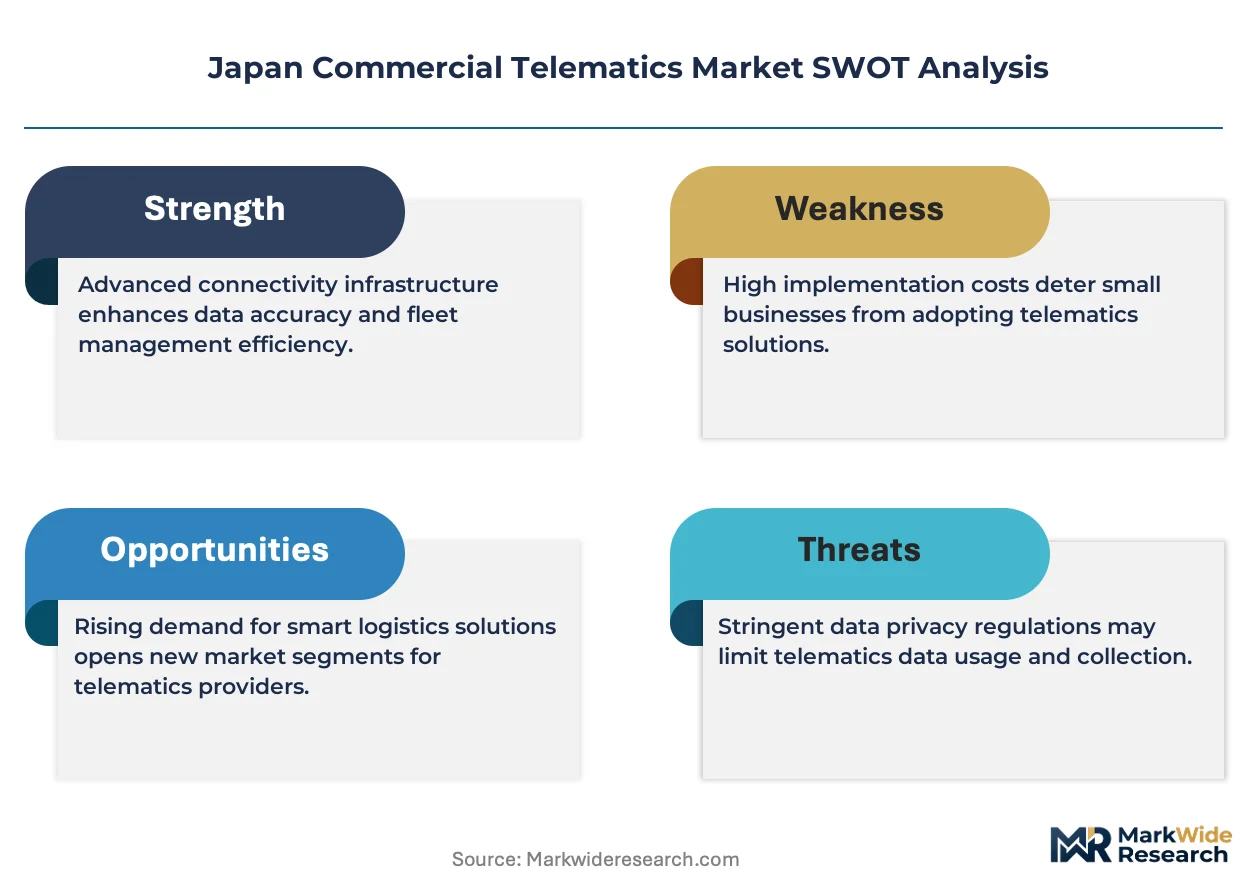
- Legacy Fleet Retrofit Costs:Small and mid-size operators face prohibitive capex burdens when upgrading from 2G/3G cellular protocols to LTE-M and 5G-ready architectures.
- Data Localization Requirements:METI's draft amendments to cross-border data transfer rules create compliance friction for multinational fleet operators with centralized analytics platforms.
Strategic Opportunities
- Hokkaido and Tohoku Underpenetration:Northern Japan's agricultural and cold-chain logistics fleets remain below 15% telematics penetration, offering first-mover expansion potential.
- AI-Driven Predictive Maintenance:Convergence of edge AI chips with vehicle CAN bus integration enables real-time component failure prediction for refrigerated transport units.
- Dealer Network Channel Innovation:Toyota's captive dealer networks now bundle telematics subscriptions with commercial vehicle leases, creating embedded distribution paths.
Industry Challenges
- Embedded Systems Engineering Talent Gap:Japanese OEMs and Tier-1 suppliers compete for scarce firmware developers capable of integrating JIS-standard automotive electronics with cloud-native platforms.
- Multi-Protocol Integration Complexity:Fleet operators demand seamless coexistence of legacy GPS, emerging C-V2X, and satellite backup systems, stretching systems integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Commercial Telematics Market |
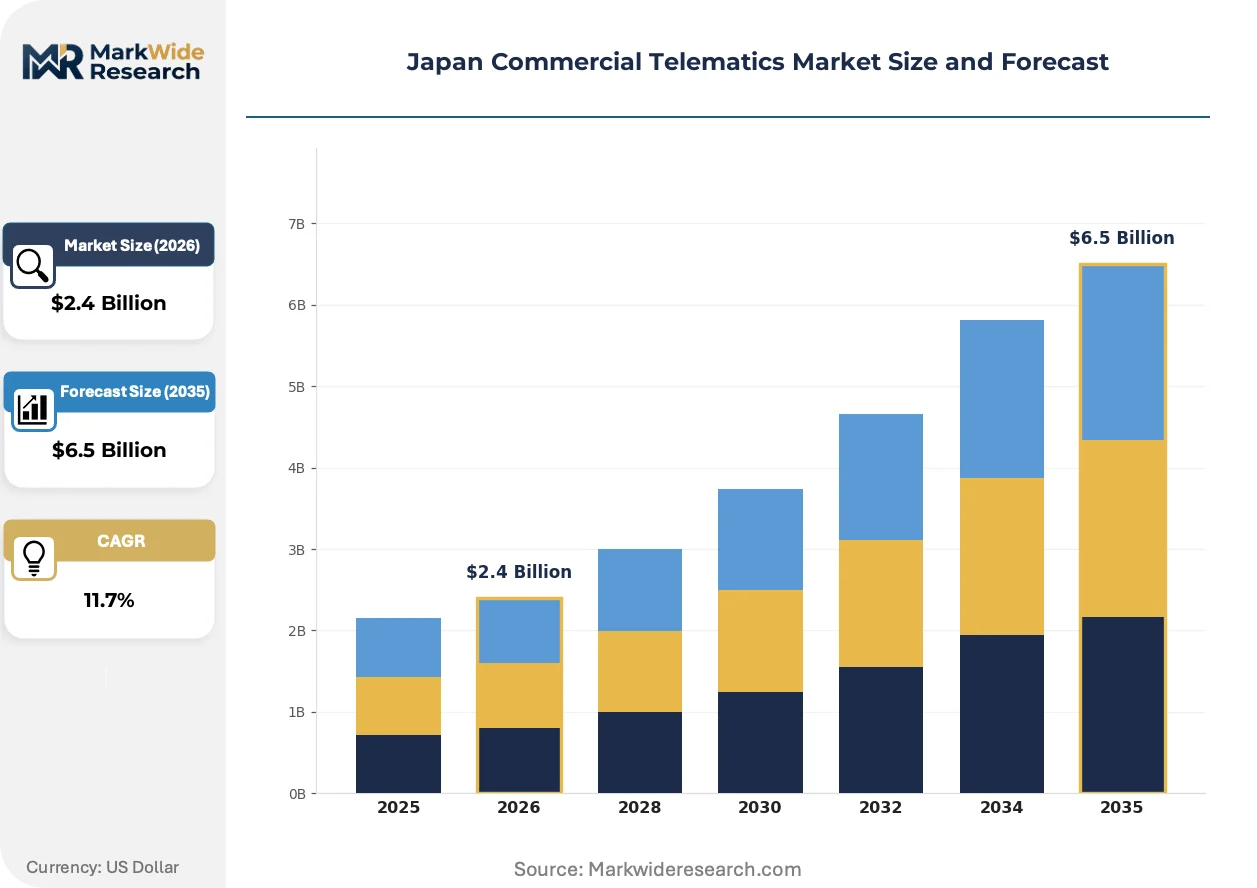
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fleet Management, Insurance Telematics, Navigation Services, Driver Behavior Monitoring Technology: GPS, RFID, Cellular, Bluetooth End User: Logistics, Transportation, Construction, Public Sector Deployment: On-Premise, Cloud-Based, Hybrid, Integrated Solutions |
| Companies Covered | Denso Corporation, Panasonic Corporation, Toyota Motor Corporation, Bosch, Continental, Nissan Corporation, Fujitsu Limited, NTT Docomo, Honda Motor Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Commercial Telematics Market Strategic Shifts & Innovations
Edge computing architectures and AI inference at the vehicle level are compressing latency requirements for safety-critical telematics applications. Three developments dominate vendor roadmaps and fleet procurement criteria.
Multi-constellation GNSS chipsets combining GPS, QZSS, and Galileo signals is miniaturizing into surface-mount packages suitable for motorcycle and light commercial vehicle form factors. Tier-1 automotive suppliers embed these modules at the factory level for new vehicle platforms. The shift eliminates aftermarket installation costs while enabling sub-meter positioning accuracy for lane-level routing in Tokyo's dense urban corridors.
METI's 2024 amendments to the Act on the Protection of Personal Information impose explicit consent requirements for driver biometric data collection through in-cabin cameras. Fleet operators must now deploy anonymization pipelines before transmitting footage to cloud analytics platforms. Insurance telematics providers face the steepest compliance burden, as usage-based pricing models rely on granular driver behavior scoring.
Subscription-based fleet management software is displacing perpetual license purchases among Kanto region logistics providers. Buyers prefer operational expenditure models that bundle hardware, connectivity, and platform access into per-vehicle monthly fees. This preference concentrates among third-party logistics operators with volatile fleet sizes, who prioritize cash flow flexibility over long-term asset ownership.
Japan Commercial Telematics Market Segmentation
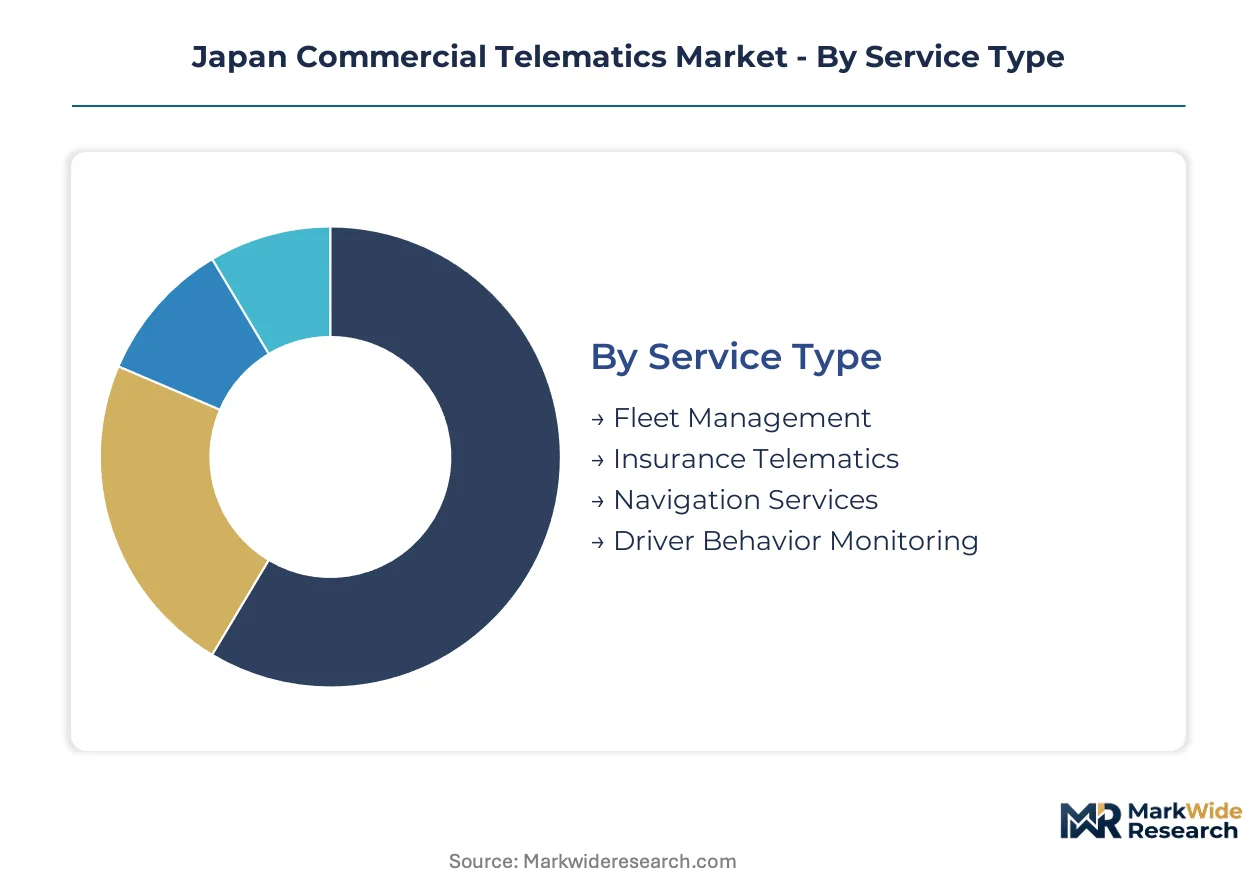
Segmentation in Japan's commercial telematics market reveals how regulatory mandates and infrastructure investments concentrate demand across distinct technology and service configurations. Fleet operators select segments based on METI compliance requirements, 5G coverage availability, and integration complexity with existing vehicle platforms.
Service Type:
METI's data governance frameworks and Japan's Ministry of Land, Infrastructure, Transport and Tourism safety mandates create divergent compliance burdens across service categories, with insurance-linked offerings facing the steepest biometric consent requirements.
- Fleet Management:GPS-enabled vehicle monitoring combined with cellular data transmission and cloud-based analytics optimizes asset utilization and regulatory compliance for logistics corridors. Demand concentrates among Kanto region third-party logistics operators managing volatile fleet sizes, driven by subscription-based operational expenditure preferences over perpetual licensing.
- Insurance Telematics:Usage-based risk models mandate embedded hardware collecting granular driver behavior data for Japanese non-life insurers. METI's 2024 Act on the Protection of Personal Information amendments impose explicit consent and anonymization pipelines for biometric footage, creating compliance friction for centralized analytics platforms.
- Navigation Services:Multi-constellation GNSS combining GPS, QZSS, and Galileo enables sub-meter lane-level routing accuracy.
- Driver Behavior Monitoring:In-cabin cameras with edge AI processing support safety scoring while addressing data localization requirements.
Fleet Management handles the majority of throughput; Insurance Telematics is expanding most quickly on share.
Technology:
Cellular protocol migration along Japan's expressway corridors is reshaping deployment volumes, with 5G infrastructure enabling real-time video telematics and displacing legacy 2G/3G architectures.
- GPS:Satellite positioning remains the foundational location technology, though multi-constellation chipsets now integrate QZSS and Galileo signals for enhanced accuracy. Deployment concentrates in factory-embedded modules for new commercial vehicle platforms, eliminating aftermarket installation costs for Tokyo-Kanagawa-Saitama logistics corridors.
- Cellular:LTE-M and 5G protocols enable edge computing applications and real-time telemetry transmission along Tomei and Meishin expressway corridors. Japanese non-life insurers now mandate cellular-connected hardware for usage-based commercial fleet policies, accelerating displacement of older protocols.
- RFID:Short-range identification supports yard management and asset tracking in dense urban distribution centers.
- Bluetooth:Low-energy protocols facilitate driver authentication and proximity-based vehicle access control.
Cellular is gaining share fastest; GPS maintains the dominant installed base.
End User:
Application intensity varies by sector compliance exposure, with intercity heavy-duty trucking facing the strictest drive-by-wire logging and driver monitoring mandates.
- Logistics:Third-party operators and enterprise fleet providers across the Kanto industrial belt deploy comprehensive telematics stacks combining GPS tracking, cellular connectivity, and predictive maintenance algorithms. Subscription bundling through Toyota's captive dealer networks now embeds telematics with commercial vehicle leases.
- Transportation:Intercity bus and coach operators face Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates for drive-by-wire logging and driver monitoring systems on heavy-duty routes.
- Construction:Equipment tracking and utilization monitoring addresses project-site asset management requirements.
- Public Sector:Municipal fleet electrification and safety compliance drive standardized procurement across prefecture-level governments.
Logistics captures the dominant revenue pool; Transportation shows the steepest regulatory-driven expansion.
Deployment:
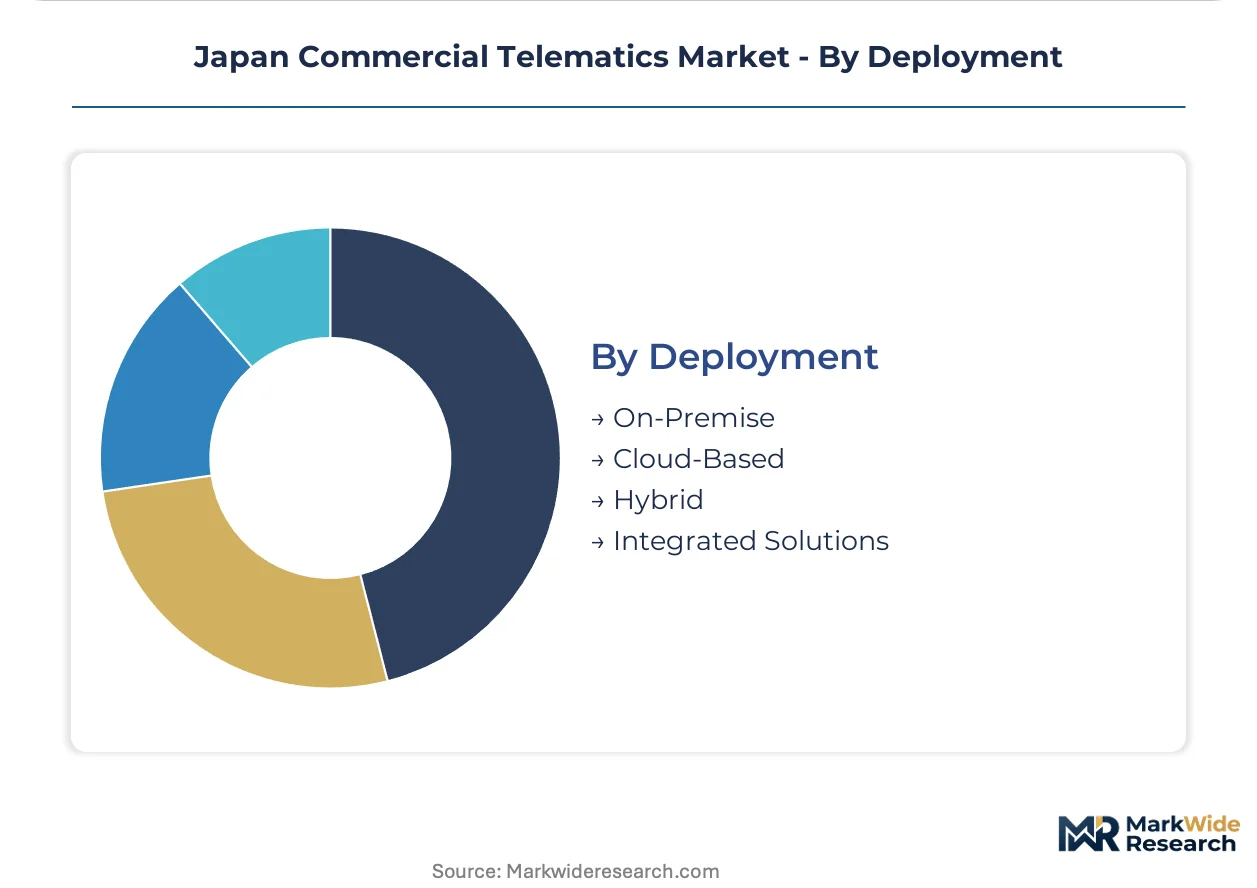
Cloud migration patterns among Kanto region operators reflect preference for operational expenditure models that bundle hardware, connectivity, and platform access into per-vehicle monthly fees.
- Cloud-Based:Subscription fleet management software displaces perpetual licenses among volatile-size operators prioritizing cash flow flexibility. METI's draft cross-border data transfer amendments create compliance friction for multinational fleet operators with centralized analytics platforms hosted outside Japan.
- On-Premise:Large enterprise logistics providers with captive IT infrastructure maintain localized data retention to satisfy impending Road Transport Vehicle Law amendments on data retention obligations.
- Hybrid:Edge computing architectures with cloud analytics pipelines balance latency requirements against storage economics.
- Integrated Solutions:Factory-embedded telematics at the Tier-1 supplier level eliminate aftermarket installation complexity.
Cloud-Based leads new procurement; Integrated Solutions is climbing fastest on share through OEM bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tomei and Meishin expressway corridors anchor Japan's commercial telematics infrastructure, enabling 5G-enabled real-time telemetry across the country's densest logistics networks. These arterial routes connect the Kanto industrial belt to western manufacturing centers, creating contiguous coverage zones for cellular-protocol fleet management systems.
Kanto
Tokyo, Kanagawa, and Saitama prefectures concentrate over half of Japan's third-party logistics operators, driving subscription-based telematics procurement. METI's data governance frameworks mandate platform standardization here first, with fleet operators piloting edge-computing architectures before national rollout. The Port of Tokyo and Port of Yokohama container terminals generate dense short-haul trucking demand for GPS-cellular hybrid tracking.
Kansai
Osaka and Kyoto prefectures host automotive component suppliers integrating factory-embedded telematics into commercial vehicle platforms. Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates for intercity heavy-duty trucks apply with particular force on the Meishin corridor connecting to Nagoya. Cold-chain logistics operators in the Kansai Science City cluster deploy predictive maintenance algorithms for refrigerated transport units.
Chubu
Aichi and Shizuoka prefectures anchor Toyota's captive dealer network distribution for telematics-embedded commercial vehicle leases. The Tomei Expressway's 5G infrastructure enables real-time video telematics pilots here before eastern corridor extension. Nagoya's automotive manufacturing belt generates OEM-Tier-1 collaboration on multi-constellation GNSS module integration.
Hokkaido
Agricultural and cold-chain logistics fleets across Hokkaido remain below 15% telematics penetration, offering expansion headroom for first-mover vendors. METI's draft cross-border data transfer amendments create compliance complexity for multinational operators with centralized platforms. Sapporo's food distribution hub drives isolated demand for satellite-backup systems where cellular coverage gaps persist.
Kyushu
Fukuoka and Saga prefectures host semiconductor packaging facilities supplying automotive-grade GPS modules to domestic telematics assemblers. The Kyushu Shinkansen extension improves intercity freight rail competition, pressuring trucking operators toward efficiency-optimizing fleet management software. Kitakyushu's industrial zone maintains legacy 2G/3G retrofit demand among smaller construction fleet operators.
Japan Commercial Telematics Market Key Industry Players
Listed leaders compete with private specialists across factory-embedded versus aftermarket installation channels, creating a tiered structure where captive automotive supply relationships dominate premium procurement. Tier-1 automotive suppliers leverage OEM integration pathways to eliminate dealer-level hardware decisions. Strategic archetypes separate into factory-embedded platform providers, ruggedized device manufacturers, and captive mobility ecosystem extenders. Dominant competitive moves center on dealer network bundling arrangements and backward integration into semiconductor module sourcing.
Among Japan-based conglomerates with automotive supply heritage, Denso Corporation, Panasonic Corporation, and Toyota Motor Corporation exemplify the three prevailing archetypes. Denso occupies a position representing Tier-1 factory-embedded integration, Panasonic anchors the ruggedized hardware manufacturing tier, and Toyota sits within the captive ecosystem extension model. These three structures illustrate how commercial telematics procurement in Japan flows through pre-existing automotive supply relationships rather than independent software vendor channels. Bosch and Continental represent non-Japanese participants competing through technology licensing rather than domestic manufacturing presence.
| Leading Market Players |
|---|
| Denso Corporation |
| Panasonic Corporation |
| Toyota Motor Corporation |
| Bosch |
| Continental |
| Nissan Corporation |
| Fujitsu Limited |
| NTT Docomo |
| Honda Motor Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day lead times for automotive-grade cellular modules concentrate pricing power with Taiwanese foundry partners while compressing margins for Japanese hardware assemblers facing volatile logistics corridors. This inventory exposure shapes procurement behavior across Kanto region fleet operators who must balance subscription pricing flexibility against embedded hardware commitments.
Pricing Analysis
Volume-discount tiering structures separate enterprise logistics providers purchasing thousand-unit fleets from small operators buying below fifty units. Three-tier pricing stratifies across factory-embedded OEM bundles, dealer-channel aftermarket installations, and direct-procurement ruggedized devices. Cost compression in the aftermarket tier intensifies as 5G module prices erode and subscription bundling through captive dealer networks forces standalone hardware vendors toward service-margin dependence. Small and mid-size operators exhibit highest price sensitivity, while large enterprise fleets prioritize integration reliability over per-unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for GPS receivers, cellular baseband processors, and edge AI inference chips serving Japanese telematics hardware assemblers. Domestic production draws from imported silicon wafers, automotive-grade memory components, and precision antenna substrates. Single-source vulnerability concentrates in 5G modem supply where Qualcomm and MediaTek dominate baseband architecture licensing. Distribution runs through Tier-1 automotive supplier channels that embed modules at the factory level, bypassing traditional electronics distributor networks for new vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against platform substitution as automotive OEMs internalize telematics software stacks and disintermediate independent fleet management vendors. The threat of captive ecosystem capture by Toyota-style dealer networks reshapes competitive boundaries.
For Market Incumbents: Consolidate backward integration into semiconductor sourcing to secure allocation priority during supply constraints. Deepen JIS certification investment to maintain factory-embedded positioning against aftermarket displacement. Denso's Tier-1 supply relationships demonstrate how captive automotive channels resist price erosion from software-only entrants. For New Entrants and Emerging Players: METI compliance fast-tracks for data localization and biometric consent protocols open regulatory moats against multinational competitors. Target Hokkaido's agricultural cold-chain fleets where penetration sits below fifteen percent and incumbent coverage remains thin. Partner with regional telecommunications carriers for satellite-cellular hybrid connectivity where expressway 5G gaps persist. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial electronics divisions seeking telematics portfolio rationalization. Five-to-ten year viability hinges on edge AI capability integration rather than hardware manufacturing scale. Monitor METI's final cross-border data transfer amendments as the signal indicating regulatory arbitrage windows for domestic-platform specialists.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Module Supply Agreement | Secures allocation priority from Taiwanese foundries during semiconductor constraint periods. |
| JIS Certification Fast-Track | Accelerates factory-embedded hardware approval for METI compliance mandates. |
| Dealer Network Bundling Partnership | Embeds subscription revenue through Toyota-style captive lease distribution. |
| Edge AI Chip Integration | Enables real-time predictive maintenance for refrigerated transport units. |
| Hokkaido Distribution Expansion | Captures first-mover position in agricultural logistics below fifteen percent penetration. |
Research Approach
Desk research of METI regulatory filings, JIS standard documentation, and vehicle production databases preceded structured interviews with Tier-1 supplier procurement managers, fleet operations directors at Kanto logistics providers, and telecommunications infrastructure planners. Primary fieldwork combined with secondary validation across customs trade records, expressway 5G deployment schedules, and non-life insurance policy filings. Bottom-up fleet operator surveys and top-down automotive production estimates underwent triangulation to constrain variance.
Variance decomposition across service type, technology protocol, and end-user industry dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated deployment architecture preferences, regional regulatory cluster intensity, and OEM integration depth as structural drivers. CAGRs derived from logistic curve fitting to technology substitution patterns and infrastructure rollout timelines. Forecast inputs included 5G base station deployment trajectories along Tomei and Meishin corridors and METI amendment implementation schedules.
Underlying assumptions cover stable semiconductor supply allocation to automotive grades, with deviation risk concentrated in geopolitical export controls and yen-denominated component cost volatility. Forecasts reflect these conditions without explicit probability weighting. Recalibration cycles align with material shifts in METI data governance enforcement and expressway 5G coverage milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market