
 North America Commercial Vehicle Telematics Market | 2026-2036
North America Commercial Vehicle Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Vehicle Telematics Market Analytics
Canadian and US telematics module suppliers is rebalancing capacity toward software-defined platforms after years of hardware-centric production. Trimble Inc. leverages its precision agriculture heritage to dominate construction and mixed fleet verticals with integrated positioning systems. Omnitracs LLC anchors long-haul trucking through its regulatory compliance engines and driver workflow applications. Geotab Inc. competes on open-platform architecture, allowing third-party developers to build customized fleet analytics atop its device ecosystem.
North America Commercial Vehicle Telematics encompasses GPS, cellular, Bluetooth, and Wi-Fi-enabled systems that transmit real-time vehicle location, engine diagnostics, driver behavior data, and cargo status to centralized fleet management platforms, typically operating through onboard devices with 4G LTE or satellite backhaul and cloud-based analytics dashboards. Fleet Management solutions capture the largest revenue pool as operators consolidate dispatch, fuel optimization, and compliance reporting into unified command centers, while Driver Behavior Monitoring grows fastest among insurance-aligned risk reduction programs. Route Optimization applications command premium pricing from last-mile delivery services facing urban congestion penalties, and Vehicle Tracking remains mature in asset-heavy sectors such as oilfield services and construction equipment leasing.
The Federal Motor Carrier Safety Administration's ELD mandate and the Canadian Council of Motor Transport Administrators' harmonized hours-of-service rules compel fleets to maintain connected compliance records or face operational shutdowns. The US Department of Transportation's forthcoming automatic emergency braking requirements for heavy trucks will further embed telematics into safety-critical vehicle systems. Stakeholders must weigh platform interoperability against vendor lock-in as California's Advanced Clean Trucks regulation and provincial zero-emission mandates in Quebec and British Columbia push electrified fleet transitions.
Market Dynamics
Fleet operators across the United States and Canada face mounting pressure to unify compliance, safety, and fuel management systems into single-platform architectures as regulatory mandates multiply and electrification timelines compress.
Growth Catalysts
- FMCSA ELD Mandate Enforcement:The Federal Motor Carrier Safety Administration's electronic logging device requirements compel long-haul carriers to maintain connected hours-of-service records, embedding telematics as non-negotiable infrastructure.
- Cross-Border Fleet Consolidation:Freight corridors linking Ontario, Michigan, and Texas drive demand for harmonized compliance platforms that satisfy both Canadian Council of Motor Transport Administrators and US Department of Transportation rules.
- Cellular Module Cost Compression:4G LTE chipset economies and satellite backhaul competition reduce hardware deployment barriers for mid-sized fleet operators previously priced out of connected platforms.
Market Restraints
- Semiconductor Supply Concentration:Telematics control unit production depends on concentrated Asian foundry capacity, exposing North American module suppliers to lead time volatility and allocation rationing.
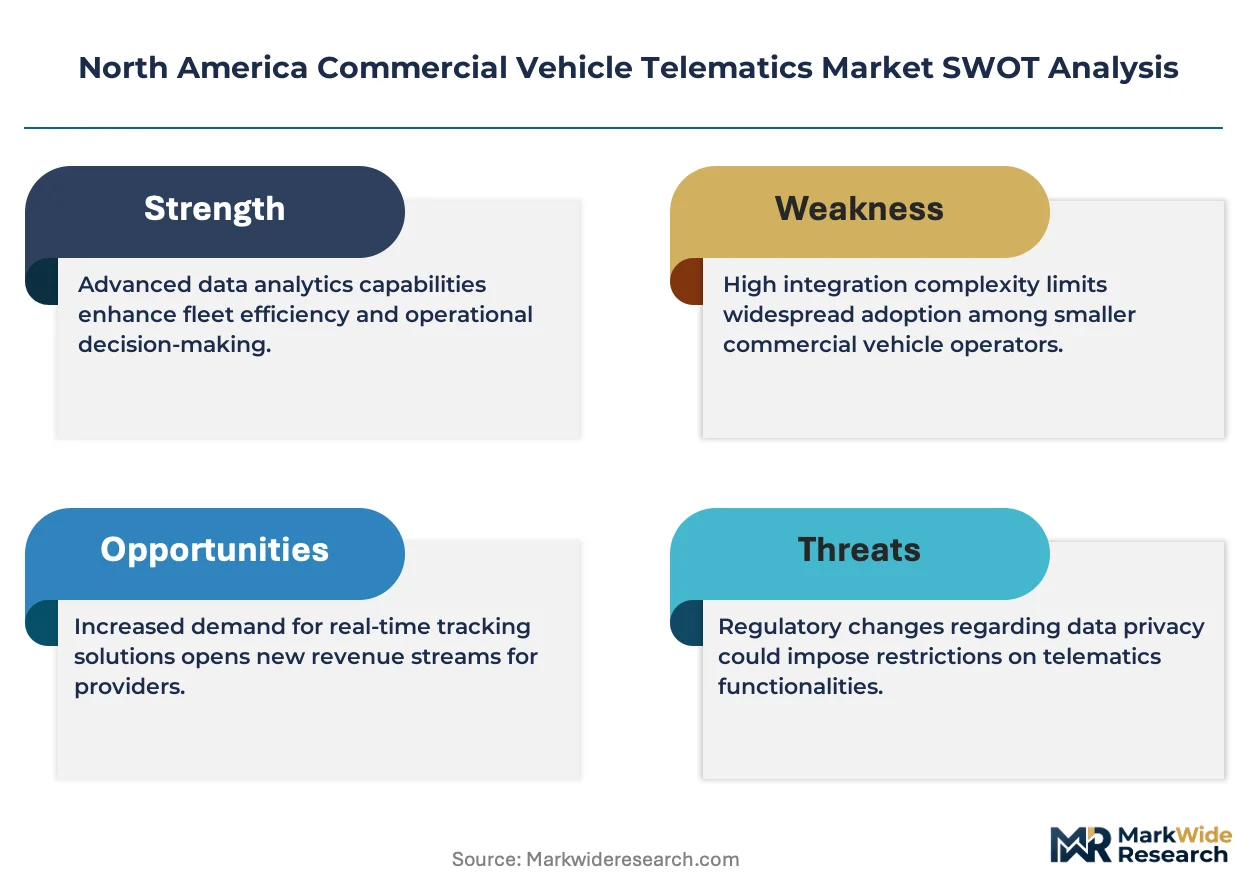
- Platform Interoperability Friction:Proprietary data protocols from dominant vendors create switching costs that lock smaller fleets into suboptimal systems and suppress competitive pressure on pricing.
- Cellular Network Sunsetting:3G network decommissioning by major carriers forces premature hardware refresh cycles for fleets that deployed earlier-generation devices, straining capital reserves.
Strategic Opportunities
- Zero-Emission Fleet Transitions:California's Advanced Clean Trucks regulation and provincial mandates in Quebec and British Columbia create demand for battery state-of-health monitoring integrated with legacy fleet management platforms.
- Insurance-Aligned Risk Programs:Usage-based insurance partnerships offer carriers premium reduction pathways through driver behavior data sharing, opening new revenue streams for telematics providers.
- Construction Equipment Leasing:Oilfield services and infrastructure contractors seek asset tracking for yellow iron and trailers, extending addressable market beyond over-the-road trucking.
Industry Challenges
- Cybersecurity Certification Burden:Fleet operators must validate connected platforms against evolving NHTSA and Transport Canada cybersecurity guidelines, extending procurement cycles and technical due diligence requirements.
- Data Science Talent Scarcity:Extracting actionable intelligence from telematics streams requires specialized analytics capabilities that mid-sized fleet operators struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Vehicle Telematics Market |
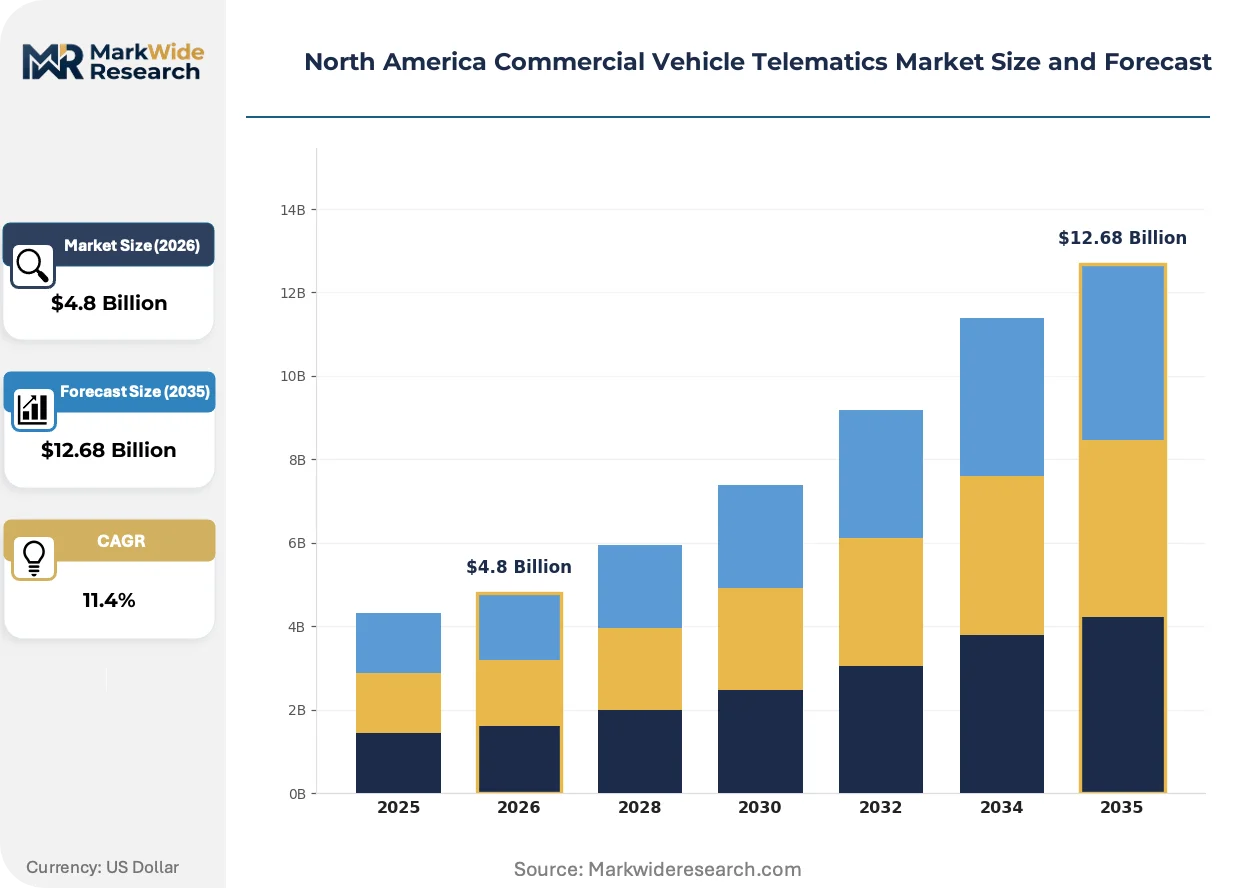
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Driver Behavior Monitoring, Route Optimization, Vehicle Tracking Technology: GPS, Cellular, Bluetooth, Wi-Fi End User: Logistics Companies, Transportation Providers, Delivery Services, Public Sector Application: Fleet Tracking, Maintenance Management, Asset Management, Safety Compliance |
| Companies Covered | Trimble Inc., Omnitracs LLC, Geotab Inc., Zonar Systems Inc., Lytx Inc., Verizon Connect Inc., Solera Holdings LLC, Platform Science Inc., Samsara Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Vehicle Telematics Market Evolving Landscape
Software-defined vehicle architectures are displacing hardware-centric telematics platforms, compressing upgrade cycles and enabling over-the-air feature deployment without physical device replacement.
Edge computing capabilities embedded within onboard telematics units are consolidating real-time processing of engine diagnostics, driver fatigue detection, and cargo monitoring that previously required cloud round-trips. Long-haul trucking fleets operating Texas-Ontario corridors are deploying these systems to maintain functionality through cellular dead zones. The shift is consolidating vendor relationships as fleets prioritize single-platform providers over multi-vendor integration.
The US Department of Transportation's forthcoming automatic emergency braking mandate for heavy trucks is embedding telematics into safety-critical control systems rather than auxiliary monitoring functions. This regulatory trajectory elevates hardware reliability standards and accelerates convergence between fleet management platforms and advanced driver-assistance systems. Canadian fleets seeking US operating authority must synchronize compliance with both NHTSA safety mandates and CCMTA hours-of-service harmonization.
Subscription-based platform access is displacing perpetual license purchases as the dominant commercial model among mid-sized fleet operators. Third-party logistics providers and last-mile delivery services in urban California markets are driving this transition, preferring operational expenditure treatment and bundled software updates. The shift compresses upfront revenue recognition for suppliers while extending customer lifetime value horizons through recurring service attachments.
North America Commercial Vehicle Telematics Market Segmentation
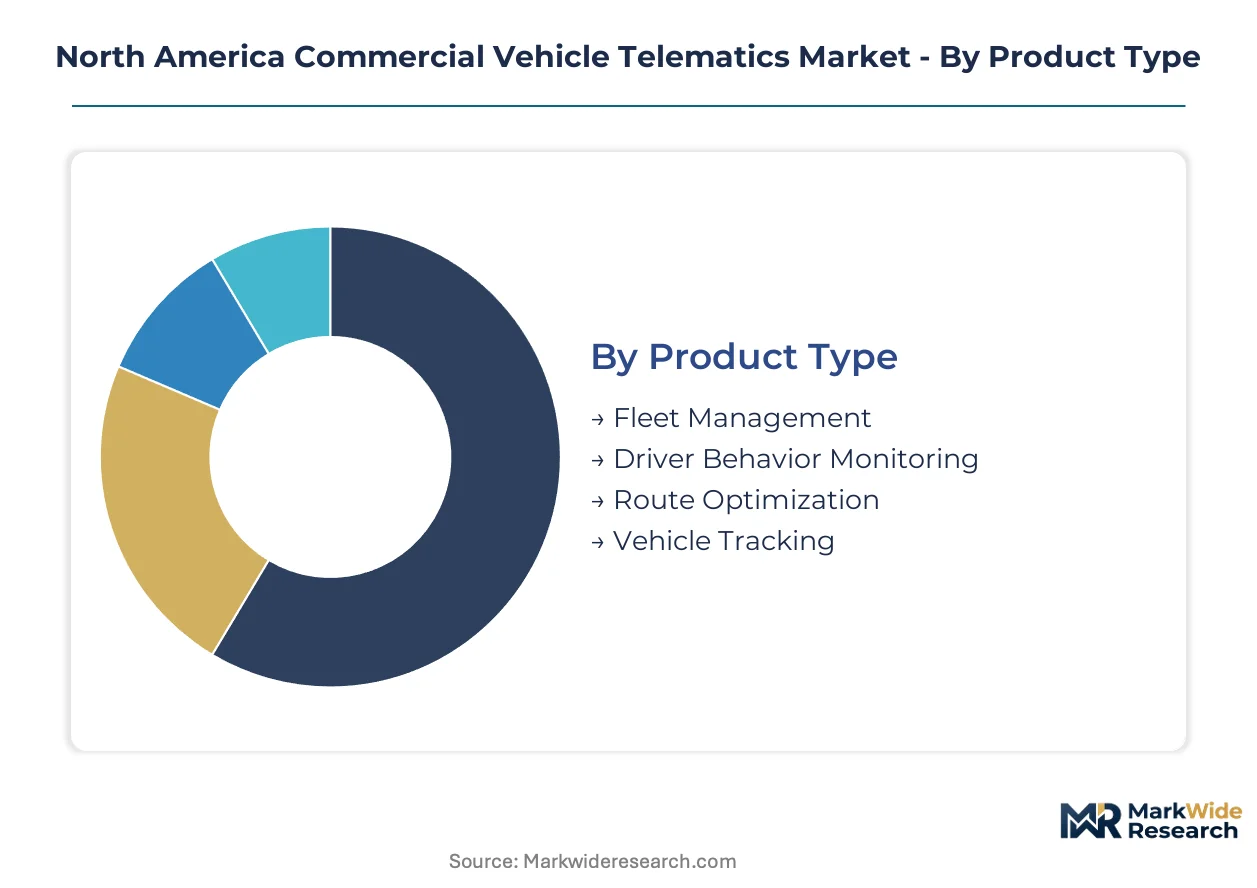
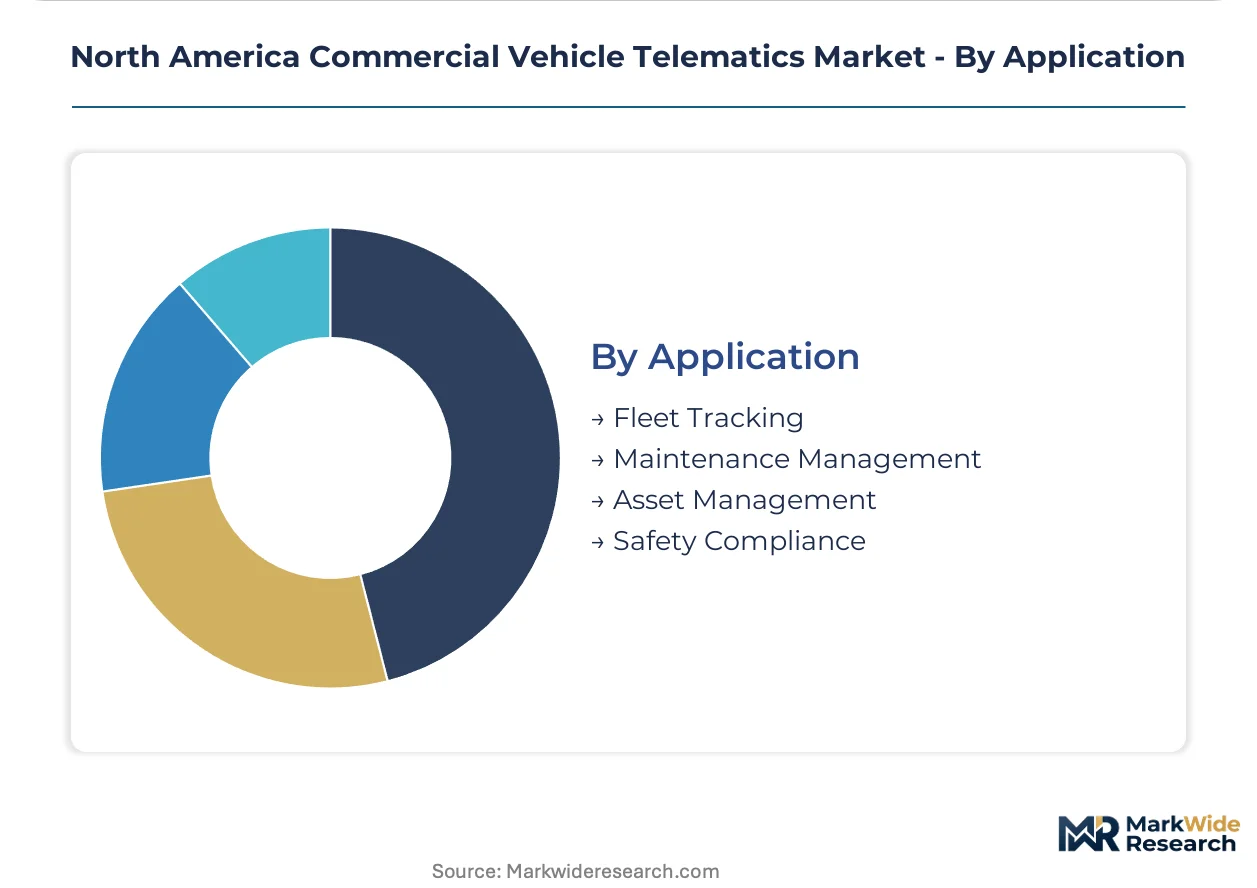
Telematics purchasing decisions across the United States and Canada diverge sharply by operational scale and regulatory exposure. Fleet operators prioritize platforms that consolidate compliance, fuel optimization, and safety monitoring into unified architectures rather than point solutions.
Product Type:
Fleet size and cross-border operational complexity determine platform selection, with large carriers demanding integrated suites while smaller operators accept modular deployments.
- Fleet Management:Unified command centers consolidate dispatch, fuel optimization, hours-of-service compliance, and maintenance scheduling into single-dashboard architectures. Long-haul trucking fleets operating Ontario-Michigan-Texas corridors anchor demand as they harmonize Canadian Council of Motor Transport Administrators and FMCSA record-keeping requirements.
- Driver Behavior Monitoring:Accelerometer, gyroscope, and cabin camera data streams feed insurance-aligned risk scoring algorithms that reduce premium burdens for safety-conscious carriers. Usage-based insurance partnerships in California and Texas are accelerating adoption among mid-sized fleets seeking competitive premium reduction pathways.
- Route Optimization:Urban congestion penalty avoidance and last-mile delivery density algorithms command premium pricing from metropolitan logistics providers.
- Vehicle Tracking:Mature GPS positioning systems dominate oilfield services and construction equipment leasing where asset recovery trumps operational analytics.
Fleet Management leads on scale; Driver Behavior Monitoring leads on momentum.
Technology:
Connectivity modality selection balances coverage reliability against hardware cost and power consumption constraints.
- GPS:Satellite positioning remains foundational for location services across all fleet categories, with multi-constellation receivers (GPS, GLONASS, Galileo) becoming standard for cross-border accuracy.
- Cellular:4G LTE chipset economies have compressed deployment barriers for mid-sized operators previously priced out of connected platforms. Major carrier network sunsetting of 3G infrastructure is forcing premature hardware refresh cycles.
- Bluetooth:Short-range protocols enable low-cost peripheral integration—tire pressure monitors, refrigerated trailer sensors, and driver wearable devices—without cellular data charges.
- Wi-Fi:High-bandwidth local connectivity supports bulk data offload at depot facilities, reducing satellite backhaul costs for video-heavy driver monitoring systems.
Cellular dominates installed base; Bluetooth is expanding most quickly through peripheral ecosystem growth.
End User:
Operational model and cargo type shape telematics requirements more than fleet size alone.
- Logistics Companies:Third-party freight brokers and dedicated contract carriers demand API-rich platforms that integrate shipper visibility requirements with carrier compliance systems. Cross-border consolidation between Ontario and Texas drives harmonized platform investments.
- Transportation Providers:Passenger bus and motorcoach operators prioritize driver fatigue detection and hours-of-service enforcement to satisfy FMCSA and Transport Canada safety mandates.
- Delivery Services:Last-mile urban operators face municipal congestion pricing and curfew restrictions that require dynamic rerouting capabilities.
- Public Sector:Municipal fleet managers emphasize procurement transparency and cybersecurity certification against evolving NHTSA guidelines.
Logistics Companies anchor revenue concentration; Delivery Services show steepest expansion trajectory.
Application:
Functional priority sequencing determines module configuration and data pipeline architecture.
- Fleet Tracking:Real-time position reporting satisfies shipper visibility contracts and supports theft recovery. Oilfield services in Texas and Alberta deploy hardened units for remote asset monitoring.
- Maintenance Management:Engine diagnostic code streaming and predictive failure algorithms reduce unplanned downtime for high-utilization long-haul tractors.
- Asset Management:Non-powered equipment tracking—trailers, containers, yellow iron—extends telematics value beyond motive assets.
- Safety Compliance:ELD mandate enforcement and forthcoming automatic emergency braking integration embed telematics into safety-critical vehicle control systems.
Fleet Tracking holds largest deployment base; Safety Compliance is gaining share fastest through regulatory embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between US and Canadian compliance costs is redistributing fleet operator investments across North American corridors. The FMCSA's electronic logging device enforcement and Transport Canada's harmonized hours-of-service rules create divergent cost structures that shape platform procurement decisions.
United States
Long-haul trucking fleets operating Texas-to-Michigan corridors drive concentrated demand for cross-border compliance platforms. The FMCSA's forthcoming automatic emergency braking mandate for heavy trucks elevates telematics integration into safety-critical vehicle systems. Dallas-Fort Worth and Detroit anchor hardware deployment clusters where fleet operators consolidate dispatch and fuel optimization systems.
Canada
Ontario-based logistics providers harmonize record-keeping with US counterparts through integrated fleet management architectures. The Canadian Council of Motor Transport Administrators maintains hours-of-service alignment with FMCSA rules to facilitate cross-border freight fluidity. The Windsor-Quebec City corridor concentrates telematics module distribution serving Ontario's manufacturing supply chain.
California
The state's Advanced Clean Trucks regulation compels zero-emission fleet transitions requiring battery state-of-health monitoring integration. Municipal congestion pricing in Los Angeles and San Francisco accelerates dynamic rerouting capability investments among last-mile delivery operators. Sacramento's regulatory framework shapes national compliance technology trajectories through early mandate adoption.
Texas
Oilfield services and energy logistics operators deploy hardened asset tracking systems across Permian Basin operations. The state's minimal regulatory overlay on intrastate trucking attracts fleet operators seeking operational flexibility. Houston's petrochemical corridor generates specialized demand for hazardous materials cargo monitoring integrated with legacy fleet platforms.
Mexico
Cross-border manufacturing supply chains linking Nuevo León and Texas create demand for harmonized visibility platforms. The Secretariat of Communications and Transportation's gradual electronic logging device alignment with US standards shapes procurement timelines. Monterrey's industrial cluster anchors telematics deployment serving automotive and electronics freight corridors.
North America Commercial Vehicle Telematics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined platform specialization and insurance-aligned risk analytics. The vendor base concentrates around three distinct maturity tiers: legacy hardware manufacturers defending installed base, cloud-native challengers capturing mid-sized fleet share, and telecommunication carriers leveraging network infrastructure. Strategic archetypes include precision-positioning heritage players, open-platform ecosystem builders, and regulatory compliance engine specialists. Dominant competitive moves encompass vertical integration into cellular module supply and strategic partnerships with usage-based insurance underwriters.
Within the precision-positioning tier, Trimble Inc. exemplifies heritage technology translation from agricultural automation into construction and mixed fleet verticals. Omnitracs LLC anchors the regulatory compliance specialist archetype through long-haul trucking workflow applications. Geotab Inc. occupies the open-platform ecosystem position, enabling third-party developer access atop its device architecture.
| Leading Market Players |
|---|
| Trimble Inc. |
| Omnitracs LLC |
| Geotab Inc. |
| Zonar Systems Inc. |
| Lytx Inc. |
| Verizon Connect Inc. |
| Solera Holdings LLC |
| Platform Science Inc. |
| Samsara Inc. |
| Others |
Value Network & Pricing Analysis
Captive cellular module production by Asian foundries anchors both hardware cost structures and supplier pricing power across North American telematics deployment. This integration pattern concentrates component sourcing in concentrated manufacturing zones while fleet operators face compressed negotiation leverage on device procurement.
Pricing Analysis
Distributor margins on cellular-enabled hardware modules range from 15 to 25 percent before fleet management platform fees. Subscription-based SaaS tiers dominate revenue recognition, with pricing stratifying across enterprise, mid-market, and small fleet levels based on vehicle count and API access depth. Cost compression in 4G LTE chipsets is intensifying because carrier economies of scale and satellite backhaul competition are driving hardware commoditization. Small fleet operators exhibit highest price sensitivity, while enterprise carriers prioritize platform interoperability over per-unit cost.
Supply Chain Analysis
Refurbishment flows for sunsetting 3G hardware are creating secondary market circulation as carriers forced into premature upgrade cycles seek residual value recovery. Telematics control unit production draws from concentrated foundry capacity in Taiwan, South Korea, and mainland China. Semiconductor wafer supply, cellular baseband processors, and GPS receiver chipsets constitute critical input dependencies. Single-source vulnerability around advanced node fabrication exposes North American module assemblers to allocation rationing during demand surges. Distribution runs through direct OEM partnerships and specialized fleet technology distributors serving regional carrier clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Commercial Vehicle Telematics Market functions as a regulatory compounder where FMCSA mandate enforcement and forthcoming automatic emergency braking requirements continuously expand addressable platform penetration.
For Market Incumbents: To counter open-platform challengers eroding proprietary data protocol lock-in, incumbents should deepen API ecosystem investments that embed third-party developers while pursuing backward integration into cellular module supply to secure allocation priority during semiconductor constraints. For New Entrants and Emerging Players: Insurance brokerage partnerships offer the most penetrable channel for usage-based risk analytics, particularly among mid-sized California and Texas fleets seeking premium reduction pathways through driver behavior data sharing. For Investors and Strategic Acquirers: Roll-up economics work for construction equipment telematics specialists because asset-heavy verticals remain underpenetrated relative to over-the-road trucking saturation. Platform consolidation targets should demonstrate battery state-of-health monitoring capabilities aligned with zero-emission fleet transitions. The signal to watch is California Advanced Clean Trucks compliance timeline acceleration as an inflection indicator for electrification-related feature demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Migration | Over-the-air feature deployment reduces hardware refresh cycles and extends customer lifetime value for fleet operators. |
| Usage-Based Insurance Partnership | Driver behavior data monetization opens recurring revenue streams beyond core fleet management subscriptions. |
| Cross-Border Compliance Harmonization | Integrated FMCSA and CCMTA record-keeping platforms capture Ontario-Michigan-Texas corridor freight volumes. |
| Edge Computing Module Integration | Real-time processing in cellular dead zones differentiates platforms for long-haul routes through remote territories. |
| Cybersecurity Certification Investment | NHTSA guideline validation accelerates procurement cycles among municipal and public sector fleet operators. |
Research Methodology
Coverage spans the United States, Canada, and cross-border freight corridors, with primary inputs from each jurisdiction combined with secondary validation. Fleet operations directors, telematics platform product managers, cellular module procurement leads, and insurance underwriting specialists contributed structured interviews. Secondary sources include FMCSA regulatory filings, Transport Canada safety bulletins, carrier equipment procurement databases, and cellular carrier network deployment disclosures. Bottom-up vehicle installation estimates and top-down fleet technology spending analysis were triangulated to derive market sizing.
Rate-of-change decomposition across the analysis window separates hardware unit growth from software attach rate expansion and services revenue per vehicle. Segmentation dimensions modeled include fleet size tier, connectivity modality, application function, and end-user operational model. CAGRs were derived from logistic diffusion curves fitted to regulatory mandate compliance deadlines and technology replacement cycles. Forecast inputs incorporate cellular network sunsetting schedules and zero-emission fleet transition timelines by state and province.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply allocation volatility and cybersecurity guideline evolution. Forecasts reflect documented assumptions around regulatory enforcement intensity and carrier capital expenditure cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Edge Computing in Automotive Market