
 Europe Automotive Infotainment Systems Market | 2026-2036
Europe Automotive Infotainment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Infotainment Systems Market Insights
High-definition display interface upgrades is unwinding legacy cabin electronics architectures across European assembly lines. Continental AG leverages captive semiconductor sourcing to secure OLED panel allocations for premium cockpit programs. Robert Bosch GmbH sustains R&D intensity across its Stuttgart engineering centers for haptic feedback integration. Harman International anchors aftermarket revenue through modular audio retrofit kits sold via certified installer networks.
Europe automotive infotainment systems encompass embedded computing platforms, connectivity modules, and human-machine interface hardware that process navigation, entertainment, and vehicle status data through CAN bus integration and over-the-air update protocols. These systems serve the primary commercial purpose of differentiating vehicle cabin experience while reducing driver distraction through consolidated touchscreen and voice control architectures. Embedded Systems command the dominant margin pool as OEMs specify fixed hardware-software pairings for model lifecycle stability, while Connectivity Modules represent the fastest-expanding segment as 5G-V2X integration becomes standard in electric vehicle platforms. Display Interfaces retain mature growth trajectories in mass-market passenger cars where cost engineering limits pixel density advances.
The EU AI Act imposes algorithmic transparency mandates on voice recognition and driver monitoring subsystems, forcing suppliers to revalidate machine learning components for high-risk classification. CE marking under the Radio Equipment Directive governs Bluetooth and navigation transmission hardware, while ECHA REACH compliance restricts hazardous substance content in display backplanes and circuit assemblies. Stakeholders must monitor whether the European Commission extends cybersecurity certification requirements to aftermarket infotainment retrofit products.
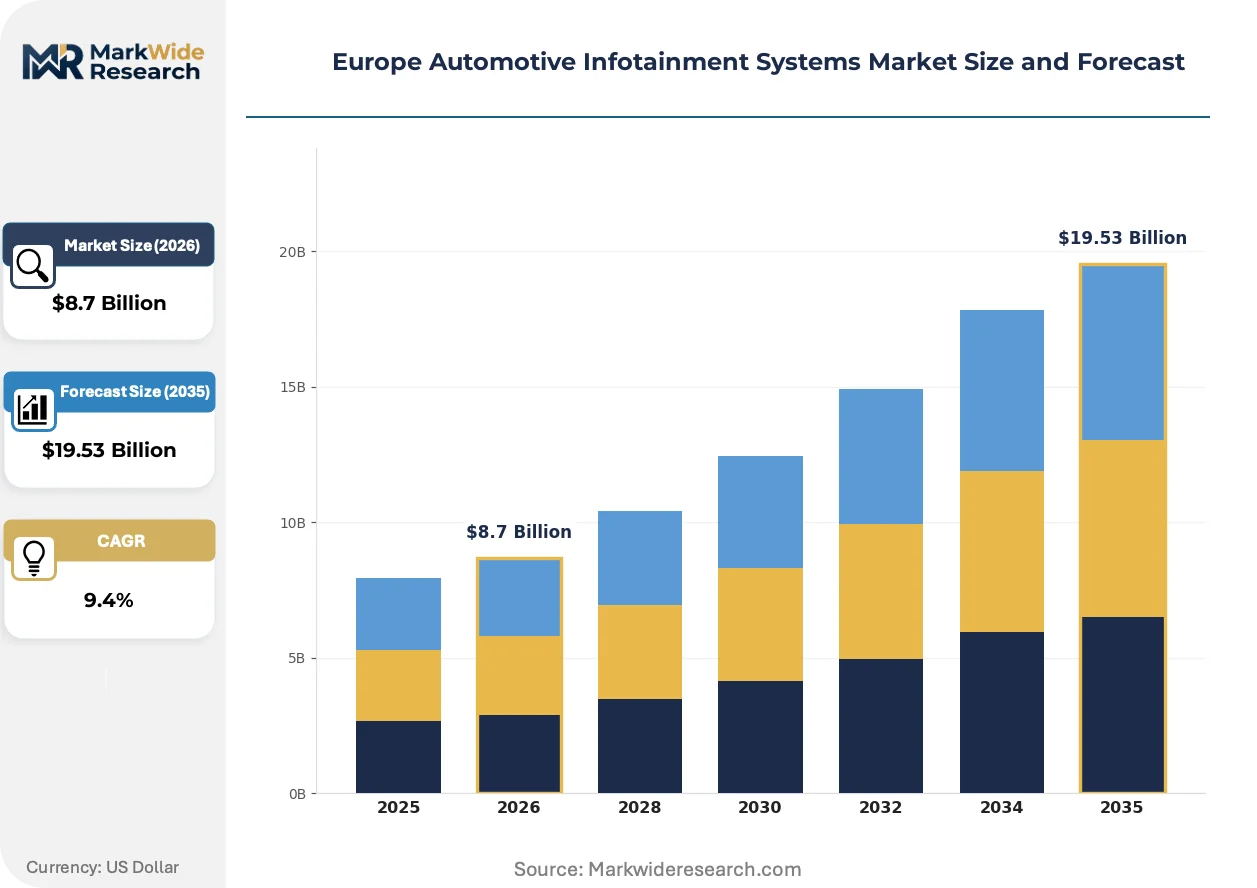
Market Dynamics
EU AI Act compliance deadlines are compressing supplier certification cycles for voice recognition and driver monitoring subsystems, forcing parallel revalidation of machine learning pipelines before 2026 model year launches.
Growth Catalysts
- GDPR-mandated data localization:OEMs are specifying edge-computing architectures that process biometric driver data within vehicle domains, expanding orders for high-performance embedded controllers.
- 5G-V2X module integration:Electric vehicle platforms across Germany and France are standardizing cellular vehicle-to-everything connectivity, pulling demand for combined telematics-infotainment head units.
- Cockpit digitization programs:Stuttgart and Munich-based manufacturers are consolidating instrument clusters and center-stack displays into unified OLED surfaces, accelerating display interface procurement.
Market Restraints
- Semiconductor allocation constraints:Foundry capacity for automotive-grade system-on-chips remains concentrated among Taiwan-based suppliers, creating order backlogs for European Tier-1 integrators.
- CE marking complexity under RED:Bluetooth and Wi-Fi hardware modules require renewed Radio Equipment Directive certification for each software revision, extending product launch timelines.
- Legacy CAN bus architecture persistence:Mass-market vehicle programs retain 500 kbps controller area network backbones that throttle bandwidth for 4K video streaming and real-time navigation rendering.
Strategic Opportunities
- Poland and Czechia manufacturing expansion:Lower-cost assembly locations within EU regulatory perimeter offer margin relief for connectivity module production serving central European OEM plants.
- ECHA REACH substitution incentives:Restrictions on cadmium and lead in display backplanes are accelerating adoption of indium phosphide quantum dot alternatives with premium positioning potential.
- Over-the-air update monetization:Subscription-enabled feature activation for navigation maps and audio streaming creates recurring revenue streams from hardware already deployed in vehicle fleets.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for driver monitoring cameras remains concentrated among German and Swedish engineering consultancies, inflating project staffing costs.
- Multi-domain integration complexity:Consolidating infotainment, advanced driver assistance, and body electronics onto zonal compute architectures demands renegotiated supplier interfaces and liability frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Infotainment Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Connectivity Modules, Display Interfaces, Audio Systems Technology: Bluetooth, Android Auto, Apple CarPlay, Navigation Systems End User: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Cars Installation Type: OEM Installations, Aftermarket Solutions, Integrated Systems, Standalone Units |
| Companies Covered | Continental AG, Robert Bosch GmbH, Harman International, Visteon Corporation, Panasonic Automotive Systems, Alpine Electronics, Denso Corporation, AISIN Corporation, Aptiv PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Infotainment Systems Market Trends and Innovations
Generative AI inference at the edge is redefining voice assistant capabilities, while regulatory pressure on algorithmic transparency forces architectural choices that prioritize explainability over raw performance.
Zonal electronic architectures are fragmenting the traditional centralized infotainment domain into distributed compute nodes. Premium German OEMs are migrating cockpit functions to zone controllers mounted at vehicle extremities. This topology is fragmenting supplier hierarchies as display integrators must now certify compatibility with multiple zone gateway providers rather than single head-unit assemblers.
The EU AI Act's high-risk system classification is mandating technical documentation for biometric identification algorithms. Suppliers must maintain version-controlled model cards and training data provenance for driver distraction detection subsystems. Voice recognition modules with emotion inference capabilities face the strictest conformity assessment routes through notified bodies in Germany and France.
Fleet operators and leasing companies are consolidating procurement decisions for embedded connectivity services, displacing individual consumer subscription choices. Large rental groups in Spain and Italy now negotiate pan-European data plans directly with mobile network operators. This concentration is visible most acutely in commercial vehicle segments where total cost of ownership calculations dominate specification meetings.
Europe Automotive Infotainment Systems Market Segmentation
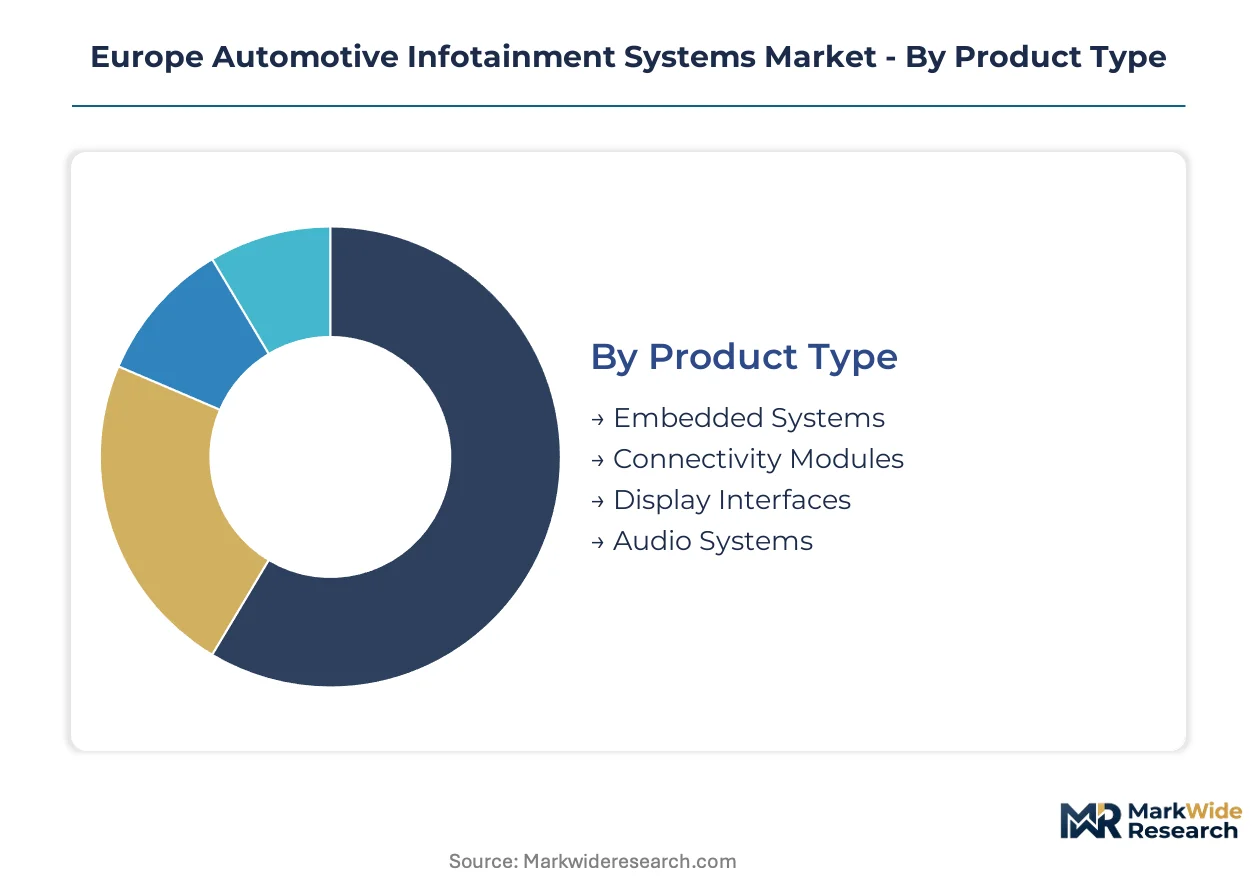
Channel configuration varies sharply across Europe's automotive infotainment landscape. OEM installations dominate premium vehicle programs while aftermarket solutions capture aging fleet retrofits and independent repair networks.
Product Type:
Embedded systems flow through captive OEM supply chains with multi-year program commitments, while connectivity modules and display interfaces split volume across tiered distribution channels serving mass-market and premium segments differently.
- Embedded Systems:Fixed hardware-software pairings specified for full model lifecycles, processing navigation and vehicle status data through integrated CAN bus architectures. German OEMs in Stuttgart and Munich are expanding orders for high-performance controllers to meet GDPR-mandated edge computing requirements. By volume, Embedded Systems leads. By growth pace, Connectivity Modules is ahead.
- Connectivity Modules:5G-V2X and telematics hardware enabling cellular vehicle-to-everything communication. Electric vehicle platforms across France and Germany are standardizing combined telematics-infotainment head units, pulling demand through integrated procurement channels.
- Display Interfaces:Touchscreen and instrument cluster panels spanning LCD to OLED technologies. Cost engineering limits pixel density advances in mass-market passenger cars distributed through high-volume OEM channels.
- Audio Systems:Modular speaker arrays and amplifier hardware. Aftermarket installer networks in Spain and Italy sustain replacement demand for legacy vehicle acoustic upgrades.
Margin concentration follows product complexity, with embedded controllers commanding premium pricing through direct OEM negotiation while display interfaces face commoditization pressure in volume segments.
Technology:
Certification requirements under the EU AI Act and Radio Equipment Directive create divergent cost structures across technology categories, with voice recognition and biometric systems facing stricter conformity assessment than basic connectivity protocols.
- Bluetooth:Short-range wireless protocol for audio streaming and hands-free calling. CE marking under RED governs each software revision, extending launch timelines for hardware modules distributed through both OEM and aftermarket channels.
- Android Auto:Google's smartphone projection standard integrating mobile apps with vehicle displays. Mass-market OEMs across Czechia and Poland specify this protocol to reduce embedded software development costs.
- Apple CarPlay:Apple's equivalent projection ecosystem commanding higher specification rates in premium segments. Luxury manufacturers in the United Kingdom maintain exclusive CarPlay integration for differentiation.
- Navigation Systems:GPS and GLONASS-based positioning with real-time traffic processing. Over-the-air update monetization is creating recurring revenue streams from hardware already deployed across European fleets.
Adoption velocity separates the technologies, with smartphone projection standards expanding most quickly while standalone navigation faces displacement from mobile device integration.
End User:
Vehicle electrification intensity determines specification sophistication, with electric platforms mandating integrated connectivity architectures that combustion programs address through modular add-ons.
- Passenger Cars:Mass-market hatchbacks and sedans representing volume demand concentration. Cockpit digitization programs at Stuttgart-based manufacturers are consolidating instrument clusters and center-stack displays into unified surfaces.
- Commercial Vehicles:Fleet-operated vans and trucks where total cost of ownership dominates procurement. Large rental groups in Spain and Italy negotiate pan-European data plans directly with mobile network operators, displacing individual subscription choices.
- Electric Vehicles:Battery-electric platforms requiring native connectivity for charging infrastructure integration and battery management telemetry. 5G-V2X module integration is standardizing across German and French electric vehicle architectures.
- Luxury Cars:Premium segments specifying highest pixel density displays and haptic feedback integration. Robert Bosch GmbH sustains R&D intensity across Stuttgart engineering centers for advanced interface hardware serving this category.
Specification intensity inverts against volume, with luxury cars driving technology insertion that subsequently cascades to mass-market programs after cost engineering.
Installation Type:
Channel structure fragments between captive OEM supply chains with multi-year visibility and aftermarket networks serving fragmented demand through certified installer relationships.
- OEM Installations:Factory-integrated systems specified during vehicle development programs. Continental AG leverages captive semiconductor sourcing to secure OLED panel allocations for premium cockpit programs through direct OEM relationships.
- Aftermarket Solutions:Retrofit hardware sold through independent installer networks. Harman International anchors revenue through modular audio retrofit kits distributed via certified channels in Italy and Spain.
- Integrated Systems:Combined infotainment-ADAS-body electronics architectures on zonal compute platforms. Multi-domain integration complexity demands renegotiated supplier interfaces and liability frameworks.
- Standalone Units:Discrete head-unit replacements for legacy vehicles. CE marking complexity under RED extends product launch timelines for each software revision in this channel.
Channel mix is shifting toward integrated architectures as zonal electronics consolidate previously separate domains, compressing standalone unit addressable market scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial trade surplus in automotive infotainment components, exporting embedded controllers and display modules to assembly plants across Eastern Europe and North Africa. Import dependency concentrates in Taiwan-sourced semiconductors and South Korean OLED substrates, creating currency exposure for Euro-denominated procurement teams.
Germany
Stuttgart and Munich OEMs are consolidating cockpit electronics into unified OLED surfaces, pulling demand for high-performance embedded controllers. KBA vehicle type approval mandates cybersecurity documentation for connected infotainment systems before market entry. Bavarian engineering clusters around Ingolstadt and Munich sustain ISO 26262 ASIL-D certification expertise for driver monitoring cameras.
France
Paris-based fleet operators negotiate pan-European connectivity data plans directly with mobile network operators, displacing individual consumer subscriptions. ANSM algorithmic transparency guidelines intersect with EU AI Act implementation for biometric driver monitoring systems. The Île-de-France region hosts validation laboratories for CE marking under the Radio Equipment Directive.
United Kingdom
Luxury manufacturers maintain exclusive smartphone projection integration as a cabin experience differentiator against German competitors. The Information Commissioner's Office enforces GDPR biometric data processing limits on voice recognition subsystems. Midlands automotive clusters around Birmingham and Coventry supply wiring harnesses and assembly services for continental OEM programs.
Italy
Aftermarket installer networks in Turin and Milan sustain modular audio retrofit demand for aging vehicle fleets. ECHA REACH compliance deadlines accelerate substitution of cadmium-containing display backplanes in components sourced from Asian suppliers. Emilia-Romagna manufacturing corridors near Modena produce premium acoustic components for luxury vehicle programs.
Spain
Large rental groups in Madrid and Barcelona consolidate embedded connectivity procurement across multi-thousand vehicle fleets. Spanish data protection authority guidance reinforces GDPR edge-computing requirements for biometric data localization. Catalan electronics assembly plants serve French and German OEM demand for mid-market connectivity modules.
Europe Automotive Infotainment Systems Market Competitive Landscape
Concentration sits with diversified automotive Tier-1 suppliers possessing captive semiconductor sourcing relationships and direct OEM program access. The vendor base stratifies across three archetypes: integrated cockpit electronics specialists, modular audio retrofit providers, and connectivity module fabricators. Dominant competitive moves include backward integration into display panel supply chains and strategic partnerships with foundry operators for automotive-grade chip allocation security.
Within the integrated cockpit tier, Continental AG and Robert Bosch GmbH exemplify diversified German engineering conglomerates with captive supply relationships securing component allocations. Harman International occupies a position representing modular audio specialists serving aftermarket channels through certified installer networks. Visteon Corporation anchors the display interface segment among US-origin Tier-1 suppliers with European engineering presence.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Harman International |
| Visteon Corporation |
| Panasonic Automotive Systems |
| Alpine Electronics |
| Denso Corporation |
| AISIN Corporation |
| Aptiv PLC |
| Others |
Pricing and Supply Chain Analysis
Indium phosphide quantum dot substitution for cadmium-based display backplanes simultaneously shifts procurement geography toward South Korean substrate suppliers and compresses margin structures for European Tier-1 integrators facing ECHA REACH compliance deadlines. This materials transition concentrates pricing power among OLED panel fabricators while fragmenting cost engineering options for mass-market display interfaces.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for embedded controllers, with price differentiation driven by ISO 26262 ASIL-D certification grade and volume scale. Premium cockpit programs command substantial brand premiums through direct Stuttgart and Munich OEM negotiations, while aftermarket connectivity modules face price erosion from CE marking complexity under RED extending launch timelines. Fleet operators in Spain and Italy exhibit highest price sensitivity through consolidated pan-European data plan negotiations, whereas luxury manufacturers demonstrate lowest sensitivity for haptic feedback integration.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites logistics risk for Taiwan-sourced automotive-grade system-on-chips feeding German assembly plants. Supply concentration centers on Taiwan, South Korea, and Japan for semiconductors and OLED substrates, with raw material dependencies spanning indium phosphide quantum dots, gallium nitride wafers, and rare earth magnet components for haptic actuators. Single-source vulnerability concentrates in foundry capacity for 5G-V2X baseband processors. Distribution runs through captive OEM supply chains with multi-year program commitments, supplemented by certified installer networks for aftermarket audio retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across zonal electronic architectures creates niche opportunities as cockpit digitization displaces traditional head-unit hierarchies. The shift toward distributed compute nodes enables specialist suppliers to capture zone controller integration roles previously consolidated under Tier-1 assemblers.
For Market Incumbents: Consolidate backward integration into display panel supply chains to secure OLED allocations against South Korean substrate concentration, while expanding captive semiconductor sourcing relationships to mitigate Taiwan foundry bottlenecks. Prioritize ISO 26262 ASIL-D certification investment for driver monitoring cameras to defend margin position against emerging modular retrofit providers. For New Entrants and Emerging Players: Anchor in aftermarket connectivity module production for aging European fleet retrofits, where CE marking complexity under RED creates barriers for established OEM-integrated suppliers. Target Poland and Czechia manufacturing locations within EU regulatory perimeter for margin relief on central European OEM plant supply. Pursue certified installer network partnerships in Italy and Spain as primary go-to-market channel. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive semiconductor relationships and direct OEM program access. Long-term viability across the projection horizon hinges on regulatory compliance capabilities under EU AI Act and GDPR frameworks. Monitor KBA cybersecurity documentation mandates as inflection indicator for connected system certification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated cockpit architectures reduce supplier count for Stuttgart-based OEM digitization programs. |
| Battery Supply Agreement | Electric vehicle platforms mandate native connectivity integration for charging infrastructure telemetry. |
| Software-Defined Vehicle Investment | Over-the-air update monetization creates recurring revenue from deployed European fleet hardware. |
| Geographic Manufacturing Footprint | Polish and Czech assembly locations offer margin relief within EU regulatory perimeter. |
| Charging Infrastructure Partnership | 5G-V2X module standardization pulls demand for combined telematics-infotainment head units. |
Research Methodology
Cross-validation between Tier 1 supplier procurement leads and OEM platform engineering directors anchors the qualitative findings, supplemented by aftermarket distributor interviews and dealership operations feedback. Secondary validation draws from vehicle production databases, IHS Markit registration data, KBA type approval filings, and ECHA REACH substance restriction notifications. Bottom-up segment sizing triangulates against top-down European automotive electronics spend estimates.
Sensitivity analysis across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions shapes the analytical framework. CAGRs derive from modeled adoption curves for 5G-V2X integration and cockpit digitization intensity, incorporating electric vehicle platform standardization timelines and GDPR edge-computing hardware specifications. Forecast inputs include semiconductor allocation constraints from Taiwan foundry disclosures and OLED substrate supply commitments from South Korean panel manufacturers.
Underlying assumptions cover regulatory compliance timelines, with deviation risk concentrated in EU AI Act implementation pacing and CE marking backlog durations. Practitioners should keep alternative scenarios live as ECHA REACH substitution deadlines and cybersecurity certification extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Edge Computing in Automotive Market