
 Automotive Exhaust Headers Market | 2026-2036
Automotive Exhaust Headers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Headers Market Outlook
Mexico is narrowing its role as a near-shore manufacturing base for tubular exhaust components serving North American aftermarket distributors. Holley Performance Products leverages vertical integration across carburetion and exhaust categories to control channel access. Borla Performance Industries anchors its position through sustained R&D intensity in mandrel-bent stainless steel fabrication. MagnaFlow competes on acoustic engineering capabilities that extend its brand into complete exhaust system solutions.
Automotive exhaust headers are tubular manifolds that collect exhaust gases from multiple engine cylinders and channel them into a single outlet, typically constructed from 304-grade stainless steel or 409-grade ferritic stainless for thermal fatigue resistance and corrosion protection in high-temperature cycling. Their primary purpose is to reduce backpressure, improve scavenging efficiency, and thereby increase engine power output across RPM ranges. Long tube headers dominate margin pools in the performance segment due to complex bending requirements and premium pricing, while shorty headers sustain volume in direct-replacement applications where installation clearance constraints limit design freedom. Stainless steel as a material category leads value contribution owing to durability warranties and visual appeal in exposed underhood configurations.
EPA emissions certification under Title II of the Clean Air Act shapes product legality for street-driven vehicles, while CARB executive orders determine market access in California and the fourteen states adopting its standards. NHTSA crashworthiness guidelines influence header placement and heat shielding requirements in OEM supply contracts. Stakeholders must monitor regulatory preemption debates between federal and state authorities while calibrating inventory mixes between 50-state legal and off-road-only product lines.
Market Dynamics
EPA emissions enforcement under Title II of the Clean Air Act is compressing the addressable market for street-legal configurations while simultaneously concentrating margin pools in CARB-exempt and off-road-only product lines.
Growth Catalysts
- Muscle car restoration demand:Collector vehicle owners in the United States sustain replacement cycles for long tube headers as motorsport sanctioning bodies mandate periodic exhaust system upgrades.
- Stainless steel thermal fatigue resistance:304-grade and 409-grade ferritic stainless configurations command premium pricing through extended durability warranties in high-temperature cycling applications.
- Mexico near-shore manufacturing expansion:Tubular exhaust component production is migrating to Baja California and Chihuahua to serve North American aftermarket distributors with compressed lead times.
Market Restraints
- Nickel and chromium input volatility:Stainless steel feedstock costs fluctuate with London Metal Exchange pricing, squeezing fabrication margins for mandrel-bent header producers.
- California Air Resources Board preemption:CARB executive orders restricting aftermarket exhaust modifications in fourteen adopting states fragment inventory requirements and complicate nationwide distribution.
- Catalytic converter integration mandates:EPA Tier 3 standards requiring close-coupled catalyst placement limit header design freedom and increase thermal management complexity.
Strategic Opportunities
- Off-road-only product line expansion:Side-by-side and ATV segments in Texas, Arizona, and Utah present uncapped demand for non-certified configurations outside EPA jurisdiction.
- Additive manufacturing convergence:Laser powder bed fusion of Inconel alloys is enabling complex merge collector geometries previously impossible with conventional tube bending.
- Direct-to-installer e-commerce channels:Performance shops and restoration specialists are bypassing traditional warehouse distributors through manufacturer-owned digital platforms.
Industry Challenges
- Mandrel bending technician scarcity:Precision tube fabrication requires specialized craft skills that vocational programs have deprioritized, constraining production scaling for long tube configurations.
- CARB executive order certification timelines:California Air Resources Board approval processes for 50-state legal headers extend eighteen to twenty-four months, delaying revenue recognition for new product introductions.
- Heat shield integration complexity:NHTSA crashworthiness guidelines governing underhood component placement conflict with thermal protection requirements in modern engine bays with reduced clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Headers Market |
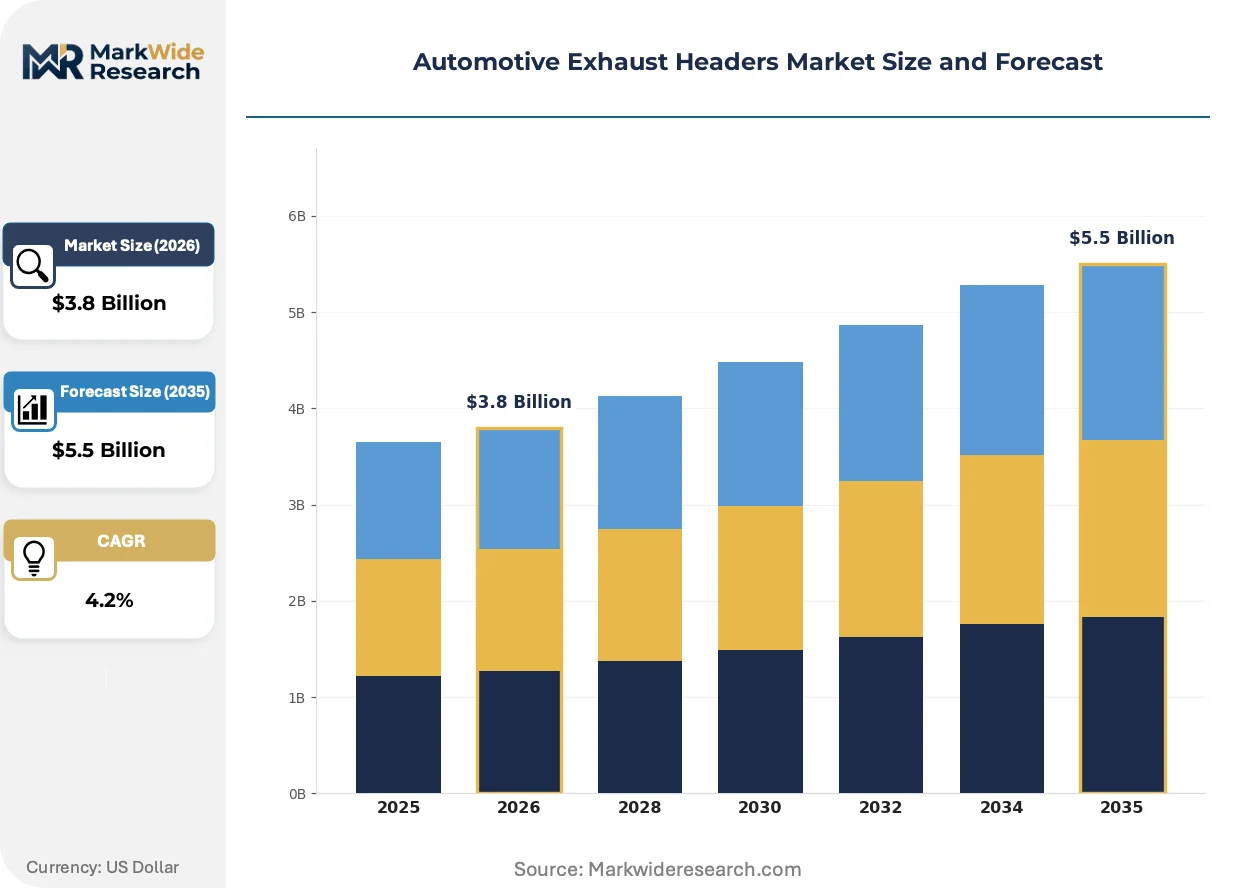
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorty Headers, Long Tube Headers, Turbo Headers, Block Hugger Headers Material: Stainless Steel, Mild Steel, Titanium, Cast Iron Vehicle Type: Passenger Cars, Light Trucks, SUVs, Sports Cars Installation Type: Aftermarket, OEM, Performance Upgrades, Off-Road Applications |
| Companies Covered | Holley Performance Products, Borla Performance Industries, MagnaFlow, Flowmaster, JBA Headers, Doug Thorley Headers, American Racing Headers, Stainless Works, Kooks Headers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Headers Market Strategic Shifts
Computational fluid dynamics is displacing empirical design in header development, compressing prototype iterations while mandrel-bent stainless fabrication and acoustic engineering capabilities are becoming table stakes for competitive positioning.
Digital twin simulation software is virtualizing exhaust scavenging analysis, enabling header manufacturers to model pressure wave propagation and velocity stack tuning before physical prototyping. Performance aftermarket specialists in the United States are adopting these tools at accelerating rates, collapsing development cycles from months to weeks. This capability is virtualizing the traditional cut-and-test methodology that historically dominated header R&D programs.
California Air Resources Board waivers are reshaping product legality frameworks, forcing manufacturers to maintain dual inventory streams for 50-state legal and off-road-only configurations. The industrial consequence is SKU proliferation and working capital intensity for distributors serving multi-state markets. Street-driven vehicle applications in California, New York, and Massachusetts are responding through certified pre-engineered kits that bundle headers with compliant catalytic converters.
Restoration specialists are consolidating procurement through single-source exhaust system suppliers rather than discrete component vendors. The independent speed shop channel is being disrupted by integrated header-muffler-pipe bundle offerings with unified warranty coverage. This pattern is most visible in the United States, where Holley Performance Products and Borla Performance Industries are capturing share through complete system solutions rather than standalone header sales.
Automotive Exhaust Headers Market Segmentation
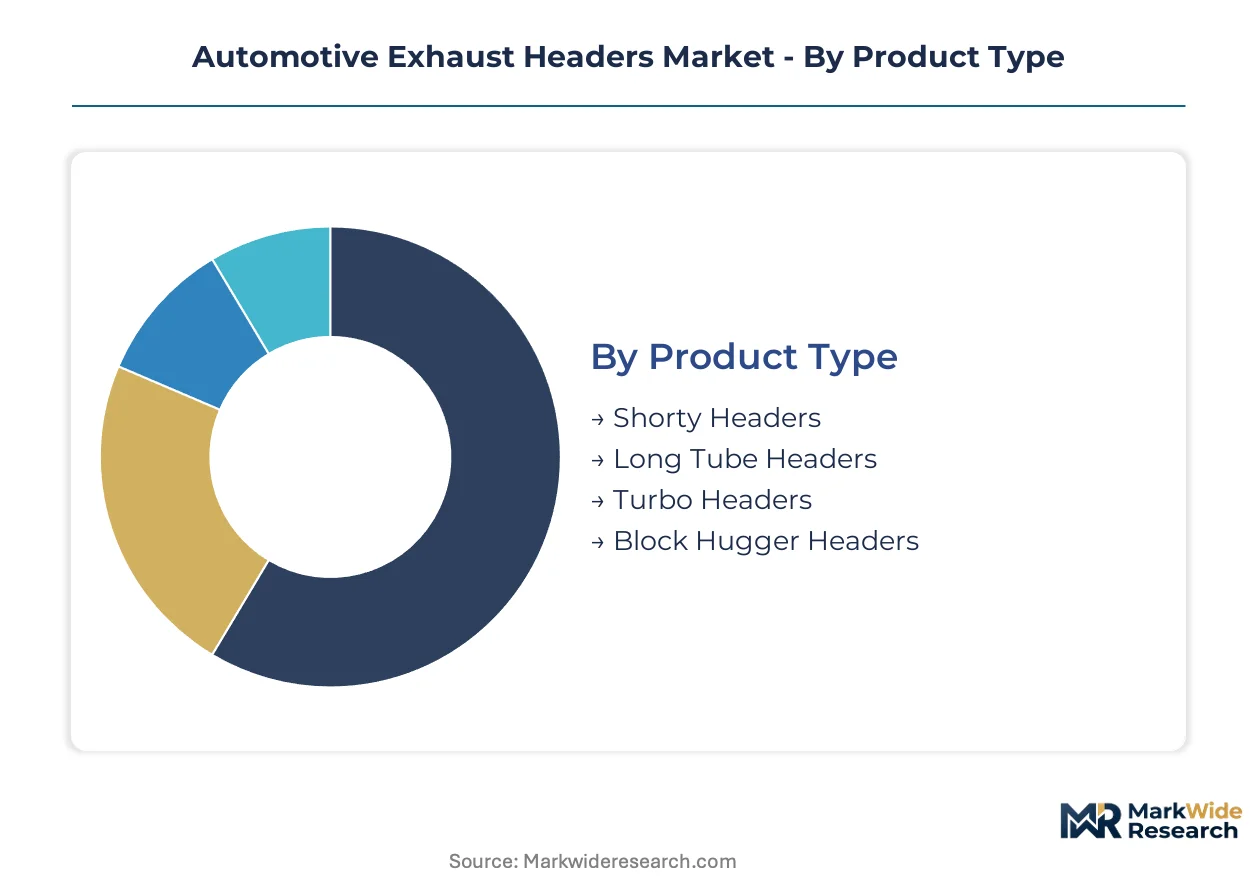
Automotive exhaust headers serve divergent use cases spanning daily-driven street vehicles, competition-only race builds, and collector car restoration. Segmentation reveals how material selection and installation channel determine regulatory exposure, margin structure, and customer procurement behavior across the value chain.
Product Type:
Product configurations span the performance spectrum from clearance-constrained direct replacements to maximum-efficiency racing designs.
- Shorty Headers:Compact designs with minimal primary tube length optimize fitment in modern engine bays with limited clearance. Direct-replacement demand concentrates in light trucks and SUVs where owners seek modest power gains without triggering CARB compliance reviews.
- Long Tube Headers:Extended primary tubes with tuned length-to-diameter ratios maximize scavenging efficiency across broad RPM ranges. Muscle car restoration specialists in the United States sustain replacement cycles as motorsport sanctioning bodies mandate periodic exhaust system upgrades.
- Turbo Headers:Thick-walled stainless configurations withstand extreme thermal cycling from forced induction systems.
- Block Hugger Headers:Ultra-compact designs tuck tightly against engine blocks for chassis swaps and custom builds.
Established volume favors shorty headers; emerging adoption favors long tube configurations in the restoration segment.
Material:
Material selection trades thermal durability against fabrication cost and visual finish requirements.
- Stainless Steel:304-grade austenitic and 409-grade ferritic variants deliver superior corrosion resistance and thermal fatigue performance. Collector vehicle owners in California and the fourteen CARB-adopting states pay premiums for extended warranties on exposed underhood configurations.
- Mild Steel:Lower alloy content reduces raw material costs while ceramic coating extends service life in budget-conscious applications.
- Titanium:Half the density of steel with comparable strength enables weight-critical motorsport applications.
- Cast Iron:OEM legacy designs persist in mass-production vehicles where cost minimization outweighs performance optimization.
Stainless steel commands the premium tier; mild steel retains the replacement volume base.
Vehicle Type:
Vehicle classification determines header design constraints around ground clearance, underhood packaging, and emissions integration.
- Passenger Cars:Compact engine bays and close-coupled catalyst placement limit header design freedom in modern unibody platforms. EPA Tier 3 standards compressing the addressable market for street-legal configurations.
- Light Trucks:Body-on-frame architecture accommodates larger primary tube diameters and merge collector volumes. Texas and Arizona fleets sustain demand for off-road-only configurations outside EPA jurisdiction.
- SUVs:Shared platforms with light trucks drive similar header specifications with additional heat shielding for enclosed cabin proximity.
- Sports Cars:Exposed underhood configurations in mid-engine and front-engine rear-drive platforms prioritize visual finish and weight reduction.
Light trucks anchor current procurement volumes; sports cars are climbing the fastest as track-day participation expands.
Installation Type:
Installation channel determines regulatory compliance burden, warranty responsibility, and customer acquisition economics.
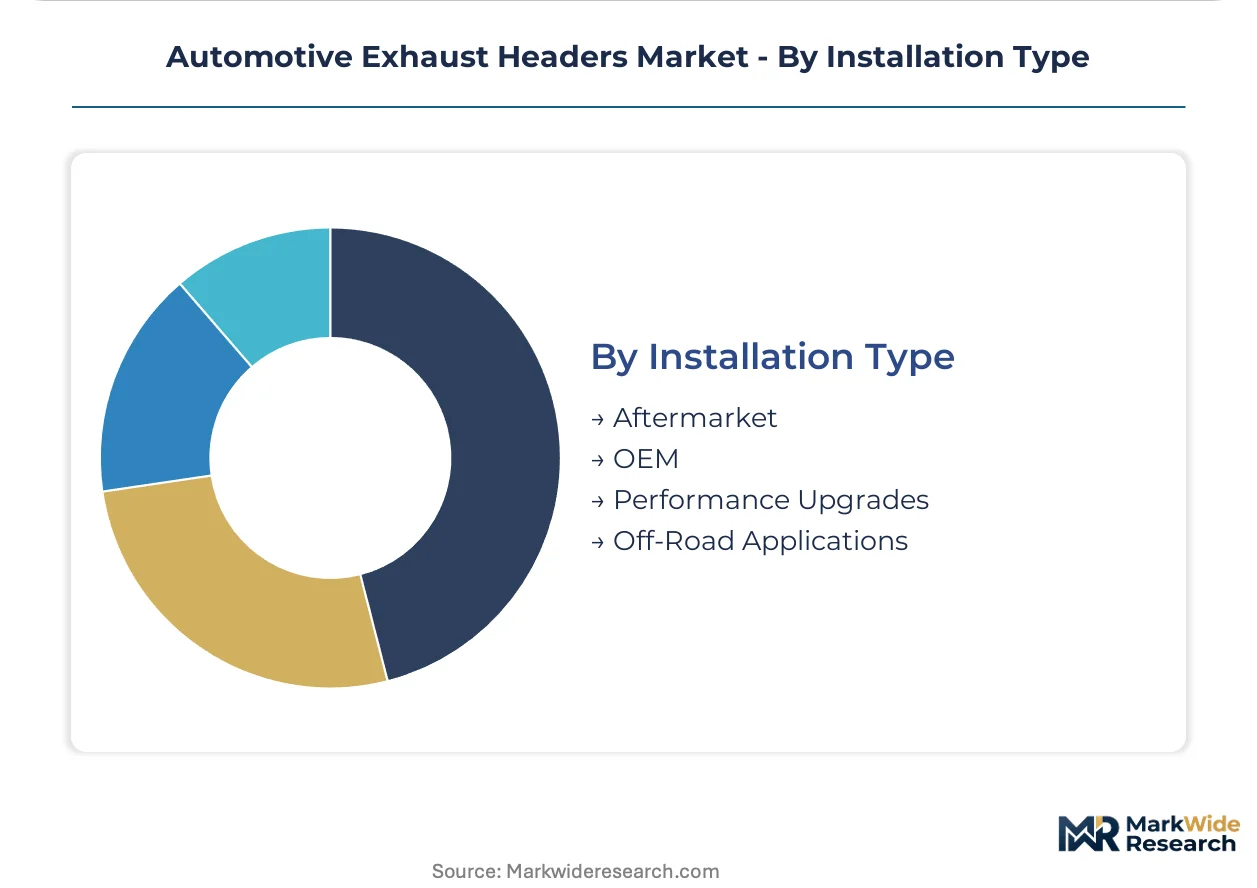
- Aftermarket:Independent speed shops and restoration specialists procure through warehouse distributors or direct manufacturer platforms. CARB executive order certification timelines extending eighteen to twenty-four months delay revenue recognition for new product introductions.
- OEM:Original equipment supply contracts require NHTSA crashworthiness compliance and thermal management integration with vehicle safety systems.
- Performance Upgrades:Bundled header-muffler-pipe offerings with unified warranty coverage disrupt discrete component procurement.
- Off-Road Applications:Side-by-side and ATV segments in Utah and Arizona present uncapped demand for non-certified configurations.
Aftermarket channels dominate value capture; off-road applications are expanding most quickly as EPA enforcement tightens street-legal alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles corridor underwrites North American aftermarket distribution for tubular exhaust components, while Mexico's rail links to Chihuahua and Baja California compress lead times for mandrel-bent fabrication.
United States
Muscle car restoration in Texas and Arizona sustains procurement cycles for long tube headers as off-road vehicle modification escapes EPA jurisdiction. NHTSA crashworthiness guidelines govern heat shielding requirements for street-legal configurations. The Detroit-Toledo corridor concentrates OEM supply relationships with integrated exhaust system producers.
Mexico
Near-shore manufacturing clusters in Baja California and Chihuahua serve North American distributors with compressed lead times for stainless steel tubular components. The country's maquiladora program reduces tariff exposure for cross-border aftermarket parts movement. Monterrey anchors precision tube bending capacity for performance header exports.
Germany
Aftermarket demand concentrates in Bavaria and Baden-Württemberg where motorsport sanctioning bodies mandate periodic exhaust system upgrades for track-day vehicles. KBA type-approval requirements shape product legality for street-driven configurations. Stuttgart's supplier ecosystem integrates acoustic engineering capabilities with mandrel-bent fabrication.
Japan
Kei car and mini-truck modification cultures in Osaka and Nagoya sustain niche demand for compact header configurations. METI industrial standards influence thermal fatigue testing protocols for stainless steel applications. The Kansai region concentrates specialty fabricators serving domestic tuner markets.
Australia
V8 Supercar and street machine cultures in Victoria and Queensland drive replacement cycles for high-performance headers outside OEM supply chains. The country's national automotive regulator enforces emissions compliance for road-registered vehicles. Melbourne's industrial suburbs host independent speed shops consolidating procurement through direct manufacturer platforms.
Automotive Exhaust Headers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three strategic archetypes: vertically integrated performance conglomerates controlling channel access through bundled exhaust solutions, stainless steel fabrication specialists competing on mandrel-bent quality and thermal durability warranties, and acoustic engineering houses extending brand equity into complete system offerings. Dominant competitive moves include backward integration into captive supply of tubular components and geographic expansion through Mexico-based production to compress North American lead times.
Within the integrated platform tier, Holley Performance Products exemplifies the conglomerate archetype spanning carburetion and exhaust categories, while Borla Performance Industries anchors the stainless steel fabrication specialist position. MagnaFlow occupies the acoustic engineering vector, representing the brand-extension model into complete exhaust system solutions. These three players illustrate how competitive positioning stratifies between upstream component supply and downstream system integration in the performance aftermarket.
| Leading Market Players |
|---|
| Holley Performance Products |
| Borla Performance Industries |
| MagnaFlow |
| Flowmaster |
| JBA Headers |
| Doug Thorley Headers |
| American Racing Headers |
| Stainless Works |
| Kooks Headers |
| Others |
Value Chain & Pricing Dynamics
The Port of Long Beach and Los Angeles corridor freight cost dynamics compress margins for stainless steel tubular imports while amplifying price differentiation between CARB-certified and off-road-only header configurations. Supply concentration in Mexican maquiladora zones and domestic mandrel-bending facilities creates tiered procurement economics that downstream distributors pass through as certification-grade pricing spreads.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from single-unit restoration specialist purchases, with long tube headers commanding premium positioning against shorty configurations. Price differentiation rests on CARB executive order certification status and 304-grade stainless thermal warranty coverage, with EPA enforcement tightening cost compression in street-legal tiers. Restoration specialists in Texas and Arizona exhibit lowest price sensitivity due to collector vehicle valuation economics, while budget-conscious daily-driver segments in mass-market channels face acute margin pressure from nickel feedstock volatility.
Supply Chain Analysis
Upstream nickel and chromium feedstock sourcing draws from Indonesian mining operations, Chinese refining capacity, and London Metal Exchange spot markets, creating cost volatility that fabricators hedge through long-term offtake agreements. Geographic supply concentrates in Mexico's Baja California and Chihuahua manufacturing clusters, domestic stainless steel service centers in Ohio and Pennsylvania, and specialized mandrel-bending shops in California. Single-source vulnerability persists in precision tube bending technician labor pools. Distribution runs through warehouse distributors serving independent speed shops, direct-to-installer e-commerce platforms, and OEM supply contracts with integrated exhaust system producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers creates niche capture opportunities as CARB adoption spreads to fourteen states and EPA enforcement bifurcates street-legal from off-road demand pools.
For Market Incumbents: Insulate margin pools by deepening captive supply of mandrel-bent tubular components and accelerating CARB executive order certification pipelines to preempt competitor 50-state legal introductions. Threat substitution from additive manufacturing Inconel merge collectors demands R&D investment in laser powder bed fusion capabilities. Channel control through direct-to-installer digital platforms represents the critical defensive lever against distributor consolidation. For New Entrants and Emerging Players: Pursue uncapped off-road-only segments in side-by-side and ATV applications across Utah, Arizona, and Texas where EPA jurisdiction terminates. The most penetrable white-space sits in turbo header configurations for forced induction restoration builds, where thick-walled stainless thermal cycling specifications command premium positioning. Go-to-market execution through performance shop co-development programs bypasses established warehouse distributor gatekeepers. For Investors and Strategic Acquirers: Acoustic engineering specialists with brand equity extension potential into complete exhaust system solutions present compelling platform consolidation targets. Long-term viability across the analysis window hinges on regulatory arbitrage capabilities between federal and state compliance frameworks. The signal to watch is CARB executive order certification timeline compression or federal preemption litigation that would collapse dual-inventory working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Certification Pipeline Acceleration | Reduces eighteen-to-twenty-four month approval delays that stall new product revenue recognition. |
| Mexico Manufacturing Footprint Expansion | Compresses North American lead times through Baja California and Chihuahua maquiladora capacity. |
| Direct-to-Installer E-Commerce Platform | Bypasses warehouse distributor intermediaries to capture margin and customer relationship data. |
| Additive Manufacturing Capability Buildout | Enables complex Inconel merge collector geometries impossible with conventional mandrel bending. |
| Off-Road-Only Product Line Diversification | Captures uncapped demand in side-by-side and ATV segments outside EPA emissions jurisdiction. |
Study Parameters
A standing panel of aftermarket distributor procurement directors, OEM platform engineers, mandrel-bending shop owners, and restoration specialist shop managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement action databases, CARB executive order registries, NHTSA crashworthiness guideline filings, and stainless steel trade flow customs records. Bottom-up demand modeling from vehicle registration and restoration activity data triangulated against top-down value chain revenue estimates.
Scenario-bracketing around regulatory preemption outcomes and nickel price volatility bands anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include header configuration type, material grade tier, vehicle classification, installation channel, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline demand estimates, with inputs from motorsport sanctioning body rule change schedules and collector vehicle demographic trends.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing, freight rate indices, or trade policy tariffs would shift the trajectory. Cross-checking against IHS Markit vehicle production forecasts and SEMA market sizing studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Automotive Relay Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Automotive Pedals Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Defroster Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Bushing Technologies Market