
 India Automotive Hydraulic Actuators Market | 2026-2036
India Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Hydraulic Actuators Market Foresight
Fleet operators running medium and heavy commercial vehicles is unwinding the historical dominance of passenger car OEMs in hydraulic actuator procurement. Robert Bosch GmbH leverages its brake system integration capabilities to anchor supply relationships with domestic truck manufacturers. Continental AG competes through localized electro-hydraulic module production. Denso Corporation specializes in compact rotary actuators for automated manual transmissions.
India automotive hydraulic actuators are fluid-powered mechanical devices that convert pressurized oil flow into linear or rotational motion, typically operating at system pressures between 150 and 350 bar to control braking, steering, and suspension functions in vehicles. Double acting actuators lead volume uptake in braking and transmission applications due to their bidirectional force output and superior load-holding characteristics. Electro-hydraulic technology is gaining fastest adoption as OEMs integrate electronic control units with hydraulic power elements to meet precision requirements for advanced driver assistance functions.
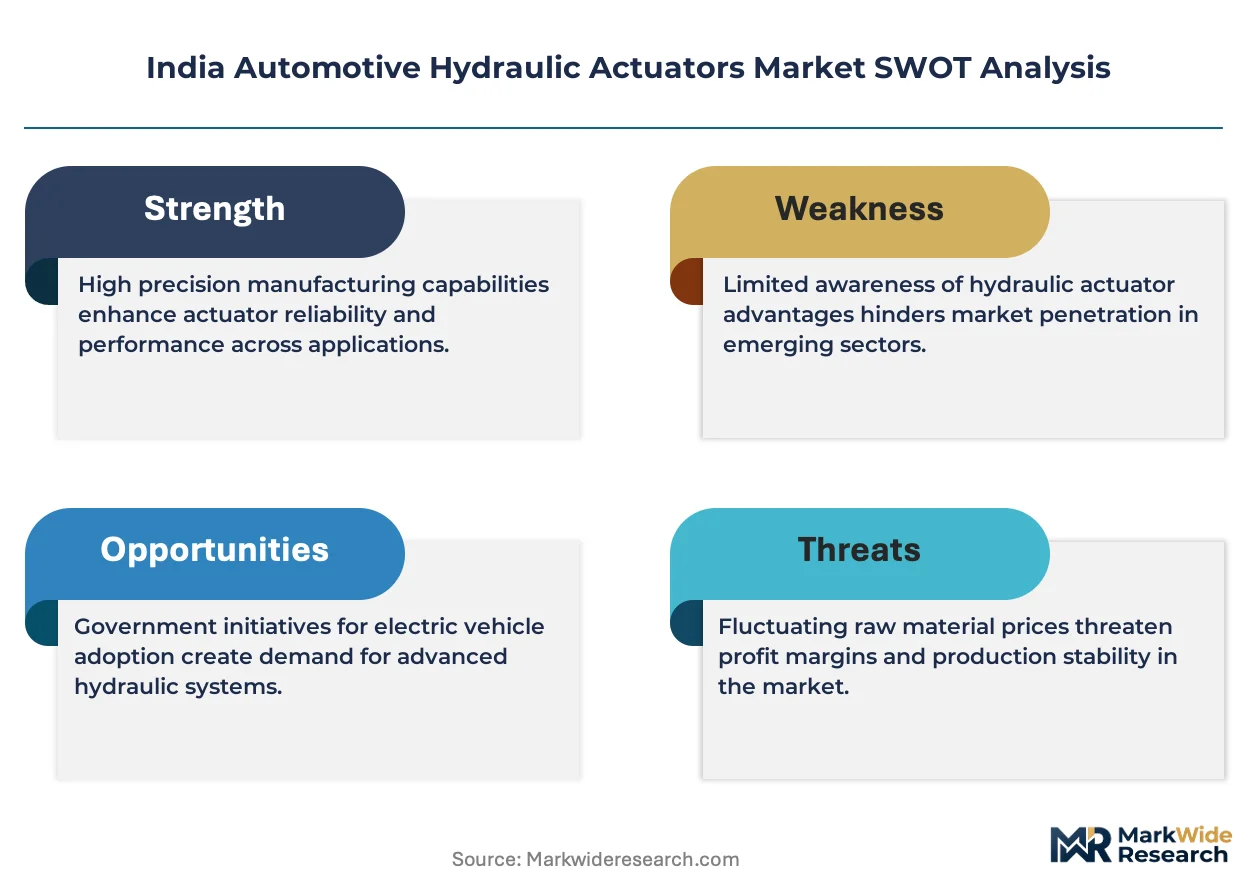
Bharat Stage VI norms enforced by the Central Pollution Control Board and Automotive Research Association of India compel tighter actuator tolerances and leak-proof sealing standards across on-highway segments. BIS certification requirements for automotive hydraulic components create compliance barriers for unorganized tier-2 suppliers while favoring established tier-1 players with testing infrastructure. Stakeholders must monitor how proposed CAFE regulations and state-level electric vehicle mandates reshape hydraulic content in future powertrain architectures.
Market Dynamics
The India automotive hydraulic actuators market is experiencing structural pressure from the Central Pollution Control Board's Bharat Stage VI enforcement, which compels fleet operators to accelerate replacement cycles and tighten tolerance specifications across braking and transmission systems.
Growth Catalysts
- Bharat Stage VI emission norms:The Central Pollution Control Board's stringent enforcement mandates leak-proof sealing and precision tolerances, forcing commercial vehicle fleets into proactive actuator replacement programs.
- Electro-hydraulic integration:Advanced driver assistance systems require electronic control units merged with hydraulic power elements, creating demand for precision actuators in automated manual transmissions.
- Tamil Nadu supplier concentration:Chennai-based OEM plants and dedicated component zones generate cluster economies that lower logistics costs and accelerate supplier qualification timelines.
Market Restraints
- Specialized alloy input volatility:High-grade steel and aluminum price fluctuations compress margins for actuator housing and piston manufacturers dependent on imported raw materials.
- BIS certification barriers:The Bureau of Indian Standards' testing infrastructure requirements exclude unorganized tier-2 suppliers, concentrating supply among established tier-1 players with captive labs.
- Electromechanical substitution:Pure electric actuators are displacing hydraulic units in light passenger vehicle segments where power density requirements are lower.
Strategic Opportunities
- Western India aftermarket penetration:Maharashtra and Gujarat commercial vehicle corridors remain underserved for replacement actuator distribution relative to Tamil Nadu density.
- PLI scheme localization:The Production Linked Incentive scheme for automobile and auto components rewards domestic manufacturing of precision hydraulic sub-assemblies.
- Electro-hydraulic convergence:Integration of sensor feedback loops with proportional valve control creates premium positioning for suppliers mastering mechatronic system design.
Industry Challenges
- Precision machining skill scarcity:CNC grinding and honing expertise for 150-350 bar pressure sealing surfaces remains concentrated among aging workforces in Pune and Chennai tool rooms.
- Legacy system integration friction:Retrofitting electro-hydraulic modules into existing Bharat Stage IV and VI vehicle architectures demands custom calibration protocols that extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Hydraulic Actuators Market |
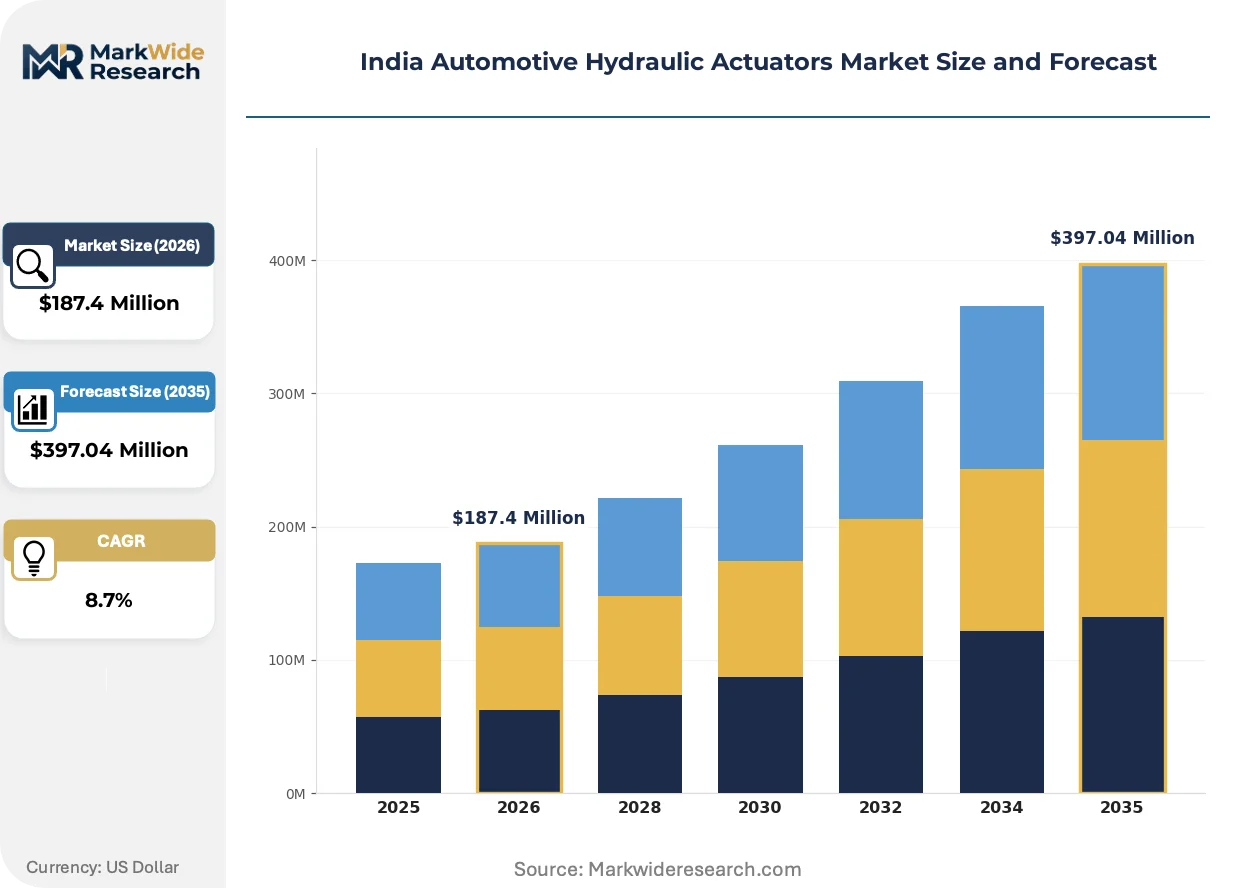
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Linear, Rotary Application: Braking System, Steering System, Suspension System, Transmission System End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Electro-Hydraulic, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Hitachi Ltd, Robert Bosch GmbH, Denso Corporation, Aptiv Plc, BorgWarner Inc, Mitsubishi Electric Corporation, Continental AG, Johnson Electric Holdings Ltd, Nidec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Hydraulic Actuators Market Shifts & Advancements
Technology trajectories in the India automotive hydraulic actuators market are diverging between cost-optimized mechanical units for mass-market commercial vehicles and precision electro-hydraulic systems for advanced safety applications.
Electro-hydraulic actuator architecture is bifurcating the supplier landscape. These systems combine proportional solenoid valves with compact hydraulic power units to enable real-time pressure modulation for anti-lock braking and electronic stability control. Domestic truck manufacturers are adopting these modules at accelerating pace for medium and heavy commercial vehicle platforms. The technology is bifurcating procurement patterns, separating fleet buyers prioritizing total cost of ownership from OEMs seeking ADAS-ready component integration.
CAFE regulations proposed by the Ministry of Road Transport and Highways are reshaping hydraulic content requirements. Tighter corporate average fuel economy standards penalize parasitic power losses from conventional hydraulic pumps, incentivizing demand-controlled actuator designs with variable displacement. Passenger car OEMs in the National Capital Region are responding fastest, specifying on-demand hydraulic assist systems that deactivate during steady-state highway operation.
Fleet procurement patterns are compressing replacement cycle timelines. Large commercial vehicle operators in Karnataka and Andhra Pradesh are unbundling actuator purchases from full brake system contracts, establishing direct supplier relationships for high-rotation wear components. This disintermediation is most visible among logistics aggregators operating consolidated truck fleets, who now specify actuator part numbers directly rather than accepting OEM-specified assemblies.
India Automotive Hydraulic Actuators Market Segmentation
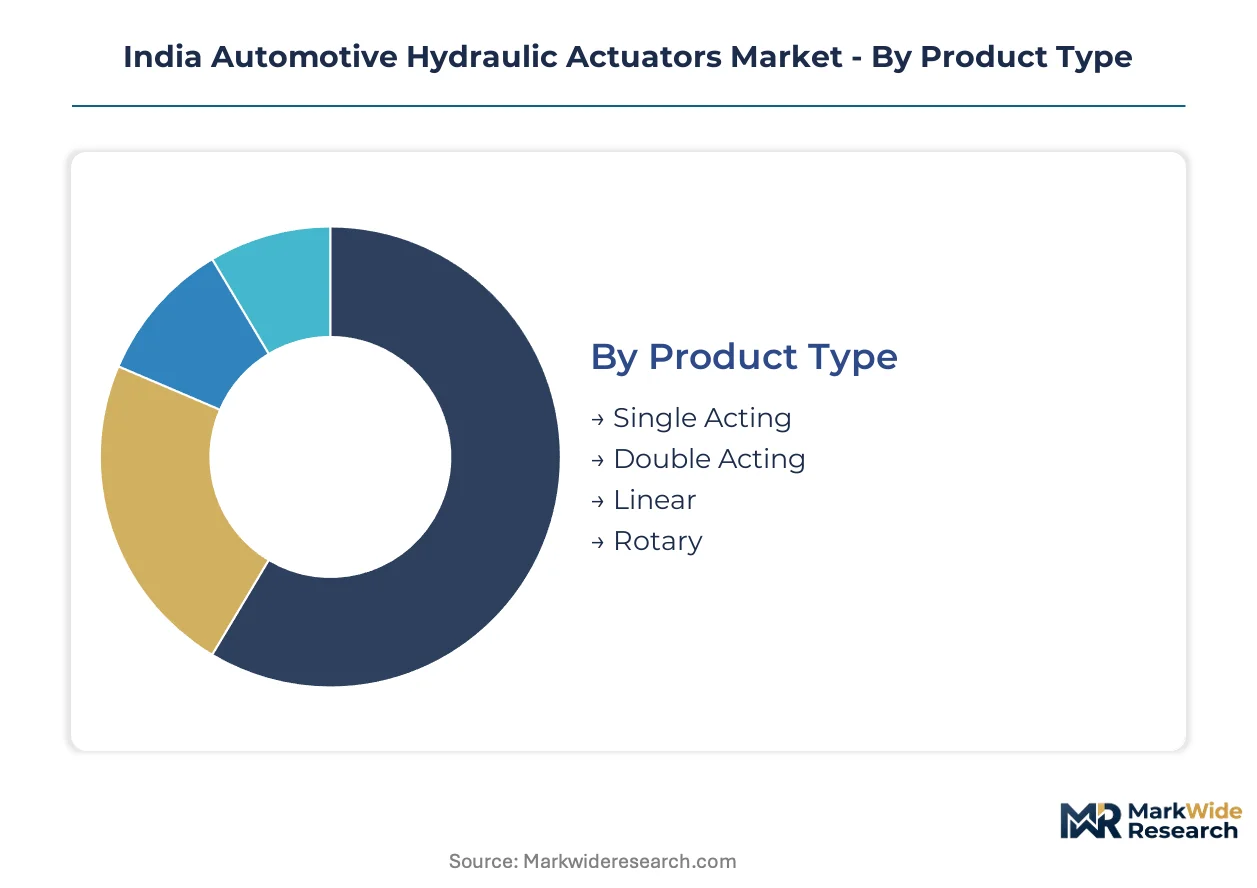
Hydraulic actuator procurement in India fragments across product architecture, vehicle system integration, and supply chain position. Each segmentation axis reveals distinct margin concentrations and competitive entry barriers that shape supplier strategy.
Product Type:
Double acting and rotary configurations command premium positioning due to precision manufacturing requirements and Bharat Stage VI compliance integration.
- Double Acting:Bidirectional force output enables superior load-holding in braking and transmission applications. Tamil Nadu's commercial vehicle clusters absorb the majority of domestic volume as fleet operators replace legacy single-acting units under tighter emission enforcement.
- Rotary:Compact torque conversion for automated manual transmissions demands CNC-machined sealing surfaces at 150-350 bar operating pressure. Denso Corporation's Chennai operations anchor supply for passenger car OEMs integrating electronic control feedback loops.
- Single Acting:Simpler unidirectional designs retain cost advantage in entry-level two-wheeler brake actuation.
- Linear:Piston-rod configurations dominate suspension height adjustment and clutch release mechanisms.
Double acting holds installed capacity. Rotary is rotating up the share rankings.
Application:
System-level integration requirements vary sharply, with braking and transmission commanding the tightest tolerance specifications.
- Braking System:Anti-lock braking modules require electro-hydraulic convergence with real-time pressure modulation. Robert Bosch GmbH leverages brake system integration capabilities to capture fleet replacement cycles accelerated by Central Pollution Control Board enforcement.
- Transmission System:Automated manual transmission actuators demand compact rotary designs with sensor feedback integration. Continental AG's localized electro-hydraulic module production targets this application for medium and heavy commercial vehicle platforms.
- Steering System:Power steering assist actuators face displacement pressure from pure electric rack-and-pinion systems in light passenger segments.
- Suspension System:Active damping actuators remain niche, concentrated in premium SUV platforms from National Capital Region assemblers.
Braking system anchors current revenue. Transmission system is expanding most quickly.
End User:
Procurement authority is shifting downstream as fleet operators disintermediate traditional OEM-specified assemblies.
- OEMs:Original equipment manufacturers specify integrated brake system contracts with tier-1 anchors, though their historical dominance unwinds as commercial vehicle fleets assert direct component purchasing.
- Aftermarket Providers:Western India corridors in Maharashtra and Gujarat remain underserved relative to Tamil Nadu density, creating distribution expansion opportunities for replacement actuator specialists.
- Vehicle Assemblers:Contract manufacturers in Karnataka and Andhra Pradesh logistics clusters now unbundle actuator purchases from full system contracts.
- Tier-1 Suppliers:Established players with BIS certification and captive testing infrastructure consolidate supply as unorganized tier-2 competitors face compliance barriers.
Aftermarket providers capture replacement velocity. Tier-1 suppliers are climbing the fastest.
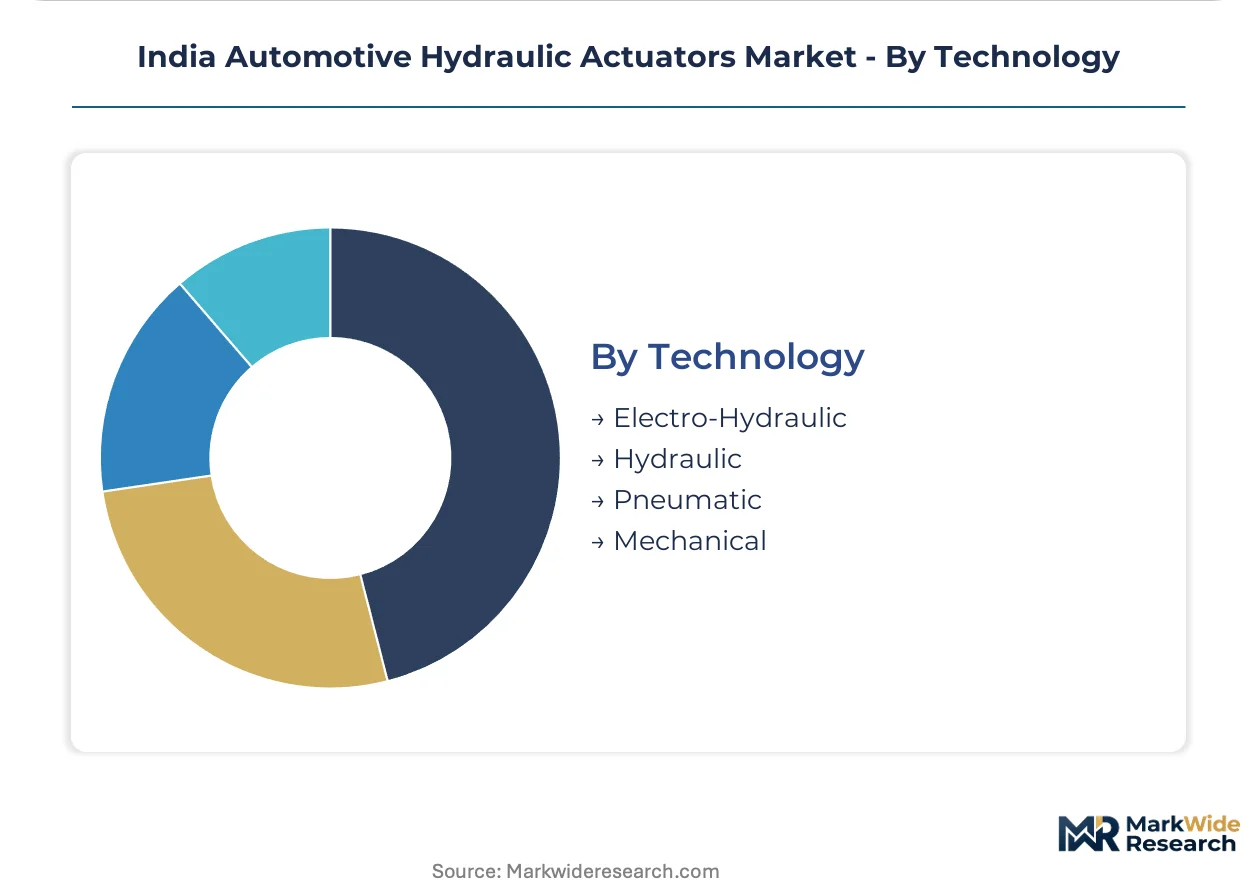
Technology:
Architecture choices bifurcate between cost-optimized mechanical units and precision electro-hydraulic systems for advanced safety applications.
- Electro-Hydraulic:Proportional solenoid valves merged with compact hydraulic power units enable real-time pressure modulation for anti-lock braking and electronic stability control. Domestic truck manufacturers adopt these modules at accelerating pace for ADAS-ready platforms.
- Hydraulic:Conventional fluid-power systems retain dominance in price-sensitive commercial vehicle segments where electronic integration costs prove prohibitive.
- Pneumatic:Compressed air actuation competes in heavy-duty braking for mining and construction vehicles operating in high-dust environments.
- Mechanical:Cable and linkage systems persist in legacy two-wheeler and three-wheeler platforms below Bharat Stage VI compliance thresholds.
Hydraulic retains volume base. Electro-hydraulic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision hydraulic components to Indian commercial vehicle manufacturers, while Japanese suppliers route rotary actuator systems through Chennai's dedicated automotive zones.
Tamil Nadu
Chennai-based OEM plants and supplier parks cluster around dedicated component zones, generating cluster economies that lower logistics costs. The Central Pollution Control Board's Bharat Stage VI enforcement compels fleet operators into proactive actuator replacement programs. Denso Corporation's localized operations anchor supply for passenger car manufacturers integrating electronic control feedback loops.
Maharashtra
Western India commercial vehicle corridors in Maharashtra remain underserved for replacement actuator distribution relative to Tamil Nadu density. The Bureau of Indian Standards certification requirements create compliance barriers that concentrate supply among established tier-1 players with captive testing infrastructure. Pune's precision machining tool rooms harbor aging workforces with CNC grinding expertise for 150-350 bar pressure sealing surfaces.
Karnataka
Logistics aggregators operating consolidated truck fleets in Karnataka now specify actuator part numbers directly rather than accepting OEM-specified assemblies. The Production Linked Incentive scheme for automobile and auto components rewards domestic manufacturing of precision hydraulic sub-assemblies. Bengaluru-based vehicle assemblers unbundle actuator purchases from full brake system contracts.
Gujarat
Commercial vehicle fleet operators in Gujarat expand replacement schedules amid stricter emission enforcement. State-level electric vehicle mandates reshape hydraulic content requirements in future powertrain architectures. Dedicated supplier zones around Ahmedabad attract tier-1 anchor investments seeking western India aftermarket penetration.
Andhra Pradesh
Large commercial vehicle operators in Andhra Pradesh establish direct supplier relationships for high-rotation wear components. The Automotive Research Association of India testing protocols validate leak-proof sealing standards across on-highway segments. Vijayawada logistics corridors witness accelerating fleet procurement pattern shifts.
India Automotive Hydraulic Actuators Market Competitive Landscape
Listed leaders compete with private specialists across brake system integration and electro-hydraulic module production. The vendor base concentrates among tier-1 anchors with BIS certification and captive testing infrastructure, while unorganized tier-2 competitors face exclusion. Three archetypes dominate: precision rotary actuator specialists, brake system integrators, and electro-hydraulic convergence players. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for ADAS-ready platform adoption.
Among Japan-based fabricators, Hitachi Ltd and Denso Corporation occupy positions within the precision actuator tier, while Robert Bosch GmbH anchors the brake system integration archetype. These three exemplify the competitive structure: Hitachi represents scale-driven hydraulic component production, Denso exemplifies compact rotary actuator specialization for transmission applications, and Bosch sits within the electro-hydraulic convergence category where electronic control units merge with hydraulic power elements.
| Leading Market Players |
|---|
| Hitachi Ltd |
| Robert Bosch GmbH |
| Denso Corporation |
| Aptiv Plc |
| BorgWarner Inc |
| Mitsubishi Electric Corporation |
| Continental AG |
| Johnson Electric Holdings Ltd |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Electro-hydraulic module substitution for conventional mechanical actuators simultaneously shifts procurement geography toward Tamil Nadu's supplier corridors and compresses pricing economics for legacy single-acting units. This technology transition concentrates margin capture among tier-1 anchors with BIS-certified testing infrastructure while fragmenting residual demand across price-sensitive aftermarket channels.
Pricing Analysis
Current-generation electro-hydraulic actuators command 40-60% premiums over prior-generation mechanical units, while next-generation demand-controlled designs with variable displacement pricing stratify across premium, standard, and economy tiers based on Bharat Stage VI certification grade and sensor integration depth. Price differentiation hinges on BIS compliance tier and volume scale, with fleet procurement aggregators extracting steepest discounts through direct supplier relationships. Cost compression in mechanical actuator tiers is intensifying because unorganized tier-2 suppliers face exclusion from OEM qualification pipelines. Commercial vehicle fleet operators exhibit highest price sensitivity, while passenger car OEMs integrating ADAS platforms demonstrate lowest sensitivity to electronic control unit premiums.
Supply Chain Analysis
Germany and Japan anchor precision hydraulic component production for Indian commercial vehicle manufacturers, while China feeds aluminum alloy and high-grade steel inputs for actuator housings. Domestic supply chains draw from imported CNC grinding equipment and specialized sealing materials, with localized electro-hydraulic module assembly expanding through Tamil Nadu's dedicated component zones. Single-source vulnerability concentrates in precision machining skill pools aging across Pune and Chennai tool rooms. Distribution runs through tier-1 supplier direct contracts with OEM platform engineers, supplemented by aftermarket channels penetrating western India corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bharat Stage VI enforcement creates a high-growth disruption window as electro-hydraulic convergence rewrites procurement authority and compliance barriers consolidate supply among certified tier-1 anchors.
For Market Incumbents: Consolidate BIS certification advantages by expanding captive testing infrastructure in Tamil Nadu supplier parks, capturing fleet replacement cycles accelerated by Central Pollution Control Board enforcement. Deepen backward integration into precision alloy sourcing to buffer margin compression from imported raw material volatility. Anchor electro-hydraulic module production capacity ahead of ADAS platform adoption curves. For New Entrants and Emerging Players: Aftermarket distribution gaps in Maharashtra and Gujarat commercial vehicle corridors offer white-space entry points for replacement actuator specialists with western India logistics partnerships. Target vehicle assembler direct procurement relationships in Karnataka and Andhra Pradesh logistics clusters where fleet operators now unbundle component purchases from full system contracts. Pursue PLI scheme qualification for precision hydraulic sub-assembly localization to offset tier-1 incumbents' certification head start. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component platforms seeking exit liquidity amid electro-hydraulic technology transition costs. Long-term viability favors suppliers mastering mechatronic system design with sensor feedback loop integration over pure mechanical actuator manufacturers facing demand displacement. Monitor Central Pollution Control Board enforcement intensity as inflection indicator for replacement cycle velocity and tier-2 supplier exclusion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Module Localization | Captures PLI incentives while positioning for ADAS-ready platform specifications from Chennai-based OEMs. |
| Precision Machining Skill Acquisition | Addresses CNC grinding expertise scarcity in Pune tool rooms through targeted workforce development partnerships. |
| Western India Aftermarket Expansion | Penetrates underserved Maharashtra and Gujarat corridors with dedicated distribution infrastructure investments. |
| BIS Certification Infrastructure Buildout | Creates compliance moats excluding unorganized tier-2 competitors from fleet procurement pipelines. |
| Backward Integration into Alloy Supply | Reduces exposure to high-grade steel and aluminum price volatility compressing actuator housing margins. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and fleet maintenance managers provided ongoing calibration across primary fieldwork. Secondary validation drew from Automotive Research Association of India testing protocols, Central Pollution Control Board enforcement disclosures, BIS certification registries, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional vehicle registration data and tier-1 supplier revenue disclosures. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster throughout the forecast period. CAGRs derived from trend extrapolation of electro-hydraulic adoption curves and fleet replacement cycle compression patterns, with Bharat Stage VI compliance timelines and PLI scheme uptake rates as key industry-specific inputs.
Forecasts assume regulatory continuity in Central Pollution Control Board emission enforcement and BIS certification requirements; material policy shifts would require re-modeling. Specific risks that could revise projections include electromechanical substitution acceleration in light passenger segments, raw material tariff escalations affecting alloy input costs, and precision machining skill scarcity extending development cycles. Recalibration cycles align with material shifts in CAFE regulation finalization and state-level electric vehicle mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Friction Pads Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Timing Gear Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Weatherstrips Market