
 Automotive Hydroformed Parts Market | 2026-2036
Automotive Hydroformed Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hydroformed Parts Market Analysis
Electric vehicle architecture is repositioning the buyer mix for hydroformed components away from conventional powertrain brackets toward battery enclosure rails and motor mounts. Magna International leverages its North American stamping heritage to dominate structural hydroforming for light truck platforms. Thyssenkrupp AG anchors European supply through its integrated steel-to-parts pipeline, while Vari-Form specializes in tube hydroforming for exhaust and chassis applications.
Automotive hydroformed parts are metal components shaped by pressurizing fluid inside a blank or tube against a die cavity, typically achieving wall thickness uniformity of 0.5–3.0 mm and tensile strengths exceeding 600 MPa in advanced high-strength steels. Their primary purpose is to deliver complex geometries with reduced part count and superior stiffness-to-weight ratios for vehicle structures. Chassis components lead volume demand due to control arm and subframe standardization, while structural parts represent the fastest-growing category as electric vehicle skateboard platforms require elongated rails with integrated mounting features. Aluminum hydroforming commands premium positioning in battery-electric applications where mass reduction directly extends range.
NHTSA Federal Motor Vehicle Safety Standards and EPA Corporate Average Fuel Economy regulations in the United States mandate structural efficiency that hydroforming satisfies through part consolidation. EMA and EU Green Deal carbon-border adjustments in Europe are pushing OEMs toward recycled-content aluminum and low-carbon steel hydroformed products. Stakeholders must monitor evolving battery pack dimensional standards across regulatory jurisdictions to align die investments with platform architectures.
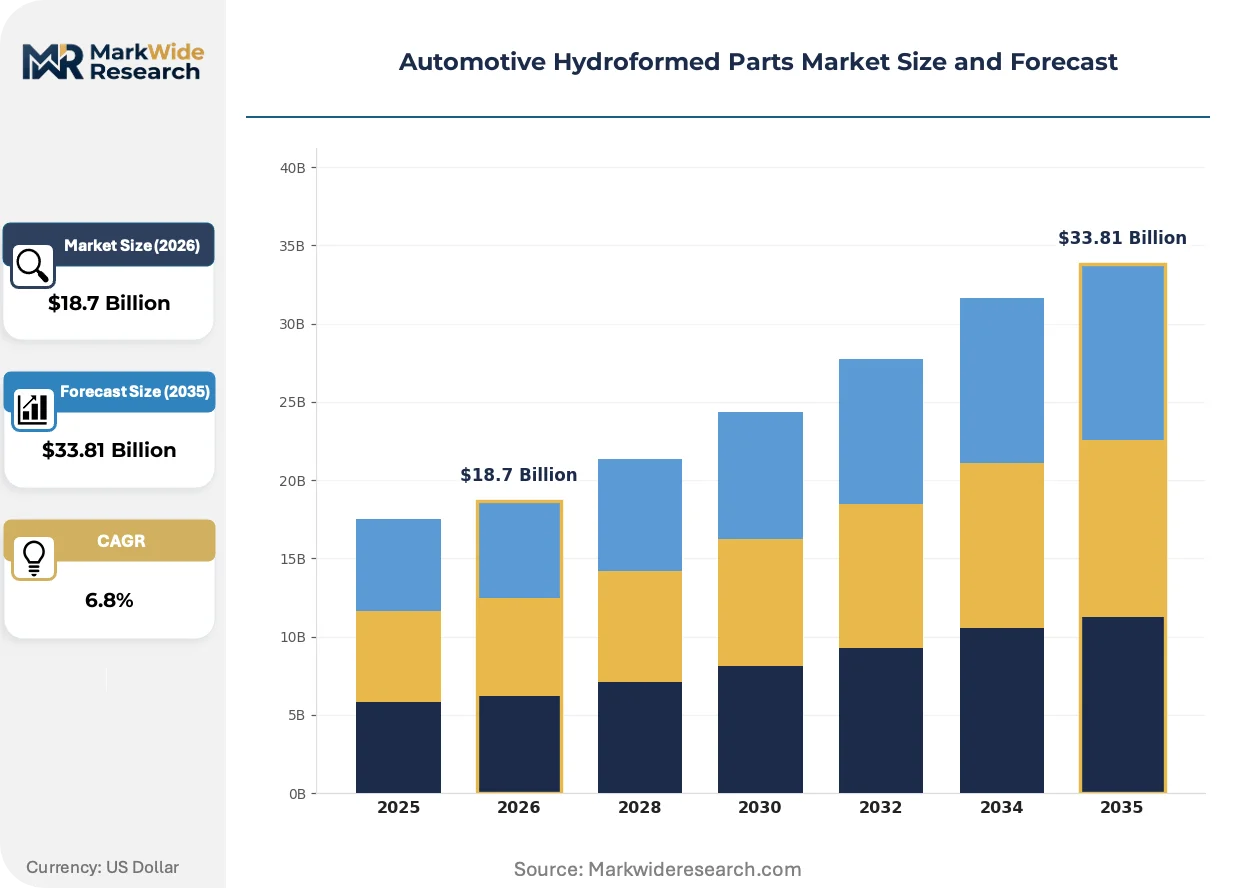
Market Dynamics
Electric vehicle platform architectures are forcing a wholesale reconfiguration of hydroformed part specifications, as battery enclosure rails and motor mounts displace traditional powertrain brackets in engineering priorities and procurement volumes.
Growth Catalysts
- NHTSA Crashworthiness Standards:Federal Motor Vehicle Safety Standards mandate structural integrity thresholds that hydroforming achieves through part consolidation and continuous cross-sections, accelerating adoption for subframes and control arms in light truck platforms.
- Aluminum Alloy Advances:6xxx and 7xxx series aluminum formulations now achieve 350 MPa yield strengths post-hydroforming, enabling battery-electric vehicle manufacturers to hit mass targets without sacrificing rail stiffness.
- German Automotive Cluster:OEM localization of battery-electric vehicle supply chains around Stuttgart and Munich is concentrating demand for hydroformed chassis components within a 200-kilometer supplier radius.
Market Restraints
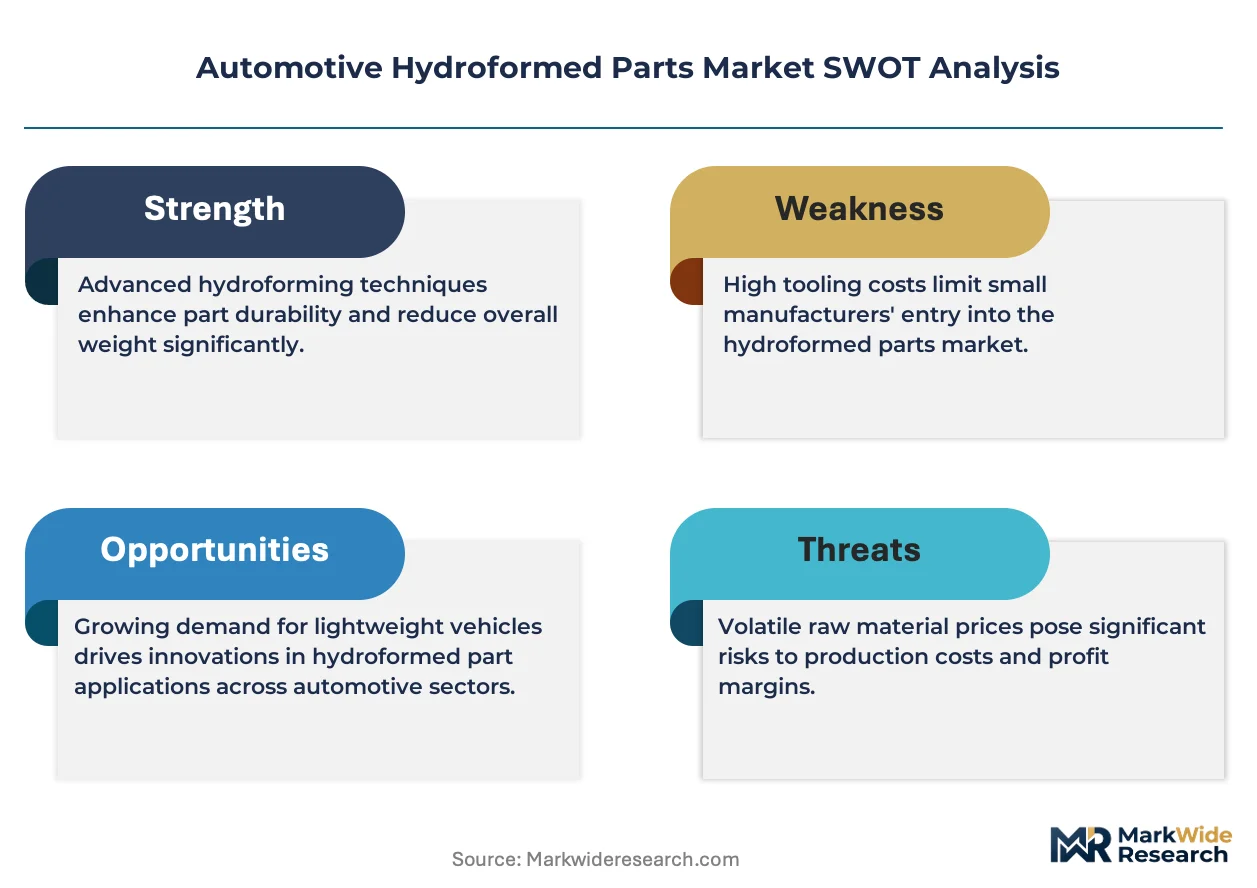
- Tooling Cost Concentration:Die development for complex hydroformed geometries requires 12-18 month lead times and capital commitments exceeding $2 million per part family, locking out mid-volume entrants.
- High-Strength Steel Input Volatility:AHSS coil pricing fluctuates with scrap metal and alloying element markets, compressing margins for contract manufacturers without upstream steel integration.
- Tube Hydroforming Dimensional Limits:Current press capacities restrict maximum tube lengths to 6 meters for most commercial equipment, fragmenting production of elongated EV skateboard rails across multiple joints.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced manufacturing are attracting hydroforming capacity to serve domestic electric two-wheeler and compact car platforms.
- Digital Twin Integration:Convergence of finite element analysis with real-time press monitoring is compressing die trial cycles and enabling first-part-right production for prototype-to-production transitions.
- Recycled-Content Aluminum Mandates:EU Green Deal carbon-border adjustments create premium positioning for hydroformed components using 75%+ post-consumer scrap, rewarding early recyclate integration.
Industry Challenges
- Die Tryout Technician Scarcity:The specialized skill set combining hydraulic systems knowledge with metallurgical troubleshooting is concentrating among aging workforces in Germany, Japan, and the US Midwest.
- Battery Pack Dimensional Standardization Lag:Absent universal enclosure rail specifications across OEM platforms, die investments risk obsolescence as cell chemistry and thermal management architectures evolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hydroformed Parts Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chassis Components, Structural Parts, Exhaust Systems, Body Panels Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Performance Cars Material: Aluminum, Steel, Magnesium, Composite Materials Manufacturing Process: Die Hydroforming, Tube Hydroforming, Stamping, Welding |
| Companies Covered | Nissin Kogyo, Metalsa, Magna International, F-TECH, Alf Engineering, Thyssenkrupp AG, Sango Co., Ltd., Vari-Form, Tenneco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hydroformed Parts Market Emerging Trajectories
Process digitization and material science breakthroughs are compressing development cycles while regulatory carbon accounting is rewriting supplier qualification criteria across automotive tiers.
Adaptive press control systems using machine vision feedback loops are automating real-time pressure modulation during forming cycles. Tier-1 suppliers in North America and Europe are deploying these systems for high-volume subframe production, reducing scrap rates and enabling thinner-wall designs without dimensional drift. This automation is compressing the competitive gap between established hydroforming specialists and stamping houses entering the category.
EU Green Deal carbon-border adjustment mechanisms are reshaping raw material sourcing decisions for hydroformed components. The regulation imposes embodied carbon tariffs on imported aluminum and steel above threshold intensities, pushing OEMs to document supply chain emissions through certified mass-balance systems. European suppliers with integrated recycled-content pipelines are capturing preferential placement in battery-electric vehicle programs.
Platform engineering teams are unbundling structural component procurement from traditional chassis system integrators. Direct sourcing relationships between OEM body-in-white engineers and hydroforming specialists are displacing tiered supply arrangements in Germany and Japan. This disintermediation is most visible in battery-electric vehicle programs where rail geometry customization demands iterative die development cycles outside standard component catalog structures.
Automotive Hydroformed Parts Market Segmentation
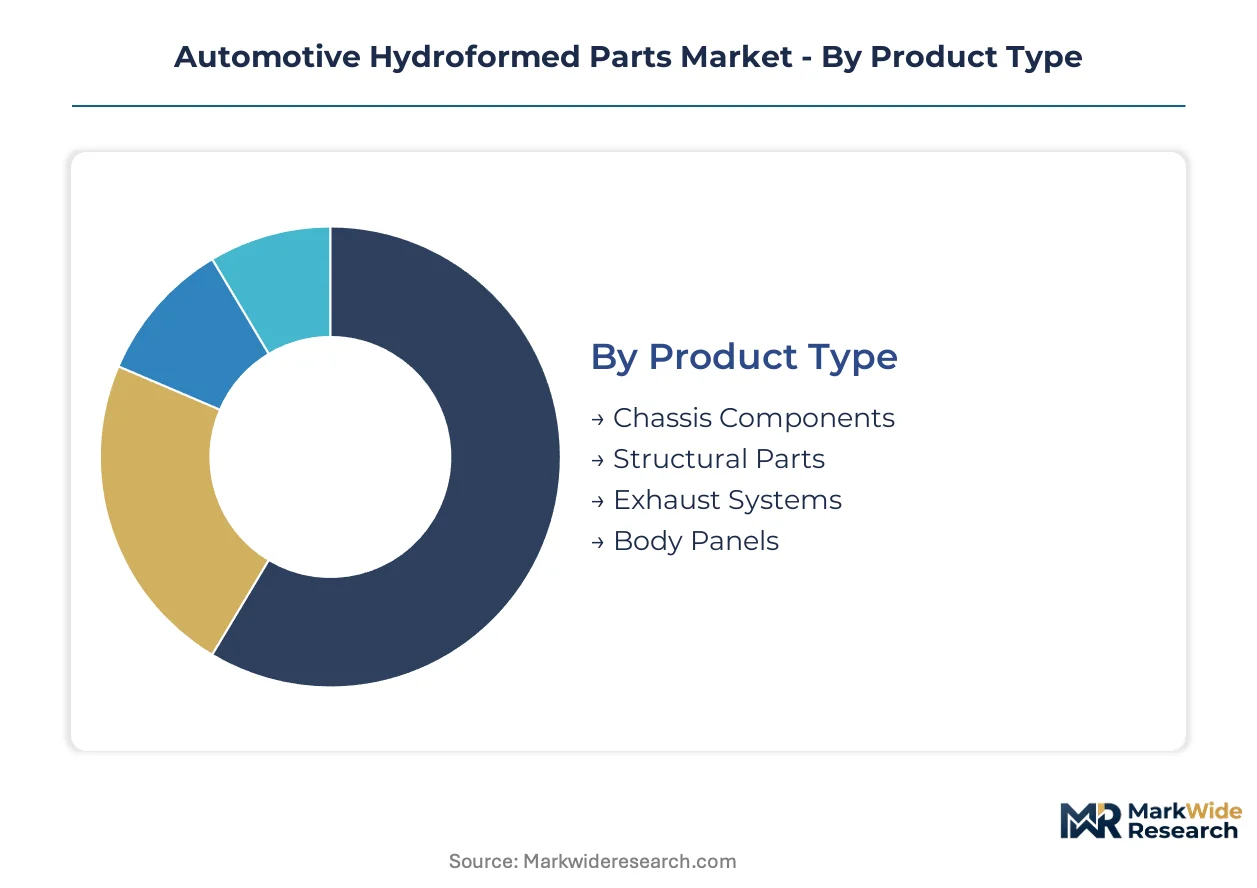
Segmentation in automotive hydroforming reveals how material choices and manufacturing methods concentrate margin capture among specialized suppliers. Each dimension—product architecture, vehicle application, raw material, and forming technology—creates distinct competitive moats based on capital intensity and technical certification barriers.
Product Type:
Supply concentration clusters around chassis and structural categories where die investments exceed two million dollars per part family, locking out mid-volume competitors.
- Chassis Components:Control arms, subframes, and suspension links dominate current procurement volumes through standardized geometries across light truck platforms. Demand concentrates in Michigan and Stuttgart manufacturing corridors where OEMs localize battery-electric vehicle assembly, driven by NHTSA crashworthiness mandates requiring continuous cross-sections for structural integrity.
- Structural Parts:Battery enclosure rails and motor mounts for electric vehicle skateboard platforms command premium positioning due to elongated geometries and integrated mounting features. German and Japanese OEMs are concentrating direct sourcing relationships with hydroforming specialists outside traditional tiered supply chains, displacing conventional powertrain brackets in engineering priorities.
- Exhaust Systems:Manifolds and catalytic converter housings sustain steady demand from internal combustion residual fleets.
- Body Panels:Roof rails and A-pillar reinforcements serve niche applications in performance vehicles.
Today's leader: Chassis Components. Tomorrow's challenger: Structural Parts.
Application:
Cost tier stratification separates mass-market passenger programs from premium electric architectures where aluminum hydroforming commands material premiums.
- Passenger Vehicles:High-volume compact and mid-size platforms drive baseline demand for steel hydroformed subframes through standardized part families. Production concentrates in Tennessee and South Carolina assembly corridors serving North American markets, constrained by twelve-to-eighteen-month die lead times that favor incumbent suppliers with existing press capacity.
- Electric Vehicles:Battery-electric platforms require elongated rails with complex mounting features for pack integration. Demand is climbing the fastest among all application categories as OEMs redesign body-in-white architectures around skateboard foundations, with aluminum formulations capturing disproportionate share in premium segments.
- Commercial Vehicles:Heavy-duty truck chassis sustain demand for high-strength steel tube hydroforming.
- Performance Cars:Low-volume specialty applications prioritize magnesium and composite hybrid structures.
Passenger Vehicles anchor current volume. Electric Vehicles are gaining share fastest through platform conversion cycles.
Material:
Volume distribution favors steel for cost-sensitive applications while aluminum captures margin expansion in electrification programs.
- Steel:Advanced high-strength grades achieve tensile strengths exceeding 600 MPa post-hydroforming, satisfying structural requirements for light truck subframes and control arms. Pricing volatility in scrap metal and alloying element markets compresses contract manufacturer margins without upstream integration.
- Aluminum:6xxx and 7xxx series formulations now deliver 350 MPa yield strengths, enabling battery-electric manufacturers to hit mass targets without sacrificing rail stiffness. EU Green Deal carbon-border adjustments are rewarding European suppliers with 75-plus percent post-consumer scrap integration.
- Magnesium:Limited adoption in specialty performance applications due to corrosion sensitivity and forming complexity.
- Composite Materials:Hybrid metal-composite structures serve experimental lightweighting programs in motorsport-derived road cars.
Steel dominates unit economics. Aluminum offers the steepest expansion trajectory through electrification mandates.
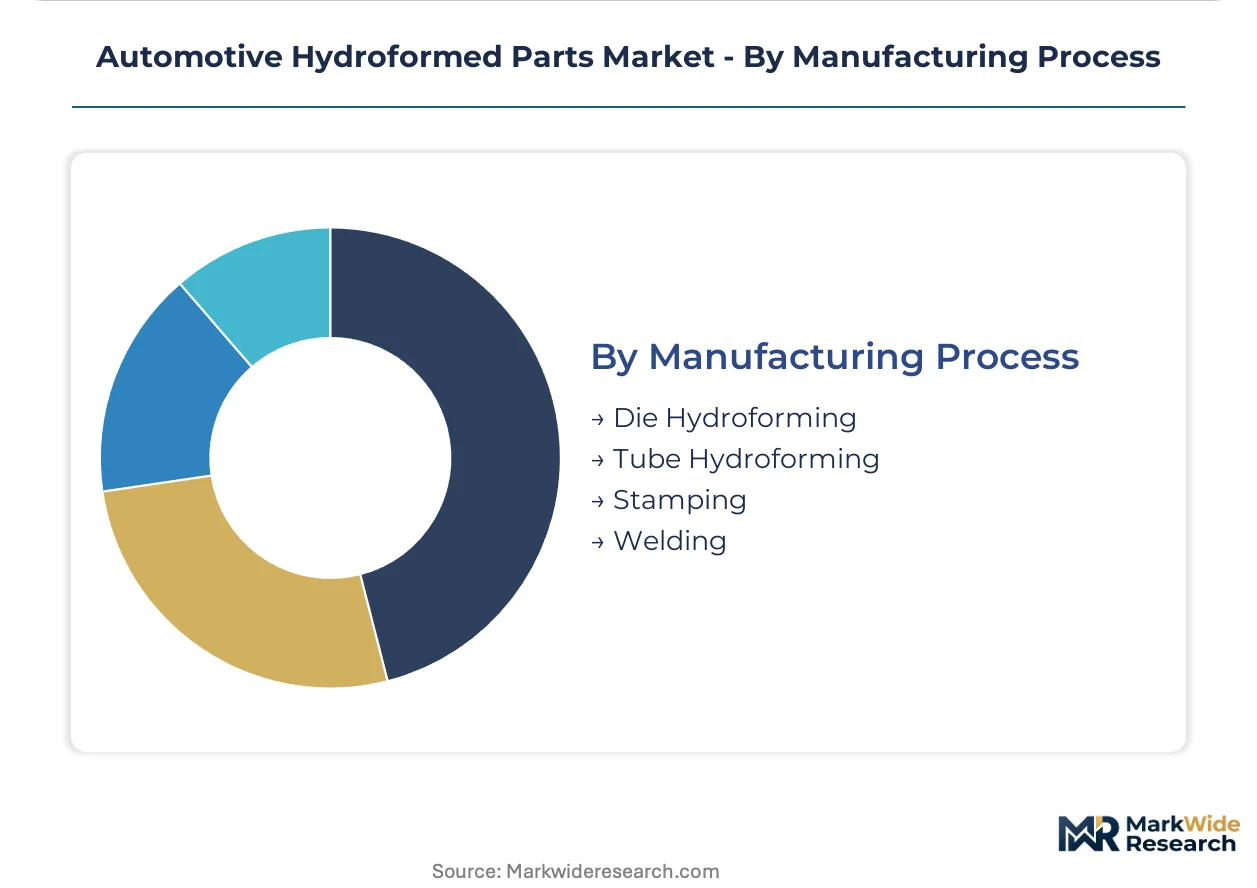
Manufacturing Process:
Capability scarcity concentrates among aging workforces in Germany, Japan, and the US Midwest, where die tryout technicians combine hydraulic systems expertise with metallurgical troubleshooting.
- Tube Hydroforming:Fluid pressurization inside tubular blanks creates complex hollow sections with superior stiffness-to-weight ratios for chassis and exhaust applications. Current press capacities restrict maximum tube lengths to six meters, fragmenting production of elongated EV skateboard rails across multiple joints.
- Die Hydroforming:Sheet blank forming against cavity dies produces body panels and structural reinforcements with wall thickness uniformity of 0.5 to 3.0 millimeters. Digital twin integration using finite element analysis and real-time press monitoring is compressing die trial cycles for prototype-to-production transitions.
- Stamping:Conventional mechanical forming serves high-volume simple geometries where hydroforming complexity is unnecessary.
- Welding:Secondary joining operations consolidate multi-piece hydroformed assemblies into final subframe modules.
Tube Hydroforming leads structural applications. Die Hydroforming is expanding most quickly through body-in-white integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich corridor anchors hydroformed chassis demand as German OEMs localize battery-electric vehicle supply chains within a 200-kilometer supplier radius. Regulatory pressure from EU Green Deal carbon-border adjustments and NHTSA crashworthiness standards in export markets is reshaping regional production priorities across four major manufacturing centers.
United States
Light truck platforms in Michigan and Tennessee drive steel subframe demand as NHTSA Federal Motor Vehicle Safety Standards mandate structural integrity through continuous cross-sections. The EPA Corporate Average Fuel Economy regulations accelerate aluminum adoption for electric vehicle rails. Detroit-area suppliers concentrate die capacity to serve battery-electric platform launches from domestic OEMs.
Germany
EMA and EU Green Deal decarbonization targets push OEMs toward recycled-content aluminum hydroformed products with documented mass-balance certification. The Stuttgart automotive cluster concentrates direct sourcing relationships between body-in-white engineers and hydroforming specialists. Bavarian suppliers capture preferential placement in premium electric vehicle programs through low-carbon steel integration.
Japan
METI industrial policy supports domestic production of high-strength steel tube hydroforming for hybrid and electric vehicle architectures. The Nagoya-Toyota City corridor maintains specialized die tryout technician concentrations combining hydraulic systems expertise with metallurgical troubleshooting. Kanto-region suppliers serve export markets with precision chassis components for global OEM platforms.
China
MIIT new energy vehicle mandates and dual carbon goals accelerate localized hydroforming capacity for domestic battery-electric brands. The Yangtze River Delta automotive cluster concentrates demand for aluminum enclosure rails as local OEMs redesign skateboard platforms. Shanghai-area fabricators expand press capacity to serve both domestic consumption and export assembly programs.
India
The PLI scheme for auto components attracts hydroforming investment to serve domestic electric two-wheeler and compact car platforms. BIS standards alignment with global crashworthiness protocols enables component export qualification. Tamil Nadu and Maharashtra manufacturing corridors concentrate new capacity for battery-electric vehicle supply chain localization.
Automotive Hydroformed Parts Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers position press lines near OEM battery-electric vehicle assembly corridors. The market structure concentrates among integrated steel-to-parts pipelines and specialized tube hydroforming houses with multi-decade die development heritage. Three archetypes define competitive positioning: upstream-integrated metallurgical processors, process-specialist fabricators with captive tooling expertise, and diversified automotive Tier-1s leveraging stamping heritage. Geographic expansion and strategic partnerships represent the dominant competitive moves, with die development cycle compression through digital twin integration emerging as a secondary vector.
Among diversified North American automotive suppliers, Magna International exemplifies the scale-driven archetype leveraging regional stamping heritage. Thyssenkrupp AG represents the upstream-integrated model with captive steel production and downstream parts fabrication. Vari-Form occupies a specialist position in tube hydroforming process expertise. These three anchors illustrate how competitive positioning stratifies across integration depth, geographic footprint, and technical certification barriers rather than product line differentiation alone.
| Leading Market Players |
|---|
| Nissin Kogyo |
| Metalsa |
| Magna International |
| F-TECH |
| Alf Engineering |
| Thyssenkrupp AG |
| Sango Co., Ltd. |
| Vari-Form |
| Tenneco |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-border adjustment mechanisms gate qualified supply access and premium-tier pricing positioning for hydroformed component manufacturers serving European OEM programs. Suppliers without certified mass-balance documentation for recycled-content aluminum face exclusion from battery-electric vehicle procurement lists, compressing margins in undifferentiated steel categories while rewarding low-carbon integrated pipelines with pricing power.
Pricing Analysis
Direct-to-OEM contract structures dominate, with tiered pricing separating aluminum battery enclosure rails from high-strength steel subframe commodities. Price differentiation hinges on EU Green Deal mass-balance certification and die development heritage, with certified European suppliers capturing 15-20 point margin premiums over undifferentiated contract manufacturers. Cost compression in steel chassis components intensifies as scrap metal volatility feeds through AHSS coil input costs. Fleet procurement officers at commercial vehicle OEMs exhibit highest price sensitivity, while premium electric vehicle platform engineers prioritize mass reduction over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs require qualified secondary suppliers for all safety-critical hydroformed chassis components, fragmenting die investment recovery across smaller production lots. Geographic supply concentration centers on Germany, Japan, and the United States, with emerging capacity additions in China and India. Raw material dependencies span 6xxx and 7xxx series aluminum billet, AHSS coil from integrated mills, and specialized hydraulic press components from Italian and Japanese equipment builders. Single-source vulnerability concentrates in die tryout technician expertise, where aging workforces in Stuttgart, Nagoya, and Detroit constrain capacity expansion. Distribution runs through Tier 1 chassis system integrators, though direct OEM relationships are displacing traditional tiered arrangements for electric vehicle structural programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through aluminum alloy substitution in battery-electric platforms, where mass-reduction premiums offset higher input costs and extend pricing power to qualified suppliers.
For Market Incumbents: Hedge against steel input volatility through backward integration into recycled-content aluminum pipelines or long-term offtake agreements with low-carbon smelters. Secure die tryout technician pipelines through apprenticeship partnerships with technical institutes in Germany and Japan, addressing workforce concentration risk that threatens capacity utilization. Prioritize EU Green Deal mass-balance certification investment to defend premium positioning as carbon-border adjustments tighten qualification thresholds. For New Entrants and Emerging Players: Begin with digital twin-enabled die development services for prototype-to-production transitions, where incumbent capacity constraints create white-space for agile specialists. Target Indian electric two-wheeler and compact car platforms under PLI scheme incentives, where localized hydroforming capacity lags demand from domestic OEM skateboard programs. Pursue joint development agreements with battery pack engineering teams to embed rail geometry specifications early in platform design cycles. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap die hydroforming specialists because OEM disintermediation is fragmenting procurement relationships and creating multiple bite-sized acquisition targets with complementary press capacities. Five-to-ten year viability hinges on aluminum content per vehicle trajectory in mass-market electric platforms. Watch NHTSA and EPA regulatory stringency as the signal for accelerated platform conversion timelines that would expand addressable demand for lightweight structural components.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Aluminum Integration | EU Green Deal mass-balance certification unlocks premium placement in German OEM battery-electric programs. |
| Digital Twin Die Development | Finite element analysis convergence compresses trial cycles for prototype-to-production transitions at Tier 1 suppliers. |
| Geographic Capacity Expansion | Press line investments near Stuttgart and Tennessee assembly corridors capture localized battery-electric platform demand. |
| Direct OEM Engineering Relationships | Body-in-white collaboration outside traditional tiered supply chains secures rail geometry specification influence. |
| Die Tryout Technician Pipeline Development | Apprenticeship partnerships with German and Japanese technical institutes address workforce aging concentration risk. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and die tryout technicians informed demand-side dynamics and technical certification barriers. Secondary sources included vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs records for aluminum and steel trade flows. Bottom-up modeling of content per vehicle by platform architecture triangulated against top-down market value estimates.
Granularity-level modeling disaggregated volume and value across the analysis window by product type, vehicle application, raw material grade, and manufacturing process technology. Segmentation dimensions included chassis versus structural part architectures, passenger versus electric versus commercial vehicle platforms, steel versus aluminum versus magnesium material classes, and tube versus die hydroforming methods. CAGRs derived from platform conversion cycle timing, regulatory mandate phase-in schedules, and OEM localization announcements. Industry-specific inputs encompassed battery pack dimensional standardization trajectories and NHTSA crashworthiness test protocol evolution.
Several conditions sit outside the modeled scope, including potential breakthroughs in composite structural materials that could displace metal hydroforming, abrupt shifts in cell chemistry altering enclosure rail geometries, and trade policy disruptions affecting aluminum billet sourcing. Forecasts reflect assumptions about electric vehicle adoption rates and platform architecture convergence that may revise with regulatory enforcement intensity or consumer demand fluctuations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Small Engine Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive Parking Heater Market