
 Egypt Passenger Vehicles Lubricants Market | 2026-2036
Egypt Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Passenger Vehicles Lubricants Market Foresight
Egypt is narrowing the gap between domestic blending capacity and import dependence as new refinery investments near Suez come online. Misr Petroleum leverages its state-backed distribution network to sustain volume leadership across Upper Egypt and the Delta. ExxonMobil Corporation anchors premium positioning through synthetic formulations targeting high-temperature engine performance. Royal Dutch Shell PLC competes via integrated service partnerships with authorized dealership networks in Cairo and Alexandria.
Passenger vehicles lubricants comprise formulated oils and functional fluids engineered from base stocks and additive packages to reduce friction, dissipate heat, and prevent wear in internal combustion powertrains, with viscosity grades typically spanning SAE 0W-20 to 20W-50 for Egyptian climatic conditions. Motor oil dominates product-type revenue due to mandatory drain intervals tied to OEM warranty requirements, while transmission fluid generates higher per-liter margins from specialized dual-clutch and CVT formulations. Fleet operators represent the fastest-expanding end-user segment as ride-hailing platforms and corporate leasing schemes consolidate procurement into annual supply contracts.
Egypt's General Authority for Standards and Quality (EOS) mandates compliance with API and ACEA performance classifications for all imported lubricants, while the Ministry of Environment enforces waste oil collection protocols under national environmental law. The Egyptian General Petroleum Corporation coordinates with international certifiers to align domestic blending facilities with evolving OEM specifications. Stakeholders must monitor how electrification-adjacent fluid requirements and bio-based additive approvals reshape product development priorities ahead of regulatory transitions.
Market Dynamics
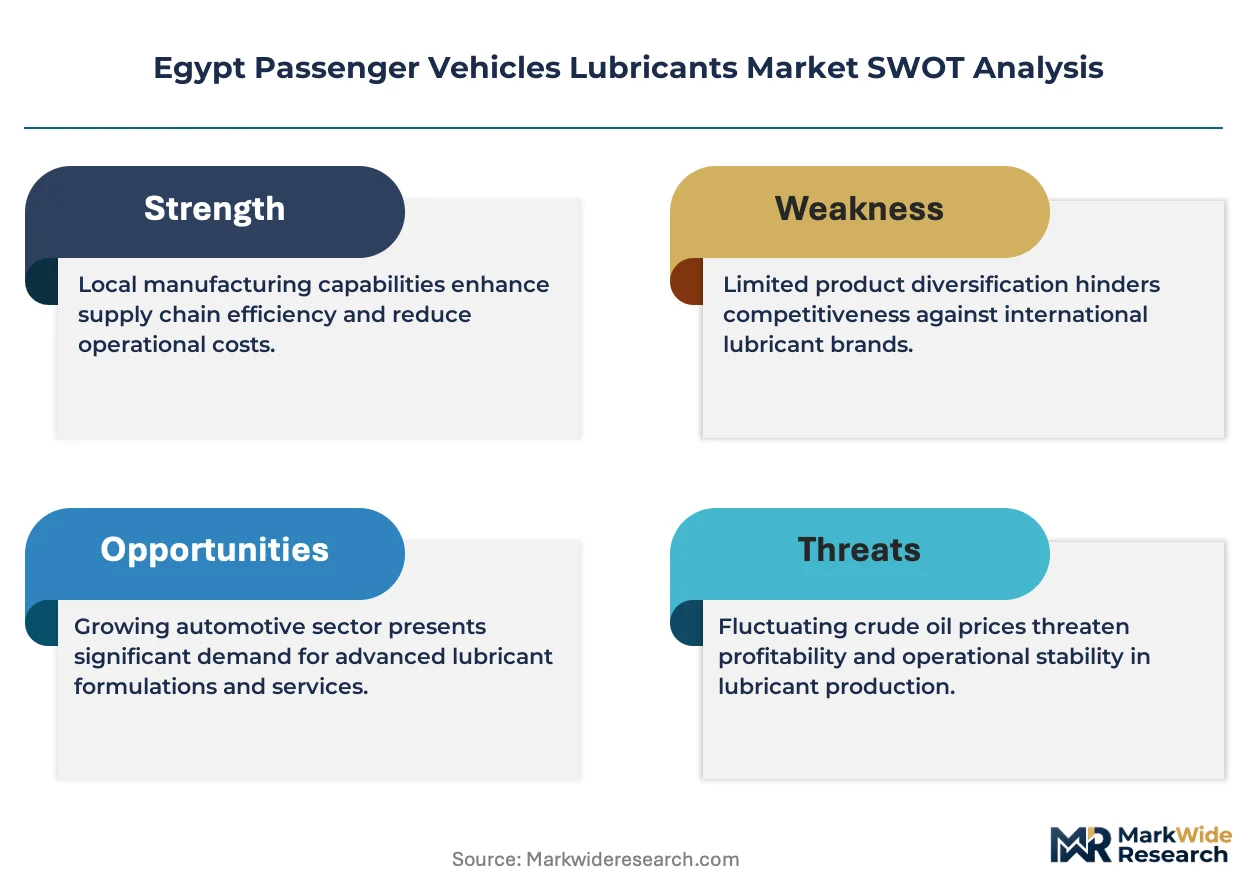
Egypt's passenger vehicle lubricants sector faces structural pressure from the Ministry of Petroleum and Mineral Resources' tightened import quality standards for base oils, forcing distributors to abandon informal supply channels and certify their sourcing.
Growth Catalysts
- Fleet operator procurement consolidation:Ride-hailing platforms and corporate leasing schemes are aggregating demand into annual supply contracts, creating predictable volume pipelines for blenders.
- API and ACEA compliance mandates:The General Authority for Standards and Quality enforces performance classifications that disqualify substandard imports, elevating certified product penetration.
- High-temperature synthetic formulations:Advanced additive packages engineered for Egyptian climatic conditions are extending drain intervals and reducing total cost of ownership for vehicle owners.
Market Restraints
- Base oil import dependence:Egypt's domestic refining capacity remains insufficient for Group II and III base stock requirements, exposing blenders to currency fluctuation and freight cost volatility.
- Waste oil collection infrastructure gaps:Ministry of Environment enforcement of national environmental law protocols lags in Upper Egypt and rural Delta governorates, creating compliance friction for nationwide distributors.
- Electrification substitution threat:Battery electric powertrains eliminate engine oil demand entirely, with Cairo and Alexandria ride-hailing fleets piloting EV conversions that remove lubricant consumption from high-utilization vehicles.
Strategic Opportunities
- Upper Egypt service network expansion:Vehicle density growth in Sohag, Assiut, and Qena outpaces lubricant retail presence, creating first-mover advantage for branded distributor partnerships with independent workshops.
- Dual-clutch and CVT transmission fluids:Specialized formulations for automated manual transmissions command per-liter margins significantly above conventional motor oils as Korean and European OEMs expand market share.
- Bio-based additive regulatory pathway:The Egyptian General Petroleum Corporation's coordination with international certifiers on evolving OEM specifications opens approval channels for renewable-derived friction modifiers.
Industry Challenges
- Technical talent scarcity in formulation chemistry:Blending facilities near Suez struggle to recruit additive package specialists capable of reverse-engineering competing synthetic products.
- Certification timeline compression:API SP and ILSAC GF-6A approval cycles for new product launches now exceed typical Egyptian distributor inventory financing horizons.
- Legacy workshop equipment incompatibility:Independent service stations in Alexandria and Port Said lack bulk fluid handling systems required for synthetic oil dispensing, constraining premium product penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Passenger Vehicles Lubricants Market |
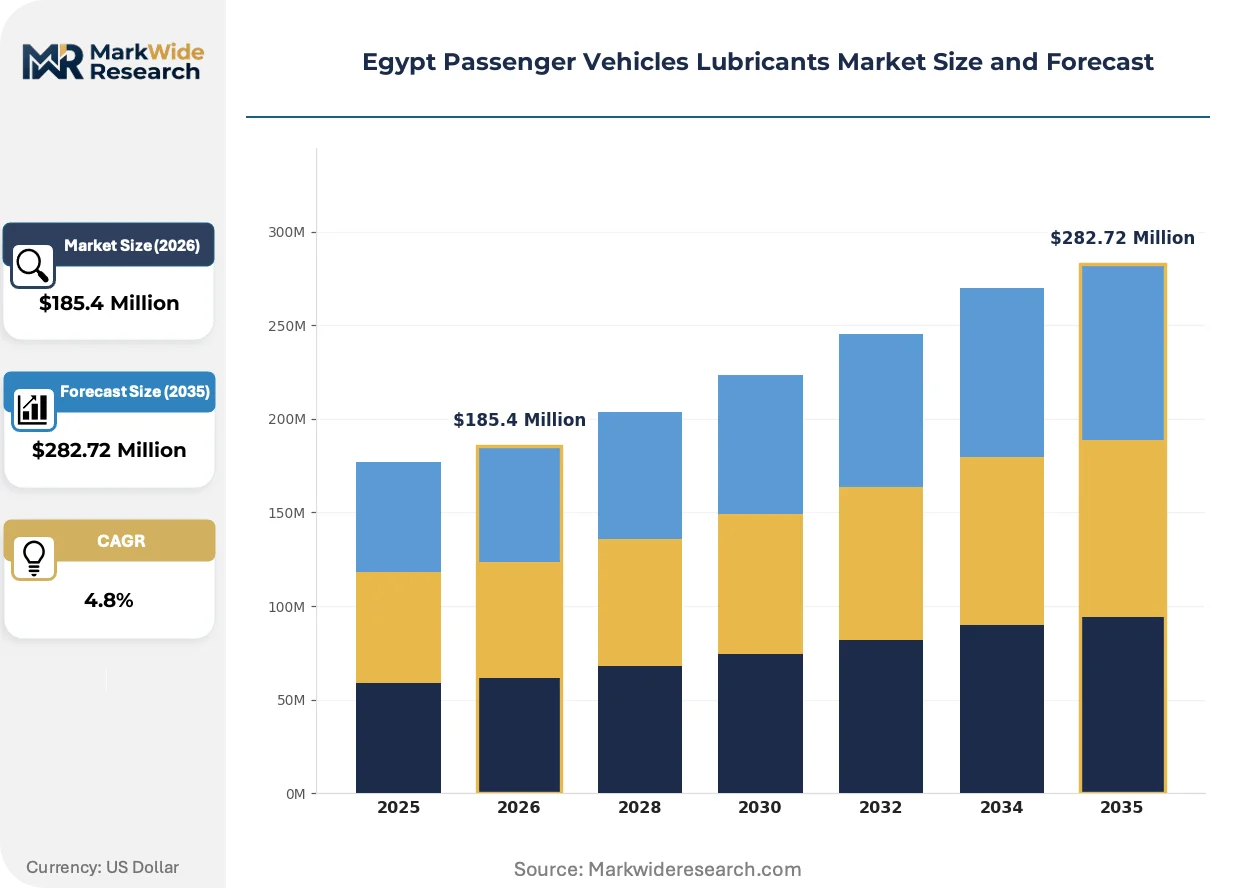
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $282.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Oil, Transmission Fluid, Grease, Additives Application: Engine Lubrication, Transmission, Chassis, Hydraulic Systems End User: Personal Use, Fleet Operators, Automotive Workshops, Dealerships Packaging Type: Bottles, Drums, Pails, Bulk |
| Companies Covered | Emarat, ExxonMobil Corporation, BP PLC (Castrol), Misr Petroleum, FUCHS, Chevron Corporation, ENOC Misr, Royal Dutch Shell PLC, Cooperative Societe des Petroleums, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation technology, regulatory alignment, and procurement restructuring are converging to reshape how lubricants reach Egyptian vehicle owners and fleet operators.
Low-viscosity synthetic motor oils are hybridizing conventional mineral-based supply chains. These SAE 0W-20 and 5W-30 formulations reduce cold-start wear and improve fuel economy in turbocharged direct-injection engines. Authorized dealership networks in Greater Cairo are mandating their use for warranty compliance, compressing demand for 20W-50 conventional grades that previously dominated the aftermarket.
Egypt's Ministry of Environment is tightening enforcement of waste oil collection protocols under national environmental law. This regulatory pressure is industrializing reverse logistics infrastructure, requiring distributors to invest in used fluid tracking systems and certified recycling partnerships. Fleet operators with centralized maintenance facilities face the steepest compliance costs, driving consolidation toward lubricant suppliers with integrated waste management capabilities.
Workshop-level purchasing is fragmenting as independent service stations bypass traditional distributors for direct importer relationships. Digital procurement platforms are displacing cash-based spot buying in Alexandria and Cairo, enabling smaller garages to access synthetic formulations previously reserved for dealership channels. This channel shift is most visible in corporate fleet maintenance contracts, where procurement managers now specify lubricant brands directly rather than delegating to workshop discretion.
Egypt Passenger Vehicles Lubricants Market Segmentation
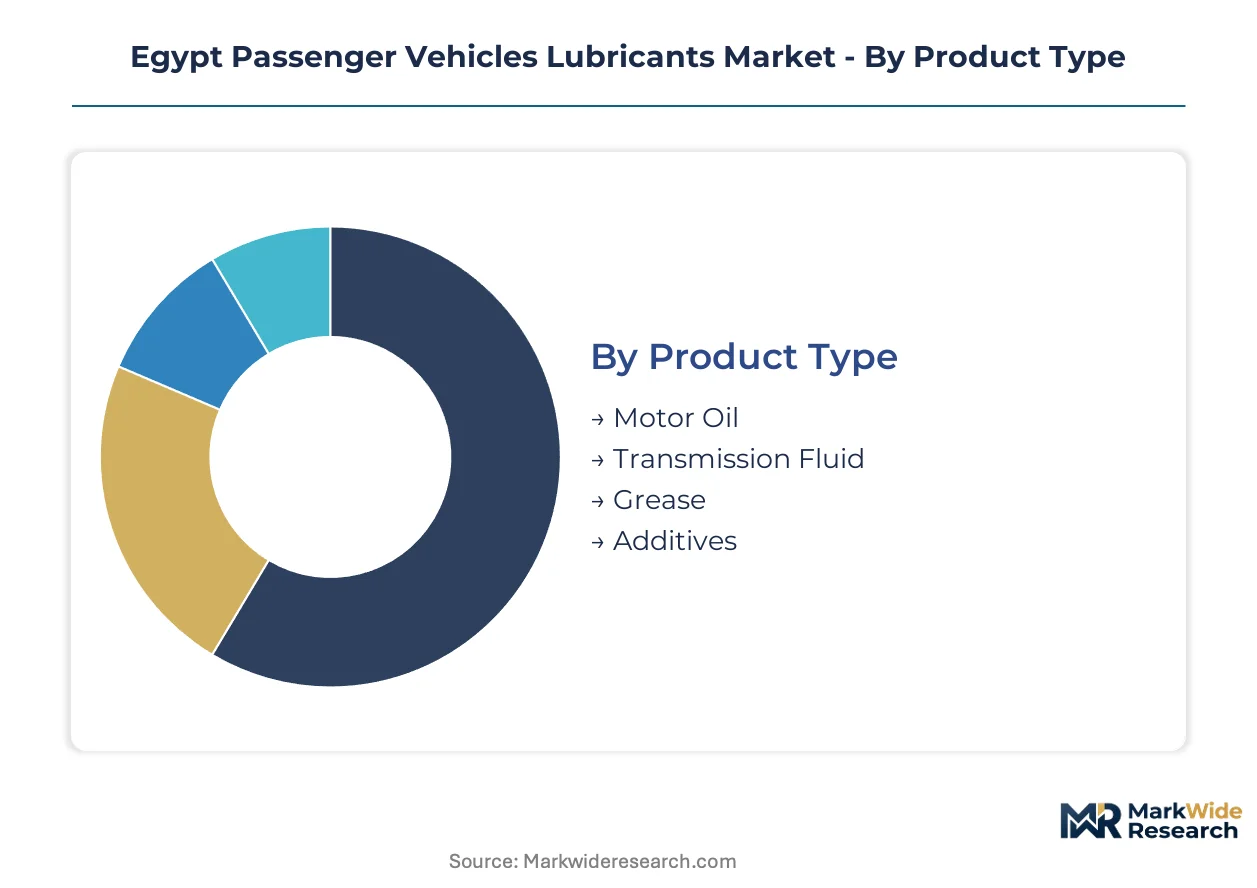
Egypt's lubricant market segments reflect divergent procurement logics across vehicle lifecycle stages and customer sophistication levels. Understanding these divisions clarifies why formulation investments concentrate in certain channels while margin compression hits others.
Product Type:
Use-case spectrum spans routine consumables through specialized functional fluids with distinct technical barriers and replacement economics.
- Motor Oil:Formulated from Group II/III base stocks with API SP or ACEA C3 additive packages to manage soot, oxidation, and wear in gasoline and diesel powertrains. Demand clusters in Greater Cairo's dealership service bays where OEM warranty compliance mandates certified drain intervals. Fleet operators with centralized maintenance facilities negotiate annual volume contracts that prioritize total cost of ownership over per-liter pricing.
- Transmission Fluid:Specialized low-viscosity synthetics for dual-clutch and CVT architectures requiring precise friction modification and shear stability. Korean and European OEM expansion in Alexandria drives per-liter margin premiums substantially above conventional motor oils. Technical specification complexity limits qualified blender competition.
- Grease:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, wheel bearings, and universal joints. Independent workshops in Upper Egypt favor economy-grade options for older vehicle parc maintenance.
- Additives:Supplementary packages including detergents, dispersants, and viscosity index improvers sold separately for aftermarket blending. Port Said distributors handle bulk importation for regional reconstitution.
Established volume favors motor oil; emerging adoption favors transmission fluid.
Application:
Functional criticality determines formulation investment intensity and certification requirements across vehicle systems.
- Engine Lubrication:High-shear environments in turbocharged direct-injection engines demand synthetic base stocks with enhanced thermal oxidative stability. Egyptian climatic conditions with ambient peaks exceeding 45°C accelerate additive depletion and shorten drain intervals versus temperate markets.
- Transmission:Automated manual and continuously variable architectures require precisely tuned friction coefficients for clutch engagement smoothness. Misr Petroleum and international majors compete on OEM approval acquisition speed.
- Chassis:Suspension and steering linkage lubrication using NLGI-grade greases with corrosion inhibition. Rural Delta agricultural vehicle conversions sustain steady demand.
- Hydraulic Systems:Power steering and brake fluid formulations with low compressibility and elastomer compatibility. Aftermarket substitution risk rises with brake-by-wire technology adoption.
Engine lubrication commands formulation R&D concentration; transmission applications generate steepest margin expansion.
End User:
Procurement sophistication separates price-sensitive spot purchasers from contract-negotiating volume aggregators with technical specification authority.
- Personal Use:Individual vehicle owners purchasing through retail channels or workshop delegation. Digital platforms in Cairo and Alexandria enable direct synthetic product access previously restricted to dealership networks.
- Fleet Operators:Ride-hailing platforms and corporate leasing schemes consolidating multi-vehicle maintenance into centralized procurement with waste oil collection compliance obligations. These operators represent the segment gaining share fastest as utilization rates rise and vehicle ownership models shift.
- Automotive Workshops:Independent service stations in Sohag, Assiut, and Qena with limited bulk fluid handling infrastructure. Cash-based spot buying persists despite platform penetration in coastal cities.
- Dealerships:Authorized OEM service networks mandating certified lubricants for warranty preservation. ExxonMobil and Shell anchor supply relationships through integrated service partnerships.
Fleet procurement consolidation favors branded distributors with compliance infrastructure; personal use channels fragment toward direct importer relationships.
Packaging Type:
Handling economics and consumption scale determine containerization choices from individual retail units through tanker-delivered bulk systems.
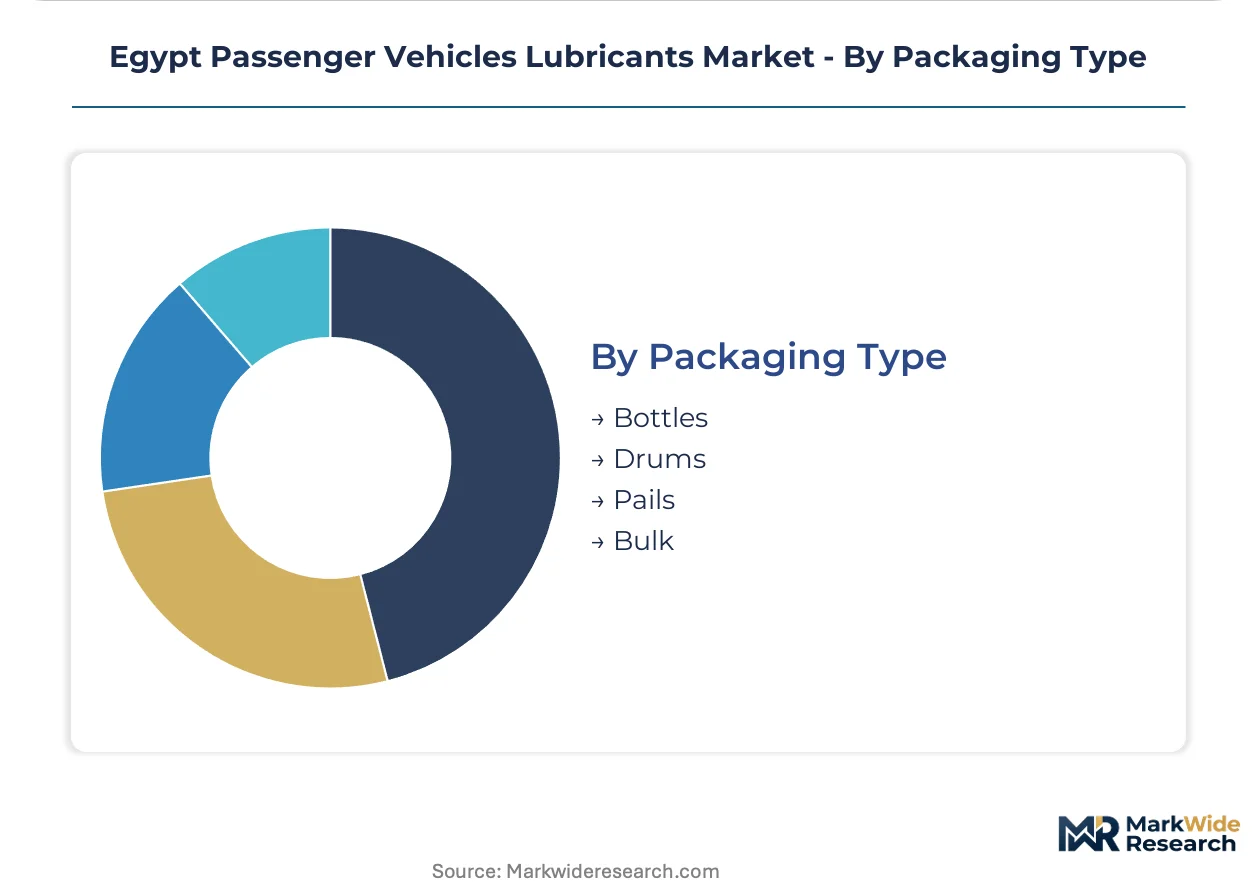
- Bottles:One-liter and four-liter retail formats for personal vehicle owners and small independent workshops. Alexandria and Port Said retail networks stock synthetic grades in response to OEM warranty awareness.
- Drums:Standard 200-liter steel containers for mid-volume workshops and fleet maintenance facilities. Suez Canal Economic Zone blending facilities optimize drum filling lines for this format.
- Pails:Intermediate 20-liter plastic containers for rural service stations with limited storage capacity. Upper Egypt distribution networks favor this format for logistics flexibility.
- Bulk:Tanker-delivered fluid for high-throughput dealership service centers and centralized fleet facilities. Requires investment in storage tanks and dispensing systems constraining penetration in legacy workshop infrastructure.
Drum and pail formats dominate current throughput; bulk infrastructure expansion favors dealership and fleet channels with capital deployment capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone anchors Egypt's lubricant distribution infrastructure, connecting Red Sea and Mediterranean shipping lanes to domestic blending capacity. This maritime corridor positions Egypt as a regional hub for base oil importation and formulated product re-export.
Greater Cairo
Ride-hailing fleet expansion and dealership service networks concentrate lubricant demand in Cairo and Giza governorates. The General Authority for Standards and Quality enforces API SP compliance at Port Sokhna entry points. Sixth of October City blending facilities supply synthetic formulations to authorized OEM workshops across the capital region.
Alexandria
European and Korean vehicle import volumes through Alexandria Port drive specialized transmission fluid requirements. The Ministry of Environment extends waste oil collection enforcement to coastal governorates under amended environmental law protocols. El Amreya industrial zone hosts bulk storage terminals serving dealership networks in the northern Delta.
Suez Canal Zone
Refinery investments near Ain Sokhna are narrowing Egypt's Group II and III base oil import dependence. The Egyptian General Petroleum Corporation coordinates blending facility certification with international OEM specifiers. Suez blending plants optimize drum and pail filling lines for Upper Egypt distribution networks.
Upper Egypt
Vehicle density growth in Sohag, Assiut, and Qena outpaces lubricant retail infrastructure development. Informal supply channels persist despite Ministry of Petroleum import quality standard tightening. Independent workshops in Minya and Beni Suef favor economy-grade grease and conventional motor oils for older vehicle parc maintenance.
Delta Region
Agricultural vehicle conversions and rural fleet operators sustain steady chassis lubricant demand across Damietta and Mansoura. Waste oil collection infrastructure gaps in rural governorates create compliance friction for nationwide distributors. Port Said handles bulk additive importation for regional reconstitution by mid-volume blenders.
Egypt Passenger Vehicles Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and additive package expertise. Egypt's passenger vehicle lubricants sector exhibits tiered concentration, with state-backed distributors leveraging infrastructure access while international majors compete on OEM certification speed. Three archetypes dominate: national oil companies with pipeline and terminal control, global majors with specification leadership, and regional traders with import flexibility. Competitive moves center on dealership network exclusivity agreements and waste oil collection service bundling.
Among state-aligned distributors, Misr Petroleum exemplifies the infrastructure-anchored archetype through its Upper Egypt and Delta coverage networks. ExxonMobil Corporation and Royal Dutch Shell PLC occupy positions on the premium formulation vector, with the former representing synthetic high-temperature performance positioning and the latter exemplifying integrated service partnership models with authorized dealership networks in Cairo and Alexandria.
| Leading Market Players |
|---|
| Emarat |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Misr Petroleum |
| FUCHS |
| Chevron Corporation |
| ENOC Misr |
| Royal Dutch Shell PLC |
| Cooperative Societe des Petroleums |
| Others |
Supply & Pricing Matrix
Base oil import dependence on Middle Eastern and European refiners exposes Egyptian blenders to currency fluctuation and freight cost volatility, compressing margin spreads between synthetic premium grades and economy mineral formulations while forcing distributors toward certified supply chains that elongate payment cycles.
Pricing Analysis
Volume-discount tiering structures separate annual contract fleet operators from spot-buying independent workshops across three performance tiers. Premium synthetic formulations carrying API SP certification command substantial markups over economy mineral oils due to OEM warranty compliance requirements and extended drain interval economics. Pricing pressure stems from informal import channels undercutting certified products in Upper Egypt and rural Delta governorates. Fleet operators with consolidated procurement demonstrate lowest price sensitivity, prioritizing total cost of ownership and waste oil collection compliance over per-liter expenditure.
Supply Chain Analysis
Supplier-financing facilities from regional base oil traders extend 90-120 day payment terms to Egyptian blenders, easing working capital strain amid Egyptian pound volatility. Group II and III base stocks draw from Saudi Arabian, UAE, and European refining capacity, with Suez Canal transit costs feeding into landed pricing. Single-source vulnerability concentrates in specialized additive packages from German and US chemical suppliers. Distribution runs through Misr Petroleum's state-backed terminal network for inland coverage, while Alexandria and Port Said handle direct importer relationships with coastal workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's passenger vehicle lubricants sector functions as a service-attach opportunity where waste oil collection compliance and fleet maintenance contracts expand faster than standalone product volumes, rewarding distributors with integrated environmental service capabilities.
For Market Incumbents: Entrench position by securing exclusive supply partnerships with ride-hailing platforms consolidating procurement into annual contracts, and accelerate backward integration into Group II base stock production through Suez Canal Economic Zone refinery investments. Battery electric vehicle substitution in Cairo and Alexandria fleets threatens engine oil demand from highest-utilization vehicles, making transmission fluid specialization and OEM certification speed critical defensive levers. For New Entrants and Emerging Players: Upper Egypt's Sohag-Assiut-Qena corridor offers white-space expansion where vehicle density growth outpaces branded retail presence and informal channels dominate. Target independent workshop partnerships with pail-format logistics flexibility and digital procurement platform access previously restricted to coastal markets. Lead with economy-grade grease and conventional motor oil positioning for older vehicle parc maintenance, then migrate certified synthetics through fleet operator relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors blending facility operators with Egyptian General Petroleum Corporation certification alignment and integrated waste management capabilities. Mid-term viability hinges on electrification-adjacent fluid development and bio-based additive regulatory pathway navigation. Monitor API SP and ILSAC GF-6A approval timeline compression as inflection indicator for formulation chemistry capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Suez Canal Economic Zone refinery investments reduce import dependence and currency exposure for Egyptian blenders. |
| Fleet Operator Annual Contract Securement | Ride-hailing platform consolidation creates predictable volume pipelines with waste oil collection compliance bundling. |
| Dual-Clutch and CVT Transmission Fluid Specialization | Korean and European OEM expansion in Alexandria drives per-liter margin premiums above conventional motor oils. |
| Upper Egypt Distribution Network Buildout | Vehicle density growth in Sohag and Assiut outpaces lubricant retail infrastructure, enabling first-mover positioning. |
| Integrated Waste Oil Collection Service Launch | Ministry of Environment enforcement industrializes reverse logistics requirements for nationwide distributor compliance. |
Research Methodology
A standing panel of blending facility operations managers, fleet procurement directors at ride-hailing platforms, independent workshop owners in Greater Cairo and Alexandria, and Egyptian General Petroleum Corporation certification specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through customs import records, API licensing databases, and Ministry of Environment enforcement disclosures. Bottom-up volume modeling from distributor shipment data triangulated against top-down refinery capacity and base oil import statistics.
Scenario-bracketing framed low, base, and high cases around electrification penetration speed in commercial fleets and regulatory enforcement intensity in Upper Egypt. Segmentation modeling spanned product type, application system, end-user procurement sophistication, and packaging format across the projection horizon. CAGRs derived from polynomial trend fitting to historical volume series adjusted for vehicle parc growth and drain interval extension effects from synthetic formulation adoption.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by regional traders or accelerated EV conversion subsidies would shift outcomes. Macroeconomic volatility in Egyptian pound valuation, regulatory transition to bio-based additive standards, or technological breakthrough in solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Electric Vehicle Brake Pad Market