
 WAN Connected Returnable Transport Asset Tracking Market | 2026-2036
WAN Connected Returnable Transport Asset Tracking Market Size, Share, and Industry Trends Forecast 2026-2036
WAN Connected Returnable Transport Asset Tracking Market Analytics
Third-party logistics channel control is tilting toward technology-integrated fleet operators as shippers demand real-time visibility across multi-modal networks. ORBCOMM leverages satellite-cellular hybrid networks to sustain coverage across remote distribution corridors. Zebra Technologies anchors enterprise-grade RFID deployments through dense manufacturing plant installations. Honeywell competes on sensor miniaturization for harsh-environment container tracking.
WAN Connected Returnable Transport Asset Tracking encompasses cellular, satellite, and low-power wide-area network devices affixed to reusable shipping assets, transmitting location, environmental condition, and utilization data through cloud-based platforms with refresh intervals typically ranging from one minute to hourly depending on connectivity cost structures. The primary purpose is eliminating asset loss, reducing pool shrinkage, and enabling circular supply chain economics through automated return-loop reconciliation. RFID and IoT Sensors represent the fastest-expanding technology pairing as passive identification merges with active condition monitoring in pharmaceutical and cold-chain applications. Pallets and Containers dominate product-type value pools where high unit volumes justify per-asset connectivity investment against replacement costs.
FDA traceability rules under the Food Safety Modernization Act and EU REACH chemical transport documentation requirements are mandating granular asset-level records across food and hazardous materials flows. FCC equipment authorization processes and CE marking under the Radio Equipment Directive shape hardware market access timelines for North American and European deployments. Stakeholders must weigh proprietary network lock-in against emerging open-standards interoperability as procurement specifications evolve.
Market Dynamics
Cellular-to-satellite handoff architectures are compressing connectivity dead zones across intermodal corridors, forcing hardware vendors to redesign power budgets and antenna configurations for seamless roaming between terrestrial and orbital networks.
Growth Catalysts
- EU Digital Product Passport:Mandatory traceability documentation under this framework compels automotive and electronics manufacturers to instrument returnable packaging with persistent identifiers, expanding addressable hardware demand across German and French industrial zones.
- Pharmaceutical cold chain integrity:FDA Food Safety Modernization Act enforcement drives deployment of temperature-logging trackers on reusable thermal shippers, particularly for vaccine distribution networks requiring excursion-proof documentation.
- East Asian manufacturing corridor density:Just-in-time assembly operations in Vietnam's northern industrial provinces and China's Pearl River Delta generate concentrated demand for sub-minute location refresh rates on high-velocity container pools.
Market Restraints
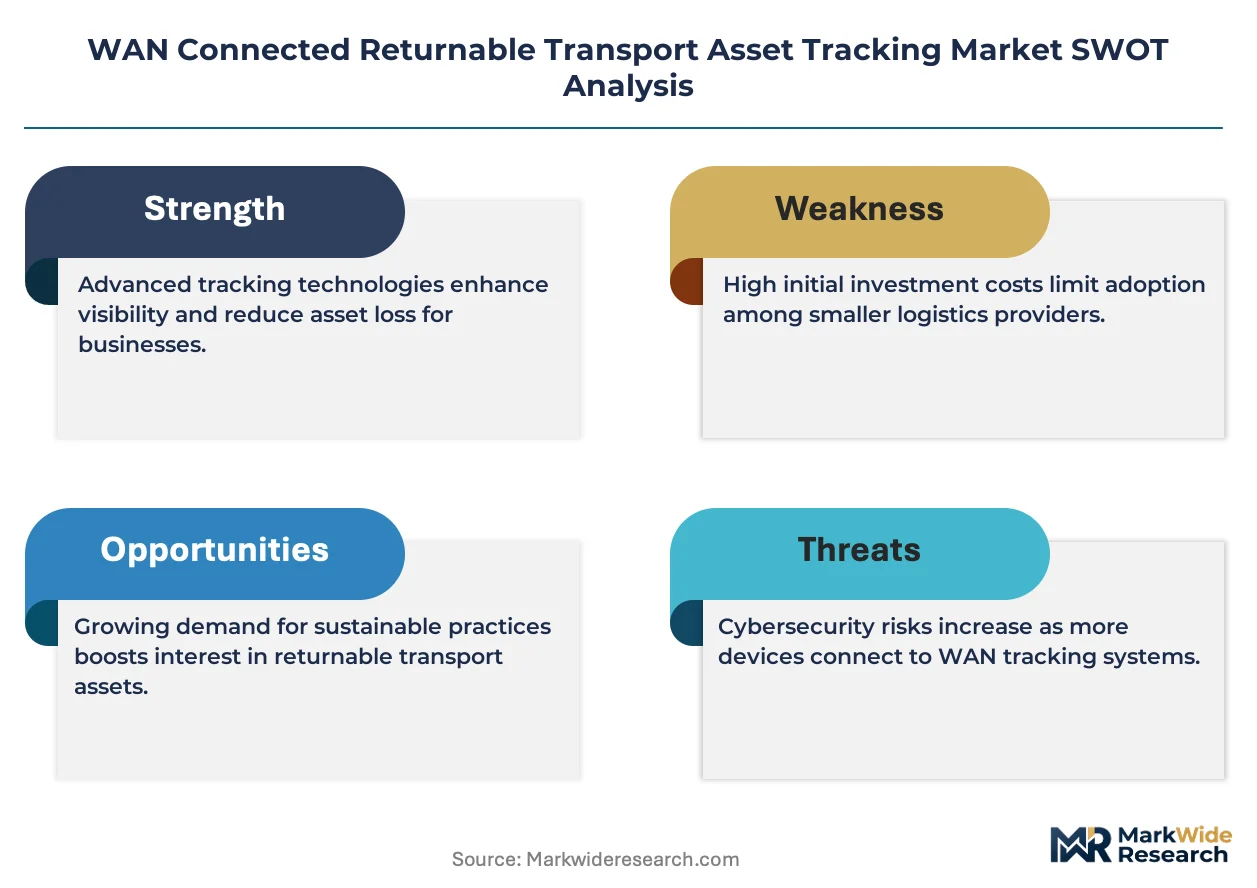
- Lithium battery supply concentration:Cell production for tracker power modules clusters in Chinese and South Korean facilities, exposing hardware vendors to input cost volatility and export license uncertainty.
- Radio Equipment Directive compliance friction:CE marking timelines for multi-band cellular modules extend hardware certification cycles by four to six months, delaying European market entry for non-established suppliers.
- Passive RFID substitution in low-value assets:Pallet pools below replacement cost thresholds increasingly deploy chipless acoustic or optical identification, capping connectivity penetration in commodity logistics segments.
Strategic Opportunities
- Indian pharmaceutical export corridors:Cold-chain infrastructure gaps between Mumbai port and inland formulation plants create whitespace for satellite-backhauled environmental monitors on insulin and biologic shipping containers.
- Battery logistics standardization:UN 38.3 lithium transport certification mandates are expanding to cover returnable battery racks, opening dedicated tracker categories with integrated gas detection and thermal runaway alerting.
- Low-power wide-area convergence:NB-IoT and LoRaWAN module cost parity with 2G legacy hardware enables hybrid deployments where cellular density gaps are patched with unlicensed spectrum fallback.
Industry Challenges
- RF engineering talent scarcity:Competent antenna designers capable of optimizing radiation patterns for metal-container environments command premium compensation, constraining hardware startup scaling.
- Enterprise resource planning integration complexity:Tracker data streams must reconcile with SAP and Oracle warehouse management modules through custom middleware, extending deployment timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | WAN Connected Returnable Transport Asset Tracking Market |
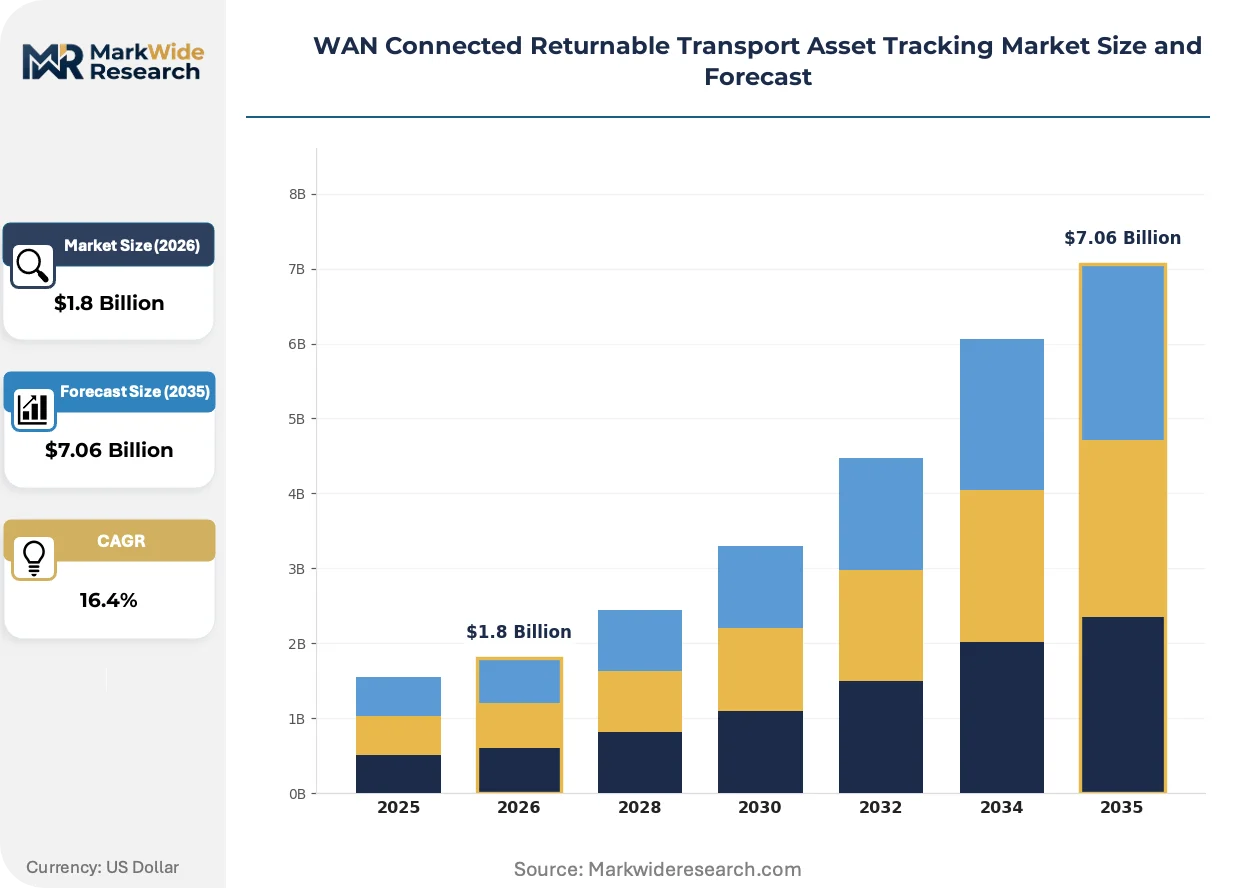
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Crates, Containers, Reusable Packaging Technology: RFID, GPS, IoT Sensors, Wireless Tracking End User: Manufacturing, Retail, Logistics, Food & Beverage Application: Inventory Management, Supply Chain Optimization, Asset Monitoring, Fleet Management |
| Companies Covered | ORBCOMM, Zebra Technologies, Roambee, IBM, Honeywell, Sensitech, AssetFlo, Savi Technology, Tive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
WAN Connected Returnable Transport Asset Tracking Market Evolving Landscape
Asset intelligence architectures are bifurcating between high-refresh cellular endpoints for premium cargo and ultra-low-power satellite messengers for remote infrastructure, compressing the viable design space for mid-tier connectivity solutions.
Edge preprocessing capabilities are migrating from centralized cloud platforms to tracker-local microcontrollers, enabling anomaly detection and geofence alerting without persistent backhaul. Automotive tier-one suppliers in Stuttgart and Detroit are piloting these architectures for inbound parts sequencing, reducing data transmission costs by filtering redundant location reports. The structural consequence is a hardware bill-of-materials shift toward more powerful ARM-based chipsets and away from simple modem-on-a-board designs.
REACH chemical transport documentation amendments now mandate container-level substance history records for hazardous material flows, extending retention requirements from shipment duration to full asset lifecycle. German chemical conglomerates and Rotterdam port operators are deploying blockchain-anchored tracker logs to satisfy audit trails. Battery electrolyte and agrochemical segments face the steepest compliance burdens, driving consolidation around vendors offering ten-year data archival guarantees.
Shippers are unbundling fleet visibility from carrier contracts, procuring standalone tracking subscriptions direct from hardware-platform vendors and demanding API-native integration with their control towers. This disintermediation is most pronounced in North American automotive inbound logistics, where OEMs bypass 3PL data layers to capture raw telemetry from supplier-managed container pools. The practice compresses carrier margin capture and forces asset owners to subsidize connectivity hardware that was previously bundled in freight rates.
WAN Connected Returnable Transport Asset Tracking Market Segmentation
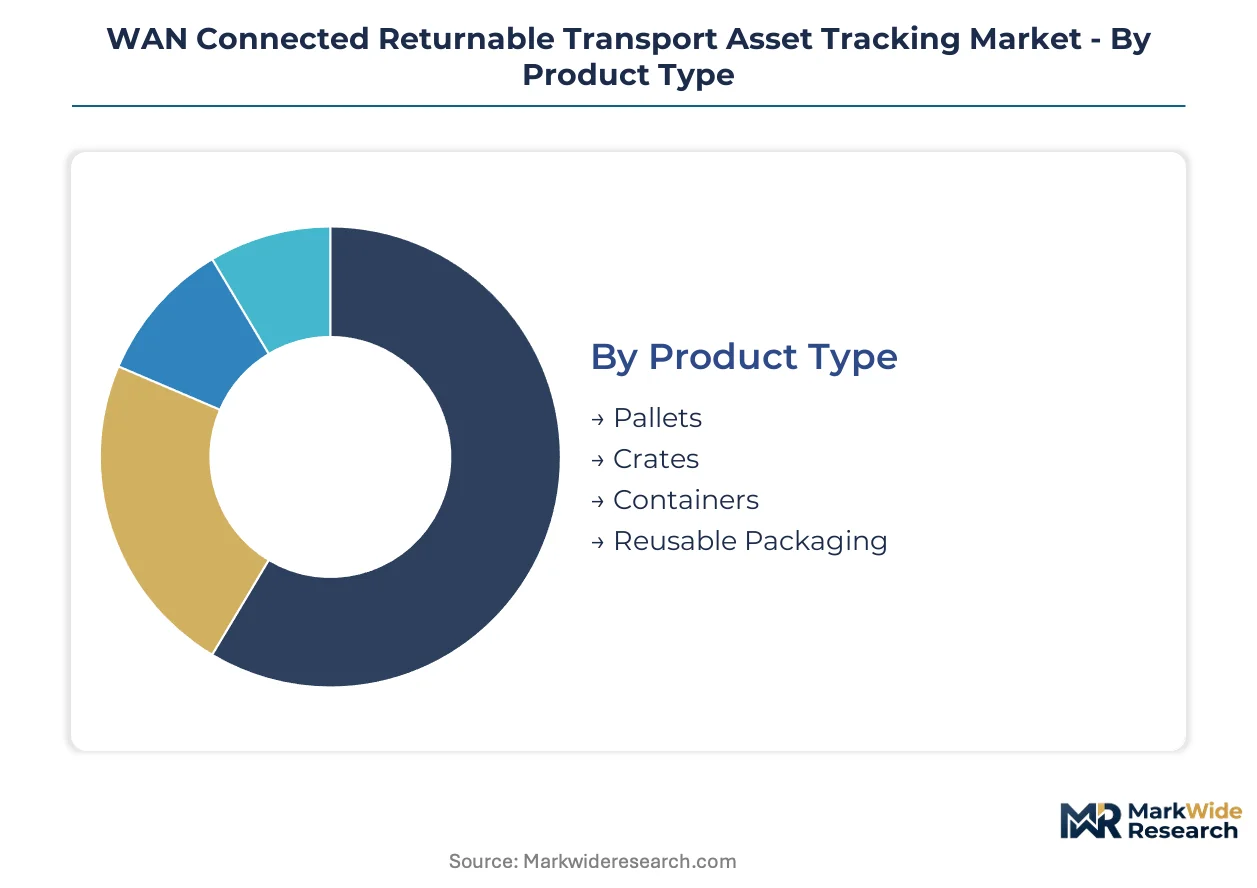
Segmentation in WAN connected returnable transport asset tracking reveals how hardware specifications, connectivity protocols, and operational intensity vary across asset classes and customer workflows. Procurement patterns diverge sharply between high-velocity manufacturing pools and long-dwell retail networks, forcing vendors to modularize platform architectures.
Product Type:
The use-case spectrum spans from lightweight, high-turnover units to capital-intensive, long-lifecycle containers with integrated power and sensing modules.
- Pallets:Wooden and composite platforms dominate unit volumes in fast-moving consumer goods distribution. German automotive suppliers and Vietnamese electronics manufacturers deploy cellular-enabled pallets for just-in-time sequencing, though passive RFID substitution pressures connectivity attachment rates in commodity segments.
- Containers:Steel and composite intermodal boxes justify the highest per-unit hardware investment through integrated GPS, accelerometers, and door sensors. Pharmaceutical cold-chain operators in the United States and EU mandate temperature-logging variants under FDA and EMA distribution guidelines.
- Crates:Rigid plastic totes serve closed-loop retail and agricultural harvesting operations with lower shock tolerance requirements. European grocery chains favor reusable crate pools with basic RFID identification over active tracking due to cost thresholds.
- Reusable Packaging:Custom-engineered dunnage and protective housings for fragile components span automotive glass, electronics modules, and medical devices. Battery logistics standardization under UN 38.3 certification is expanding demand for gas-detection-integrated variants in lithium transport.
The dominant share belongs to Containers, while Reusable Packaging is closing the gap fastest through specialized hazardous material compliance requirements.
Technology:
Cost tier stratification separates passive identification from active monitoring, with hybrid architectures emerging at the boundary.
- IoT Sensors:Multi-modal devices combining location, temperature, humidity, and shock detection anchor premium cold-chain and pharmaceutical applications. FDA Food Safety Modernization Act enforcement drives deployment on vaccine distribution thermal shippers requiring excursion-proof documentation.
- RFID:Passive UHF and HF tags provide identification without power consumption for high-volume, low-margin asset pools. Chipless acoustic and optical alternatives are displacing silicon-based tags in commodity pallet segments below connectivity cost thresholds.
- GPS:Satellite positioning modules deliver meter-level accuracy for yard management and intermodal handoff verification. FCC equipment authorization timelines and CE marking under the Radio Equipment Directive extend hardware certification cycles for multi-band cellular-GPS combinations.
- Wireless Tracking:Encompasses proprietary mesh, low-power wide-area, and satellite-backhauled protocols for coverage extension beyond cellular density. ORBCOMM and similar operators leverage hybrid satellite-cellular networks to sustain visibility across remote distribution corridors.
IoT Sensors command the premium tier by margin, with RFID retaining volume leadership despite passive substitution headwinds.
End User:
Application maturity varies by sector data infrastructure and regulatory compliance burden.
- Logistics:Third-party and fourth-party operators aggregate multi-shipper visibility demands, driving API-native platform requirements and disintermediating carrier-bundled tracking services.
- Manufacturing:Automotive and electronics assembly plants instrument inbound parts sequencing with sub-minute refresh rates, compressing hardware power budgets and antenna configurations for metal-container environments.
- Food & Beverage:Perishable distribution networks face FDA traceability mandates and EU food safety documentation requirements, mandating granular asset-level records with extended retention periods.
- Retail:Closed-loop packaging pools between distribution centers and stores prioritize basic identification over environmental monitoring, constraining connectivity penetration in high-volume, low-complexity flows.
Logistics channels aggregate the broadest deployment scale, though Manufacturing exhibits the steepest expansion trajectory through just-in-time operational mandates.
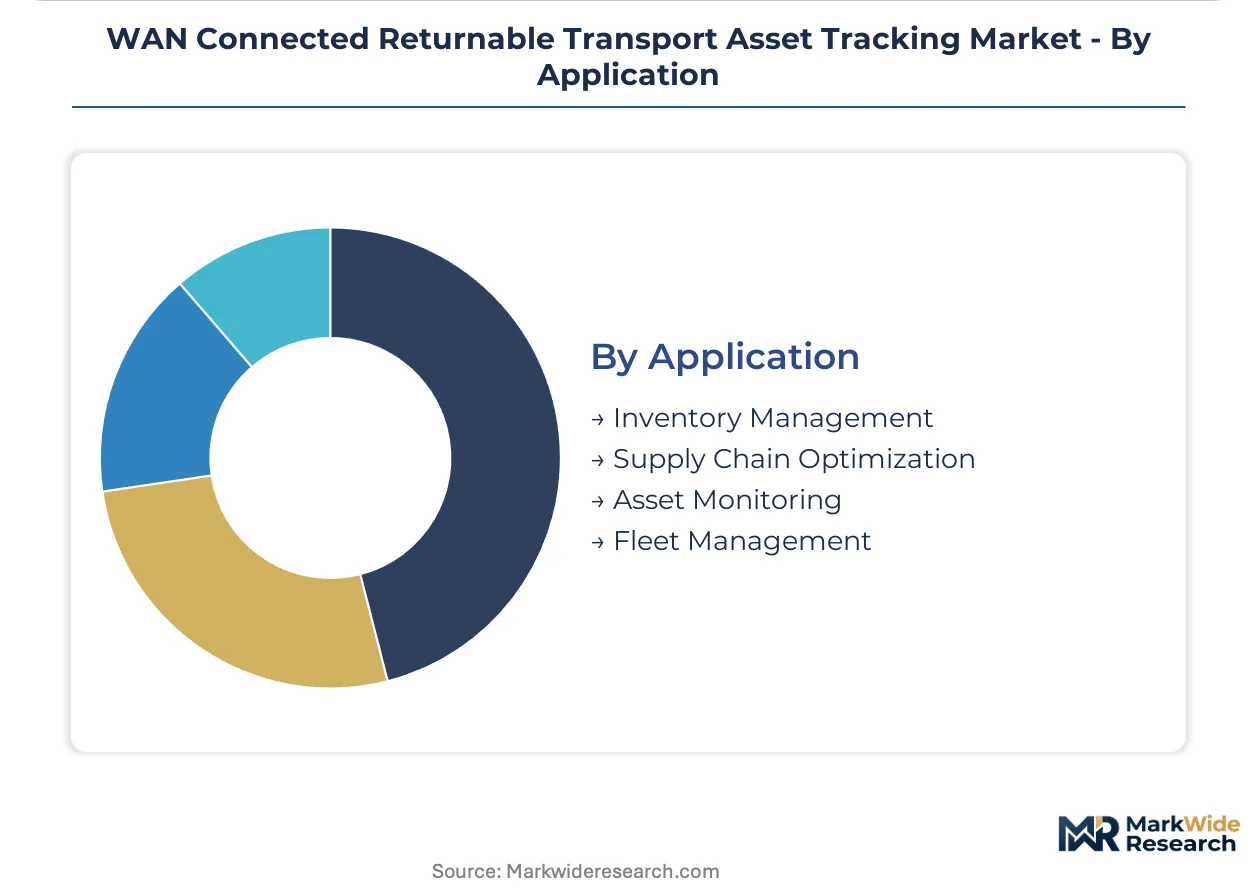
Application:
Functional priority shifts from cost avoidance to revenue protection across the deployment spectrum.
- Asset Monitoring:Real-time location and condition surveillance prevents loss, damage, and unauthorized diversion in high-value container pools. German chemical conglomerates deploy blockchain-anchored tracker logs to satisfy REACH documentation amendments requiring container-level substance history records.
- Supply Chain Optimization:Velocity analytics and dwell-time reduction drive working capital efficiency in automotive and electronics corridors. East Asian manufacturing clusters in China's Pearl River Delta and Vietnam's northern industrial provinces generate concentrated demand for precision asset visibility.
- Inventory Management:Automated reconciliation of return loops eliminates manual counting and accelerates pool turnaround. Enterprise resource planning integration complexity with SAP and Oracle warehouse management modules extends deployment timelines through custom middleware requirements.
- Fleet Management:Carrier and shipper coordination through shared visibility platforms compresses detention and demurrage exposure. North American automotive OEMs increasingly bypass 3PL data layers to capture raw telemetry from supplier-managed container pools.
Asset Monitoring captures the highest per-unit value, while Supply Chain Optimization is gaining share fastest through circular economy and sustainability reporting pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's intermodal rail links anchor European container tracking deployment, while Vietnam's Cai Mep-Thi Vai deepwater complex underwrites Southeast Asian manufacturing corridor visibility. These infrastructure nodes concentrate hardware demand across automotive, pharmaceutical, and electronics supply chains.
United States
Automotive OEMs in Detroit and pharmaceutical distributors in New Jersey drive cellular-enabled container deployment for inbound parts sequencing and cold-chain integrity. FDA Food Safety Modernization Act enforcement mandates temperature-logging documentation on reusable thermal shippers. The Port of Long Beach handles tracker-equipped container volumes for Pacific Rim electronics imports.
Germany
REACH chemical transport amendments require container-level substance history records across hazardous material flows. The EU Digital Product Passport framework compels automotive manufacturers in Stuttgart and Wolfsburg to instrument returnable packaging with persistent identifiers. Bavarian chemical conglomerates deploy blockchain-anchored tracker logs for audit compliance.
China
Just-in-time assembly operations in the Pearl River Delta generate concentrated demand for sub-minute location refresh rates on high-velocity container pools. MIIT radio equipment certification shapes hardware market access timelines for domestic and imported trackers. Shenzhen electronics manufacturers integrate satellite-cellular hybrid modules for export corridor visibility.
Vietnam
Northern industrial provinces around Hai Phong and Bac Ninh attract electronics assembly investment requiring precision asset visibility for just-in-time delivery. The country's national logistics regulator advances cold-chain infrastructure standards for pharmaceutical exports. Samsung supplier parks in Thai Nguyen deploy connected tracking systems on reusable component containers.
India
Cold-chain infrastructure gaps between Mumbai port and inland pharmaceutical formulation plants create demand for satellite-backhauled environmental monitors. CDSCO distribution guidelines tighten traceability requirements on insulin and biologic shipping containers. Pune and Hyderabad formulation clusters pilot connected returnable packaging for export compliance.
WAN Connected Returnable Transport Asset Tracking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF modules, sensors, and power management chips. The vendor base stratifies between enterprise-grade fleet operators and hardware-agnostic software layers. Three archetypes dominate: satellite-cellular hybrid network operators, dense manufacturing plant RFID deployers, and sensor miniaturization specialists for harsh-environment applications. Competitive moves center on API-native platform development and strategic partnerships with automotive tier-one suppliers.
Within the network operator archetype, ORBCOMM anchors satellite-cellular hybrid coverage for remote distribution corridors. Zebra Technologies exemplifies the enterprise RFID deployment model through manufacturing plant instrumentation. Honeywell occupies a position in sensor miniaturization for harsh-environment container tracking, representing the specialized hardware tier.
| Leading Market Players |
|---|
| ORBCOMM |
| Zebra Technologies |
| Roambee |
| IBM |
| Honeywell |
| Sensitech |
| AssetFlo |
| Savi Technology |
| Tive |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese lithium-cell manufacturing facilities is compressing module costs for tracker power systems while simultaneously eroding supplier margins and forcing tiered pricing differentiation based on certification grade and volume commitment tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hardware procurement, with CE-marked cellular modules commanding substantial premiums over uncertified alternatives due to Radio Equipment Directive compliance timelines. Price differentiation hinges on certification level and volume scale, with automotive OEM procurement pools leveraging thousand-unit commitments for standard-tier hardware while pharmaceutical cold-chain operators absorb premium pricing for FDA-validated temperature-logging variants. Cost compression in the economy tier is intensifying because chipless acoustic RFID alternatives are displacing silicon-based tags in commodity pallet segments. Third-party logistics operators exhibit the highest price sensitivity, whereas pharmaceutical distributors demonstrate minimal elasticity given regulatory documentation mandates.
Supply Chain Analysis
Upstream feedstock for tracker power modules draws from Chinese and South Korean lithium-cell facilities, with RF semiconductor fabrication concentrated in Taiwan and Malaysia. Critical component inputs include multi-band cellular modems, GPS receivers, and ARM-based microcontrollers for edge preprocessing capabilities. Single-source vulnerability in Chinese rare-earth magnet supply for antenna assemblies exposes hardware vendors to export license uncertainty. Distribution runs through contract electronics manufacturers in Shenzhen and Ho Chi Minh City, with final assembly gravitating toward proximity with German automotive and Vietnamese electronics manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU Digital Product Passport mandates and FDA traceability rules create structural switching costs that cement incumbent positions.
For Market Incumbents: Harden API-native platform architectures against disintermediation threats from shipper-direct procurement models bypassing 3PL data layers. Deepen backward integration into satellite-cellular hybrid network infrastructure to defend margin position against emerging low-power wide-area module cost parity. Prioritize certification investment for UN 38.3 lithium transport gas-detection variants to capture battery logistics standardization tailwinds. For New Entrants and Emerging Players: Pursue whitespace in Indian pharmaceutical export corridors where cold-chain infrastructure gaps between Mumbai port and inland formulation plants demand satellite-backhauled environmental monitors. Target the reusable packaging segment for hazardous material compliance, where REACH chemical transport documentation amendments mandate container-level substance history records with ten-year data archival guarantees. Lead with blockchain-anchored tracker logs as a differentiated audit-trail offering for German chemical conglomerates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among satellite-cellular hybrid network operators with enterprise-grade manufacturing plant deployments, suggesting superior long-term viability over hardware-agnostic software layers across a five-to-ten-year window. Acquisition targets should center on RF engineering talent-dense specialists capable of optimizing radiation patterns for metal-container environments. The signal to monitor is cellular-to-satellite handoff architecture adoption rates among automotive tier-one suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Integration | Enables shipper-direct telemetry capture bypassing 3PL data intermediation layers. |
| Satellite-Cellular Hybrid Network Expansion | Sustains coverage across remote distribution corridors where cellular density gaps persist. |
| Edge Preprocessing Capability Migration | Reduces data transmission costs through ARM-based microcontroller anomaly detection. |
| Blockchain-Anchored Data Archival | Satisfies REACH documentation amendments requiring full asset lifecycle retention. |
| UN 38.3 Gas-Detection Module Certification | Captures lithium battery logistics standardization mandates for thermal runaway alerting. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, FCC equipment authorization filings, and EU Radio Equipment Directive certification databases. Interviews with hardware platform engineering directors, automotive tier-one supplier procurement leads, pharmaceutical cold-chain logistics managers, and third-party fleet operations heads inform demand-side validation. Bottom-up unit shipment estimates triangulate against top-down addressable hardware spend analysis across German automotive, Vietnamese electronics, and Indian pharmaceutical export corridors.
Forecast inputs encompass connectivity protocol adoption curves, regulatory compliance timeline acceleration, and lithium-cell cost trajectories across the projection horizon. Segmentation dimensions modeled include asset class, technology pairing, end-use vertical, and regional manufacturing cluster intensity. CAGRs derive from installed base turnover rates and replacement cycle compression in high-velocity container pools. Industry-specific inputs incorporate FDA Food Safety Modernization Act enforcement pacing and EU Digital Product Passport implementation phasing.
Sensitivities concentrate around MIIT radio equipment certification delays, lithium battery export license restrictions, and passive RFID substitution acceleration in commodity logistics segments. Cross-checking against semiconductor foundry capex disclosures and cellular module shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market