
 Automotive Fluid Reservoir Market | 2026-2036
Automotive Fluid Reservoir Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fluid Reservoir Market Analytics
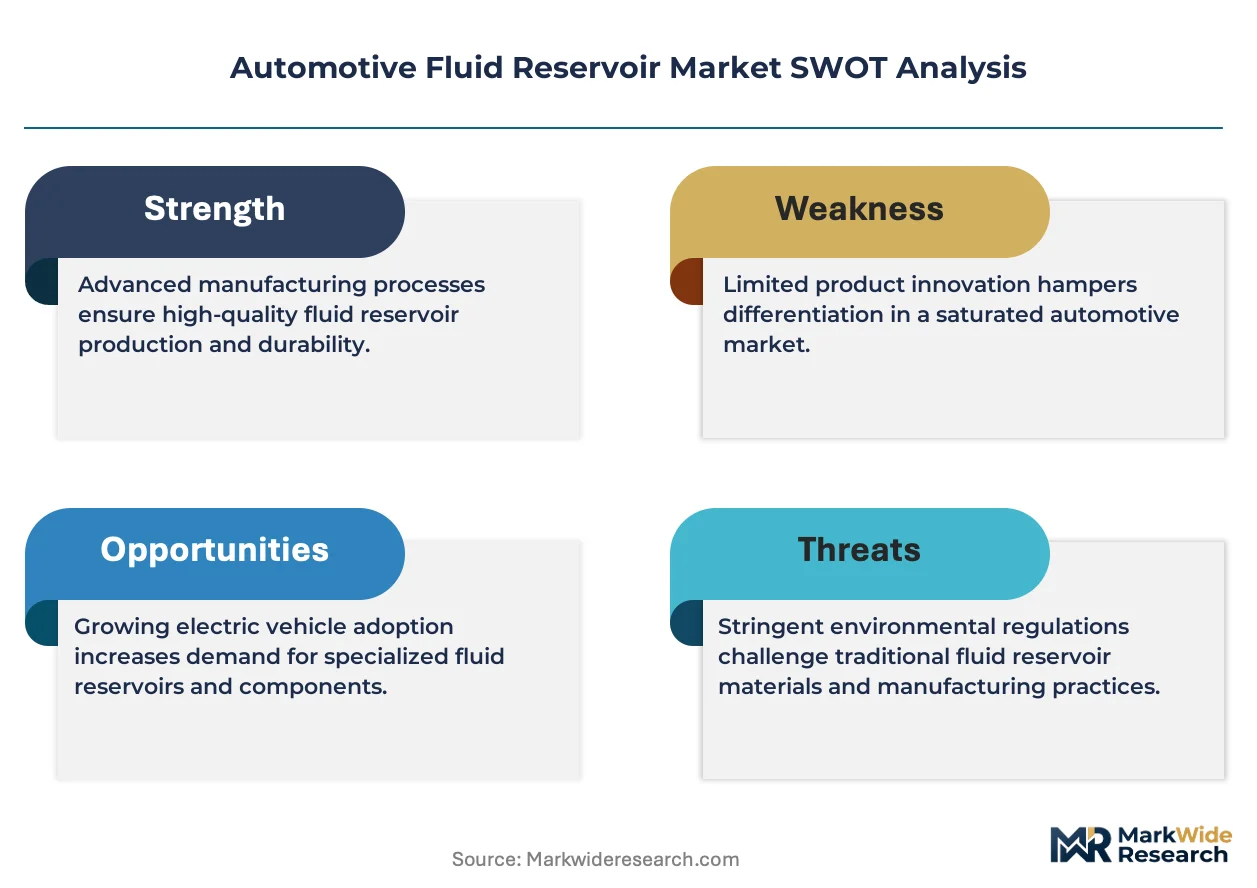
Polypropylene is restructuring cost structures across fluid reservoir manufacturing as OEMs displace heavier metal tanks. TI Fluid Systems leverages captive blow-molding capacity to anchor European supply chains for thermal management reservoirs. Continental AG sustains R&D intensity in integrated sensor-embedded reservoir designs. MANN+HUMMEL dominates filtration-coupled reservoir systems for commercial vehicle platforms.
Automotive fluid reservoirs are sealed containment vessels engineered from blow-molded thermoplastics, stamped steel, or fiber-reinforced composites, designed to store and regulate coolant, brake fluid, washer fluid, or urea solution within specified pressure and temperature tolerances. Plastic reservoir variants lead unit volume due to corrosion resistance and design flexibility, while composite materials represent the fastest-expanding margin pool as electrified powertrains impose stricter thermal cycling demands. OEM direct supply channels capture the dominant value share, though aftermarket providers compete on replacement-cycle predictability for aging internal-combustion fleets.
EPA Corporate Average Fuel Economy standards and EU F-Gas Regulation constrain material selections and permeation rates across reservoir designs. NHTSA brake-fluid specifications and ECE R34 fuel-system integrity rules dictate crashworthiness testing protocols for tank mounting and rupture resistance. Stakeholders must monitor how battery-electric thermal architectures redefine reservoir count, capacity, and fluid chemistry requirements.
Market Dynamics
The electrification of vehicle powertrains is restructuring fluid reservoir specifications as thermal management architectures multiply coolant circuit complexity. Battery electric platforms now demand reservoirs engineered for dielectric fluids and aggressive thermal cycling profiles that legacy internal-combustion designs cannot accommodate.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Automakers face escalating penalties for fleet inefficiency, compelling adoption of lightweight blow-molded reservoirs that reduce vehicle mass and improve thermal efficiency ratings.
- Polypropylene material substitution:OEM procurement teams are displacing stamped steel tanks with corrosion-resistant thermoplastic variants that enable complex geometries and integrated sensor mounting points.
- German thermal management redesign:Volkswagen Group and BMW are consolidating coolant circuit architectures around centralized reservoir modules, concentrating demand for high-capacity multi-chamber designs in Baden-Württemberg and Bavaria supplier clusters.
Market Restraints
- Polypropylene resin price volatility:Feedstock costs tied to propylene monomer supply from Gulf Coast petrochemical complexes create margin compression for blow-molding specialists without long-term supply agreements.
- Tooling amortization burdens:Complex multi-cavity molds for integrated sensor-embedded reservoirs require capital commitments exceeding standard reservoir platforms, disadvantaging smaller Tier 2 suppliers.
- Aluminum tank substitution in commercial vehicles:Heavy-duty truck fleets retain metal reservoirs for extreme-duty thermal cycling, capping thermoplastic penetration in the highest-margin segment.
Strategic Opportunities
- India PLI scheme for auto components:Component manufacturers can access production-linked incentives by establishing localized blow-molding capacity for domestic electric vehicle programs from Tata Motors and Mahindra.
- Sensor-reservoir integration:Convergence of IoT-enabled level sensing with blow-molded housings creates aftermarket revenue streams through predictive maintenance data services.
- EU F-Gas Regulation phase-down:Refrigerant containment requirements for heat pump thermal systems are mandating secondary reservoir barriers, expanding addressable content per vehicle.
Industry Challenges
- Multi-material bonding expertise:Reservoir suppliers lack sufficient polymer welding and overmolding specialists to execute sensor-embedded designs at production scale.
- ISO 26262 functional safety certification:Coolant level sensing for battery thermal management requires ASIL-rated validation timelines that extend development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fluid Reservoir Market |
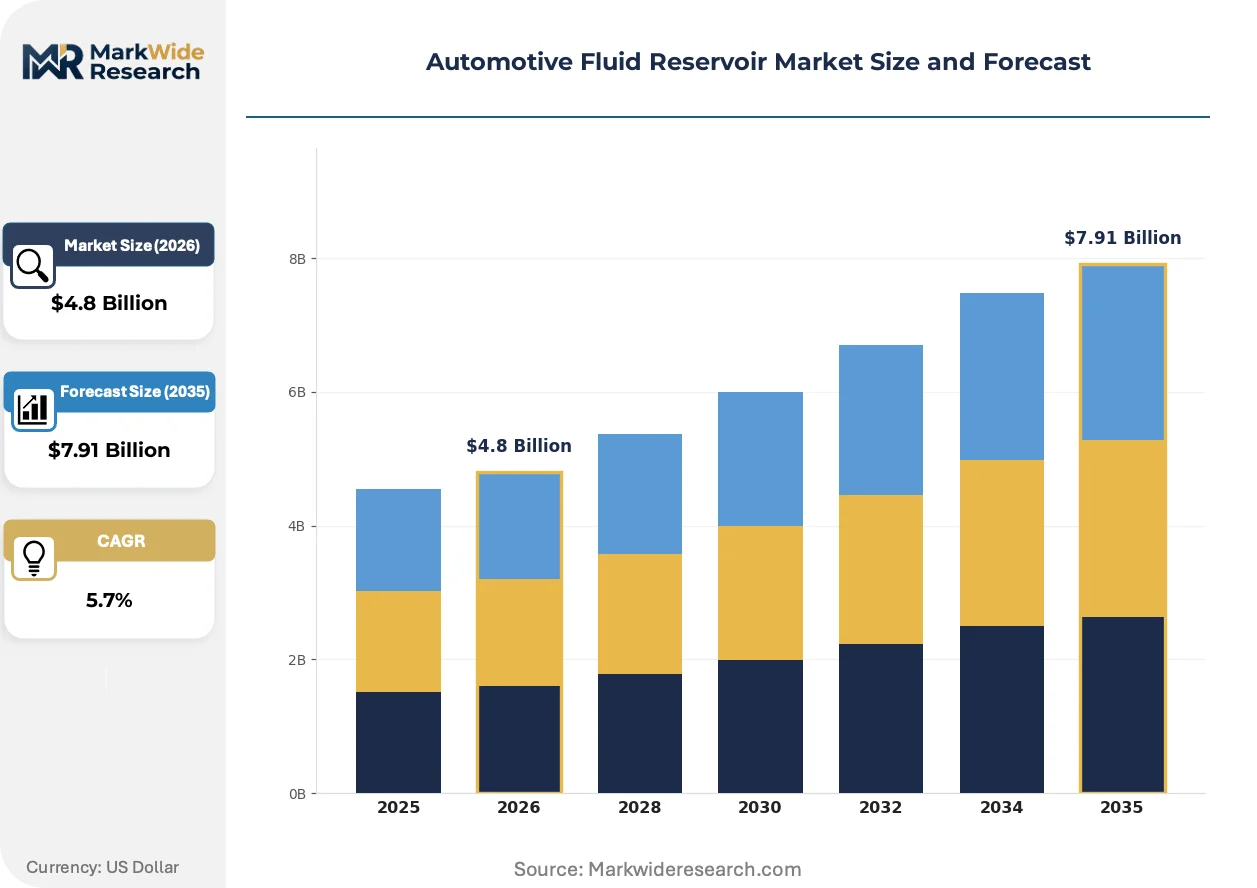
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Gasoline, Hybrid, Electric Material: Plastic, Metal, Rubber, Composite End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | TI Fluid Systems, Magna International, Continental AG, Calsonic Kansei, HELLA KGaA Hueck, MANN+HUMMEL, Gemini Group, Kyoraku, Cooper Standard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fluid Reservoir Market Evolving Landscape
Blow-molding automation and material science advances are compressing cycle times while expanding design freedom for complex internal geometries. Reservoir architectures are evolving from passive containment vessels toward active thermal management nodes.
Glass-reinforced polypropylene compounds are expanding into high-temperature coolant reservoirs for electric vehicle battery packs. Tier 1 suppliers in Germany and China are qualifying these materials for continuous-use temperatures above 120°C. The technology is expanding into applications previously reserved for metal or engineering thermoplastics, reducing unit cost by 15-25% while maintaining pressure-cycle durability.
EU F-Gas Regulation is mandating reduced permeation rates for refrigerant-bearing components in automotive heat pump systems. Reservoir manufacturers must validate barrier-layer coextrusion designs against stringent leakage thresholds. European OEMs are responding by specifying five-layer blow-molded constructions with ethylene vinyl alcohol cores, shifting material specifications across their supplier bases.
Fleet operators are unbundling reservoir replacement from scheduled maintenance contracts, creating direct procurement relationships with aftermarket specialists. Independent service networks in the United States are capturing volume previously routed through franchised dealerships. This pattern is most visible in commercial vehicle segments where uptime economics favor predictive reservoir replacement based on telematics data rather than calendar intervals.
Automotive Fluid Reservoir Market Segmentation
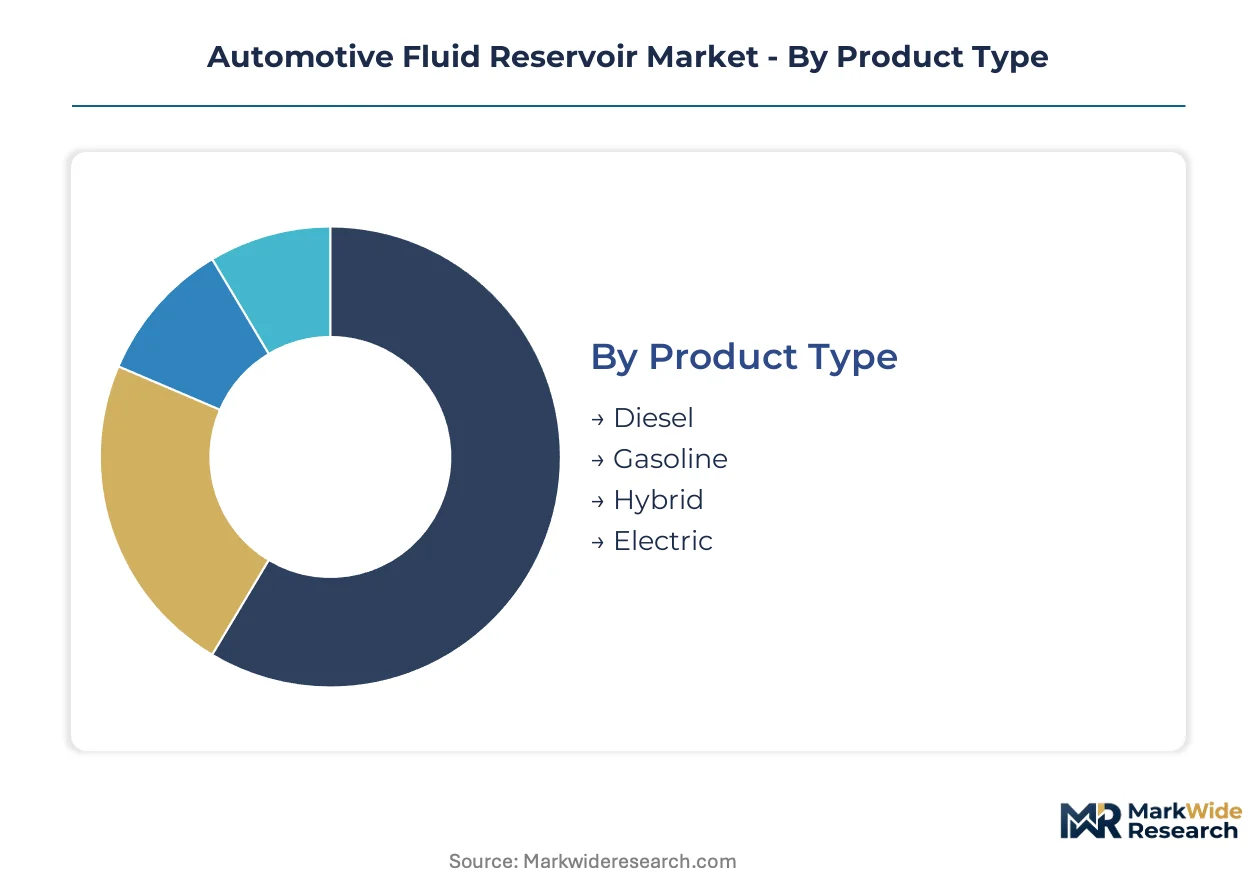
Reservoir specifications diverge sharply across powertrain architectures and thermal management requirements. Material selection and capacity sizing carry distinct certification burdens that reshape supplier qualification timelines and procurement patterns.
Product Type:
Certification requirements vary by powertrain: EPA Tier 3 and Euro 6 standards govern gasoline and diesel reservoirs, while ISO 26262 ASIL ratings apply to coolant level sensing in battery electric platforms.
- Electric:Dielectric fluid compatibility and aggressive thermal cycling specifications dominate engineering priorities. Volkswagen Group and BMW are consolidating multi-chamber centralized reservoir modules in Baden-Württemberg and Bavaria supplier clusters, driving demand for high-capacity designs with integrated sensor mounting points.
- Hybrid:Dual thermal circuits require reservoirs engineered for both conventional coolant and battery-specific dielectric fluids. Procurement teams at Toyota and Hyundai are specifying modular architectures that accommodate both fluid chemistries within single housing units.
- Gasoline:Blow-molded polypropylene variants displace stamped steel for corrosion resistance and complex geometry enablement.
- Diesel:Urea solution (DEF) containment demands specialized barrier-layer constructions against crystallization and permeation.
Leading the category by volume: Gasoline. Growing fastest: Electric.
Material:
Cost tiers stratify sharply: commodity thermoplastics anchor high-volume programs while fiber-reinforced compounds capture electrification premiums.
- Plastic:Polypropylene blow-molding dominates unit economics through corrosion resistance and design flexibility. TI Fluid Systems leverages captive blow-molding capacity to anchor European supply chains for thermal management reservoirs serving Volkswagen and Stellantis programs.
- Composite:Glass-reinforced polypropylene compounds expand into high-temperature coolant reservoirs for electric vehicle battery packs, qualifying for continuous-use temperatures above 120°C and reducing unit cost by 15-25% versus engineering thermoplastics.
- Metal:Aluminum and stamped steel retain share in heavy-duty commercial vehicles for extreme-duty thermal cycling applications.
- Rubber:Gasket and seal integration within reservoir assemblies addresses permeation and vibration damping requirements.
Plastic commands the volume base. Composites are climbing the fastest on electrification thermal demands.
End User:
Customer type determines channel economics: direct OEM supply carries longest qualification cycles but highest contract values.
- OEMs:Direct procurement relationships with Volkswagen Group, BMW, and Stellantis concentrate demand for integrated sensor-embedded reservoir designs. Continental AG sustains R&D intensity in these architectures, extending development cycles by 8-14 months for ISO 26262 ASIL-rated validation.
- Aftermarket Providers:Fleet operators are unbundling reservoir replacement from scheduled maintenance contracts, creating direct procurement relationships with independent service networks in the United States that capture volume previously routed through franchised dealerships.
- Tier-1 Suppliers:MANN+HUMMEL dominates filtration-coupled reservoir systems for commercial vehicle platforms.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging market localization programs.
OEMs dominate contract value. Aftermarket providers are expanding fastest on predictive maintenance economics.
Capacity:
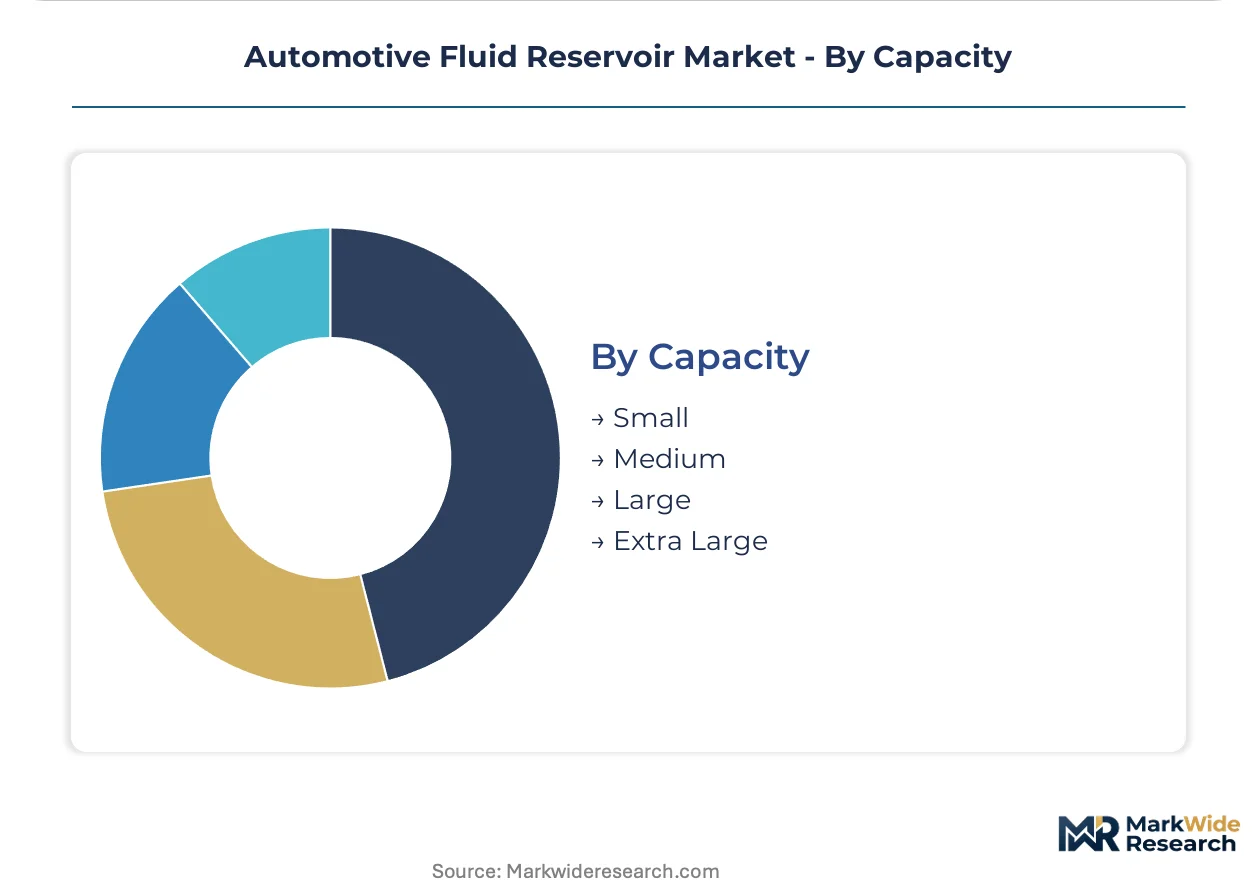
Application scale drives sizing: passenger vehicles cluster in small-to-medium ranges while commercial and electric platforms pull toward larger configurations.
- Large:Battery electric thermal management architectures demand expanded coolant volumes for heat pump systems and battery pack conditioning. EU F-Gas Regulation mandates secondary reservoir barriers for refrigerant containment, expanding addressable content per vehicle.
- Medium:Conventional internal combustion passenger vehicles standardize around optimized volume-to-weight ratios for engine cooling circuits.
- Small:Auxiliary fluid containment for brake systems and washer applications in compact vehicle segments.
- Extra Large:Heavy-duty commercial vehicle and off-highway equipment specifications for extended operating intervals.
Medium capacity leads by unit volume. Large capacity sees steepest expansion trajectory on battery electric thermal complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive fluid reservoirs concentrates in Germany where Volkswagen Group and BMW are redesigning thermal management architectures, while regulatory pressure from the EPA and EU F-Gas Regulation is reshaping material specifications across multiple jurisdictions.
United States
EPA Corporate Average Fuel Economy standards are compelling automakers toward lightweight blow-molded reservoirs that reduce vehicle mass. NHTSA brake-fluid specifications dictate crashworthiness testing protocols for tank mounting and rupture resistance. Detroit-area supplier clusters are retooling for electrified powertrain thermal management requirements.
Germany
Volkswagen Group and BMW are consolidating coolant circuit architectures around centralized reservoir modules in Baden-Württemberg and Bavaria. EU F-Gas Regulation mandates reduced permeation rates for refrigerant-bearing components in automotive heat pump systems. Stuttgart and Munich supplier corridors are scaling multi-chamber high-capacity designs with integrated sensor mounting points.
China
Domestic electric vehicle programs from BYD and NIO are driving demand for dielectric fluid-compatible reservoirs with aggressive thermal cycling specifications. MIIT dual carbon goals are pressuring manufacturers toward lower-emission material selections. Yangtze River Delta manufacturing hubs are qualifying glass-reinforced polypropylene compounds for continuous-use temperatures above 120°C.
India
Tata Motors and Mahindra electric vehicle programs are creating procurement opportunities for localized blow-molding capacity. The PLI scheme for auto components offers production-linked incentives for establishing domestic manufacturing. Tamil Nadu and Gujarat supplier zones are attracting Tier 1 reservoir specialists seeking cost-competitive export platforms.
Japan
Toyota and Hyundai procurement teams are specifying modular reservoir architectures that accommodate both conventional coolant and battery-specific dielectric fluids. METI industrial policy supports thermal management component innovation for hybrid platforms. Nagoya-area manufacturing clusters are advancing integrated sensor-embedded reservoir designs for ASIL-rated validation.
Automotive Fluid Reservoir Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM direct supply channels capturing dominant contract values while aftermarket providers compete on replacement-cycle predictability. The vendor base organizes around three strategic archetypes: integrated Tier 1 systems suppliers with captive blow-molding capacity, specialized reservoir fabricators focused on thermal management innovation, and diversified automotive component conglomerates leveraging cross-product economies. Competitive dynamics center on M&A activity targeting sensor-integration capabilities and geographic expansion into emerging EV manufacturing corridors.
Among European-based integrated suppliers, Continental AG and MANN+HUMMEL occupy positions exemplifying the systems-integration archetype, while TI Fluid Systems represents the specialized fabricator model with dedicated thermal management focus. These three entities anchor the competitive structure across OEM direct supply channels, each sitting within distinct strategic postures regarding R&D intensity and geographic footprint.
| Leading Market Players |
|---|
| TI Fluid Systems |
| Magna International |
| Continental AG |
| Calsonic Kansei |
| HELLA KGaA Hueck |
| MANN+HUMMEL |
| Gemini Group |
| Kyoraku |
| Cooper Standard |
| Others |
Value Network & Pricing Analysis
Polypropylene resin feedstock costs cascade through three distinct pricing tiers as Gulf Coast petrochemical output flows through blow-molding specialists to OEM procurement desks. Material volatility compresses margins for Tier 2 fabricators lacking long-term supply agreements while integrated Tier 1 suppliers capture pricing power through captive resin hedging.
Pricing Analysis
Volume-based contract manufacturing anchors the economy tier while sensor-embedded multi-chamber designs command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified integrated modules from commodity blow-molded tanks. Cost compression in standard-grade polypropylene reservoirs is intensifying because propylene monomer supply disruptions from Gulf Coast complexes are squeezing blow-molding specialists. Fleet operators and independent aftermarket distributors exhibit highest price sensitivity, whereas OEM direct procurement teams prioritize thermal cycling performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for remanufactured reservoir cores are emerging as Germany, China, and the United States build closed-loop polymer recovery networks. Raw material dependencies center on propylene monomer from Gulf Coast crackers, glass fiber reinforcement from Chinese suppliers, and ethylene vinyl alcohol barrier resins from Japanese petrochemical producers. Single-source vulnerability concentrates in specialized multi-cavity mold fabrication where German and Japanese toolmakers dominate lead times. Distribution runs through OEM direct supply channels for new vehicle programs while aftermarket providers bypass franchised dealerships through independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as players pursue captive blow-molding capacity to secure resin cost control and compress qualification timelines.
For Market Incumbents: Deploy sensor-integration R&D to defend against emerging electronics specialists encroaching on thermal management architectures. Consolidate Baden-Württemberg and Bavaria supplier cluster positions through capacity expansion for multi-chamber centralized reservoir modules. ISO 26262 ASIL certification investment creates switching costs that lock out unqualified competitors. For New Entrants and Emerging Players: Capture aftermarket predictive maintenance data services where fleet operators are unbundling reservoir replacement from scheduled maintenance contracts. India's PLI scheme for auto components offers the most penetrable geography for establishing cost-competitive export platforms serving Tata Motors and Mahindra programs. Partner with telematics providers to embed IoT-enabled level sensing as a differentiated entry vector. For Investors and Strategic Acquirers: Volkswagen Group and BMW thermal management redesign announcements are the leading indicator that multi-chamber centralized reservoir architectures will consolidate supplier positions. Long-term viability hinges on exposure to battery electric thermal complexity rather than legacy internal-combustion replacement cycles. Monitor EU F-Gas Regulation phase-down implementation timelines as the inflection signal for barrier-layer coextrusion capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene formulation control insulates margins from Gulf Coast feedstock volatility. |
| Sensor-Reservoir Module Certification | ASIL-rated validation timelines create 8-14 month barriers against unqualified competitors. |
| India Manufacturing Localization | PLI scheme access positions suppliers for Tata Motors and Mahindra electric vehicle procurement. |
| Five-Layer Barrier Coextrusion Scale-Up | EU F-Gas Regulation compliance mandates ethylene vinyl alcohol core constructions for heat pump systems. |
| Aftermarket Telematics Partnership | Predictive maintenance data services unlock recurring revenue from fleet operator direct relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and blow-molding operations managers provided demand-side validation. EPA Corporate Average Fuel Economy documentation, EU F-Gas Regulation implementation guidance, NHTSA brake-fluid specifications, and vehicle production databases from IHS Markit supplied regulatory and volume benchmarks. Bottom-up unit economics modeling triangulated against top-down OEM thermal management architecture forecasts.
Granularity-level modeling tracked reservoir specifications across propulsion architecture, material grade tier, capacity sizing, and regional production cluster dimensions. CAGRs were derived from segment-level volume trajectories weighted by content-per-vehicle assumptions for battery electric thermal management complexity. Propulsion mix scenarios incorporated MIIT dual carbon goals, EPA fleet efficiency penalties, and German automaker platform consolidation announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric adoption curves and polypropylene resin price volatility. Forecasts reflect documented assumptions regarding thermal management architecture consolidation and regulatory phase-down timelines. Practitioners should monitor EU F-Gas Regulation barrier-layer compliance deadlines and German OEM multi-chamber module qualification announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Car Oil Filter Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Steering Damper Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Engine Flush Market
Powertrain
Europe Turbocharger Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Engines Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Tachometer Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
United States Electro Hydraulic Power Steering Market