
 Exhaust Flexible Couplings Market | 2026-2036
Exhaust Flexible Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust Flexible Couplings Market Insights
The capital-intensity divergence between Tier-1 suppliers and mid-tier fabricators is unwinding as emission-control mandates force consolidation around certified manufacturing. BOSAL leverages its European foundry network to sustain cost advantages in stainless steel bellows production. Tenneco anchors North American aftermarket distribution through direct channel control with major fleet operators. FORVIA competes by extending its integrated exhaust-system portfolio into hybrid-vehicle thermal management applications.
Exhaust flexible couplings are corrugated metal bellows or multi-ply expansion joints engineered to absorb thermal expansion, vibration isolation, and angular misalignment in engine exhaust streams, typically fabricated from austenitic stainless steel grades 321 or 309 with wall thicknesses between 0.3 mm and 0.5 mm. Their primary purpose is to protect downstream catalytic converters, diesel particulate filters, and turbocharger housings from mechanical stress failure during thermal cycling. Bellows assemblies occupy the largest value share due to their ubiquity across passenger vehicle platforms and established OEM qualification protocols. Nickel alloy segments command premium positioning for marine vessel and high-performance applications where salt corrosion resistance justifies material cost escalation. Carbon steel variants face margin compression as regulatory thresholds for exhaust system durability rise in major automotive markets.
EPA emission standards for heavy-duty engines and the EU Green Deal's phased CO2 reduction targets for commercial vehicles are tightening product validation requirements, forcing suppliers to maintain dual certification across Atlantic regulatory regimes. China's MIIT implements GB standards for exhaust system component life testing that restrict market access for uncertified imports. Stakeholders must monitor divergence between US and European durability test protocols, as misaligned certification timelines threaten to fragment supply chain planning for platform-global exhaust architectures.
Market Dynamics
Stainless steel bellows fabrication is consolidating around certified European foundries as dual Atlantic emission mandates force Tier-1 suppliers to absorb mid-tier fabricators lacking EPA and EU Green Deal validation protocols simultaneously.
Growth Catalysts
- EPA Heavy-Duty Engine Standards:Fleet operators in the United States face mandatory exhaust system durability upgrades, pulling demand for thermal-fatigue-resistant coupling architectures.
- Marine Vessel Nickel Alloy Adoption:Salt corrosion resistance requirements in offshore propulsion systems justify material cost escalation for austenitic grades 309 and 321 bellows.
- Germany Production Cluster Density:Eberspächer and BOSAL anchor concentrated OEM supply chain proximity, reducing logistics friction for just-in-time exhaust module delivery.
Market Restraints
- Raw Material Volatility:Nickel and chromium price swings compress margin stability for stainless steel bellows fabricators without long-term ore contracts.
- Certification Timeline Misalignment:Divergent EPA and EU Green Deal durability test protocols fragment supply chain planning for platform-global exhaust architectures.
- Carbon Steel Substitution Collapse:Regulatory durability thresholds in major automotive markets eliminate low-cost carbon steel variant viability.
Strategic Opportunities
- Hybrid Vehicle Thermal Management:Integrated exhaust-system portfolios extend into battery-electric range-extender applications, opening new OEM qualification pathways.
- China GB Standards Market Access:MIIT component life testing mandates create certified-supplier scarcity that Western foundries can exploit through joint venture structures.
- Direct Fleet Distribution Channels:North American aftermarket bypasses traditional jobber networks through direct contractual relationships with heavy-duty truck operators.
Industry Challenges
- Welding Automation Skill Scarcity:Multi-ply bellows seam welding requires precision orbital TIG expertise that vocational pipelines fail to replenish at replacement rates.
- Dual Certification Capex Burden:Simultaneous EPA and EU test facility investment strains mid-tier fabricator balance sheets before revenue recognition.
- Legacy Platform Integration Friction:Retrofit coupling designs must accommodate obsolete exhaust manifold geometries without triggering warranty void clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust Flexible Couplings Market |
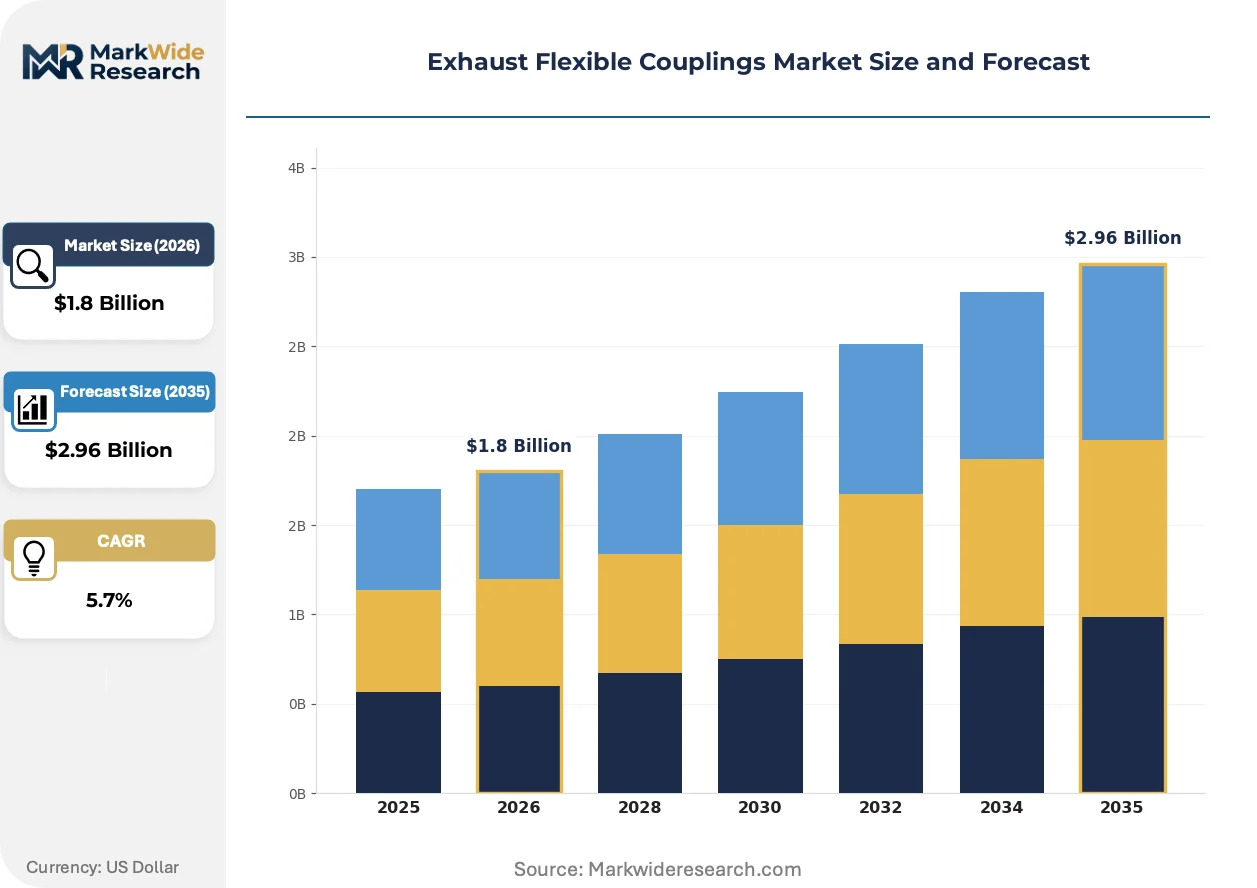
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bellows, Expansion Joints, Universal Joints, Slip Joints, Bellow Assemblies Material: Stainless Steel, Aluminum Alloy, Carbon Steel, Nickel Alloy, Titanium Application: Passenger Vehicles, Heavy Duty Trucks, Agricultural Machinery, Construction Equipment, Marine Vessels End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers, Workshop Service Providers |
| Companies Covered | BOSAL, Tenneco, FORVIA, Eberspächer, Benteler, Sango, Sejong Industrial, Dinex, Katcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust Flexible Couplings Market Trends and Innovations
Corrugated metal bellows engineering is pivoting toward thermal management integration as powertrain electrification fragments traditional exhaust system architectures and demands multi-functional component designs.
Multi-ply hydroformed bellows is miniaturizing wall thickness profiles below 0.3 mm while maintaining pressure containment for turbocharged gasoline direct injection engines. Passenger vehicle OEMs in Germany and Japan adopt these architectures for underfloor packaging density. The technology is miniaturizing physical envelope requirements without sacrificing fatigue cycle performance, compressing legacy single-ply designs out of compact vehicle segments.
EU Green Deal phased CO2 reduction targets for commercial vehicles mandate 15-year exhaust component durability certification that exceeds prior 10-year baselines. Suppliers must retest existing stainless steel bellows portfolios against accelerated thermal cycling protocols. Heavy-duty truck platforms serving German and French fleets face the steepest compliance cost escalation.
Fleet procurement departments now specify outcome-based total cost of ownership metrics rather than unit price for coupling replacement cycles. Direct channel contracts with major North American operators displace traditional aftermarket distributors. This behavioral shift concentrates buying power among operators with telematics-enabled predictive maintenance systems.
Exhaust Flexible Couplings Market Segmentation
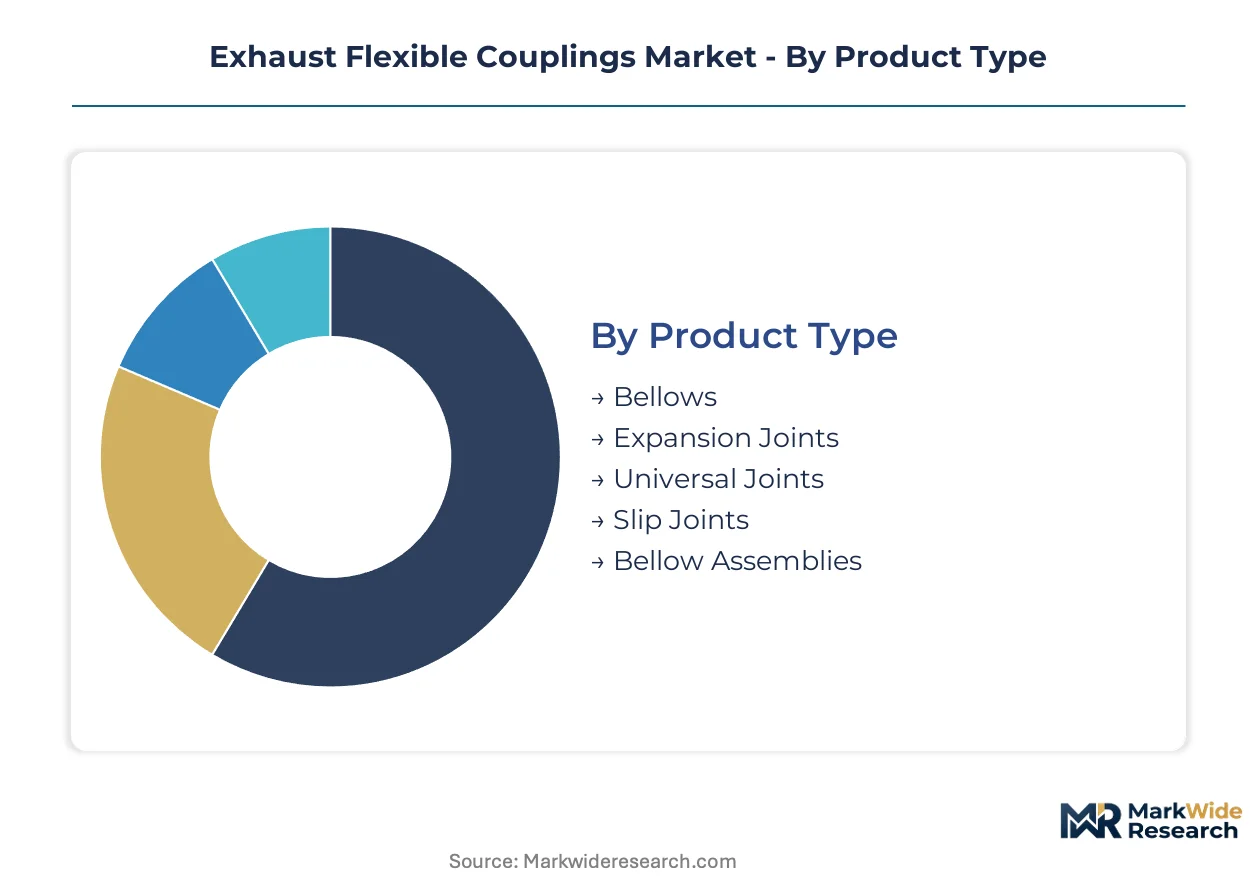
Exhaust flexible coupling architectures fragment across four distinct taxonomies that reshape procurement economics and supplier qualification pathways. Product type and material composition determine thermal fatigue certification requirements, while application and end-user channels govern pricing power and inventory velocity.
Product Type:
Margin pools concentrate in bellows derivatives where multi-ply hydroforming commands OEM qualification premiums.
- Bellows:Corrugated austenitic stainless steel tubes with wall thickness between 0.3 mm and 0.5 mm absorb axial and angular displacement in passenger vehicle underfloor packaging. German and Japanese OEMs specify these for turbocharged gasoline direct injection thermal cycling durability.
- Bellow Assemblies:Pre-fabricated subsystems integrating end fittings, interlock liners, and protective braid capture value through reduced assembly labor at vehicle plants. Heavy-duty truck manufacturers in the United States specify these for EPA-mandated exhaust system durability upgrades.
- Expansion Joints:Multi-convolution designs for marine and stationary engine applications where pressure containment exceeds 3 bar.
- Universal Joints:Cardan-style couplings accommodating angular misalignment up to 15 degrees in agricultural driveline connections.
- Slip Joints:Telescopic sleeve designs for axial thermal expansion compensation in long exhaust runs on construction equipment.
Bellows holds installed capacity. Bellow assemblies is rotating up the share rankings.
Material:
Cost tier stratification separates certified stainless foundries from commodity metal suppliers facing margin compression.
- Stainless Steel:Grades 321 and 309 dominate passenger vehicle and heavy-duty truck platforms, with chromium-nickel content optimized for oxidation resistance above 800°C. Eberspächer and BOSAL sustain European production advantages through captive foundry integration.
- Nickel Alloy:Inconel and Hastelloy variants command 4-6x material cost multiples for marine propulsion salt corrosion resistance. Offshore vessel operators in Norway and Singapore specify these for 15-year service life guarantees.
- Aluminum Alloy:Weight-driven adoption in hybrid vehicle range-extender applications where thermal loads permit lower temperature ratings.
- Carbon Steel:Regulatory durability thresholds in EPA and EU Green Deal jurisdictions have eliminated viability for new platform qualification.
- Titanium:Motorsport and aerospace derivative applications where specific strength justifies procurement complexity.
Stainless steel holds installed capacity. Nickel alloy is climbing the fastest toward share expansion.
Application:
Volume concentration tracks emissions regulation intensity across commercial vehicle fleets.
- Heavy Duty Trucks:EPA heavy-duty engine standards and EU Green Deal CO2 reduction mandates force thermal fatigue-resistant coupling architectures. Fleet operators specify 15-year durability certification for underfloor and vertical exhaust configurations.
- Passenger Vehicles:Downsized turbocharged engines with gasoline direct injection generate steeper thermal cycling profiles. German and Japanese OEMs miniaturize packaging envelopes below 0.3 mm wall thickness through hydroformed multi-ply designs.
- Marine Vessels:Salt corrosion resistance requirements justify nickel alloy cost escalation in offshore propulsion systems.
- Construction Equipment:Vibration isolation priorities in non-road mobile machinery drive slip joint specification for axial expansion accommodation.
- Agricultural Machinery:Cost-sensitive universal joint adoption in driveline connections with moderate thermal loads.
Heavy duty trucks holds installed capacity. Passenger vehicles is gaining share fastest.
End User:
Customer type determines channel control and pricing power concentration.
- OEM Manufacturers:Direct platform engineering relationships with Eberspächer, BOSAL, and Tenneco sustain multi-year supply agreements with volume commitments and joint thermal testing protocols.
- Tier-1 Suppliers:Exhaust system integrators qualifying coupling subsystems within complete aftertreatment module assemblies for just-in-time delivery to vehicle assembly plants.
- Aftermarket Suppliers:Tenneco anchors North American distribution through direct contractual relationships with telematics-enabled fleet operators, displacing traditional jobber networks.
- Vehicle Assemblers:Captive procurement of standardized coupling architectures for platform-global exhaust systems.
- Workshop Service Providers:Fragmented demand for replacement cycles with limited specification influence.
OEM manufacturers holds installed capacity. Tier-1 suppliers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for exhaust flexible couplings favor European fabricators with captive stainless steel foundry capacity, while North American and Asian markets absorb premium-tier assemblies through direct OEM supply contracts rather than spot procurement channels.
United States
Heavy-duty truck fleet operators drive thermal fatigue-resistant coupling demand under EPA heavy-duty engine standards mandating 15-year exhaust system durability. The agency's phased emission reduction timelines force platform-wide component upgrades. Tenneco anchors aftermarket distribution through direct contractual relationships with telematics-enabled fleet operators concentrated in the Midwest manufacturing corridor and Texas energy transport hubs.
Germany
Passenger vehicle OEMs specify hydroformed multi-ply bellows below 0.3 mm wall thickness for downsized turbocharged gasoline direct injection engines. EU Green Deal CO2 reduction targets for commercial vehicles extend certification baselines from 10 to 15 years. Eberspächer and BOSAL sustain production cluster density in the Baden-Württemberg and North Rhine-Westphalia industrial belts, reducing logistics friction for just-in-time exhaust module delivery to Stuttgart and Munich assembly plants.
China
Domestic heavy-duty truck manufacturers expand adoption of advanced exhaust systems as MIIT implements GB standards for component life testing that restrict market access for uncertified imports. The regulator's durability protocols create certified-supplier scarcity. Production gravity concentrates in the Yangtze River Delta and Pearl River Delta manufacturing zones, where joint venture structures between Western foundries and local fabricators exploit qualification barriers.
Japan
Automotive OEMs miniaturize packaging envelopes for hybrid vehicle range-extender thermal management applications, opening new qualification pathways for integrated exhaust-system portfolios. METI's industrial standards for automotive component durability align with EU test protocols, simplifying dual certification. Manufacturing clusters in the Aichi Prefecture around Nagoya and Kanto region near Tokyo supply precision-formed bellows to domestic and export platforms.
South Korea
Marine vessel operators in Busan-Ulsan shipbuilding hubs specify nickel alloy bellows for salt corrosion resistance in offshore propulsion systems, justifying 4-6x material cost multiples. The country's export-oriented shipyard sector drives premium-tier demand. Sejong Industrial and domestic fabricators serve Hyundai Heavy Industries and Daewoo Shipbuilding contracts from production facilities concentrated in the southeastern Gyeongsang region.
Exhaust Flexible Couplings Market Competitive Landscape
Concentration sits with integrated exhaust-system specialists possessing captive stainless steel foundry capacity and dual EPA-EU certification protocols. Mid-tier fabricators lacking simultaneous Atlantic validation face absorption or margin compression as emission mandates consolidate procurement around qualified suppliers. Two strategic archetypes dominate: European foundry-integrated OEM suppliers and North American aftermarket channel controllers. Competitive moves center on backward integration into raw material supply and direct fleet distribution partnerships that displace traditional jobber networks.
Among European foundry-integrated suppliers, BOSAL and Eberspächer exemplify the OEM-direct archetype through proximity to German vehicle assembly plants. Tenneco occupies a position within the North American aftermarket channel control segment. These three entities represent distinct competitive positioning vectors—European production cluster density versus North American distribution capture—without overlapping strategic territory.
| Leading Market Players |
|---|
| BOSAL |
| Tenneco |
| FORVIA |
| Eberspächer |
| Benteler |
| Sango |
| Sejong Industrial |
| Dinex |
| Katcon |
| Others |
Pricing and Supply Chain Analysis
EPA and EU Green Deal dual certification protocols gate both supplier qualification and price differentiation simultaneously, compressing uncertified fabricators into commodity tiers while validated foundries capture OEM premiums. Nickel-chromium alloy cost volatility transmits directly into configured-to-order pricing spreads, with fleet procurement departments now weighting total cost of ownership over unit price.
Pricing Analysis
Configured-to-order bellows assemblies command 40-60% premiums over standard catalog items due to end-fitting customization and interlock liner specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal cycle performance rating, with EPA-validated heavy-duty truck applications at the top tier. Price differentiation stems from dual Atlantic certification overhead and captive foundry integration. Cost compression in carbon steel variants is intensifying because regulatory durability thresholds have eliminated new platform viability. Aftermarket workshop service providers exhibit highest price sensitivity, while telematics-enabled fleet operators prioritize predictive maintenance value over procurement unit cost.
Supply Chain Analysis
Just-in-time delivery preferences dominate German OEM relationships, whereas North American aftermarket channels maintain strategic safety stock for fleet maintenance windows. Supply concentrates in Germany, China, and South Korea, with Baden-Württemberg foundry clusters feeding Stuttgart assembly plants and Yangtze River Delta joint ventures serving domestic heavy-duty manufacturers. Raw material sourcing draws from Indonesian nickel ore, South African chromium, and Ukrainian titanium feedstocks. Single-source vulnerability concentrates in precision orbital TIG welding equipment constrained by vocational skill scarcity. Distribution runs through direct contractual relationships with telematics-enabled fleet operators displacing traditional jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision orbital TIG welding expertise has become the binding constraint on multi-ply bellows production expansion, with vocational pipelines failing to replenish technical talent at replacement rates. Suppliers possessing this scarce capability command disproportionate OEM qualification access.
For Market Incumbents: Secure captive foundry integration in stainless steel grades 321 and 309 to insulate margin stability from nickel-chromium price volatility. Defend market position by accelerating dual EPA-EU certification absorption of mid-tier fabricators lacking simultaneous Atlantic validation, converting competitive threat into capacity expansion. For New Entrants and Emerging Players: Anchor in China GB standards certification partnerships with Western foundry joint ventures, exploiting MIIT component life testing mandates that restrict uncertified import access. Target aluminum alloy hybrid vehicle thermal management applications as the most penetrable white space, leveraging lower temperature rating requirements to bypass nickel alloy cost barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across marine vessel nickel alloy segments due to 15-year salt corrosion resistance guarantees justifying 4-6x material cost multiples. Long-term viability favors acquisition targets with captive welding automation and existing dual Atlantic certification infrastructure. Watch nickel LME futures volatility as the signal to watch; sustained price elevation above historical bands would compress stainless steel bellows margins and trigger consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Atlantic Certification Investment | EPA and EU Green Deal simultaneous validation unlocks platform-global exhaust architecture supply contracts. |
| Captive Stainless Steel Foundry Integration | Backward integration into grades 321 and 309 production insulates margin stability from nickel-chromium volatility. |
| Direct Fleet Distribution Channel Development | Bypassing traditional jobber networks captures telematics-enabled predictive maintenance procurement workflows. |
| Hybrid Vehicle Thermal Management Extension | Integrated exhaust-system portfolios penetrate battery-electric range-extender OEM qualification pathways. |
| China Joint Venture Structure Formation | MIIT GB standards compliance creates certified-supplier scarcity exploitable through Western-local fabrication partnerships. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with exhaust system procurement directors, Tier-1 supplier platform engineers, aftermarket fleet operations managers, and precision welding automation specialists; and secondary validation through EPA emission standard filings, EU Green Deal regulatory texts, MIIT GB standard documentation, and customs trade flow records. Bottom-up unit economics triangulated against top-down OEM production volume estimates established market sizing boundaries.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type architecture, material grade certification tier, vehicle application thermal load profile, and end-user channel control structure. CAGRs derived from OEM platform lifecycle commitments and fleet replacement cycle telemetry. Forecast inputs incorporated nickel LME price trajectory assumptions and welding automation equipment installation rates.
Decision-makers should treat outputs as directional under sustained EPA-EU regulatory convergence and nickel supply chain stability assumptions; material deviation would warrant model refresh. Revision becomes warranted when nickel price volatility crosses thresholds that trigger stainless steel bellows margin compression or when welding automation skill scarcity accelerates beyond vocational pipeline replacement capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Carburetor Market
Powertrain
Car Drive System Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
North America Torque Vectoring Market
Powertrain
Racing Clutches Market
Powertrain
Crate Engines Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Fuel Injection Systems Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Turbocharger Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Canada Automotive Engine Oils Market