
 Automotive Clutch Slave Cylinder Market | 2026-2036
Automotive Clutch Slave Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Clutch Slave Cylinder Market Outlook
Skilled hydraulic systems technicians is reorganizing supplier capacity across the Automotive Clutch Slave Cylinder Market, particularly in regions where manual transmission expertise has atrophied. Schaeffler Group leverages its integrated bearing and clutch module operations to control captive supply of precision-machined slave cylinder housings. Valeo competes through aftermarket channel density in European repair networks. ZF Friedrichshafen anchors high-volume programs with commercial vehicle OEMs requiring extended-duty cycle validation.
An automotive clutch slave cylinder is a hydraulically actuated piston device, typically cast from aluminum alloy with a bore diameter of 19–25 mm, that translates master cylinder pressure into mechanical release bearing displacement to disengage the clutch disc. Its primary purpose is to provide precise, low-effort clutch operation in manual and automated manual transmissions across passenger and commercial vehicles. Hydraulic product types dominate OEM fitment due to superior pedal feel modulation, while the aftermarket channel for independent retailers captures significant margin pools from aging light truck fleets. Passenger cars represent the mature volume base, though heavy trucks generate higher per-unit value through reinforced seal specifications and corrosion-resistant coatings.
FCC vehicle safety standards and EPA brake-fluid toxicity regulations shape material selection and testing protocols for slave cylinders sold in the United States, while REACH chemical restrictions in Europe limit certain elastomer compounds used in piston seals. India's BIS automotive component standards and China's GB/T hydraulic system specifications create additional compliance layers for exporters targeting those assembly markets. Stakeholders must monitor divergence between regional fluid compatibility mandates and the accelerating shift toward electromechanical clutch actuation in electric vehicle platforms.
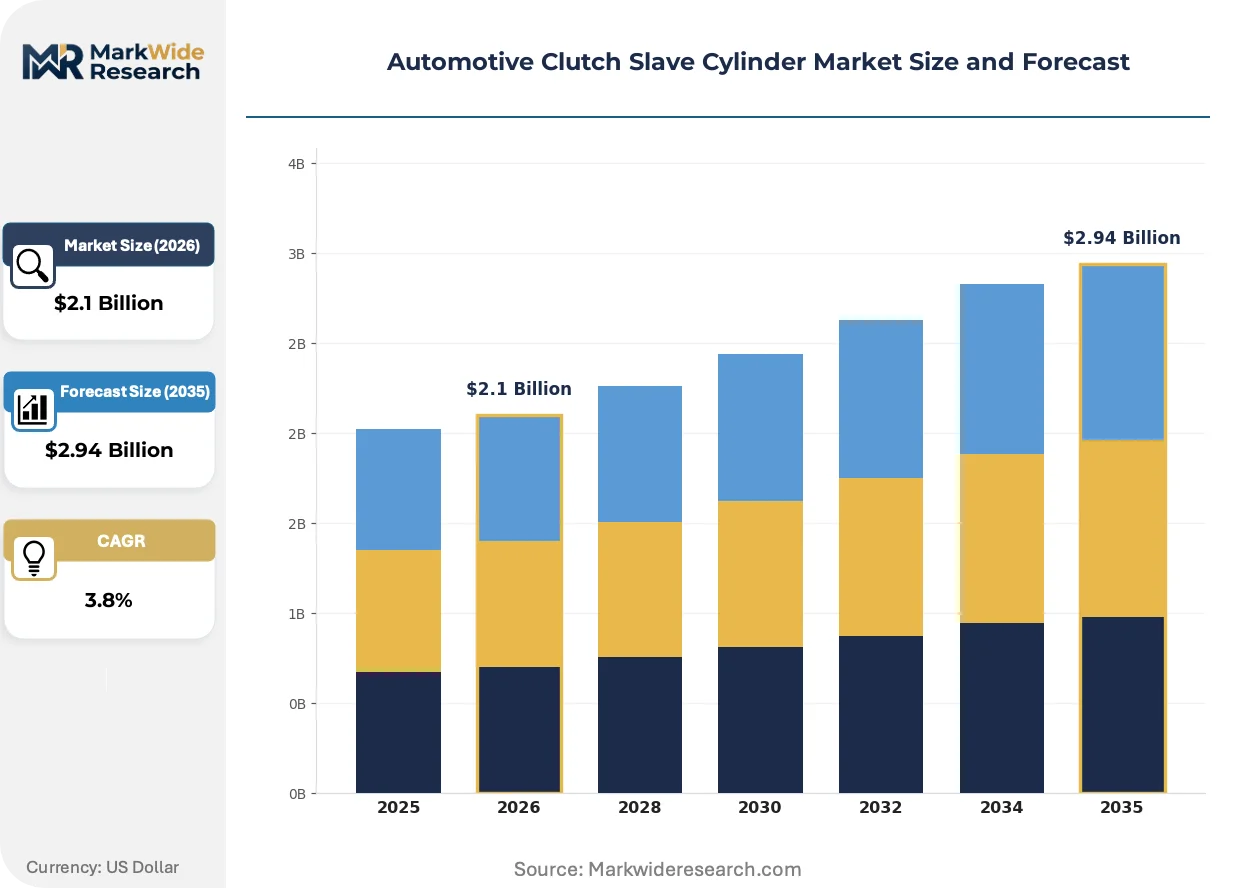
Market Dynamics
The automotive clutch slave cylinder market is being fundamentally restructured by the accelerating obsolescence of hydraulic actuation systems as electric vehicle architectures proliferate. This technology displacement is compressing replacement cycles in legacy manual transmission fleets while forcing incumbent suppliers to recalibrate their product portfolios toward electromechanical alternatives.
Growth Catalysts
- Commercial fleet replacement cycles:Latin American logistics operators are extending preventive maintenance schedules for hydraulic clutch systems in aging medium-duty trucks, generating sustained aftermarket pull.
- REACH chemical compliance:European ECHA restrictions on legacy elastomer compounds are compelling seal material upgrades that improve cylinder durability and reduce warranty claims.
- Aluminum alloy casting advances:Precision-machined bore surfaces with reduced friction coefficients are extending service intervals in heavy truck applications.
Market Restraints
- Input cost volatility:Aluminum alloy pricing fluctuations directly compress margin structures for casting-intensive slave cylinder housings.
- Supplier concentration risk:Precision bore machining capacity concentrates among tier-one automotive component suppliers in Germany and Japan.
- Electromechanical substitution:Clutch-by-wire systems in battery electric platforms eliminate hydraulic slave cylinders entirely from new vehicle architectures.
Strategic Opportunities
- Aftermarket channel digitization:Independent repair networks in Mexico's Querétaro manufacturing corridor are adopting e-procurement platforms for hydraulic component sourcing.
- Remanufacturing programs:EPA brake-fluid toxicity standards are creating regulatory space for certified remanufactured slave cylinders with reduced environmental liability.
- Cross-platform modularity:Converging automated manual transmission and dual-clutch architectures enable shared slave cylinder designs across OEM programs.
Industry Challenges
- Hydraulic systems technician scarcity:Manual transmission expertise has atrophied across North American and European service networks, complicating diagnostic and repair execution.
- Fluid compatibility certification timelines:Multi-regional brake-fluid standards under EPA, REACH, and China's GB/T specifications require parallel testing protocols that extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Clutch Slave Cylinder Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electric, Mechanical Vehicle Type: Passenger Cars, Light Trucks, Heavy Trucks, Motorcycles End User: OEMs, Aftermarket, Fleet Operators, Distributors Distribution Channel: Online Retail, Authorized Dealers, Independent Retailers, Wholesalers |
| Companies Covered | Schaeffler Group, Valeo, ZF Friedrichshafen, Exedy Corporation, Aisin Seiki, BorgWarner, FTE Automotive, Dorman Products, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Clutch Slave Cylinder Market Strategic Shifts
Hydraulic actuation technology is undergoing material and geometric refinement even as electromechanical alternatives capture new vehicle platforms. The tension between legacy system optimization and architectural replacement defines current supplier R&D allocation.
Concentric slave cylinders with integrated release bearings are miniaturizing bore diameters below 19 mm while maintaining force output through higher system pressure ratings. European passenger car OEMs are adopting these compact designs for transverse engine packaging constraints. This dimensional compression is enabling transmission tunnel space reallocation toward battery modules in hybrid architectures.
EPA brake-fluid toxicity regulations under the Toxic Substances Control Act are prohibiting specific glycol ether formulations used in legacy hydraulic fluids. Slave cylinder seal compounds must now validate compatibility with replacement fluid chemistries across extended temperature cycles. Heavy truck suppliers serving the US market are absorbing the highest compliance burden due to extended-duty thermal exposure requirements.
Fleet maintenance departments are consolidating supplier relationships around full-system hydraulic component providers rather than discrete part sourcing. Independent distributors serving Latin American commercial operators are losing share to direct OEM-affiliated channels with integrated technical support. This concentration is most pronounced in Brazil's São Paulo state logistics corridor where multinational fleet operators dominate vehicle procurement.
Automotive Clutch Slave Cylinder Market Segmentation
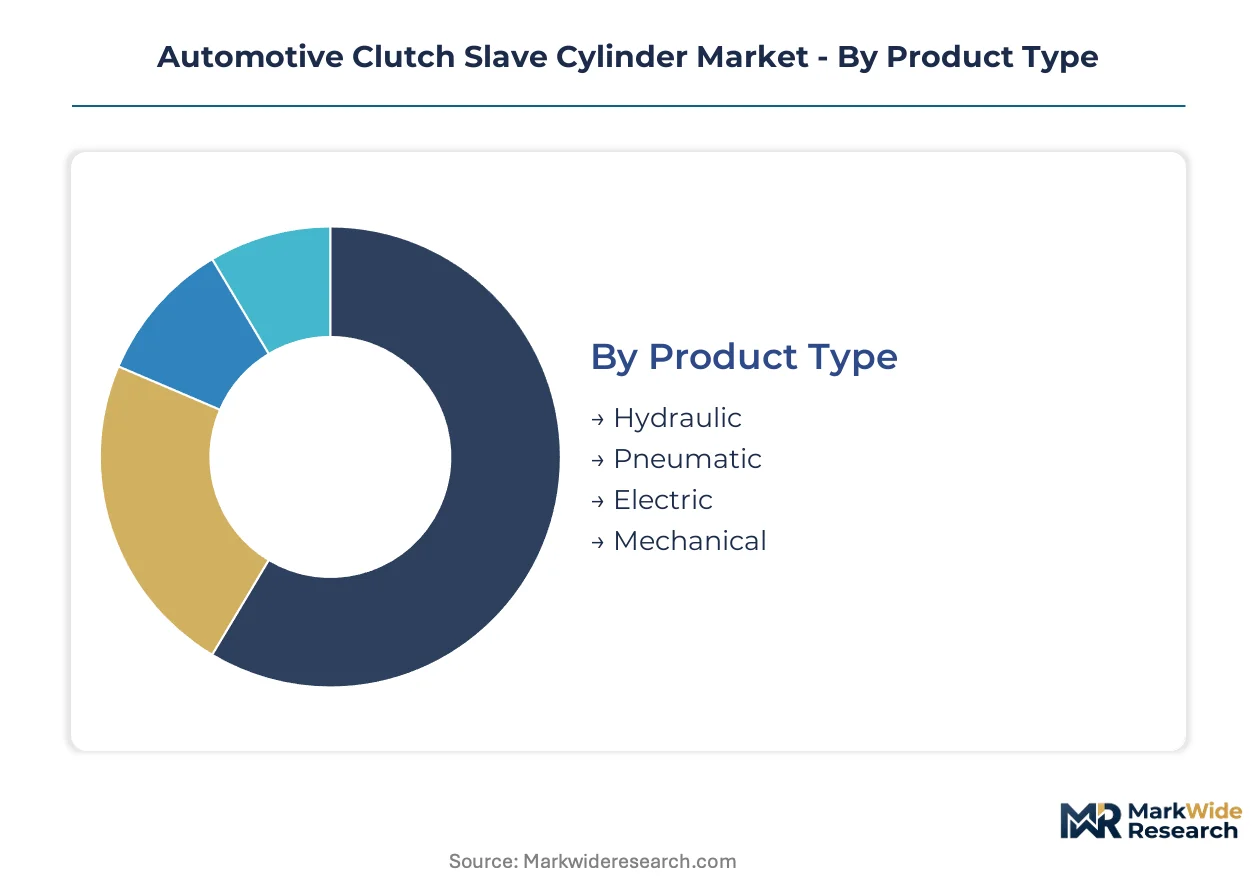
Segmentation in the Automotive Clutch Slave Cylinder Market reveals where electromechanical substitution pressure concentrates most intensely. Product type and vehicle category splits determine which suppliers can amortize hydraulic tooling investments against declining manual transmission volumes.
Product Type:
Electric slave cylinders face immediate displacement risk as clutch-by-wire architectures eliminate hydraulic actuation entirely from battery electric platforms.
- Hydraulic:Dominates current OEM fitment through superior pedal feel modulation and established service infrastructure. Demand concentrates in Mexico's Querétaro manufacturing corridor where manual transmission production continues for Latin American export markets facing slower electrification timelines.
- Electric:Electromechanical actuators replace hydraulic cylinders in new EV architectures, though aftermarket retrofit demand remains negligible. Early adoption clusters in European passenger car platforms where dual-clutch transmissions require precise electronic control.
- Pneumatic:Compressed air systems serve niche heavy truck applications in mining and construction fleets requiring explosion-resistant actuation.
- Mechanical:Cable-operated linkages persist in cost-sensitive motorcycle and emerging market light vehicle segments.
Hydraulic retains volume leadership; electric holds the steepest expansion curve.
Vehicle Type:
Commercial vehicle segments generate higher per-unit value through reinforced specifications, while passenger car volumes face accelerating erosion from transmission electrification.
- Heavy Trucks:Extended-duty cycle validation requirements and corrosion-resistant coating specifications create premium pricing tiers. Fleet operators across Brazil's São Paulo state logistics corridor sustain replacement demand through preventive maintenance programs.
- Passenger Cars:Mature volume base with shrinking manual transmission penetration. Concentric slave cylinders with integrated release bearings miniaturize bore diameters below 19 mm for transverse engine packaging constraints.
- Light Trucks:Aging fleet replacement cycles in North American independent repair networks generate aftermarket margin pools.
- Motorcycles:Mechanical and cable-actuated systems dominate cost-sensitive two-wheeler production.
Passenger cars dominate absolute unit shipments; heavy trucks command the highest value per installation.
End User:
Fleet procurement consolidation favors direct OEM-affiliated channels over independent distributors with integrated technical support capabilities.
- OEMs:Original equipment fitment requires parallel validation against EPA brake-fluid toxicity, REACH chemical restrictions, and China's GB/T hydraulic specifications. Schaeffler Group and ZF Friedrichshafen anchor high-volume programs through captive precision-machining capacity.
- Aftermarket:Independent retailers capture significant margin pools from aging light truck fleets. Latin American logistics operators extend preventive maintenance schedules, generating sustained pull for replacement hydraulic components.
- Fleet Operators:Multinational commercial vehicle buyers consolidate supplier relationships around full-system hydraulic component providers.
- Distributors:Independent channels lose share to direct procurement as e-procurement platforms reshape sourcing patterns.
OEMs retain volume leadership; fleet operators are gaining share fastest through consolidated procurement.
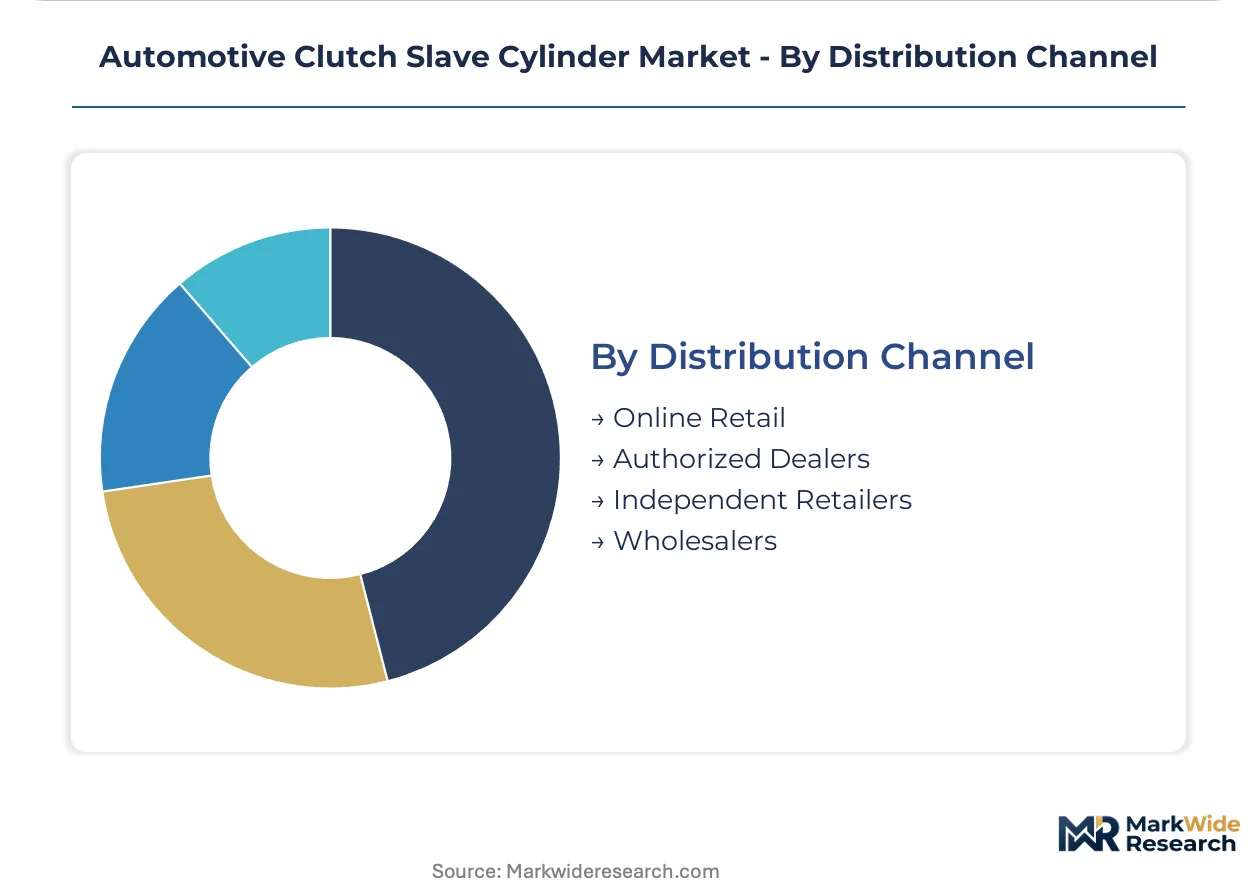
Distribution Channel:
Channel digitization concentrates procurement power among platforms with integrated fluid compatibility certification data and technical documentation.
- Authorized Dealers:OEM-affiliated networks provide warranty-backed installation and diagnostic support. Valeo competes through aftermarket channel density in European repair networks.
- Online Retail:E-procurement platforms expand among Mexico's Querétaro manufacturing corridor repair facilities seeking reduced sourcing friction.
- Independent Retailers:Traditional counter sales face compression from fleet direct procurement and digital intermediation.
- Wholesalers:Bulk distribution serves regional distributor networks with inventory pooling for slower-moving heavy truck specifications.
Authorized dealers retain volume leadership; online retail climbs the fastest as procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico consumes slave cylinders primarily through OEM manufacturing for Latin American export markets, whereas Germany and Japan concentrate on precision-machined component supply to global transmission assemblers. This consumption-mix differential shapes divergent regulatory exposure and investment priorities across major producing regions.
Mexico
Commercial fleet operators extend preventive maintenance schedules for hydraulic clutch systems in aging medium-duty trucks. EPA brake-fluid toxicity regulations under the Toxic Substances Control Act govern components exported to US markets. The Querétaro and Guanajuato manufacturing corridor anchors manual transmission production for Latin American markets facing slower electrification timelines.
Germany
Precision bore machining capacity concentrates among tier-one automotive component suppliers serving European OEM programs. REACH chemical restrictions through ECHA limit legacy elastomer compounds used in piston seals. The Baden-Württemberg industrial cluster houses integrated bearing and clutch module operations controlling captive supply of machined slave cylinder housings.
Japan
Heavy truck suppliers absorb elevated compliance burdens for extended-duty thermal exposure requirements in commercial vehicle applications. METI industrial standards and JIS specifications shape domestic product validation protocols. The Aichi Prefecture manufacturing belt around Nagoya maintains specialized capacity for corrosion-resistant coating specifications in premium commercial segments.
United States
Aging light truck fleets generate aftermarket margin pools through independent repair networks in North American replacement channels. FCC vehicle safety standards and EPA regulations govern material selection and testing protocols for domestic sales. The Midwest automotive corridor spanning Michigan and Ohio retains residual manual transmission expertise amid broader technician scarcity.
China
Dual-clutch transmission architectures in domestic passenger car platforms require precise electronic control systems. GB/T hydraulic system specifications create compliance layers for exporters targeting assembly markets. The Yangtze River Delta manufacturing region around Shanghai concentrates capacity for automated manual transmission component sourcing.
Automotive Clutch Slave Cylinder Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Automotive Clutch Slave Cylinder Market. The upper tier commands captive precision-machining capacity and anchors high-volume OEM programs, while mid-scale specialists compete through aftermarket channel density and regional fleet relationships. Two strategic archetypes dominate: integrated transmission system suppliers with backward control over bearing and housing production, and independent hydraulic component specialists with focused aftermarket penetration. Competitive moves concentrate on cross-platform modularity investments and remanufacturing program certification to capture regulatory-driven replacement demand.
Within the integrated tier, Schaeffler Group and ZF Friedrichshafen occupy positions defined by captive supply chain control over precision-machined components. Valeo exemplifies the aftermarket-focused archetype through channel density strategies in European repair networks. These three anchors represent divergent responses to technology displacement pressure from electromechanical actuation systems.
| Leading Market Players |
|---|
| Schaeffler Group |
| Valeo |
| ZF Friedrichshafen |
| Exedy Corporation |
| Aisin Seiki |
| BorgWarner |
| FTE Automotive |
| Dorman Products |
| Continental |
| Others |
Value Chain & Pricing Dynamics
Precision bore machining capacity utilization above 85% in German and Japanese tier-one facilities creates asymmetric pricing power for captive suppliers while compressing margin structures for non-integrated competitors serving aftermarket channels. This scale concentration enables Schaeffler Group and ZF Friedrichshafen to maintain price floors on OEM programs even as aluminum alloy input volatility erodes margins for independent casting houses.
Pricing Analysis
Long-term offtake contracts dominate OEM supply relationships, with Schaeffler Group and ZF Friedrichshafen anchoring multi-year agreements that lock in volume commitments against raw material escalators. Price differentiation separates corrosion-resistant heavy truck specifications from standard passenger car units, with fleet procurement consolidation intensifying cost compression in Latin American aftermarket channels. Pricing pressure stems from electromechanical substitution in new EV platforms, forcing hydraulic specialists to absorb margin erosion to retain legacy program share. Independent distributors exhibit highest price sensitivity, while integrated transmission system suppliers demonstrate lowest sensitivity due to captive machining capacity.
Supply Chain Analysis
Germany and Japan anchor precision-machined bore surface production, while Mexico concentrates aluminum alloy casting operations for Latin American export markets. The supply chain draws from aluminum alloy feedstock, specialized elastomer seal compounds, and precision bearing assemblies. Single-source vulnerability concentrates in tier-one machining capacity for concentric slave cylinder housings with sub-19 mm bore diameters. Distribution runs through OEM-affiliated authorized dealer networks and direct fleet procurement channels, with e-procurement platforms gaining traction among Mexico's Querétaro corridor repair facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
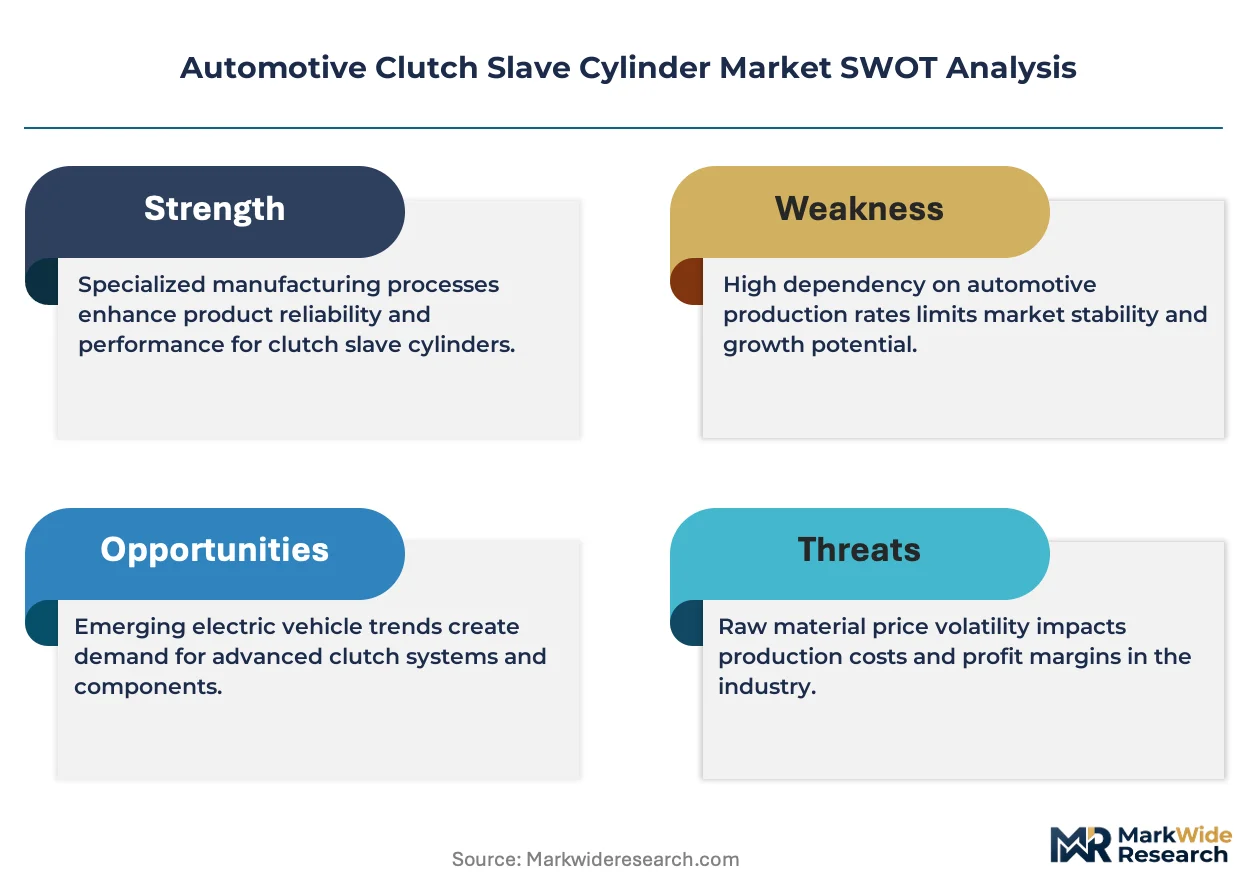
This market operates as a defensive-moat story where regulatory entrenchment around EPA brake-fluid toxicity and REACH chemical compliance creates switching costs that protect incumbent positions against technology displacement.
For Market Incumbents: Consolidate captive machining capacity in Germany and Japan to defend margin structures against aluminum alloy price volatility. Deepen backward integration into precision bearing production to control cost positions as electromechanical actuation erodes hydraulic volumes. Invest in remanufacturing program certification to capture EPA regulatory-driven replacement demand.
For New Entrants and Emerging Players: Anchor in Mexico's Querétaro and Guanajuato manufacturing corridor where manual transmission production sustains hydraulic demand against slower regional electrification timelines. Target aftermarket digitization white space through e-procurement platforms serving independent repair networks lacking fluid compatibility certification support. Pursue fleet direct procurement relationships with Latin American logistics operators extending preventive maintenance schedules.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated transmission system suppliers with backward control over bearing and housing production. Long-term viability hinges on amortizing hydraulic tooling investments against declining manual transmission penetration while capturing aftermarket replacement cycles in aging commercial fleets. Watch fleet electrification adoption curves in Brazil's São Paulo state logistics corridor as inflection indicators for replacement demand compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Remanufacturing Program Certification | EPA brake-fluid toxicity standards create regulatory space for certified remanufactured units with reduced environmental liability. |
| Cross-Platform Modularity Investment | Converging automated manual and dual-clutch architectures enable shared slave cylinder designs across OEM programs. |
| Aftermarket Channel Digitization | E-procurement platforms serving Mexico's Querétaro corridor repair facilities reduce sourcing friction for independent distributors. |
| Seal Material Upgrade Validation | REACH chemical restrictions through ECHA compel elastomer compound upgrades that improve cylinder durability. |
| Precision Machining Capacity Expansion | Sub-19 mm bore diameter miniaturization for transverse engine packaging requires specialized machining investments. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against vehicle production databases, IHS Markit registration data, EPA regulatory filings, and ECHA chemical restriction announcements. Bottom-up segmentation triangulation across product type, vehicle category, and regional production clusters converged with top-down macroeconomic indicators.
Sensitivity analysis framed the quantitative modeling across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to baseline volume estimates, incorporating aluminum alloy price elasticity and electrification adoption scenario weights. Industry-specific inputs included manual transmission penetration trajectories and commercial fleet replacement cycle patterns.
Material uncertainties — abrupt electrification acceleration, regulatory divergence on brake-fluid standards, and aluminum alloy supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about technology substitution rates and fleet procurement consolidation trajectories. Recalibration cycles align with material shifts in electrification policy and commercial vehicle emission regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Power Steering Filter Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
LNG Engine Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Engine Rocker Arm Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Diesel Engine Management System Market
Powertrain
Torque Limiter Market