
 Glazing for Automotive Market | 2026-2036
Glazing for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Glazing for Automotive Market Analysis
F-Gas Regulation is decoupling fluorinated gas-intensive manufacturing from the cost-of-entry calculus for European glazing suppliers. AGC Inc. leverages its integrated float glass operations to control raw material quality across multiple continents. Saint-Gobain Sekurit anchors its competitive position through deep partnerships with premium German OEMs. Fuyao Glass Industry Group dominates volume supply to Chinese domestic brands while extending manufacturing scale into North American assembly corridors.
Glazing for automotive encompasses transparent and translucent barrier systems installed in vehicle apertures, typically comprising laminated safety glass for windshields with polyvinyl butyral interlayers and tempered glass for side and rear applications, engineered to provide occupant protection, acoustic insulation, and structural integrity during rollovers. Laminated glass commands the largest share of OEM specification books due to mandatory windshield safety standards, while polycarbonate segments represent the fastest-growing material category as weight reduction targets intensify for battery electric platforms. Sunroof applications concentrate margin pools among premium vehicle lines, whereas aftermarket replacement channels operate on thinner spreads tied to insurance reimbursement schedules.
NHTSA's Federal Motor Vehicle Safety Standards govern glazing impact resistance and optical clarity for US market access, while ECE R43 homologation requirements shape European product development cycles and testing protocols. China's GB 9656 standard mandates specific light transmittance and fragmentation thresholds for domestic vehicle certification. Stakeholders must monitor regulatory divergence between regional safety frameworks and emerging circular-economy mandates for end-of-life glazing recovery.
Market Dynamics
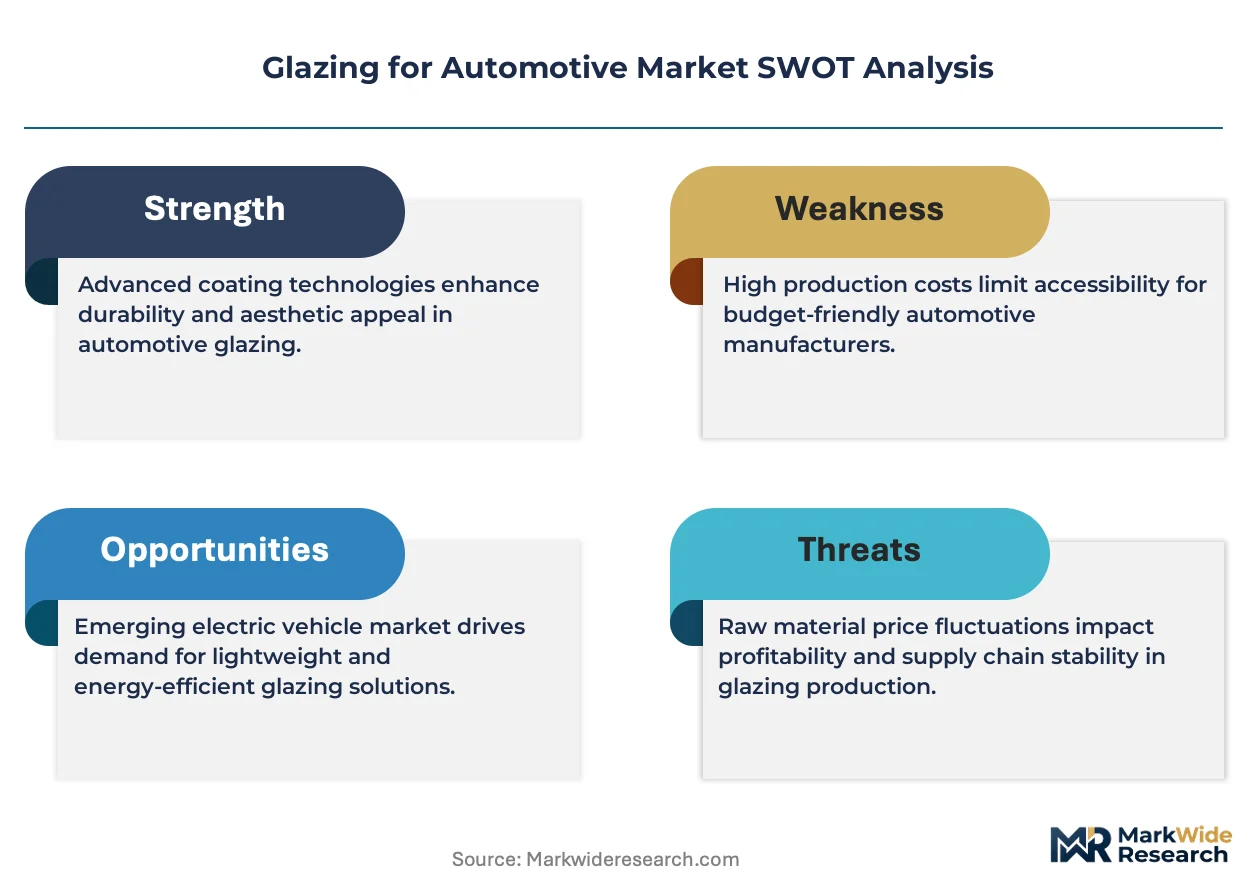
Europe's F-Gas Regulation is compressing the manufacturing window for fluorinated gas-intensive glazing processes, forcing material transitions toward polycarbonate and low-emissivity alternatives while redrawing supplier qualification criteria across OEM specification books.
Growth Catalysts
- Electric Vehicle Weight Targets:Battery electric platforms are mandating polycarbonate glazing to offset battery mass, with OEMs rewriting windshield and side-glass specifications for 15-20% weight reduction.
- ECE R43 Homologation:European safety standards for optical clarity and impact resistance are accelerating laminated glass upgrades across premium vehicle lines, tightening testing protocols for new market entrants.
- Germany's Manufacturing Corridor:OEM engineering centers in Stuttgart and Munich are sourcing advanced glazing architectures for next-generation vehicle platforms, concentrating R&D pull in Southern Germany.
Market Restraints
- Petrochemical Feedstock Volatility:Polycarbonate resin prices track benzene and propylene markets, compressing margin predictability for lightweight glazing programs.
- Float Glass Supply Concentration:Integrated glass manufacturers control 70%+ of high-quality silica sand access, limiting independent processor expansion in North America and Europe.
- Optical Distortion Limits:Polycarbonate windshields face persistent haze and abrasion resistance thresholds that laminated glass clears under NHTSA Federal Motor Vehicle Safety Standard 205.
Strategic Opportunities
- Head-Up Display Integration:Windshield-embedded HUD systems are creating specification premiums for wedge-shaped laminated glass with pvb interlayer precision control.
- China's Dual Carbon Goals:MIIT energy-efficiency mandates for vehicle production are opening procurement windows for solar-control glazing in domestic electric vehicle assembly.
- End-of-Life Recovery Mandates:EU circular-economy directives for automotive materials are positioning closed-loop pvb and glass separation technologies as qualification differentiators.
Industry Challenges
- Multi-Physics Simulation Talent:Glazing engineers capable of modeling optical, acoustic, and structural performance simultaneously command premium compensation and extended recruitment cycles.
- Homologation Timeline Compression:ECE R43 and NHTSA dual-certification requirements for global vehicle platforms extend validation programs by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazing for Automotive Market |
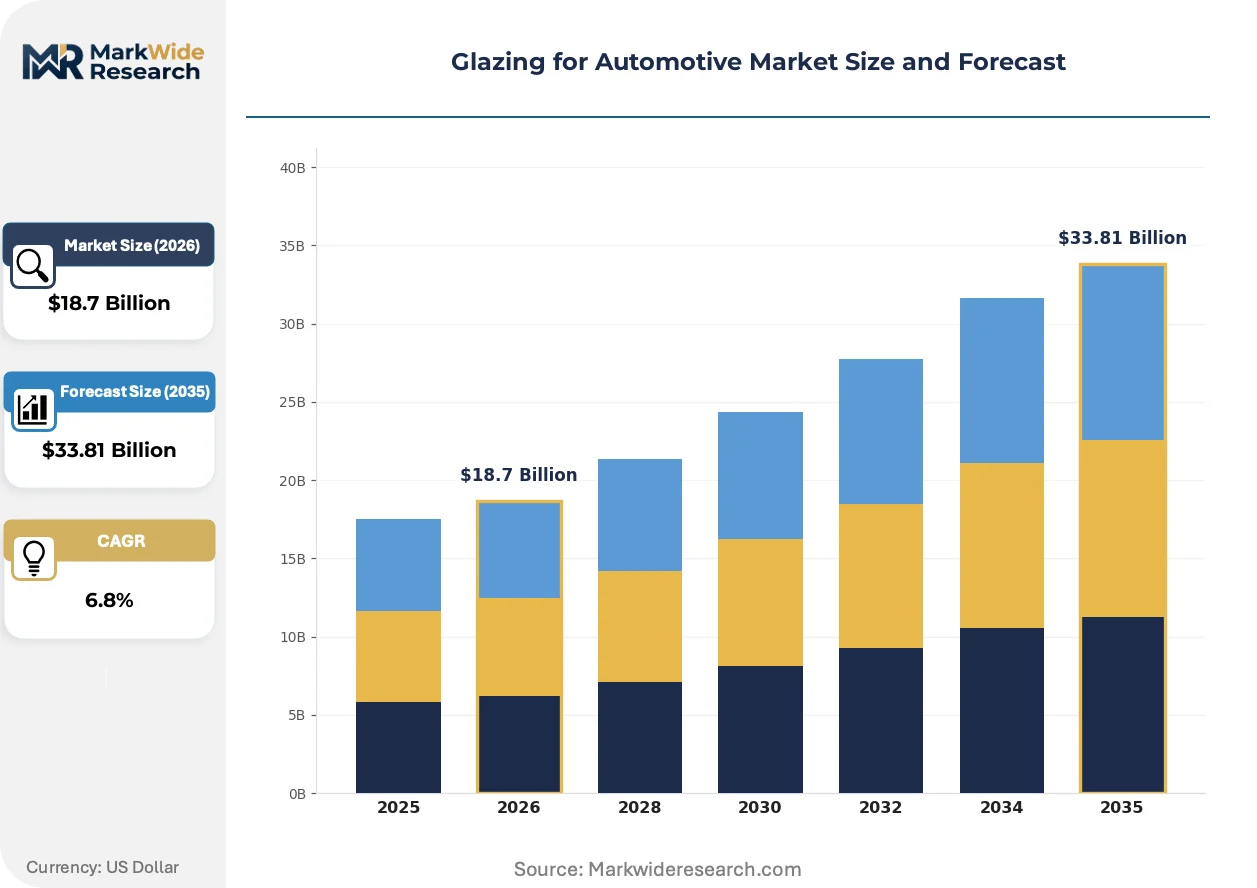
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield, Side Windows, Rear Windows, Sunroofs Material: Tempered Glass, Laminated Glass, Polycarbonate, Acrylic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Adhesive Bonding, Mechanical Fastening, Integrated Manufacturing, Replacement |
| Companies Covered | AGC Inc., Central Glass, Saint-Gobain Sekurit, Pilkington, Corning Incorporated, Fuyao Glass Industry Group, Xinyi Glass Holdings, SABIC, Nippon Sheet Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazing for Automotive Market Emerging Trajectories
Glazing technology is converging with sensor integration and energy management systems, transforming transparent vehicle surfaces from passive barriers into active functional components.
Smart glass with electrochromic and suspended particle device layers is unifying solar control with occupant comfort automation. Premium electric vehicle lines are specifying switchable tinting for panoramic roofs and rear windows. This convergence is compressing the traditional separation between glazing suppliers and climate-system integrators.
Europe's F-Gas Regulation is banning hydrofluorocarbon blowing agents in insulated glazing manufacturing from 2025. Suppliers are retrofitting float lines with hydrocarbon and CO2-based alternatives. German and French OEMs are accelerating supplier audits to verify compliance ahead of enforcement deadlines.
Fleet procurement departments are consolidating glazing contracts under total-cost-of-ownership frameworks rather than unit-price bidding. Rental and commercial vehicle operators in the United States are bundling replacement schedules with telematics-driven damage detection. This restructuring concentrates volume with suppliers offering predictive service networks.
Glazing for Automotive Market Segmentation
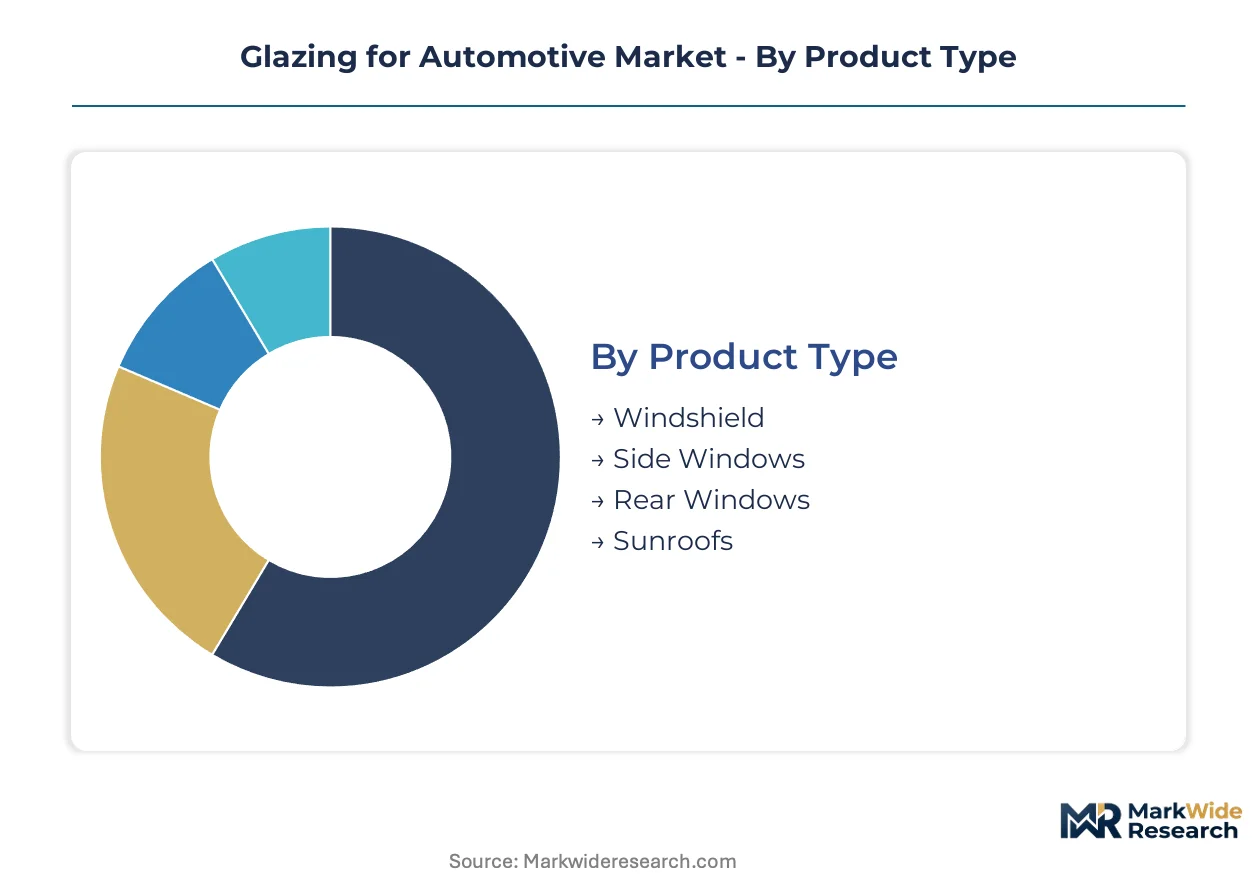
Automotive glazing segments fracture along distinct upgrade cycles and replacement economics. OEM specifications drive laminated glass premiums while aftermarket channels compress margins on tempered glass volume plays. Material transitions and installation method choices reshape supplier qualification hierarchies across vehicle platforms.
Product Type:
Upgrade cycles vary dramatically by aperture position, with windshields commanding replacement premiums and sunroofs driving factory-installed specification complexity.
- Windshield:Laminated safety glass with polyvinyl butyral interlayers dominates OEM specification books due to mandatory impact resistance standards. German luxury manufacturers source wedge-shaped variants for head-up display integration, tightening optical clarity tolerances beyond base regulatory floors.
- Sunroofs:Panoramic configurations concentrate margin pools among premium electric vehicle lines, with switchable electrochromic layers unifying solar control with cabin comfort automation. Stuttgart engineering centers specify bonded frameless architectures for next-generation platforms.
- Side Windows:Tempered glass segments serve cost-optimized vehicle lines with standardized fragmentation patterns under ECE R43 protocols.
- Rear Windows:Defroster-integrated tempered units follow replacement schedules tied to insurance reimbursement frameworks in North American markets.
Windshield sits at the top of the volume ranking, with Sunroofs climbing the fastest.
Material:
Cost tiers separate legacy glass formulations from lightweight polymer alternatives, with polycarbonate commanding technology premiums and acrylic serving economy segments.
- Laminated Glass:Polyvinyl butyral interlayer technology delivers occupant retention during rollovers and acoustic damping for luxury cabin architectures. Munich-based OEMs specify acoustic-grade variants with enhanced damping layers for electric vehicle platforms where powertrain noise masking requirements have shifted.
- Polycarbonate:Injection-molded resin systems enable 40-50% mass reduction versus glass equivalents, offsetting battery pack weight in electric architectures. NHTSA optical distortion thresholds currently constrain windshield applications to side and rear apertures.
- Tempered Glass:Thermal strengthening processes produce standardized side and rear units for high-volume assembly lines.
- Acrylic:Cast polymer sheets serve aftermarket replacement channels and specialty vehicle applications with lower structural load requirements.
Laminated Glass captures the largest share of OEM specification value, while Polycarbonate expands most quickly.
End User:
Customer type dictates procurement scale and technical integration depth, with OEMs driving specification innovation and aftermarket channels competing on logistics velocity.
- OEMs:Original equipment manufacturers consolidate glazing contracts under total-cost-of-ownership frameworks, bundling multi-year supply agreements with design-phase engineering collaboration. German premium brands require dedicated program management offices at supplier facilities.
- Aftermarket Providers:Independent distributors operate on compressed margins tied to insurance reimbursement schedules, with mobile installation networks competing on response time metrics. US fleet operators are consolidating contracts under telematics-driven damage detection systems.
- Vehicle Assemblers:Contract manufacturing facilities source glazing through tiered supplier arrangements for regional production flexibility.
- Tier-1 Suppliers:System integrators manage sub-assembly complexity for OEMs seeking modular cockpit and closure system sourcing.
OEMs sit at the top of the volume ranking, with Aftermarket Providers climbing the fastest.
Installation Type:
Application method determines labor content and structural integration depth, with adhesive systems enabling design freedom and mechanical methods preserving service accessibility.
- Adhesive Bonding:Polyurethane structural adhesives enable frameless designs and contribute to rollover structural integrity, with cure-time requirements dictating assembly line sequencing. Premium electric vehicle platforms specify high-modulus formulations for stiffness contribution.
- Replacement:Mobile service networks execute windshield swaps under insurance claim workflows, with cold-weather cure protocols extending job times in northern climates. US commercial fleet operators are bundling predictive replacement schedules with telematics platforms.
- Mechanical Fastening:Gasket and clip systems preserve service accessibility for commercial vehicle applications with high damage frequency.
- Integrated Manufacturing:Glazing-in-white processes embed units during body-in-white assembly for structural contribution maximization.
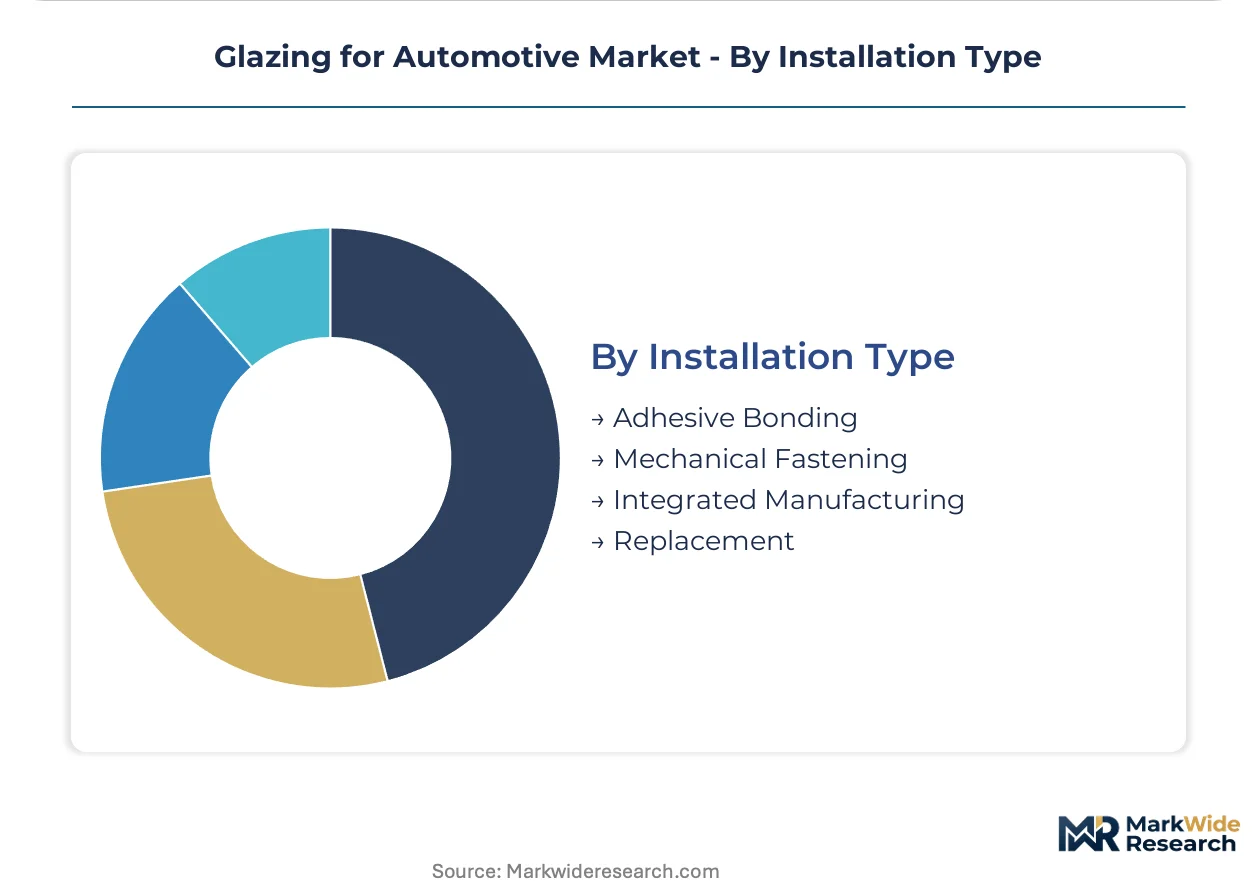
Adhesive Bonding sits at the top of the volume ranking, with Replacement climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive glazing originated in European craft glassmaking before scaling through American mass production and Asian manufacturing consolidation. Germany's float glass innovations established quality benchmarks adopted worldwide. Contemporary demand concentrates in manufacturing corridors where OEM engineering centers co-locate with supplier technical facilities.
Germany
Stuttgart and Munich engineering centers specify wedge-shaped laminated glass for head-up display integration in premium electric platforms. The F-Gas Regulation accelerates supplier audits for hydrocarbon-based manufacturing alternatives ahead of enforcement deadlines. Bavarian glass corridors concentrate R&D pull for next-generation vehicle architectures.
China
Domestic electric vehicle brands drive polycarbonate adoption for battery weight offset, with MIIT energy-efficiency mandates opening procurement windows for solar-control glazing. GB 9656 standards mandate specific light transmittance thresholds for vehicle certification. Yangtze River Delta manufacturing clusters scale advanced glazing supply for regional assembly lines.
United States
NHTSA Federal Motor Vehicle Safety Standard 205 maintains laminated glass dominance for windshield applications due to optical clarity thresholds. Michigan-based OEM engineering centers source acoustic-grade variants for electric vehicle cabin architectures. Southeast assembly corridors attract glazing-in-white process investments for structural integration.
Japan
METI industrial policy supports lightweight material transitions in automotive supply chains, with domestic OEMs specifying advanced interlayer technologies. JIS standards shape fragmentation pattern requirements for tempered glass applications. Kanto region technical centers coordinate specification development with tier-1 system integrators.
South Korea
Seoul Capital Area battery electric platforms drive polycarbonate side-window specifications for mass reduction targets. Domestic OEMs integrate smart glass with electrochromic layers for premium vehicle lines. Busan-Ulsan industrial corridors concentrate glazing sub-assembly operations for export-oriented production.
Glazing for Automotive Market Vendor Landscape
The competitive structure tilts toward integrated glass manufacturers with captive float line operations. Three to five multinational suppliers control premium OEM specification books through dedicated program management structures. The vendor base separates into integrated raw material controllers, regional volume specialists, and polymer technology licensors. Capacity expansion and strategic technology licensing represent dominant competitive moves as weight reduction targets intensify.
Within the integrated multinational tier, AGC Inc., Saint-Gobain Sekurit, and Fuyao Glass Industry Group occupy positions that exemplify distinct geographic and structural archetypes. AGC represents Japanese-originated integrated operations spanning multiple continents. Saint-Gobain Sekurit anchors European premium OEM relationships through deep specification partnerships. Fuyao exemplifies Chinese scale-driven expansion into North American assembly corridors while maintaining domestic brand dominance.
| Leading Market Players |
|---|
| AGC Inc. |
| Central Glass |
| Saint-Gobain Sekurit |
| Pilkington |
| Corning Incorporated |
| Fuyao Glass Industry Group |
| Xinyi Glass Holdings |
| SABIC |
| Nippon Sheet Glass |
| Others |
Supply Flow & Price Mechanics
Family-owned float glass operations across Southern Germany and Northern France anchor supply discipline, translating captive silica sand access into pricing power over polycarbonate-dependent challengers facing benzene feedstock volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated glass manufacturers and German premium OEMs, with price differentiation hinging on acoustic-grade certification tiers and head-up display optical precision. Three-tier pricing structure across premium, standard, and economy levels separates wedge-shaped HUD-integrated windshields from base laminated safety units and aftermarket tempered replacements. Cost compression in polycarbonate segments is intensifying because petrochemical resin prices track propylene market swings. Fleet procurement departments exhibit the highest price sensitivity, bundling replacement schedules under total-cost-of-ownership frameworks, while Stuttgart engineering centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's MIIT energy-efficiency directives are reshaping sourcing patterns, compelling Yangtze River Delta assembly clusters to prioritize local solar-control glazing suppliers over imported alternatives. Geographic supply concentration centers on Germany, China, and the United States, with Bavarian glass corridors feeding European premium platforms and Southeast US assembly lines absorbing glazing-in-white process investments. Raw material dependencies rest on high-purity silica sand reserves, polyvinyl butyral resin systems, and petroleum-derived polycarbonate pellets. Single-source vulnerability characterizes float glass supply, where integrated manufacturers control captive silica access. Distribution runs through tiered supplier arrangements anchored by dedicated program management offices at OEM facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's F-Gas Regulation operates as a regulatory compounder, accelerating material transitions toward hydrocarbon-based manufacturing alternatives and compressing qualification timelines for non-compliant suppliers.
For Market Incumbents: Acquire closed-loop PVB and glass separation technologies to preempt EU circular-economy directive enforcement. Consolidate backward integration into high-purity silica sand reserves to defend margin position against polycarbonate challengers facing feedstock volatility. Deepen acoustic-grade interlayer R&D partnerships with Munich-based OEM engineering centers to maintain specification lock-in for electric vehicle platforms. For New Entrants and Emerging Players: The premium-to-economy price gap in aftermarket replacement channels offers white-space entry for mobile installation networks bundling telematics-driven damage detection. Target US commercial fleet operators consolidating contracts under predictive service frameworks, bypassing insurance reimbursement schedule compression. Pursue polycarbonate side-window specifications for Seoul Capital Area battery electric platforms as the most penetrable lightweight glazing segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional volume specialists lacking float line integration but holding certified supplier status with domestic Chinese electric vehicle brands. The five-to-ten year viability window favors acquisition of polymer technology licensors with NHTSA optical clarity pathway progress. Watch for ECE R43 homologation timeline compression as the signal indicating incumbent qualification bottlenecks opening to agile challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Reserves | Captive raw material access insulates margin predictability from polycarbonate feedstock volatility tracked by benzene markets. |
| Head-Up Display Optical Precision Certification | Wedge-shaped laminated glass specifications with PVB interlayer control command procurement premiums from Stuttgart engineering centers. |
| Closed-Loop End-of-Life Recovery Technology | PVB and glass separation capabilities differentiate suppliers under EU circular-economy directives for automotive materials. |
| Polycarbonate Windshield Optical Clarity Pathway | NHTSA Federal Motor Vehicle Safety Standard 205 compliance investment unlocks mass reduction opportunities for battery electric platforms. |
| Telematics-Integrated Predictive Service Networks | Mobile installation platforms bundling damage detection consolidate aftermarket volume with US fleet procurement departments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and dealership service managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from integrated glass manufacturers, and customs trade records. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulated volume and value estimates across material, product type, and end-user dimensions.
Historical reference periods anchored the projection horizon to observed adoption curves for polycarbonate glazing in battery electric platforms and laminated glass upgrade cycles in premium vehicle lines. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as core segmentation dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with electric vehicle weight targets and F-Gas Regulation compliance timelines serving as primary demand-side and supply-side forecast inputs.
The model assumes a particular technology adoption path for polycarbonate windshield optical clarity advancement; alternative pathways for NHTSA certification delays would alter the outlook toward prolonged laminated glass dominance. Forecasts reflect assumptions regarding ECE R43 homologation timeline stability, petrochemical feedstock price corridors, and OEM platform standardization decisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Europe Automotive Seat Market