
 Paint Protection Film Market | 2026-2036
Paint Protection Film Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Protection Film Market Intelligence
Asset-light leasing models for precision coating equipment is rewriting competitive entry barriers in paint protection film manufacturing. XPEL leverages its North American installer network to sustain premium pricing power. Eastman Chemical Company anchors supply security through captive production of aliphatic TPU resins. Saint-Gobain S.A. differentiates via multi-layer sputtering expertise inherited from architectural glass coatings.
Paint protection film comprises multi-layer thermoplastic polyurethane or polyvinyl chloride laminates, typically 6–8 mils thick, with a self-healing top coat activated by ambient heat to recover from minor scratches. The product shields painted substrates from stone chips, UV degradation, and chemical staining in high-exposure environments. Self-healing films command margin premiums due to complex top-coat chemistry, while matte finish variants capture growing aftermarket customization demand in automotive applications. Professional installation channels dominate value capture despite DIY growth, as precision cutting and paint preparation determine warranty validity and optical clarity outcomes.
EPA regulates volatile organic compound emissions from adhesive solvents used in PPF lamination, compelling formulation shifts toward compliant chemistries. REACH restricts isocyanate-containing components in European-sourced TPU grades, altering raw material qualification protocols for multinational suppliers. California Air Resources Board imposes the strictest state-level VOC limits, effectively setting the compliance ceiling for products sold across the United States. Stakeholders must monitor evolving chemical restriction schedules and installer certification requirements to anticipate where compliance costs will reshape competitive economics.
Market Dynamics
California Air Resources Board VOC limits are compressing formulation windows for solvent-based PPF adhesives, forcing manufacturers to rebuild coating lines around water-based and UV-cured chemistries. This regulatory compression is reshaping capital allocation across the supply base.
Growth Catalysts
- Luxury OEM Specification:Factory-installed PPF programs at premium automotive brands are normalizing paint protection as a standard deliverable rather than aftermarket add-on.
- REACH Isocyanate Restrictions:European TPU qualification protocols are accelerating investment in aliphatic resin grades with superior UV stability and hydrolysis resistance.
- Sun Belt Concentration:Vehicle ownership density in Texas, Florida, and California generates sustained replacement demand driven by UV exposure and environmental degradation.
Market Restraints
- Aliphatic TPU Supply Concentration:Captive resin production at major chemical conglomerates limits independent film manufacturers' negotiating leverage on input costs.
- Professional Installation Dependency:Precision cutting and paint preparation requirements prevent full value capture through DIY channels, constraining volume scalability.
- Matte Finish Chemistry Complexity:Specialized top-coat formulations for non-gloss aesthetics carry yield losses and quality control penalties that compress margins.
Strategic Opportunities
- Dealer Network Penetration:Certified installation partnerships with franchised automotive retailers offer protected territory models and recurring fleet protection contracts.
- Water-Based Adhesive Transition:EPA compliance trajectories favor early movers with qualified low-VOC lamination processes and documented emissions reductions.
- Multi-Layer Sputtering Transfer:Architectural glass coating expertise from adjacent industrial films enables advanced optical-grade PPF with enhanced clarity and durability.
Industry Challenges
- Installer Certification Bottlenecks:Warranty validity requirements demand trained technician pipelines that outpace vocational program output in high-demand markets.
- Optical Clarity Standards:Subjective quality thresholds for self-healing film appearance create customer dispute risk and rework costs that erode job profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Protection Film Market |
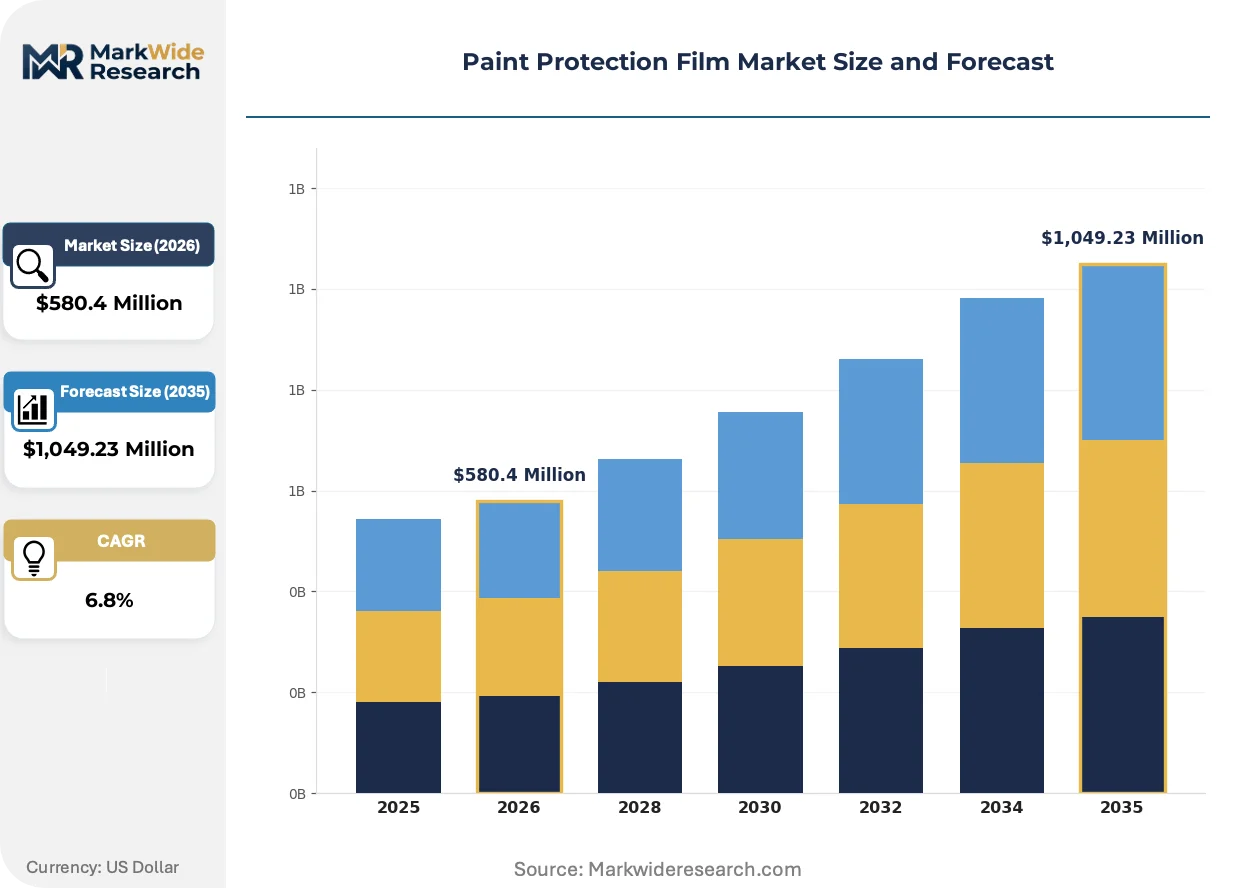
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,049.23 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Healing, Clear Bra, Matte Finish, Colored Film Application: Automotive, Electronics, Aerospace, Marine Installation: DIY, Professional, Mobile Services, Retail Distribution Channel: Online, Offline, Specialty Stores, Wholesalers |
| Companies Covered | 3M, XPEL, Eastman Chemical Company, Avery Dennison Corporation, Saint-Gobain S.A., ORAFOL Europe GmbH, Hexis S.A.S., STEK-USA, RENOLIT SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Protection Film Market Strategic Shifts & Innovations
Digital pattern databases and precision cutting equipment are virtualizing the installation workflow, reducing material waste while compressing job times. Three convergent developments are restructuring how protection films reach end users.
Computer-aided design libraries linked to vehicle VIN databases are virtualizing the template generation process for PPF installation. Professional detailers and authorized dealers are adopting these systems to eliminate hand-cutting errors and reduce material scrap rates. This digitization is virtualizing the traditional skill-based differentiation between elite installers and generalist shops, compressing quality variance across the service tier.
EPA volatile organic compound regulations for adhesive solvents are compelling lamination line retrofits at manufacturing facilities serving the United States market. Formulation shifts toward water-based and UV-cured alternatives require capital-intensive coating equipment upgrades and requalified supply chains. California's sub-federal limits are driving product architecture decisions for nationwide distribution, with manufacturers consolidating SKUs around compliant chemistries.
Fleet managers and lease return operations are unbundling paint protection from bundled reconditioning packages, creating direct procurement relationships with certified installation networks. This disintermediation of traditional body shop channels is visible in commercial vehicle segments where damage charge avoidance drives specification. Texas and Florida commercial fleets are leading this pattern, with volume contracts replacing per-vehicle retail transactions.
Paint Protection Film Market Segmentation
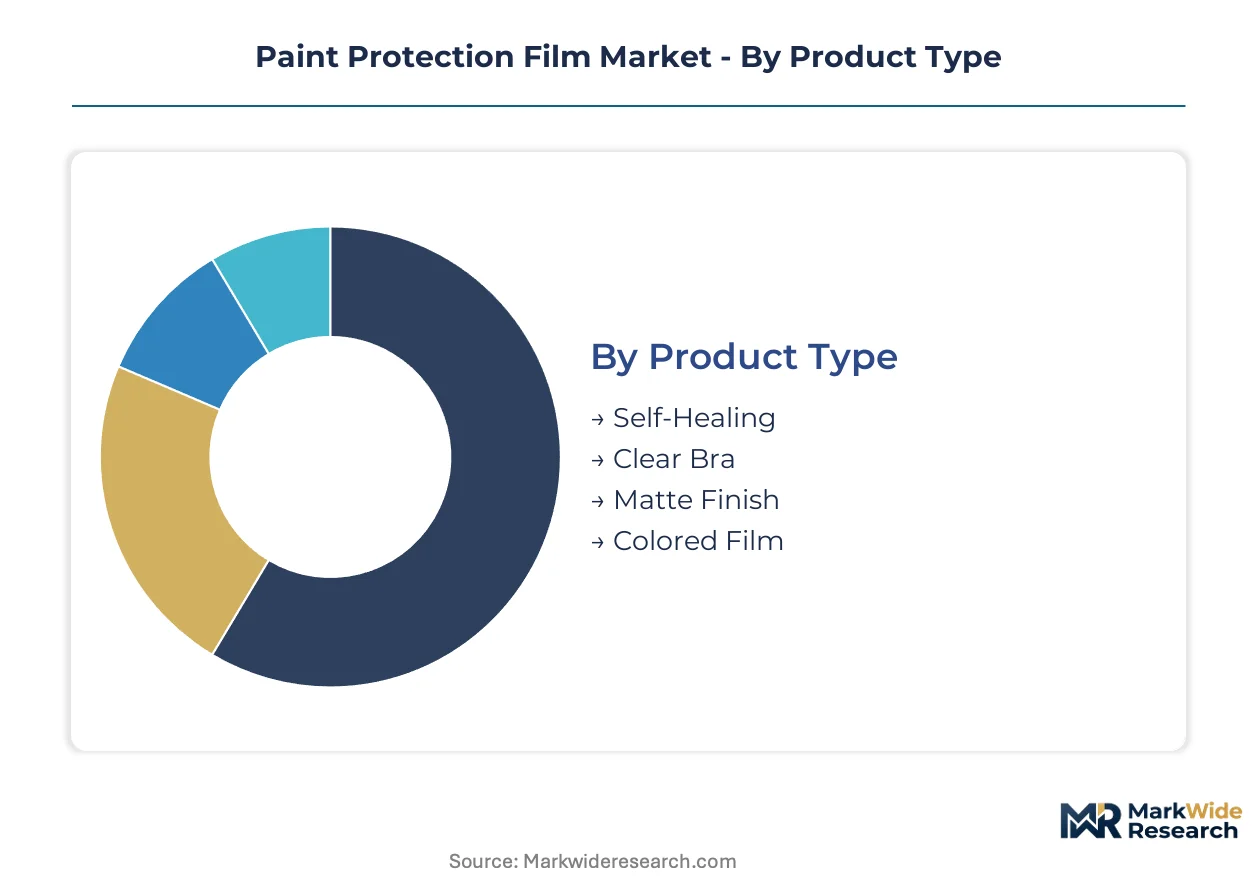
PPF market segmentation reveals how technical performance tiers, installation economics, and channel access create distinct profit pools. Manufacturers must align formulation investments with the specific durability and aesthetic requirements of each application vertical.
Product Type:
Mature self-healing films dominate premium automotive programs, while emerging matte and colored variants are capturing aftermarket customization demand.
- Self-Healing:Thermoplastic polyurethane substrates with heat-activated top-coat chemistry recover from minor scratches without manual intervention. Luxury OEM factory programs in Germany, Japan, and the United States specify these grades for dealer-installed protection packages, with warranty validity tied to certified installer networks.
- Clear Bra:Traditional transparent TPU or PVC laminates provide baseline stone-chip protection without optical tint. Fleet procurement in Texas and Florida favors these cost-controlled specifications for commercial lease return operations where damage charge avoidance drives volume.
- Matte Finish:Specialized top-coat formulations create non-gloss aesthetics for customized vehicle appearances.
- Colored Film:Pigmented PPF variants enable color-change protection without full vehicle repainting.
Self-healing films retain volume leadership; colored film holds the steepest expansion curve.
Application:
Cost tier stratification separates high-specification automotive programs from price-sensitive industrial protective films.
- Automotive:Passenger vehicle protection consumes the majority of TPU resin output, spanning factory-installed hood and bumper coverage to full-vehicle aftermarket wraps. California, Texas, and Florida generate replacement demand cycles driven by UV exposure intensity and environmental degradation rates.
- Electronics:Precision-cut films protect high-value device surfaces from abrasion and chemical exposure. Asian manufacturing clusters for consumer electronics specify optical-grade clarity thresholds that reject standard automotive film grades.
- Aerospace:Specialized formulations address altitude UV exposure and thermal cycling on exterior surfaces.
- Marine:Salt-water resistant grades protect gelcoat finishes on recreational vessels in coastal Florida and Mediterranean markets.
Automotive commands the revenue base; electronics claims the fastest margin expansion.
Installation:
Customer type segmentation distinguishes skill-dependent professional channels from convenience-oriented retail access.
- Professional:Authorized dealer and dedicated detailer networks capture value through precision cutting, paint preparation, and warranty registration. EPA-compliant water-based adhesive films require controlled environment application that DIY channels cannot replicate.
- Mobile Services:Technician-deployed installation units reduce customer friction for fleet and commercial accounts. Texas commercial vehicle operators increasingly contract mobile providers for volume protection at depot locations.
- DIY:Pre-cut kit formats serve cost-conscious consumers with simplified application protocols.
- Retail:Big-box automotive sections and specialty accessory stores stock limited SKUs for immediate purchase.
Professional installation locks in the premium tier; mobile services are climbing the fastest.
Distribution Channel:
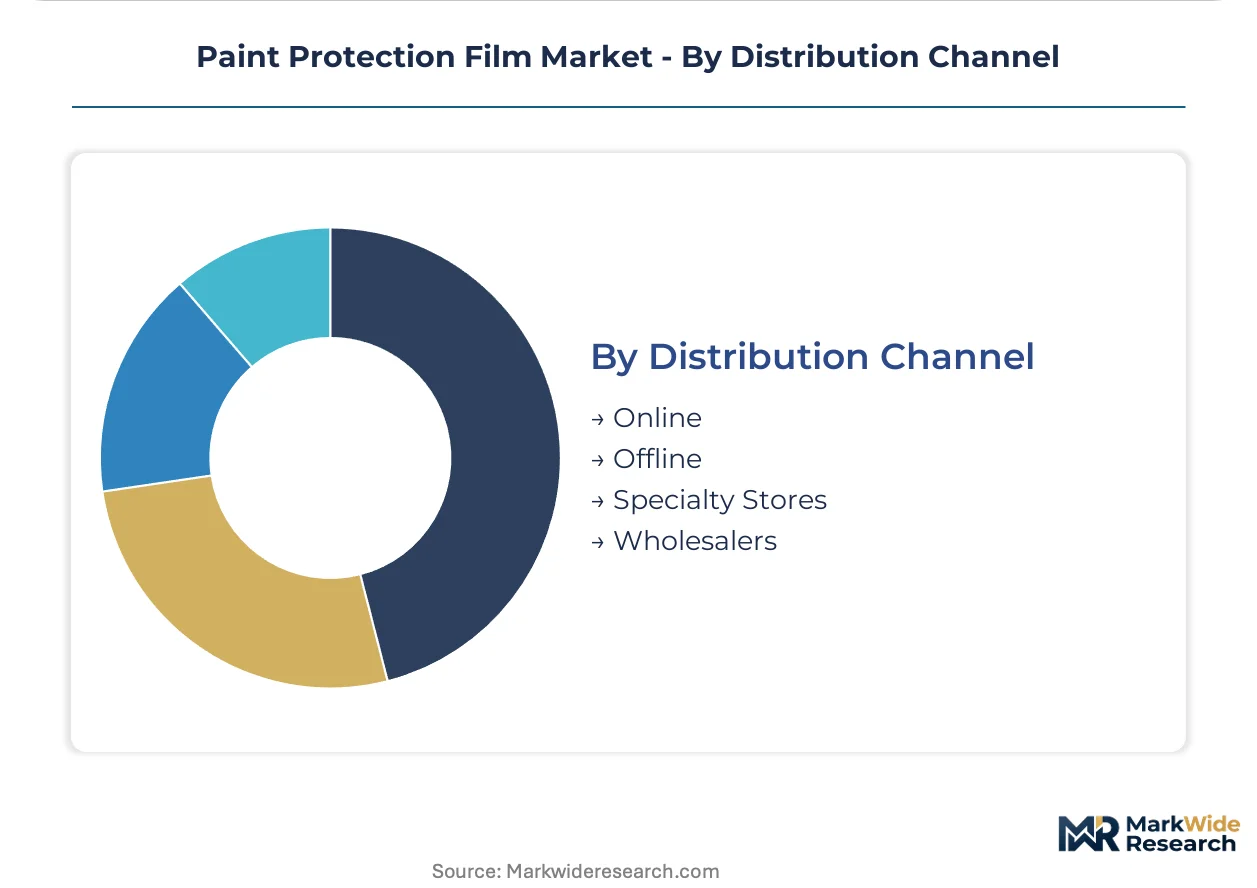
Supply concentration shapes how formulation-compliant products reach end users across fragmented installer networks.
- Offline:Authorized dealer networks and specialty automotive retailers maintain physical inventory for immediate installation scheduling. California CARB-compliant product lines consolidate through these channels due to technical consultation requirements.
- Specialty Stores:Dedicated automotive protection retailers curate premium grades with demonstrated optical clarity performance.
- Online:Direct-to-consumer platforms and marketplace listings expand geographic reach for standardized film kits.
- Wholesalers:Regional distributors aggregate volume for independent installer shops and fleet service providers.
Offline channels retain volume leadership; online distribution posts the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California Air Resources Board VOC limits are forcing lamination line retrofits across manufacturing facilities serving the United States market. This regulatory compression is reshaping capital allocation and product architecture decisions for nationwide distribution.
United States
Texas and Florida commercial fleets are unbundling paint protection from bundled reconditioning packages, creating direct procurement relationships with certified installation networks. EPA regulations on volatile organic compound emissions from adhesive solvents compel formulation shifts toward water-based and UV-cured chemistries. California leads consumer uptake due to high vehicle ownership density and intense UV exposure driving replacement demand cycles.
Germany
Luxury automotive OEMs in Germany specify self-healing PPF grades for factory-installed dealer protection packages. REACH restrictions on isocyanate-containing components in European-sourced TPU grades accelerate investment in aliphatic resin grades with superior UV stability. The Stuttgart and Munich automotive clusters concentrate precision coating equipment leasing activity for Tier 1 supplier integration.
China
Asian manufacturing clusters for consumer electronics specify optical-grade clarity thresholds that reject standard automotive film grades for device surface protection. The country's national chemical regulator enforces standards on solvent-based adhesive emissions in lamination processes. The Yangtze River Delta and Pearl River Delta industrial corridors host precision film converting operations serving domestic electronics brands.
Japan
Japanese luxury vehicle manufacturers normalize paint protection as a standard deliverable through factory-installed PPF programs rather than aftermarket add-ons. METI industrial standards influence TPU resin qualification protocols for multinational suppliers operating in the region. The Kanto and Kansai manufacturing belts concentrate automotive OEM specification activity and dealer network certification programs.
South Korea
Seoul Capital Area fleet managers and lease return operations drive specification of cost-controlled clear bra specifications for damage charge avoidance. The national chemical safety agency regulates isocyanate exposure limits in TPU resin handling facilities. The Busan-Ulsan industrial corridor hosts film lamination operations serving domestic automotive and electronics export demand.
Paint Protection Film Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into consolidated chemical conglomerates with captive resin production, precision coating equipment lessors, and dedicated film converters with installer network partnerships. Three strategic archetypes dominate: aliphatic TPU resin integrators, multi-layer sputtering technology specialists, and precision cutting equipment lessors. Competitive moves concentrate on strategic partnerships with franchised automotive retailers and technology licensing for water-based adhesive formulations.
Within the resin-integrated tier, Eastman Chemical Company and Saint-Gobain S.A. exemplify upstream control strategies. Among dedicated film specialists, XPEL occupies a position defined by installer network density. ORAFOL Europe GmbH represents the precision coating equipment and adhesive technology vector. These three anchors illustrate how competitive economics split between raw material security and distribution channel access.
| Leading Market Players |
|---|
| 3M |
| XPEL |
| Eastman Chemical Company |
| Avery Dennison Corporation |
| Saint-Gobain S.A. |
| ORAFOL Europe GmbH |
| Hexis S.A.S. |
| STEK-USA |
| RENOLIT SE |
| Others |
Cost & Logistics Intelligence
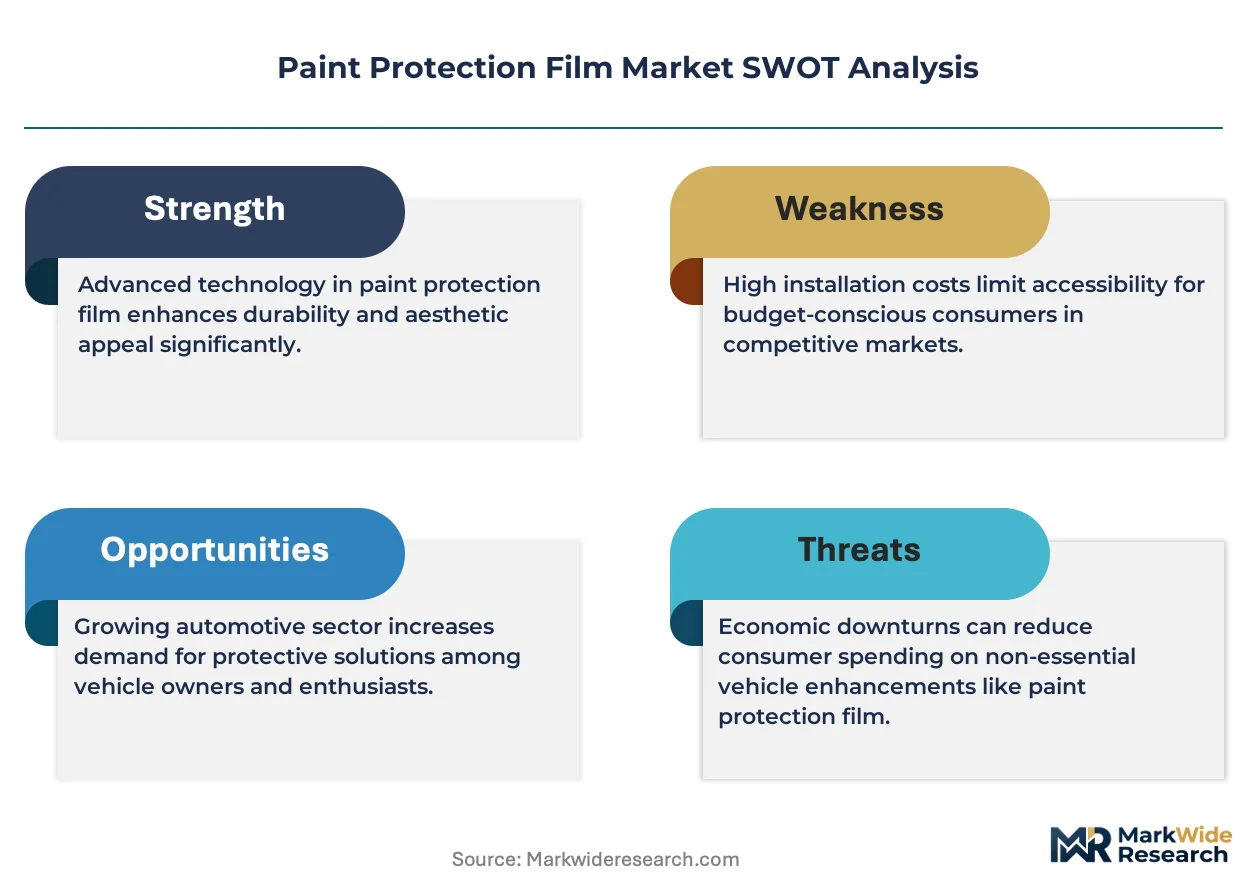
Aliphatic TPU resin supply concentration in Eastman Chemical Company and select Asian petrochemical conglomerates determines both pricing tier spreads and supply chain shape. This single-source dependency for premium-grade substrates forces independent film converters to accept pass-through cost volatility while ceding margin to integrated competitors with captive resin production.
Pricing Analysis
Certification level creates the primary spread between professional-grade and retail-accessible film tiers. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated self-healing films from uncertified clear bra alternatives. Cost compression in the DIY tier is intensifying because of pre-cut kit commoditization and marketplace platform price transparency. Fleet procurement managers in Texas and Florida demonstrate highest price sensitivity, while luxury automotive dealers accept premium positioning for warranty-backed installation.
Supply Chain Analysis
Contract manufacturing concentration rests with Eastman Chemical Company's captive TPU resin facilities and Saint-Gobain's multi-layer sputtering operations. Geographic supply concentration centers on United States, China, and Germany for resin synthesis and film lamination. Raw material dependencies draw from petroleum-derived polyols, isocyanate curing agents, and optical-grade release liners. Single-source vulnerability in aliphatic TPU grades exposes converters to allocation risk during petrochemical feedstock disruptions. Distribution runs through authorized dealer networks and regional wholesalers serving certified installer shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paint protection film is approaching a platform-economics inflection as digital pattern databases and VIN-linked cutting systems create interoperability standards between film suppliers and installer networks.
For Market Incumbents: Entrench installer network density through exclusive territory partnerships and embedded precision cutting equipment leasing. Lock in aliphatic TPU supply security via long-term offtake agreements or backward integration into resin synthesis. Counter emerging water-based adhesive specialists by accelerating EPA-compliant formulation qualification ahead of regulatory enforcement timelines.
For New Entrants and Emerging Players: Pursue mobile installation services for commercial fleet accounts in Texas and Florida where damage charge avoidance drives procurement. Target electronics surface protection applications in Asian manufacturing clusters where optical-grade clarity requirements reject standard automotive film grades. Establish direct procurement relationships with lease return operators unbundling paint protection from traditional body shop channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision coating equipment lessors and certified installer network platforms. Five-to-ten year viability hinges on regulatory compliance capabilities and digital workflow integration rather than commodity film production. Monitor EPA enforcement actions on solvent-based adhesive emissions as the primary inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Transition | EPA compliance trajectories favor early movers with qualified low-VOC lamination processes. |
| Dealer Network Certification Expansion | Franchised automotive retailers offer protected territory models and recurring fleet contracts. |
| Digital Pattern Database Integration | VIN-linked cutting systems virtualize template generation and compress installation job times. |
| Aliphatic TPU Supply Security | Captive resin production anchors margin control against petrochemical feedstock volatility. |
| Multi-Layer Sputtering Technology Transfer | Architectural glass coating expertise enables optical-grade PPF with enhanced clarity. |
Research Approach
Cross-validation between primary installer interviews and secondary trade data anchors the qualitative findings. Conversations with film manufacturer technical directors, automotive dealer service managers, fleet procurement officers, and precision coating equipment lessors informed supply chain and pricing dynamics. Secondary validation drew from EPA enforcement databases, CARB compliance filings, customs import records for TPU resin grades, and automotive OEM technical specification documents. Bottom-up segmentation modeling triangulated against top-down chemical industry capacity assessments.
Calibration against historical resin price indices and installation volume patterns shaped the projection framework. Modeled dimensions span product type, application vertical, installation channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Key inputs included aliphatic TPU supply forecasts and EPA compliance cost trajectories for adhesive formulation shifts.
Sensitivities concentrate around REACH isocyanate restriction enforcement and CARB VOC limit expansion to additional states. Forecasts reflect documented assumptions on regulatory timelines and installer certification pipeline development. Quarterly review of EPA enforcement actions and dealer network expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Interior Materials Market