
 Japan Automotive Actuators Market | 2026-2036
Japan Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Actuators Market Foresight
Tier-1 supplier procurement channels is reconfiguring around electrification-ready actuator portfolios. DENSO Corporation leverages its integrated powertrain electronics position to dominate electric actuator supply to Japanese OEMs. Mitsubishi Electric Corporation anchors high-precision motor actuator development for hybrid transmission systems. Continental AG competes through localized engineering centers in Yokohama and Nagoya.
Automotive actuators are electromechanical devices that convert electrical, hydraulic, or pneumatic energy into controlled mechanical motion, typically achieving positional accuracy within micrometer tolerances through brushless DC motors, ball screw mechanisms, or piezoelectric stacks. These components regulate throttle valves, brake calipers, suspension dampers, and steering rack engagement in passenger and commercial vehicles. Linear actuators lead volume demand for brake-by-wire and active grille shutter applications, while rotary actuators capture margin concentration in electric power steering modules. Electronic technology overlays now outpace mechanical actuator growth as software-defined vehicle architectures proliferate across Japanese platforms.
METI enforces fuel-economy benchmarks that compel OEMs to deploy intelligent actuators for thermal management and aerodynamic optimization. PMDA-aligned automotive safety validations and JIS standards govern electromagnetic compatibility and cycle durability for chassis-critical actuator installations. Stakeholders must weigh backward integration against specialist supplier partnerships as actuator software complexity escalates.
Market Dynamics
Electrification mandates from METI are forcing Japanese OEMs to replace hydraulic and pneumatic actuation with intelligent electromechanical systems across powertrain and thermal management functions.
Growth Catalysts
- JC08 Fuel-Efficiency Standards:Tightened benchmarks compel automakers to deploy active grille shutters and variable valve timing actuators that optimize aerodynamic drag and combustion efficiency.
- Hybrid Powertrain Proliferation:Dual-clutch transmission and e-axle architectures generate demand for high-torque rotary actuators in torque-vectoring differentials.
- Kanto Industrial Corridor Concentration:Proximity of Toyota City, Honda R&D centers, and Nissan Yokohama headquarters enables rapid prototype-to-production cycles for Tier-1 actuator suppliers.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium price volatility constrains brushless DC motor cost structures for precision positioning actuators.
- Single-Source Supply Risk:Specialty ball screw manufacturers in Aichi Prefecture create geographic concentration vulnerability for chassis-critical linear actuation.
- PMDA Validation Timelines:Extended electromagnetic compatibility certification cycles delay new actuator platform launches by twelve to eighteen months.
Strategic Opportunities
- Software-Defined Vehicle Architectures:Convergence of actuator control firmware with domain controllers enables over-the-air calibration updates and predictive maintenance revenue streams.
- Chūshū and Tōhoku Supplier Bases:Underdeveloped Tier-2 manufacturing clusters in western and northern Japan offer land and labor cost arbitrage for actuator assembly expansion.
- Carbon-Neutral Factory Incentives:METI's Green Transformation bonds subsidize capital expenditure for low-energy actuator test and validation facilities.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of firmware engineers with ISO 26262 functional safety expertise delays ASIL-D actuator development programs.
- Legacy CAN Bus Integration:New Ethernet-based actuator networks require gateway development to maintain backward compatibility with decade-old vehicle platforms still in production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Actuators Market |
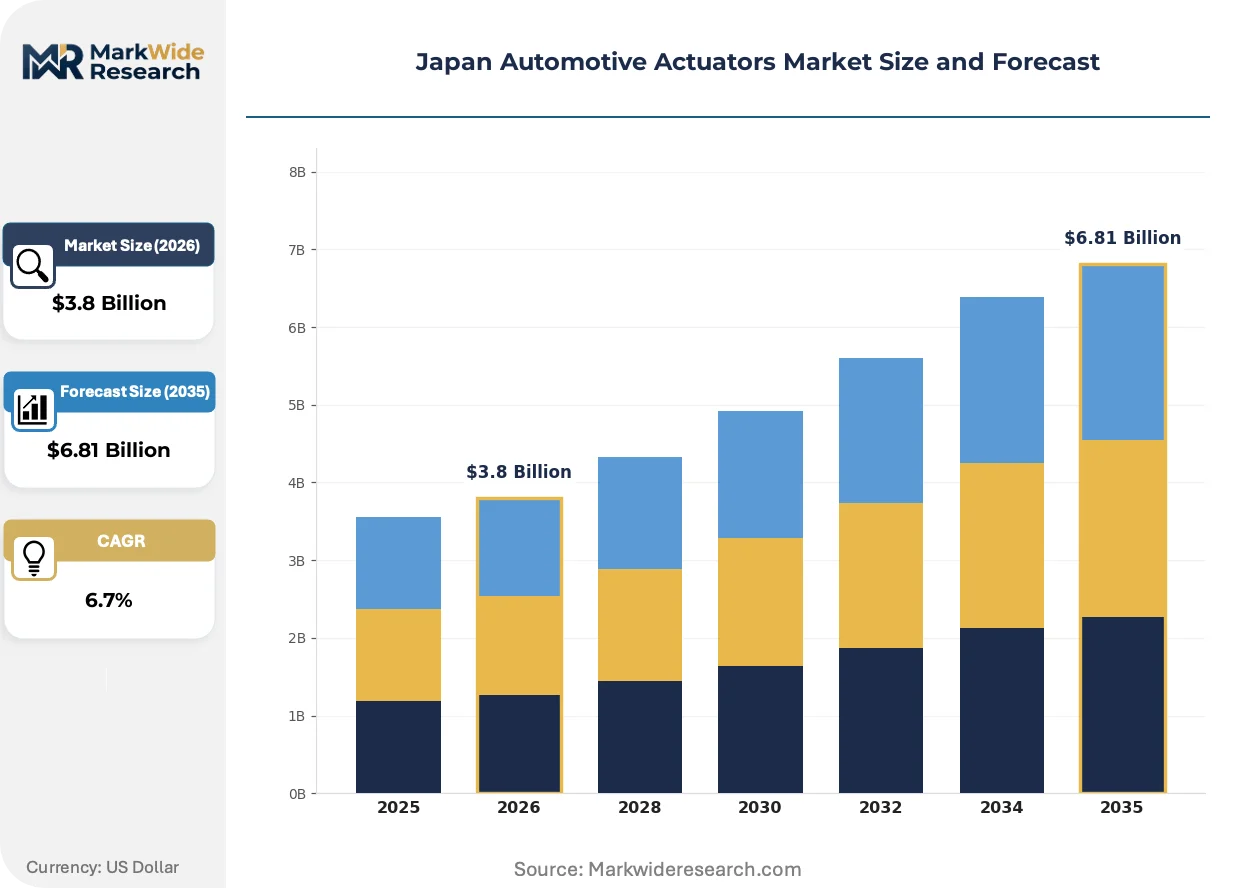
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Solenoid Actuators, Pneumatic Actuators Technology: Electric, Hydraulic, Mechanical, Electronic Application: Powertrain, Body Control, Active Suspension, Steering Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | DENSO Corporation, Mitsubishi Electric Corporation, Nidec Corporation, Hitachi Astemo Ltd., Aisin Seiki Co. Ltd., Panasonic Corporation, Continental AG, Robert Bosch GmbH, BorgWarner Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Actuators Market Shifts & Advancements
Actuator intelligence is migrating from standalone electromechanical components toward integrated mechatronic nodes with embedded sensing and edge computing capabilities.
Brushless DC motor technology is migrating from conventional Hall-effect commutation toward sensorless field-oriented control algorithms. Tier-1 suppliers in Kanagawa Prefecture are adopting these architectures for electric power steering modules. The shift is migrating from hardware-intensive designs toward software-defined torque ripple compensation that reduces BOM cost and assembly complexity.
METI's vehicle electrification roadmap mandates intelligent thermal management actuators for battery conditioning and cabin climate control. OEM procurement specifications now require LIN-bus communication and diagnostic feedback loops. Hybrid transmission suppliers face compressed development timelines to meet 2027 model-year compliance deadlines.
Buyer concentration among the three major Japanese OEMs has compressed actuator qualification cycles from thirty-six months to eighteen months. Tier-1 suppliers are responding with platformized actuator families that share firmware stacks across brake-by-wire and active suspension applications. This pattern is most visible in Aichi Prefecture, where Toyota's simultaneous engineering protocols dominate supplier R&D scheduling.
Japan Automotive Actuators Market Segmentation
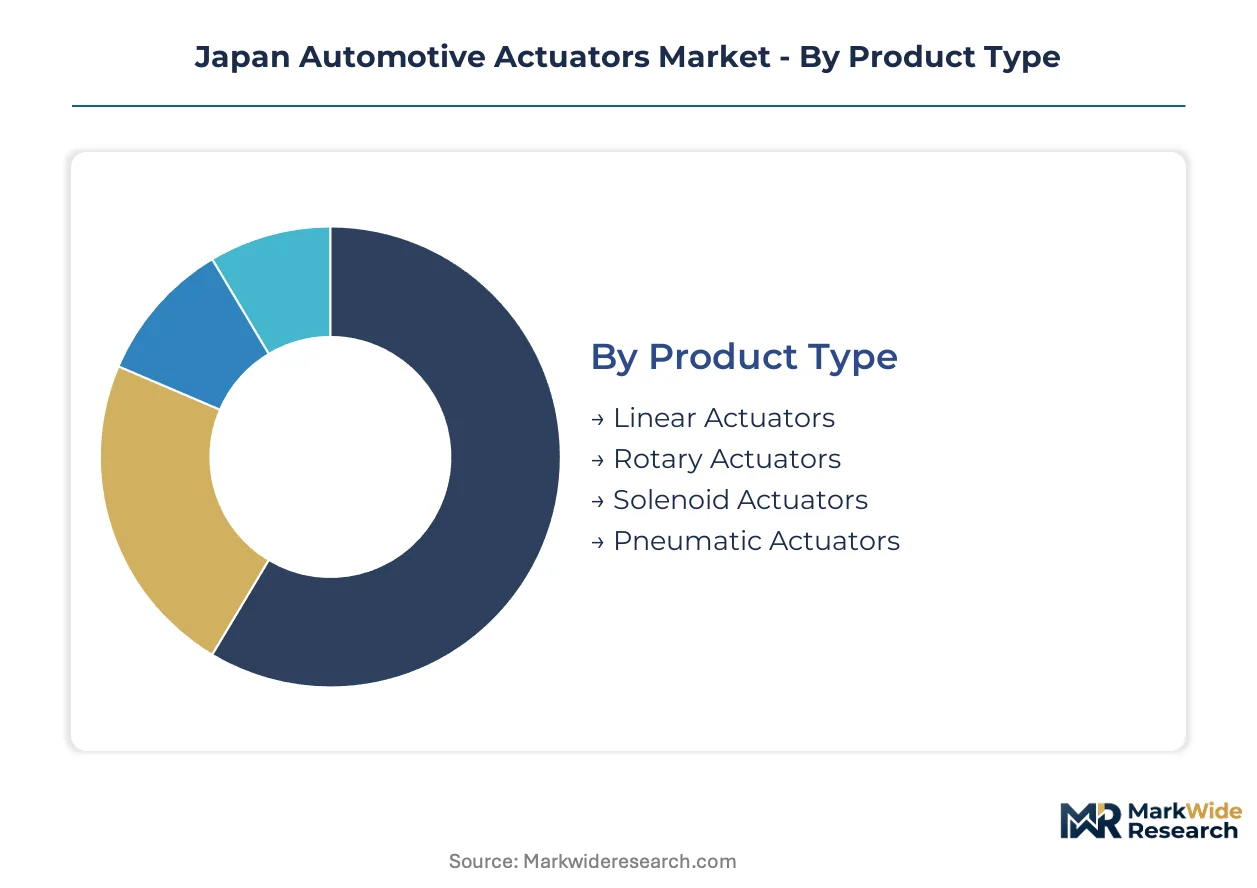
Japanese automakers segment actuator procurement by replacement velocity, with electrification-ready technologies cycling faster than legacy mechanical systems. Tier-1 suppliers in Aichi and Kanagawa Prefectures calibrate inventory and R&D pipelines around these differential turnover rates.
Product Type:
Linear actuators turn over fastest in brake-by-wire retrofits, while pneumatic systems linger longest in legacy commercial vehicle fleets. Rotary actuators occupy the middle ground with hybrid powertrain refresh cycles.
- Linear Actuators:Ball screw and belt-drive mechanisms convert rotational motor input into precise linear displacement for brake calipers and active grille shutters. Demand concentrates in Toyota City supplier parks, where JC08 aerodynamic mandates accelerate replacement of fixed grille assemblies with motorized shutter systems.
- Rotary Actuators:Brushless DC motor assemblies with harmonic drive gearing achieve angular positioning accuracy for electric power steering and torque-vectoring differentials. Kanagawa Prefecture engineering centers prioritize these for hybrid transmission integration as METI electrification timelines compress development windows.
- Solenoid Actuators:Electromagnetic plunger devices provide rapid on/off valve control for transmission fluid routing and engine stop-start systems.
- Pneumatic Actuators:Compressed air diaphragm systems persist in heavy-duty truck brake and suspension applications where electrification conversion costs remain prohibitive.
Linear actuators dominate installed base. Rotary actuators are where expansion concentrates.
Technology:
Cost tier stratification separates premium electric architectures from commodity mechanical alternatives, with hydraulic systems occupying a narrowing mid-market position.
- Electric:Sensorless field-oriented control algorithms drive brushless DC motors with software-defined torque ripple compensation. METI vehicle electrification roadmaps mandate these for all new powertrain and thermal management actuation.
- Electronic:Embedded microcontroller units with LIN-bus communication and diagnostic feedback loops enable over-the-air calibration updates. These are climbing the fastest in software-defined vehicle architectures proliferating across Japanese OEM platforms.
- Hydraulic:Pressurized fluid piston systems retain niche application in high-force chassis and construction equipment where electric motor power density remains insufficient.
- Mechanical:Cable, linkage, and spring-actuated devices face displacement as JIS standards tighten electromagnetic compatibility requirements for safety-critical installations.
Mechanical technology anchors legacy installed base. Electric architectures capture all incremental procurement.
Application:
Volume concentration tracks vehicle production schedules, with powertrain and body control commanding parallel procurement scale while active suspension remains a premium option penetration play.
- Powertrain:Variable valve timing actuators, dual-clutch transmission selectors, and e-axle disconnect clutches regulate engine breathing and torque delivery. Aichi Prefecture concentration of Toyota and Honda R&D centers drives specification harmonization across Tier-1 supplier development programs.
- Body Control:Door latch, seat adjustment, and sunroof actuators prioritize cost minimization through shared motor platforms across vehicle segments. These expand most quickly in minivan and kei-car segments where feature content differentiation intensifies.
- Active Suspension:Damper valve and anti-roll bar actuators deliver real-time ride height and stiffness modulation for luxury sedans and performance variants.
- Steering Control:Rack-assist and column-assist electric power steering modules replace hydraulic assist in all new vehicle platforms.
Powertrain applications dominate production volume. Body control modules are where specification proliferation concentrates.
End User:
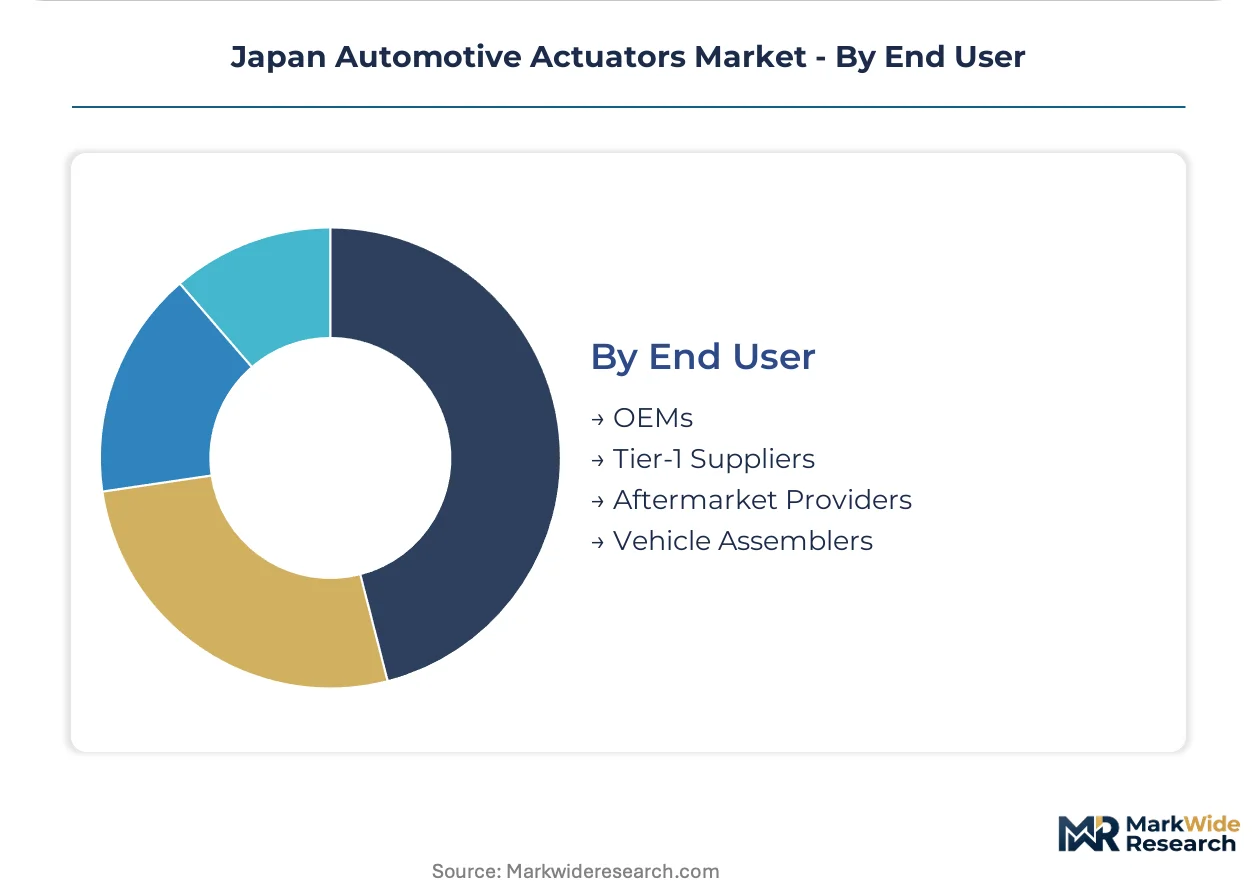
Customer type determines qualification burden and contract structure, with OEM direct procurement imposing the steepest certification requirements and aftermarket channels offering faster path to revenue.
- OEMs:Toyota, Honda, and Nissan maintain captive specification control over safety-critical actuator designs, requiring eighteen-month qualification cycles and ASIL-D functional safety validation.
- Tier-1 Suppliers:DENSO Corporation and Mitsubishi Electric Corporation consolidate procurement from Tier-2 component manufacturers for system-level integration.
- Vehicle Assemblers:Contract manufacturing partners in the Kanto industrial corridor execute final actuator calibration and installation sequences.
- Aftermarket Providers:Independent distributors serve collision repair and performance upgrade segments with reduced regulatory scrutiny.
OEM direct procurement dominates value capture. Tier-1 supplier channels are where consolidation pressure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's vehicle electrification roadmap anchors Japan's automotive actuator demand. Prefecture-level industrial clusters concentrate procurement power and accelerate prototype-to-production cycles for Tier-1 suppliers.
Kanto
Toyota City, Honda R&D centers, and Nissan Yokohama headquarters drive specification harmonization across brake-by-wire and active grille shutter applications. METI's JC08 fuel-efficiency standards compel automakers to deploy intelligent thermal management actuators. Tier-1 supplier parks in Aichi and Kanagawa Prefectures enable eighteen-month qualification cycles through simultaneous engineering protocols.
Kansai
Osaka-based electronics manufacturers supply embedded microcontroller units for LIN-bus actuator communication. The region's precision machining heritage supports ball screw mechanism production for linear displacement systems. Local engineering centers focus on software-defined torque ripple compensation algorithms for electric power steering modules.
Chubu
Nagoya anchors hybrid transmission actuator development with concentrated torque-vectoring differential procurement. The region's machine tool industry provides harmonic drive gearing for rotary positioning accuracy. METI Green Transformation bonds subsidize capital expenditure for low-energy actuator test facilities in surrounding industrial zones.
Kyushu
Underdeveloped Tier-2 manufacturing clusters offer land and labor cost arbitrage for actuator assembly expansion. The region's semiconductor packaging expertise transfers to sensorless field-oriented control chip integration. Local governments compete for automotive supplier relocation through tax incentive programs.
Tohoku
Northern Japan's rare earth magnet processing capabilities address neodymium supply constraints for brushless DC motors. The region's materials science institutes collaborate on dysprosium-reduction research for precision positioning actuators. Cold-climate testing infrastructure supports validation of battery conditioning actuators for extreme temperature operation.
Japan Automotive Actuators Market Competitive Landscape
Integrated powertrain electronics specialists and precision motor developers split the market through divergent capability investments. Supplier consolidation concentrates procurement leverage among three major Japanese OEMs. Two strategic archetypes dominate: captive Tier-1 system integrators with firmware control, and component specialists with manufacturing scale. Competitive moves center on platformized actuator families and backward integration into rare earth magnet supply.
Among Japan-based integrated suppliers, DENSO Corporation and Mitsubishi Electric Corporation occupy positions that exemplify the system-integrator archetype. Continental AG represents the localized engineering-center approach among international competitors establishing Yokohama and Nagoya presence. These three anchors demonstrate how procurement relationships reconfigure around electrification-ready actuator portfolios.
| Leading Market Players |
|---|
| DENSO Corporation |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Hitachi Astemo Ltd. |
| Aisin Seiki Co. Ltd. |
| Panasonic Corporation |
| Continental AG |
| Robert Bosch GmbH |
| BorgWarner Inc |
| Others |
Supply & Pricing Matrix
Rare earth magnet processing in Tohoku and northern Japan concentrates upstream margin capture for brushless DC motor actuators, while Tier-1 suppliers in Aichi and Kanagawa Prefectures extract value through firmware integration and ASIL-D certification control. This geographic split between raw material leverage and system-level specification power defines how pricing pressure and procurement risk distribute across the value chain.
Pricing Analysis
Price spreads between Kanto-based Tier-1 suppliers and Kyushu assembly operations reach three-to-one multiples for identical actuator specifications. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade, volume commitment scale, and backward integration depth into magnet supply. Cost compression in economy-tier brake-by-wire actuators is intensifying because Chinese motor suppliers are qualifying for JIS electromagnetic compatibility standards. Fleet procurement managers at commercial vehicle assemblers exhibit highest price sensitivity, while Toyota and Honda platform engineers prioritize performance consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk planning for ball screw mechanisms and sensorless field-oriented control chipsets. Manufacturing concentrates in Japan, China, and South Korea, with Aichi Prefecture housing specialty ball screw manufacturers and Kanagawa Prefecture anchoring embedded microcontroller integration. Neodymium magnet supply, harmonic drive gearing, and LIN-bus communication modules constitute critical input dependencies. Single-source vulnerability persists for precision ball screw production in Aichi Prefecture. Distribution runs through captive Tier-1 channels to OEM direct procurement, with aftermarket channels serving collision repair segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan Automotive Actuators Market functions as a regulatory-moat market where METI electrification mandates and PMDA validation timelines create switching costs that entrench incumbent Tier-1 suppliers. This structural entrenchment rewards early certification investment and punishes late entrants facing eighteen-month qualification cycles.
For Market Incumbents: Harden firmware control positions through sensorless field-oriented control algorithm patenting and ASIL-D toolchain standardization across platformized actuator families. Expand captive magnet supply through minority stakes in Tohoku rare earth processors to offset neodymium price volatility. Electromagnetic compatibility certification bottlenecks represent the primary threat to margin compression. For New Entrants and Emerging Players: Chūshū and Tohoku Tier-2 manufacturing clusters represent the most penetrable entry point for actuator assembly operations seeking land and labor cost arbitrage against Kanto concentration. Aftermarket collision repair channels offer faster revenue validation with reduced PMDA scrutiny. A go-to-market angle targeting independent distributors with LIN-bus retrofit kits for legacy vehicle platforms bypasses OEM direct procurement barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision machining specialists in Aichi Prefecture holding ball screw manufacturing capabilities. Five-to-ten year viability hinges on electrification-ready portfolio migration and software-defined vehicle architecture alignment. The signal to watch is Tier-1 supplier RFP specifications demanding over-the-air calibration capability as table-stake qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Toyota simultaneous engineering protocols compress supplier R&D scheduling across brake-by-wire and active suspension applications. |
| Battery Supply Agreement | Long-term offtake contracts with Tohoku rare earth processors secure neodymium magnet supply for brushless DC motor production. |
| Software-Defined Vehicle Investment | Embedded LIN-bus diagnostic feedback loops enable predictive maintenance revenue streams for Tier-1 suppliers. |
| Geographic Manufacturing Footprint | Chūshū assembly expansion captures METI Green Transformation bond subsidies for low-energy test facilities. |
| Charging Infrastructure Partnership | Thermal management actuator integration with battery conditioning systems addresses JC08 fuel-efficiency mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI policy filings, JIS standards documentation, vehicle production databases, and Tier-1 supplier procurement disclosures. Primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution managers, and rare earth processing specialists informed demand-side and supply-side validation. Bottom-up actuator shipment estimates triangulate against top-down vehicle production forecasts across the analysis window.
Forecast inputs include propulsion architecture migration rates, content per vehicle trajectories for electrified powertrains, and OEM tier procurement concentration. Segmentation modeling spans product type, technology tier, application function, and end-user channel. CAGRs derive from regression analysis of historical replacement cycles overlaid with METI electrification timeline compliance deadlines. JC08 fuel-efficiency standard stringency and PMDA validation cycle duration constitute industry-specific forecast modifiers.
Practitioners should monitor rare earth magnet price volatility, Tier-2 supplier geographic diversification announcements, and Ethernet-based actuator network adoption rates for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Subframe Market
Automotive Components
Automotive Bearing Market
Automotive Components
US Automotive Composites Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Commutator Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Automotive Glass Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Automotive Metal Timing Chain Market