
 Global Automotive Intelligent Dashboard System Market | 2026-2036
Global Automotive Intelligent Dashboard System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Intelligent Dashboard System Market Intelligence
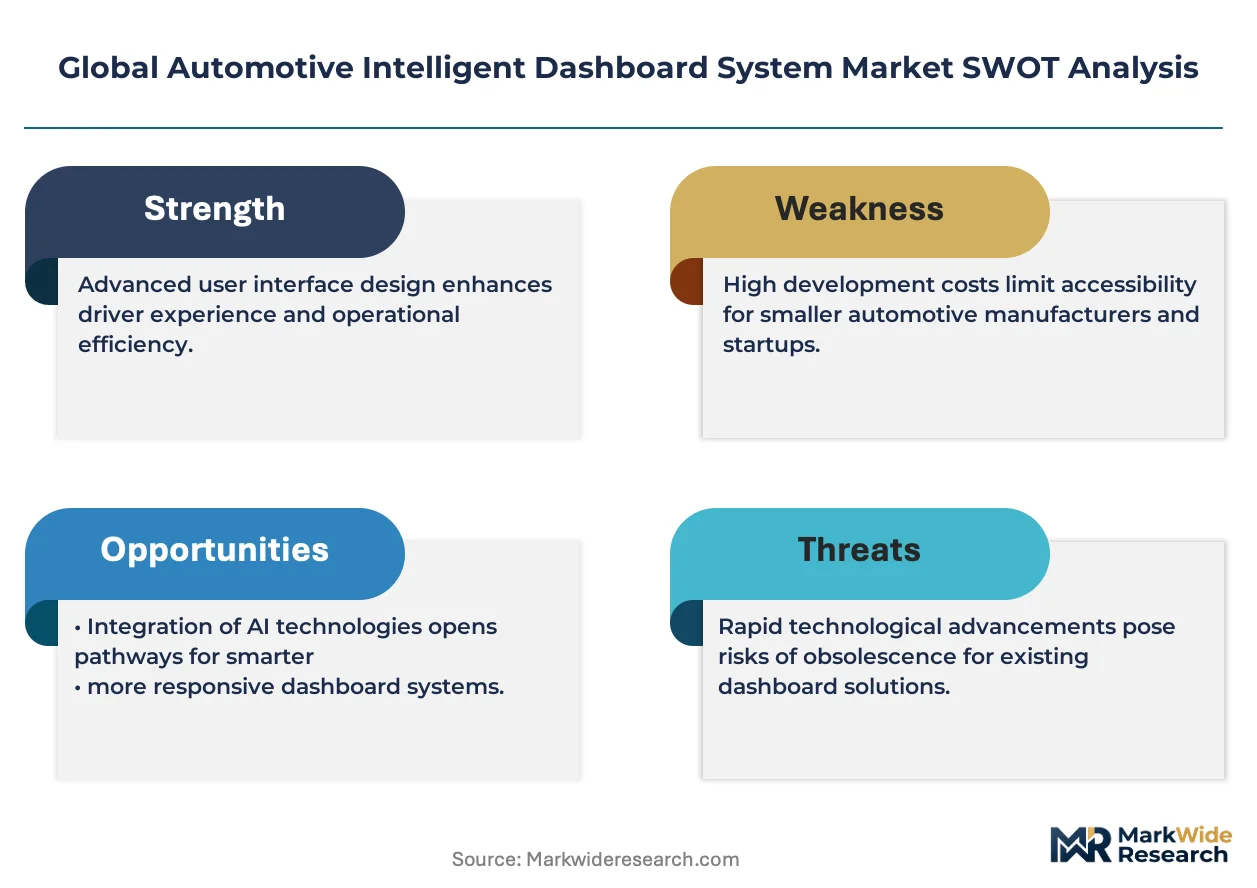
The substitution of traditional LCDs with advanced AMOLED and OLED displays is rebalancing the cost structure and performance standards for automotive dashboards. This shift benefits specialized suppliers like Visteon Corporation, which focuses on digital cluster and infotainment integration. Continental AG leverages its extensive display technology portfolio for premium vehicle segments, while Robert Bosch GmbH offers a complete suite of connected cockpit electronics.
An automotive intelligent dashboard system is an integrated digital interface that consolidates vehicle data, navigation, and infotainment onto one or more displays. These systems feature high-resolution screens and rely on powerful system-on-chip (SoC) processors to render complex graphics. Head-Up Display (HUD) units, especially those with augmented reality, represent a high-growth product type. Voice recognition and gesture control technologies are now moving beyond luxury vehicles into mass-market models.
Regulatory frameworks from the US NHTSA guide human-machine interface design to minimize driver distraction. Concurrently, compliance with the EU's General Safety Regulation and China's GB standards for data security shapes system architecture. Component suppliers must therefore decide whether to develop universal platforms or region-specific solutions to navigate these divergent regulatory requirements.
Market Dynamics
The evolution of the automotive cockpit is driven by a regulatory and consumer push for more integrated, secure, and feature-rich digital interfaces. This shift compels a fundamental re-architecture of in-vehicle electronics, moving away from siloed components toward a centralized, software-defined domain controller.
Growth Catalysts
- Cybersecurity Mandates:Regulations like the UNECE WP.29 framework require robust cybersecurity measures for vehicle electronics, compelling the adoption of sophisticated, secure intelligent dashboard systems in all new vehicle type approvals.
- Consumer Electronics Integration:Strong consumer demand, particularly within China's new energy vehicle market, for a seamless user experience that mirrors smartphones is accelerating the integration of advanced displays and connectivity features.
- SoC Performance Gains:The availability of powerful, automotive-grade System-on-Chip (SoC) processors enables the rendering of complex 3D graphics, multi-display management, and AI-driven features like voice assistance, which are key system enablers.
Market Restraints
- High Development Costs:The significant investment required for developing and validating systems to meet stringent automotive functional safety standards, such as ISO 26262, creates a high barrier to entry for new suppliers.
- Semiconductor Supply Volatility:A heavy reliance on a concentrated global supply chain for high-performance microprocessors and display drivers exposes dashboard system manufacturers to price fluctuations and potential production disruptions.
- Component Obsolescence:The mismatch between long automotive development and production lifecycles and the rapid obsolescence of consumer-grade electronic components complicates long-term serviceability and system support.
Strategic Opportunities
- Sensor Fusion for HMI:Integrating data from driver monitoring systems with augmented reality head-up displays offers a path to create more intuitive, context-aware interfaces that enhance driver safety and reduce cognitive load.
- Commercial Vehicle Telematics:There is a significant opportunity to adapt intelligent dashboard platforms for the commercial vehicle segment, focusing on fleet management, logistics integration, and driver performance monitoring.
- Aftermarket Upgrades:Developing modular, upgradable dashboard systems for the aftermarket could cater to owners of older vehicles seeking modern infotainment and connectivity features without purchasing a new car.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of software engineers skilled in both automotive-grade platforms and modern UX/UI development hinders the pace of innovation and increases development costs for system suppliers.
- Over-the-Air Update Security:Ensuring the security and reliability of over-the-air (OTA) software updates for critical dashboard functions presents a major technical and operational challenge, with significant safety implications.
- Data Standardization Gaps:The lack of a universal protocol for data communication between the dashboard and other vehicle electronic control units (ECUs) from various suppliers complicates system integration and increases software complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Intelligent Dashboard System Market |
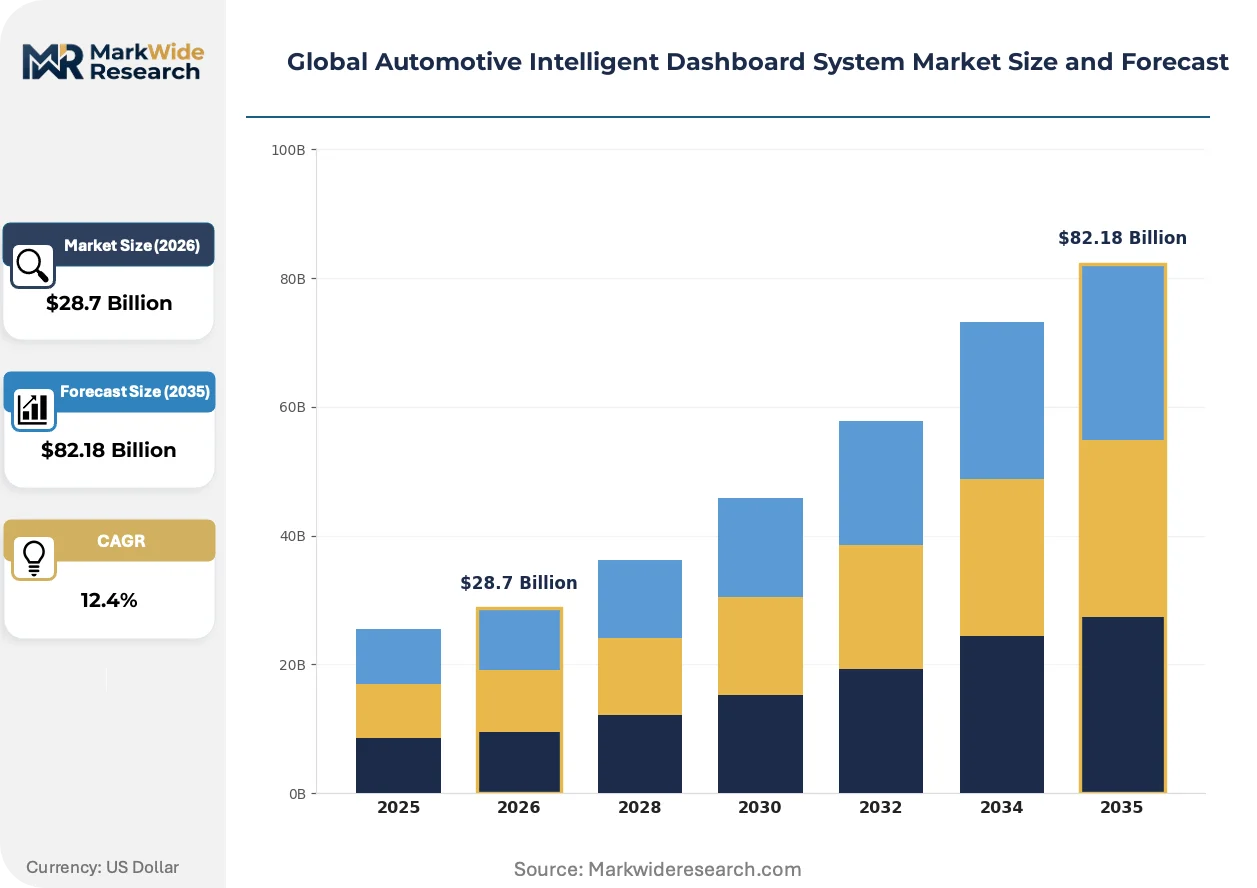
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $82.18 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrument Cluster, Head-Up Display, Central Console, Digital Infotainment Technology: Augmented Reality, Touchscreen, Voice Recognition, Gesture Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Feature: Navigation, Connectivity, Entertainment, Safety Alerts |
| Companies Covered | Denso Corporation, Continental AG, Visteon Corporation, Robert Bosch GmbH, Panasonic Automotive Systems, Aptiv PLC, Harman International, Valeo SA, Hyundai Mobis Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Intelligent Dashboard System Market Strategic Shifts & Innovations
The in-vehicle experience is being redefined by the transition toward a software-defined cockpit, where functionality and user experience are determined by updatable software rather than fixed hardware. This transformation places the digital dashboard at the center of the vehicle's electronic architecture and brand identity.
Augmented reality head-up display (AR-HUD) technology projects dynamic navigational and safety alerts directly into the driver's field of view. Premium and mainstream automakers are rapidly incorporating AR-HUDs, especially in new electric vehicle platforms, to enhance driver awareness. This technology is converging with vehicle sensor data and cloud-based services to create an immersive and intuitive guidance layer that merges the digital and physical worlds.
New guidance from the US National Highway Traffic Safety Administration (NHTSA) on HMI design is influencing interface development to reduce driver distraction. The rules pressure designers to favor simplified menus, voice commands, and tactile controls over complex touchscreen interactions. This regulatory focus most directly affects infotainment software developers, who must now balance feature-richness with stringent safety and usability standards across all vehicle segments.
A notable shift in consumer expectations is the demand for dashboard systems with software and features that can be upgraded throughout the vehicle's life. This model challenges the static, factory-set feature list, pushing automakers to explore features-on-demand and subscription services delivered via OTA updates. This trend is most advanced in the North American and Chinese EV markets, where technology-forward buyers value continuous improvement and personalization.
Global Automotive Intelligent Dashboard System Market Segmentation
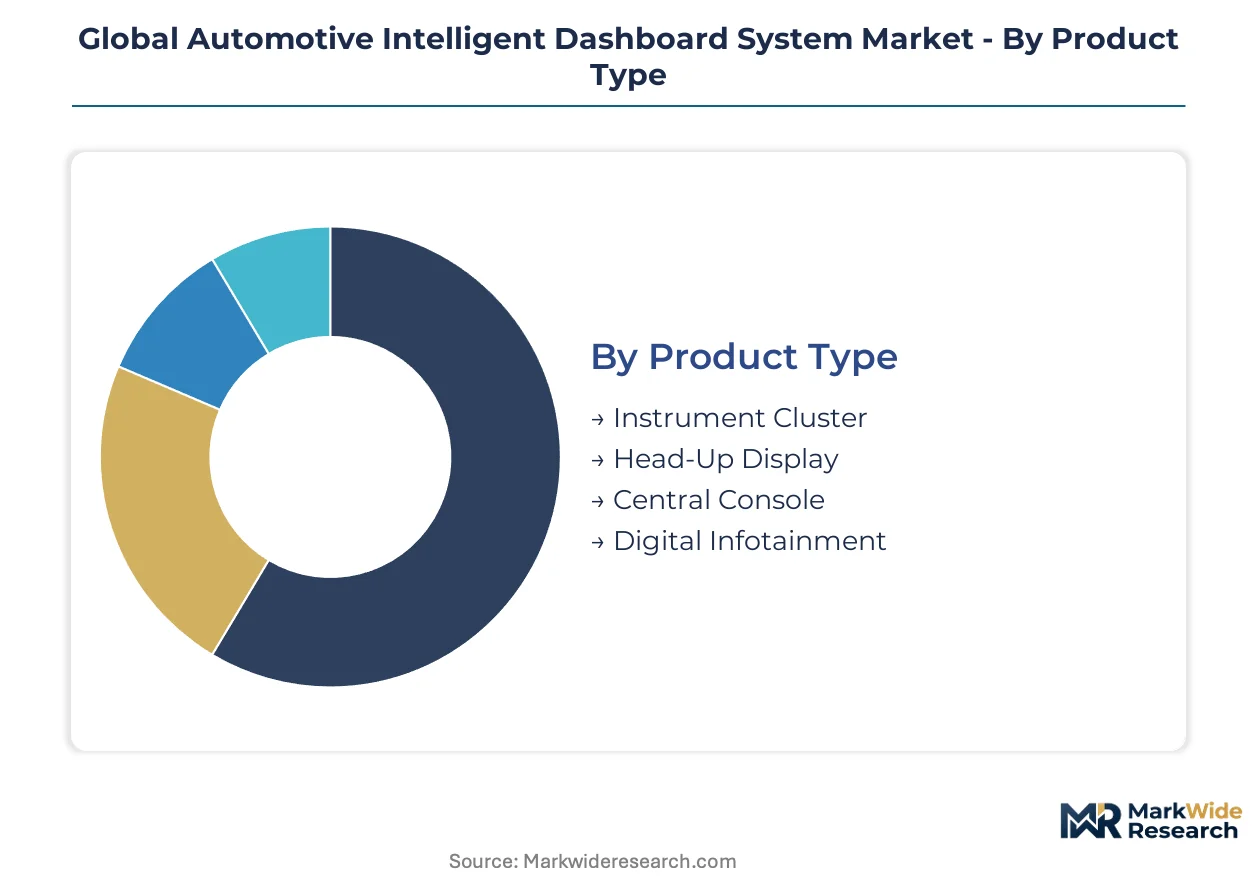
Understanding the Global Automotive Intelligent Dashboard System Market requires a granular breakdown of its constituent parts, reflecting diverse technological applications and end-user demands. This segmentation provides clarity on where innovation is concentrated and how different product types contribute to overall market value. Analyzing these segments helps pinpoint specific growth vectors and competitive battlegrounds.
Product Type:
Vehicle manufacturers prioritize specific product types based on integration complexity and perceived driver value.
- Head-Up Display:Projects critical driving information directly onto the windshield, often incorporating augmented reality elements for enhanced navigation and safety. Demand accelerates in new electric vehicle platforms, driven by a consumer push for advanced driver assistance features.
- Digital Infotainment:Consolidates multimedia, connectivity, and vehicle settings onto high-resolution screens, often leveraging powerful System-on-Chip processors. This segment sees significant demand in China, fueled by extensive consumer electronics integration in new energy vehicles.
- Instrument Cluster:Replaces traditional analog gauges with customizable digital displays, presenting speed, RPM, and essential vehicle status information. This foundational component is undergoing a transition from basic LCDs to advanced AMOLED and OLED technologies.
- Central Console:Serves as the primary interface for climate control, infotainment, and vehicle functions, typically featuring large touchscreens and haptic feedback. Its evolution is driven by the desire for a centralized, user-friendly control hub in modern cockpits.
Volume sits with Digital Infotainment; growth tilts toward Head-Up Display.
Technology:
The choice of technology directly impacts the user interaction model and feature set within modern vehicle cockpits.
- Augmented Reality:Overlays digital information onto the real-world view, particularly via head-up displays, to provide intuitive navigation cues and hazard warnings. This technology is gaining traction in premium vehicle segments, enhancing driver awareness and reducing cognitive load.
- Voice Recognition:Enables hands-free control of infotainment, navigation, and vehicle settings through natural language processing, minimizing driver distraction. Its integration is expanding beyond luxury models into mass-market vehicles due to regulatory guidance from bodies like the US NHTSA.
- Touchscreen:Provides a direct, tactile interface for controlling various vehicle functions, navigation, and entertainment systems. High-resolution touchscreen displays are becoming standard across all vehicle segments.
- Gesture Control:Allows drivers to interact with the dashboard system using specific hand movements, offering an alternative to touch and voice inputs. This technology is moving from niche luxury applications into broader vehicle adoption.
Innovation in Touchscreen interfaces is now standard, while Augmented Reality represents emerging capabilities for immersive experiences.
End User:
Different customer types drive distinct requirements for dashboard system features, integration, and lifecycle support.
- OEMs:Original Equipment Manufacturers integrate intelligent dashboard systems directly into new vehicle designs during the production phase, demanding compliance with stringent safety and cybersecurity regulations like UNECE WP.29. This segment represents the largest volume market for advanced system suppliers.
- Aftermarket Providers:Offer upgrade solutions and replacement systems for existing vehicles, catering to owners seeking modern infotainment and connectivity features. This segment provides opportunities for modular, upgradable dashboard systems that extend vehicle functionality.
- Tier-1 Suppliers:Develop and supply complete intelligent dashboard modules and components to OEMs, acting as crucial intermediaries in the automotive supply chain. Companies like Visteon Corporation and Continental AG operate heavily in this segment.
- Fleet Operators:Utilize intelligent dashboard systems for commercial vehicles, focusing on telematics, logistics integration, and driver performance monitoring. This segment prioritizes robust, scalable solutions for fleet management.
Market dynamics are shaped by the integration demands of OEMs and the retrofit potential in Aftermarket Providers.
Feature:
The functional capabilities integrated into intelligent dashboards directly address specific driver needs and regulatory compliance.
- Navigation:Provides turn-by-turn directions, real-time traffic updates, and point-of-interest information, often integrated with head-up displays for enhanced guidance. This core feature is essential for driver convenience and efficiency across all vehicle segments.
- Safety Alerts:Delivers critical warnings such as lane departure, collision proximity, and driver fatigue, often leveraging sensor fusion from advanced driver-assistance systems. These alerts are crucial for meeting regulatory safety standards and enhancing overall vehicle security.
- Connectivity:Enables seamless integration with smartphones, cloud services, and vehicle-to-everything (V2X) communication for enhanced user experience and data exchange. This feature supports over-the-air updates and subscription services.
- Entertainment:Offers multimedia playback, streaming services, and app integration to enhance the passenger experience during journeys. This functionality is a major draw for consumers, particularly in new energy vehicles.
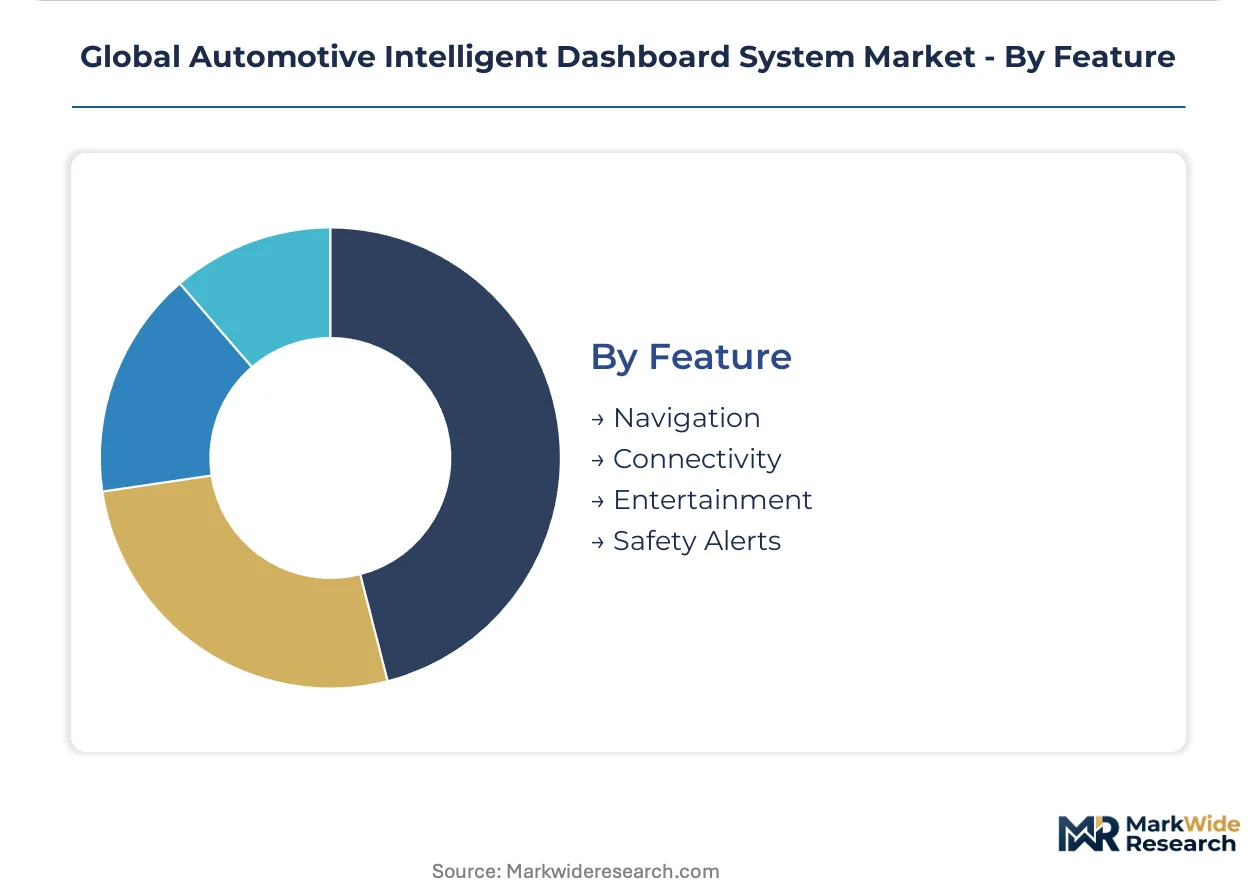
While Navigation remains a core offering, Safety Alerts are increasingly critical for advanced driver assistance systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive new energy vehicle production, particularly within its free trade zones, drives significant demand for intelligent dashboard systems. These zones facilitate manufacturing and export, attracting major automotive and electronics suppliers. This concentration supports rapid innovation and market expansion across Asia.
China
China's expansive new energy vehicle production fuels substantial demand for advanced intelligent dashboard systems. Compliance with China's GB standards for data security shapes system architecture for domestic and international suppliers. The Yangtze River Delta region, including Shanghai, acts as a hub for smart cockpit development and innovation.
United States
United States consumers drive demand for sophisticated intelligent dashboard features and advanced driver assistance systems. US NHTSA guidelines influence human-machine interface design to minimize driver distraction across all vehicle segments. Silicon Valley and Detroit's automotive corridor foster collaboration between tech companies and traditional automakers.
Germany
German premium vehicle manufacturers integrate advanced intelligent dashboard systems, prioritizing performance and driver safety. The EU's General Safety Regulation and UNECE WP.29 framework compel robust cybersecurity measures for new vehicle type approvals. Bavaria, with its strong automotive industry, serves as a center for digital cockpit engineering and integration.
Japan
Japanese consumers expect high-quality and reliable intelligent dashboard systems with advanced connectivity features. JIS standards ensure the precision and reliability required for automotive electronics and digital interfaces. The Kanto region, particularly around Tokyo, leads in R&D for AR-HUD technologies and sophisticated voice control systems.
South Korea
South Korea's rapid electric vehicle adoption and robust electronics industry accelerate intelligent dashboard system deployment. Domestic regulations align with international cybersecurity frameworks for in-vehicle digital interfaces. The Seoul Capital Area drives innovation in advanced display technologies and high-performance automotive-grade System-on-Chip processors.
Global Automotive Intelligent Dashboard System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the global automotive intelligent dashboard system market. The market exhibits a tiered structure, with established Tier-1 suppliers dominating OEM integration and niche players focusing on specific technologies. Strategic archetypes include comprehensive system integrators, display technology specialists, and software-centric solution providers. Companies pursue portfolio diversification and strategic partnerships to address evolving regulatory demands and technological shifts.
Specialists in integrated digital cockpits, Visteon Corporation exemplifies a dedicated focus on digital cluster and infotainment integration for OEMs, often positioning itself as a technology-forward partner. Continental AG, a German-based AG, represents a comprehensive Tier-1 supplier leveraging its extensive display technology portfolio and system integration capabilities for premium vehicle segments. Robert Bosch GmbH, another prominent German AG, anchors the market with a complete suite of connected cockpit electronics, often serving as a critical component and software supplier across various vehicle platforms and segments.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Visteon Corporation |
| Robert Bosch GmbH |
| Panasonic Automotive Systems |
| Aptiv PLC |
| Harman International |
| Valeo SA |
| Hyundai Mobis Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Specialized software engineering talent concentrated in key innovation hubs like Silicon Valley and Bavaria drives labor-cost differentials. These cost variations directly influence the pricing tiers for advanced intelligent dashboard systems across global markets.
Pricing Analysis
Volume-driven segments like instrument clusters exhibit tighter margins compared to high-growth, feature-rich head-up displays. The dominant pricing model involves a three-tier structure across premium, standard, and economy levels, differentiating by display technology and software complexity. Price differentiation stems from functional safety certification and extensive customization for specific OEM platforms. Pricing pressure intensifies due to the significant investment in R&D and volatile semiconductor costs. Aftermarket providers are highly price-sensitive, seeking cost-effective modular upgrades.
Supply Chain Analysis
Reverse-logistics for intelligent dashboard systems primarily involves component refurbishment and software updates, driven by component obsolescence and long automotive lifecycles. Supply concentrates heavily in China, South Korea, and Germany, reflecting advanced manufacturing capabilities. The industry relies on high-performance microprocessors and advanced display drivers as critical inputs. Semiconductor supply volatility presents a significant structural risk across the component ecosystem. Distribution runs predominantly through Tier-1 suppliers directly to Original Equipment Manufacturers for vehicle integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive intelligent dashboard system market is currently supply-constrained, primarily due to a persistent scarcity of specialized software engineers. This talent bottleneck props up development costs and influences system pricing across all segments.
For Market Incumbents: Hedge against component obsolescence by investing in modular system architectures and long-term supply agreements for critical microprocessors. Diversify portfolio offerings to include both premium AR-HUD solutions and cost-effective digital infotainment systems for mass markets. Strategic partnerships with software specialists can address the talent scarcity and accelerate UX/UI innovation. Prioritizing ISO 26262 certification strengthens market position against emerging entrants.
For New Entrants and Emerging Players: Begin with developing modular, upgradable dashboard systems specifically for the aftermarket, targeting owners of older vehicles seeking modern connectivity. Focus on the commercial vehicle segment, offering telematics and logistics integration capabilities as a white-space opportunity. The China NEV market provides a penetrable segment for advanced consumer electronics integration. A subscription-based model for features-on-demand can create recurring revenue streams.
For Investors and Strategic Acquirers: Re-rating potential sits with software-centric solution providers given the industry's shift towards software-defined cockpits and features-on-demand. The long-term viability of intelligent dashboard systems remains strong over the next decade, driven by regulatory mandates and consumer demand for integrated experiences. Acquisition targets should include specialized firms in AR-HUD technology or automotive cybersecurity. Increased OEM investment in over-the-air update infrastructure represents a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates time-to-market for new vehicle models. |
| Cybersecurity R&D Investment | Ensures compliance with UNECE WP.29 regulations and protects sensitive vehicle data. |
| AR-HUD Technology Integration | Enhances driver safety and awareness through immersive navigational aids. |
| Talent Development Programs | Addresses the scarcity of skilled software engineers for advanced UX/UI development. |
| Features-on-Demand Monetization | Creates new recurring revenue streams through software upgrades and subscription services. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews with industry stakeholders. We engaged OEM platform engineers, Tier-1 procurement leads, automotive UX/UI developers, and regulatory compliance officers. This approach combined insights from vehicle production databases and national safety administration guidelines, ensuring comprehensive data triangulation. Both bottom-up and top-down methodologies validated market sizing and growth projections.
Market sizing was modeled at a granular level across product type, technology, end-user, and feature dimensions. The analytical framework considered vehicle class and propulsion architecture, particularly new energy vehicle platforms, throughout the forecast period. Compound annual growth rates were derived through a blend of historical trend analysis and expert consensus. Key inputs included new vehicle type approvals and consumer electronics adoption rates in emerging markets.
Underlying measurement precision varies by segment; OEM integration and head-up display segments carry tighter precision than others. Forecasts reflect assumptions regarding geopolitical trade tensions and rapid display technology shifts. Material deviation in semiconductor supply stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Soc Market