
 Global Automotive Power Distribution Modules Market | 2026-2036
Global Automotive Power Distribution Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Power Distribution Modules Market Analysis
Customer concentration among tier-1 suppliers is restructuring procurement leverage across the automotive power distribution modules supply base. Eaton leverages its circuit protection heritage to anchor high-voltage contracts with electrification-focused OEMs. Bosch competes through in-house semiconductor integration that sustains margin control across smart module portfolios.
Automotive power distribution modules are electromechanical assemblies that route, protect, and manage electrical power from source to load through fused circuits, relay-controlled paths, and solid-state switching elements rated for 12V to 800V architectures. Their primary purpose is ensuring fault-isolated power delivery to safety-critical vehicle systems while minimizing harness mass and assembly complexity. Fuse boxes and battery distribution units dominate installed value in internal combustion and mild-hybrid platforms where conventional overcurrent protection remains cost-optimized. Smart modules and integrated systems command expanding share as 48V and high-voltage electric architectures require real-time diagnostics, predictive fault detection, and software-configurable load management.
FDA vehicle electronics standards, EPA emissions compliance timelines, and EU Green Deal carbon-neutrality frameworks collectively elevate electrical architecture reliability requirements and accelerate module replacement cycles. ECE R10 electromagnetic compatibility regulations and China's GB/T standards for new energy vehicles further fragment certification pathways across export destinations. Stakeholders must monitor which regulatory convergence patterns emerge between NHTSA functional safety expectations and European automated driving electrical redundancy rules.
Market Dynamics
High-voltage electrification architectures are forcing a wholesale redesign of power distribution topologies, compressing development cycles and rewiring supplier-OEM relationships across the automotive value chain.
Growth Catalysts
- EU Green Deal carbon-neutrality mandates:The framework's 2035 combustion phase-out deadline accelerates procurement of 800V battery distribution units by German and French OEMs.
- Silicon carbide semiconductor adoption:Wide-bandgap materials enable compact smart modules with faster switching speeds and reduced thermal losses in electric drivetrains.
- China's NEV production scaling:GB/T standard compliance requirements for new energy vehicles concentrate demand in domestic battery-electric platforms.
Market Restraints
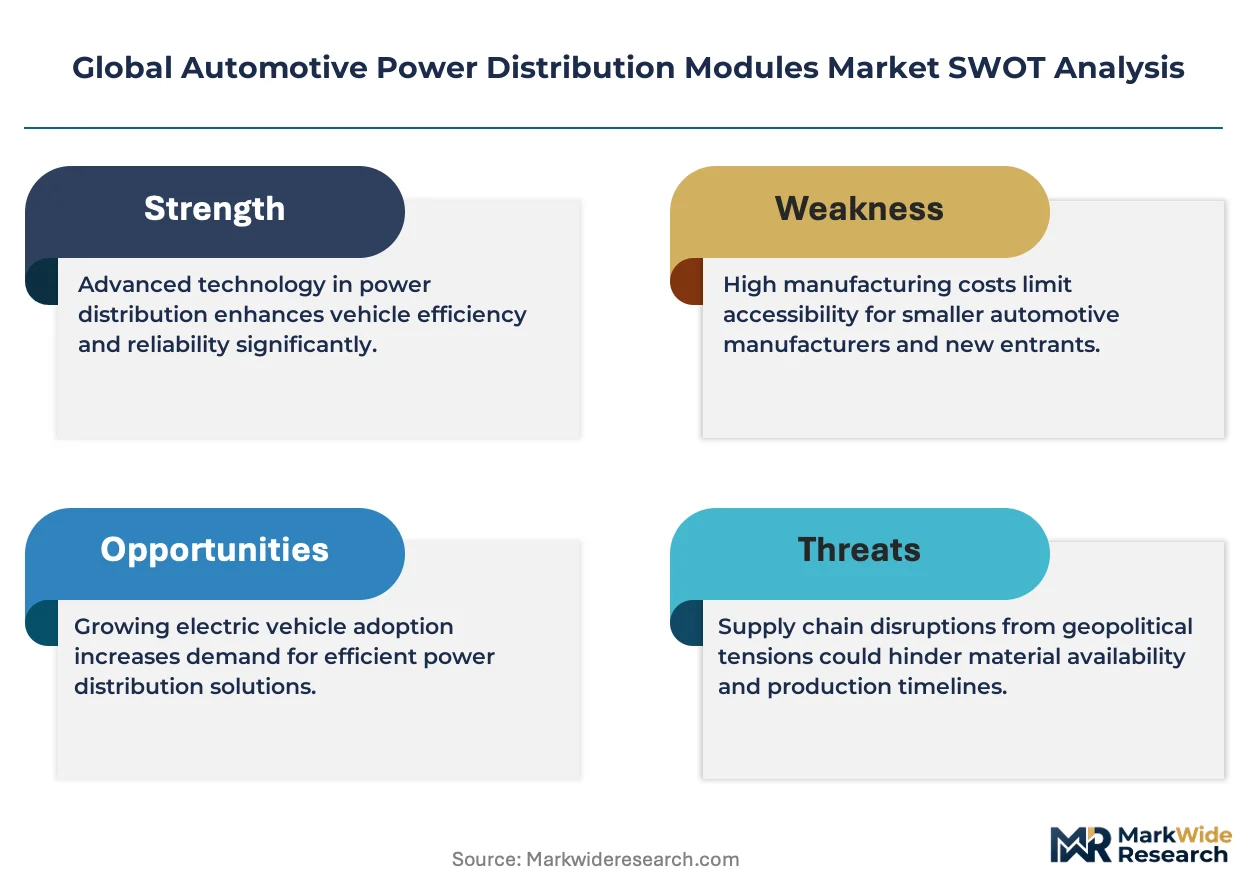
- Copper and semiconductor input volatility:Raw material cost swings compress module margins and complicate long-term contract pricing with tier-1 suppliers.
- Asian foundry concentration:Wafer fabrication capacity bottlenecks in Taiwan and South Korea constrain power semiconductor availability for distribution module integrators.
- Functional safety certification friction:ISO 26262 ASIL-D compliance timelines extend product validation cycles by 12-18 months for high-voltage architectures.
Strategic Opportunities
- Indian NEV manufacturing incentives:PLI scheme subsidies for domestic automotive electronics assembly create localized production footholds for distribution module suppliers.
- Vehicle-to-grid integration:Bidirectional power flow requirements in residential energy storage applications expand addressable market beyond propulsion systems.
- Software-defined load management:Over-the-air configurable fuse characteristics enable subscription-based feature upgrades and reduce hardware variant proliferation.
Industry Challenges
- High-voltage safety engineering talent scarcity:Specialized expertise in 400V-800V arc containment and isolation coordination remains concentrated among a limited pool of experienced engineers.
- Legacy 12V integration complexity:Hybrid architectures requiring simultaneous support for conventional low-voltage networks and high-voltage domains multiply validation matrix requirements.
- Multi-standard certification parallelism:Simultaneous ECE R10, GB/T, and FMVSS 302 compliance demands duplicate testing protocols for export-bound platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Power Distribution Modules Market |
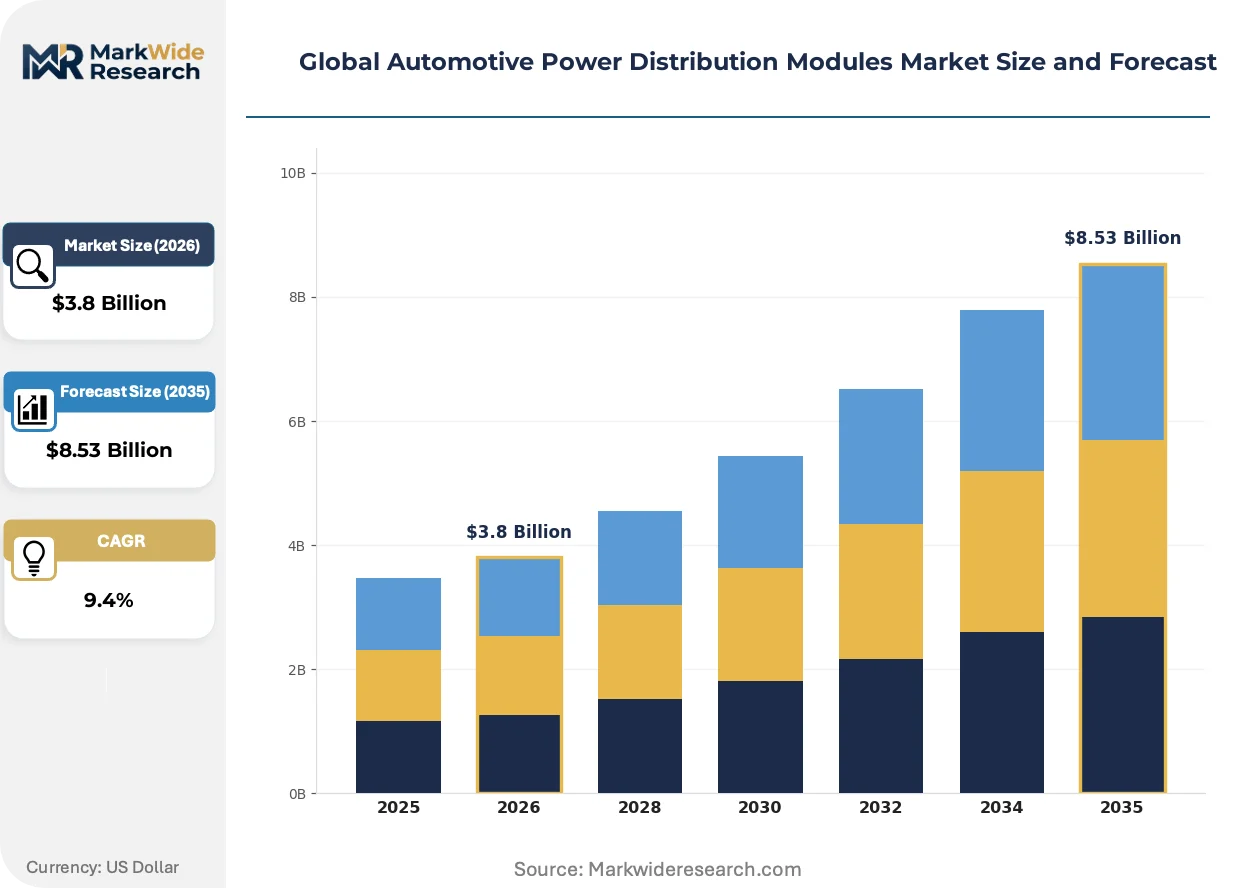
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuse Boxes, Relay Modules, Circuit Breakers, Battery Distribution Units End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Standard Modules, Smart Modules, Hybrid Modules, Integrated Systems Installation: Under Hood, Cabin, Chassis, Centralized |
| Companies Covered | Eaton, TE Connectivity, Bosch, Valeo, Infineon Technologies, Continental, Lear Corporation, Yazaki, Denso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Power Distribution Modules Market Emerging Trajectories
Solid-state switching technologies and embedded intelligence are redefining what power distribution modules accomplish, shifting their role from passive protection to active energy management nodes within vehicle electrical architectures.
Smart power stages based on silicon carbide MOSFETs are converging with real-time current sensing and edge computing to enable predictive fault isolation. Battery-electric OEMs in Germany and China are adopting these integrated modules for 800V architectures. The technology is converging with wireless diagnostic interfaces to eliminate service connector harnesses and reduce assembly mass.
EPA tailpipe regulations and NHTSA functional safety expectations are tightening electrical redundancy requirements for automated driving systems. These rules mandate duplicated power paths to critical sensors and actuators. Smart distribution modules with built-in health monitoring are capturing share from conventional fuse boxes in Level 2+ vehicle programs.
Fleet operators and commercial vehicle buyers are consolidating supplier relationships around module suppliers offering lifecycle data analytics. Long-haul trucking and last-mile delivery segments in the United States are prioritizing predictive maintenance capabilities over upfront hardware cost. This preference compression favors suppliers with embedded software competencies over pure hardware manufacturers.
Global Automotive Power Distribution Modules Market Segmentation
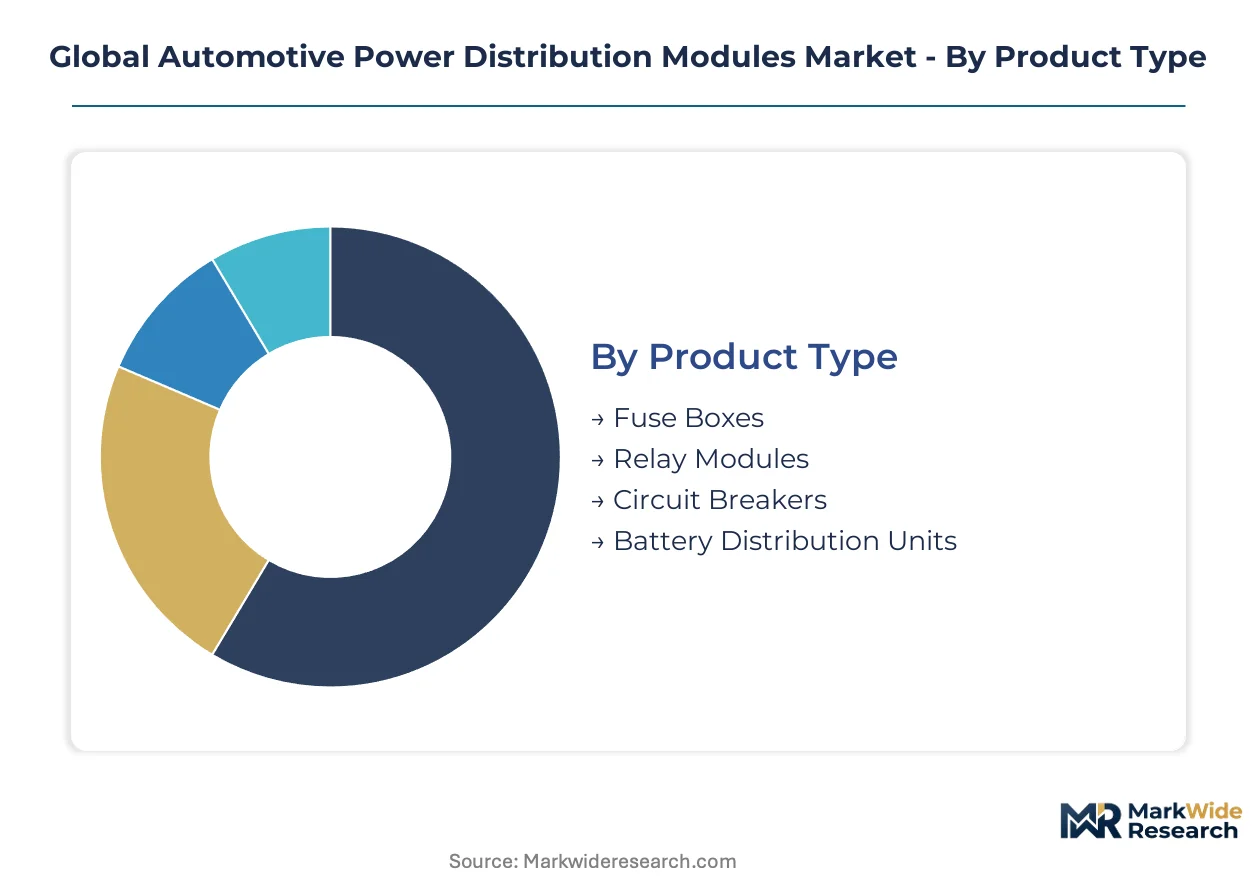
Power distribution modules fragment across four structural dimensions that determine pricing power, certification requirements, and supplier selection criteria. Product type and technology tiers capture the bulk of value migration as electrification architectures proliferate. Installation location and end-user channel definitions reshape procurement leverage and aftermarket service economics.
Product Type:
Volume production concentrates in legacy protection hardware while premium value accumulates in electrification-optimized distribution units.
- Fuse Boxes:Conventional blade-fuse assemblies with molded thermoplastic housings route 12V circuits through replaceable overcurrent protection elements. Demand concentrates in internal combustion and mild-hybrid platforms across India and Brazil where cost-optimized electrical architectures predominate.
- Battery Distribution Units:High-voltage electromechanical assemblies integrate pyro-fuses, contactors, and current sensors for 400V-800V battery pack interfaces. Procurement from German and Chinese OEMs accelerates as 800V platform production scales under EU Green Deal and GB/T compliance timelines.
- Relay Modules:Electromechanical switching devices with coil-actuated contacts control power routing to HVAC, lighting, and auxiliary systems.
- Circuit Breakers:Self-resetting thermal-magnetic protection devices serve commercial vehicle and heavy-duty applications requiring reduced service intervention.
Today's leader: Fuse Boxes. Tomorrow's challenger: Battery Distribution Units.
End User:
Direct OEM relationships command specification influence while aftermarket channels capture replacement cycle economics.
- OEMs:Original equipment manufacturers define module specifications through platform electrical architecture decisions and consolidate procurement around suppliers with ISO 26262 ASIL-D certification capabilities.
- Tier-1 Suppliers:Integrated system integrators source sub-modules for incorporation into larger powertrain or body electronics assemblies, concentrating purchasing power among German, Japanese, and North American conglomerates.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities procure distribution modules under OEM-directed supply agreements with limited specification autonomy.
- Aftermarket Providers:Independent distributors and service networks supply replacement fuse boxes and relay modules for legacy vehicle parc maintenance, with demand concentrated in 8-15 year vehicle age cohorts.
OEM specifications determine market access. Tier-1 integration capabilities determine margin capture.
Technology:
Standard hardware retains shipment volume while embedded intelligence commands expanding value share.
- Smart Modules:Solid-state switching platforms with silicon carbide MOSFETs, real-time current sensing, and edge computing enable predictive fault isolation and over-the-air configuration. German and Chinese battery-electric OEMs specify these for 800V architectures requiring diagnostic telemetry and arc fault containment.
- Integrated Systems:Multi-function assemblies combine power distribution with battery management system communication, thermal management control, and vehicle-to-grid bidirectional switching in single housings.
- Standard Modules:Passive fuse-and-relay configurations without electronic control or diagnostic capability serve cost-sensitive vehicle segments.
- Hybrid Modules:Mixed electromechanical and solid-state architectures bridge 12V legacy networks with 48V mild-hybrid systems.
Smart Modules gain specification share fastest. Integrated Systems capture the steepest expansion trajectory as platform consolidation accelerates.
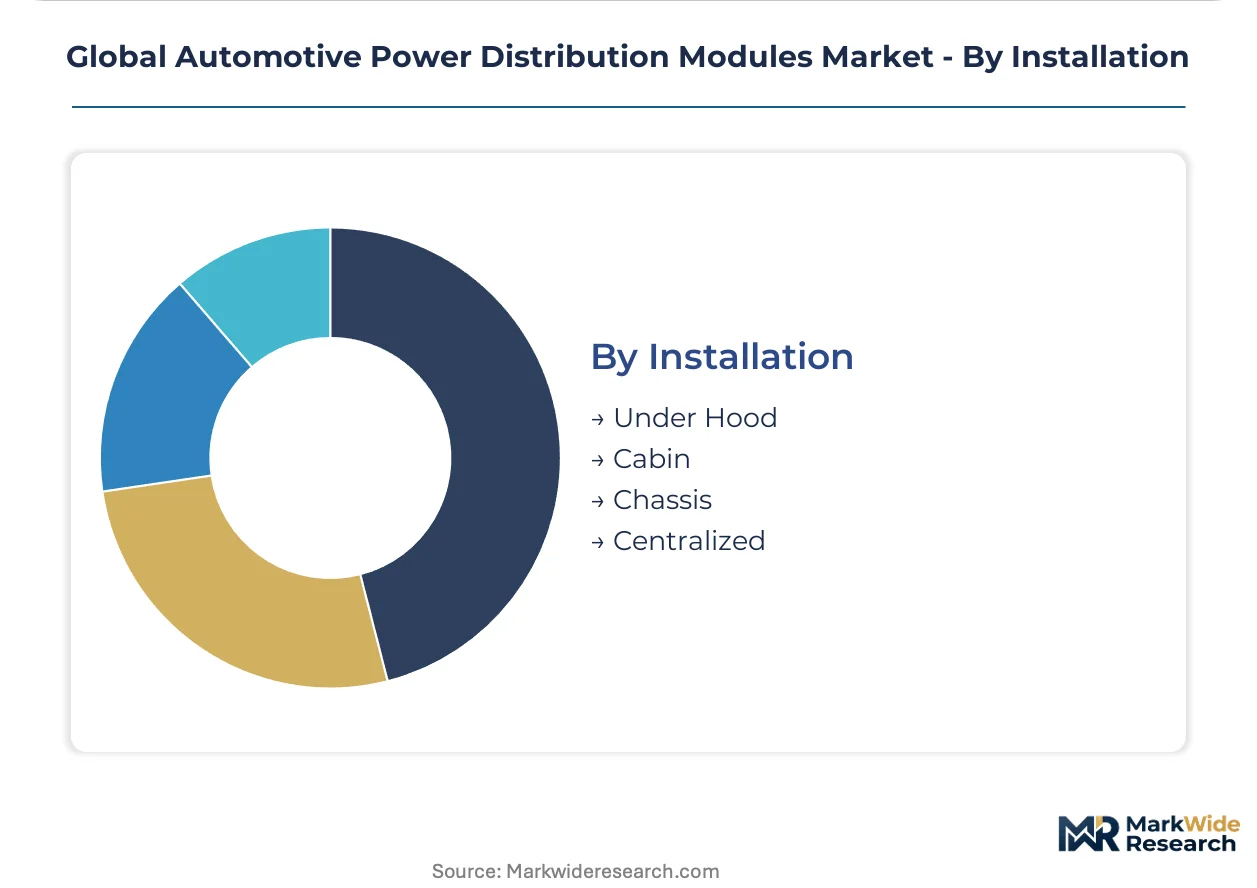
Installation:
Location determines environmental sealing requirements, thermal management design, and service accessibility constraints.
- Under Hood:Engine compartment mounting exposes modules to temperature extremes, vibration, and fluid contamination, demanding IP6K9K sealing and glass-reinforced polymer housings for thermal stability.
- Cabin:Interior placement behind dashboard or center console panels prioritizes acoustic isolation and compact packaging for occupant-accessible fuse servicing.
- Chassis:Frame rail or underbody mounting requires corrosion-resistant enclosures and stone impact protection for commercial vehicle and off-road applications.
- Centralized:Single-point distribution architectures consolidate all power routing through one high-capacity module, reducing harness mass but complicating fault isolation.
Under Hood placement dominates current production. Centralized architectures emerge as the preferred topology for skateboard electric vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in high-voltage safety and power electronics concentrate manufacturing decisions across four critical automotive production geographies. Each jurisdiction shapes module procurement through distinct regulatory timelines and electrification infrastructure investments.
Germany
Volkswagen Group and BMW procurement of 800V battery distribution units accelerates under EU Green Deal 2035 combustion phase-out mandates. KBA vehicle type approval requirements enforce ECE R10 electromagnetic compatibility standards for export-bound platforms. Bavaria's Ingolstadt and Munich clusters host tier-1 integration facilities supplying domestic OEM electrification programs.
China
CATL and BYD vertical integration into power distribution creates captive demand for high-voltage module assemblies. MIIT GB/T standards for new energy vehicles mandate specific overcurrent protection protocols for domestic battery-electric platforms. Yangtze River Delta manufacturing corridors around Shanghai concentrate module assembly capacity serving export and domestic OEMs.
United States
Detroit Three electrification investments drive specification of smart modules with predictive fault detection capabilities. EPA tailpipe regulations and NHTSA functional safety expectations tighten electrical redundancy requirements for automated driving systems. Michigan's automotive corridor anchors tier-1 supplier engineering centers developing 400V-800V distribution architectures.
Japan
Toyota and Honda hybrid platform persistence sustains demand for 12V-48V hybrid module configurations alongside pure-electric development. METI carbon-neutrality roadmaps coordinate semiconductor procurement strategies for power electronics. Nagoya's Chubu industrial region hosts specialized contactor and relay manufacturers supplying domestic vehicle assemblers.
India
Maruti Suzuki and Tata Motors NEV production scaling concentrates module demand in domestic passenger and commercial vehicle segments. PLI scheme subsidies for automotive electronics assembly incentivize localized manufacturing investments. Tamil Nadu's Sriperumbudur industrial belt attracts distribution module suppliers establishing captive production for export markets.
Global Automotive Power Distribution Modules Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement hierarchies. Tier-1 system integrators consolidate purchasing power through platform-level electrical architecture decisions. Three archetypes dominate: semiconductor-integrated module manufacturers, circuit protection heritage suppliers, and wiring harness conglomerates with distribution capabilities. Capacity expansion and strategic partnerships constitute the primary competitive vectors as electrification timelines compress development cycles.
Among diversified industrial conglomerates, Eaton and Bosch exemplify archetype differentiation through heritage positioning. Eaton occupies a position within circuit protection-focused suppliers leveraging electromechanical expertise for high-voltage contracts. Bosch sits within semiconductor-integrated manufacturers controlling margin through in-house silicon capabilities. TE Connectivity represents the connectivity-specialist archetype bridging wiring harness and power distribution domains.
| Leading Market Players |
|---|
| Eaton |
| TE Connectivity |
| Bosch |
| Valeo |
| Infineon Technologies |
| Continental |
| Lear Corporation |
| Yazaki |
| Denso |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-neutrality mandates gate qualified supply access and premium-tier pricing power for automotive power distribution modules, compressing margins for uncertified suppliers while rewarding ASIL-D-compliant manufacturers with pricing leverage in German and French OEM procurement.
Pricing Analysis
Bundled lifecycle service contracts separate from unbundled hardware-only transactions across the procurement landscape. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and silicon carbide content. Pricing pressure stems from copper and semiconductor input volatility, compressing margins for tier-2 integrators. Fleet operators exhibit lowest price sensitivity, prioritizing predictive maintenance capabilities over upfront hardware cost.
Supply Chain Analysis
Silicon carbide wafer supply rests on Taiwanese and South Korean foundry capacity, with German and Chinese module integrators drawing from concentrated Asian semiconductor sources. Copper busbar, thermoplastic housing resins, and pyro-fuse elements constitute critical input dependencies. Single-source vulnerability in 800V contactor manufacturing creates bottleneck exposure for battery distribution unit production. Distribution runs through tier-1 system integrators with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive power distribution modules hinges on silicon carbide semiconductor cost curves flattening and smart module value capture displacing commodity fuse box economics.
For Market Incumbents: Hedge against Asian foundry concentration by qualifying secondary semiconductor sources in Japan and the United States. Deepen backward integration into current sensing and arc detection IP to defend against Chinese module suppliers capturing 800V platform share. Prioritize ASIL-D certification maintenance as NHTSA functional safety expectations tighten for automated driving power redundancy. For New Entrants and Emerging Players: Launch via software-defined load management subscriptions targeting commercial vehicle fleet operators in the United States. Penetrate the Indian NEV manufacturing corridor under PLI scheme subsidies, where domestic assembly requirements create localized production footholds. Lead with over-the-air configurable fuse characteristics as a service differentiator against legacy hardware incumbents. For Investors and Strategic Acquirers: Roll-up economics work for semiconductor-integrated module specialists because tier-1 procurement consolidation favors suppliers with in-house silicon capabilities and ISO 26262 certification infrastructure. Five-to-ten year viability centers on capturing 800V platform specification share in German and Chinese battery-electric production. Watch silicon carbide MOSFET cost parity with IGBT modules as the inflection signal for smart module mass adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Integration | In-house wide-bandgap capability secures margin control against foundry-dependent competitors. |
| ASIL-D Certification Investment | Functional safety accreditation unlocks German OEM 800V battery distribution unit procurement. |
| Indian Manufacturing Footprint Establishment | PLI scheme subsidies reduce landed cost for export-bound module production. |
| Software-Defined Load Management Platform | Over-the-air configuration enables subscription revenue streams beyond hardware sales. |
| Vehicle-to-Grid Bidirectional Switching Development | Residential energy storage integration expands addressable market beyond propulsion systems. |
Methodological Framework
Multiple input streams — OEM platform engineering interviews, tier-1 supplier procurement discussions, aftermarket distributor operational reviews, and semiconductor foundry capacity assessments — were reconciled against vehicle production databases, IHS Markit registration data, SEC automotive segment filings, and customs trade records. Bottom-up module shipment estimates by propulsion architecture were triangulated with top-down automotive electronics content forecasts.
Data-stream reconciliation across the projection horizon modeled segmentation by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from platform electrification timeline analysis and semiconductor adoption curve integration. Forecast inputs incorporated EU Green Deal compliance deadlines, EPA tailpipe regulation phase-ins, and MIIT GB/T standard evolution patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility and foundry capacity constraint scenarios. Automotive power distribution module projections reflect assumptions on 800V platform penetration rates and silicon carbide cost reduction trajectories. A small set of triggers — semiconductor supply shocks, regulatory timeline acceleration, and Chinese NEV export policy shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive Grade Inductors Market