
 Vehicle Roof Control Module Market | 2026-2036
Vehicle Roof Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Roof Control Module Market Analysis
Luxury electric vehicle OEMs is redrawing procurement priorities across the Vehicle Roof Control Module landscape, shifting volume toward intelligent, factory-installed configurations. Webasto Group leverages its vertical integration in glass bonding and mechatronics to sustain engineering partnerships with European premium brands. Magna International Inc. anchors North American supply through manufacturing scale across multiple vehicle platforms. Inalfa Roof Systems Group specializes in modular panoramic architectures that compete on weight reduction and acoustic performance.
A vehicle roof control module integrates electromechanical actuators, position sensors, climate seals, and embedded control units to manage aperture operation, load distribution, and cabin environmental regulation. The assembly typically incorporates aluminum extrusions, reinforced polymer carriers, and laminated glass panels rated for rollover structural integrity per regional crash standards. Panoramic sunroof configurations command the largest value share due to their multi-panel complexity and premium vehicle penetration. Intelligent system technology represents the fastest-expanding segment, driven by rain-sensing closure, voice-activated positioning, and CAN-bus integration that differentiates supplier engineering depth. Electrical control remains the dominant technology platform, though hydraulic systems retain niche presence in heavy convertible applications where torque requirements exceed electromechanical limits.
NHTSA administers FMVSS 216 roof crush resistance testing that directly shapes module reinforcement strategies and material specifications for vehicles sold in the United States. ECE R66 and ECE R29 standards in Europe impose parallel structural and rollover requirements that filter through OEM technical specifications to Tier-1 engineering targets. OEM procurement teams must monitor how intelligent system architectures alter validation cycles and software liability exposure as roof modules absorb greater functional scope.
Market Dynamics
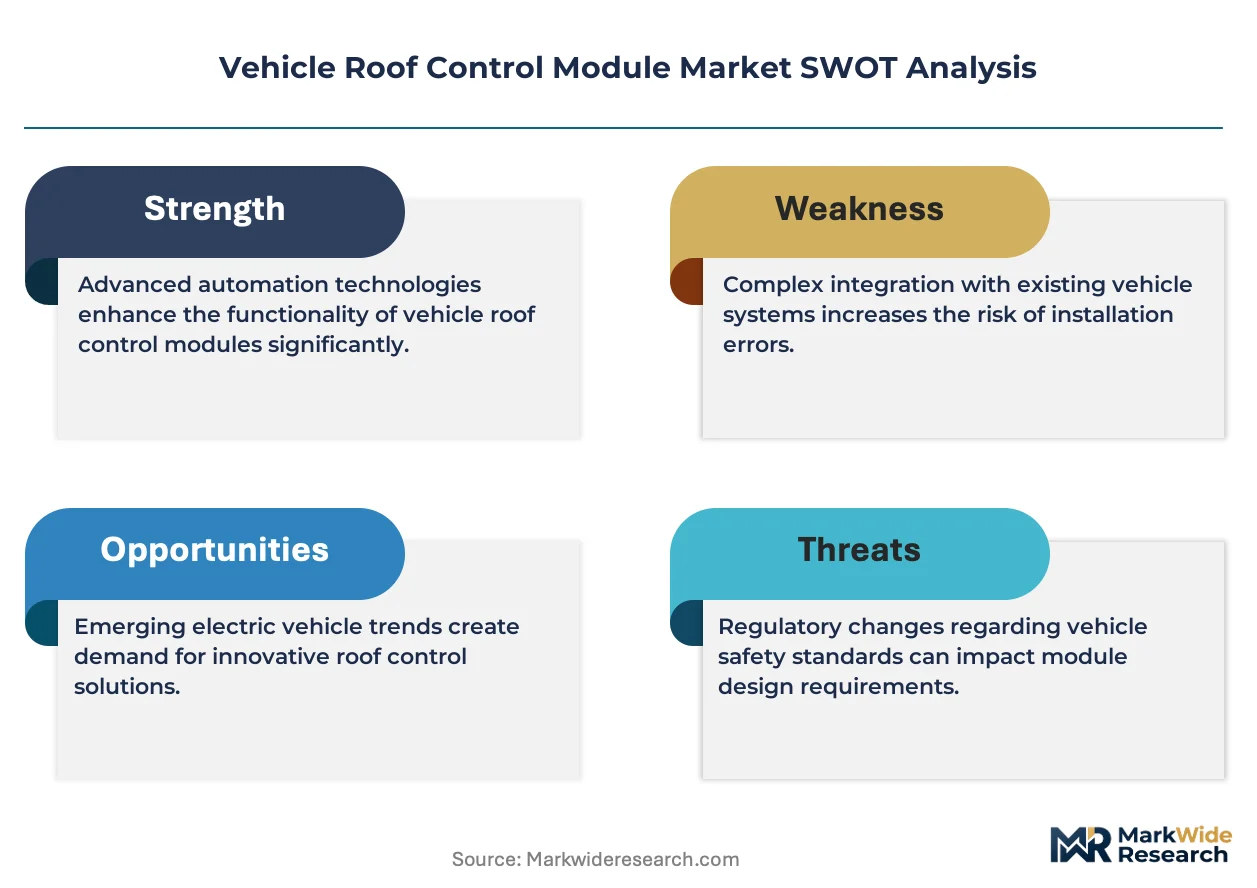
Intelligent roof system architectures are compressing validation cycles and expanding software liability exposure as electromechanical modules absorb greater functional scope from discrete body electronics. This structural shift is forcing Tier-1 suppliers to reconfigure engineering teams and capital allocation toward embedded systems competency.
Growth Catalysts
- FMVSS 216 roof crush resistance mandates:NHTSA structural testing requirements in the United States are accelerating material upgrades toward aluminum-reinforced polymer carriers that command premium module pricing.
- Luxury electric vehicle penetration:Factory-installed panoramic configurations are concentrating procurement volume with suppliers capable of glass bonding and mechatronics integration.
- CAN-bus integration protocols:Unified vehicle network architectures are enabling rain-sensing closure and voice-activated positioning that differentiate intelligent roof systems from mechanical alternatives.
Market Restraints
- Laminated glass supply concentration:Structural glass rated for rollover integrity is captive to a limited supplier base in Germany and Japan, creating input cost volatility.
- Hydraulic system legacy presence:Heavy convertible applications retain electromechanical torque limitations that fragment platform standardization efforts.
- ECE R66 certification timelines:European rollover structural requirements extend validation cycles by 8-14 months versus conventional aperture mechanisms.
Strategic Opportunities
- Voice-activated positioning convergence:Integration of natural language processing with mechatronic actuators is opening white space in premium cabin experience differentiation.
- Acoustic performance specialization:Modular panoramic architectures that reduce NVH are capturing procurement interest from German premium OEMs expanding electric vehicle portfolios.
- Aftermarket intelligent retrofits:Rain-sensing closure modules are penetrating independent service channels in the United States where panoramic sunroof install bases exceed 12 million units.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262-compliant roof control algorithms is concentrating in Stuttgart and Munich, inflating compensation premiums.
- Multi-material bonding capex intensity:Aluminum extrusion-to-glass lamination equipment requires dedicated cleanroom facilities that strain mid-cap supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Roof Control Module Market |
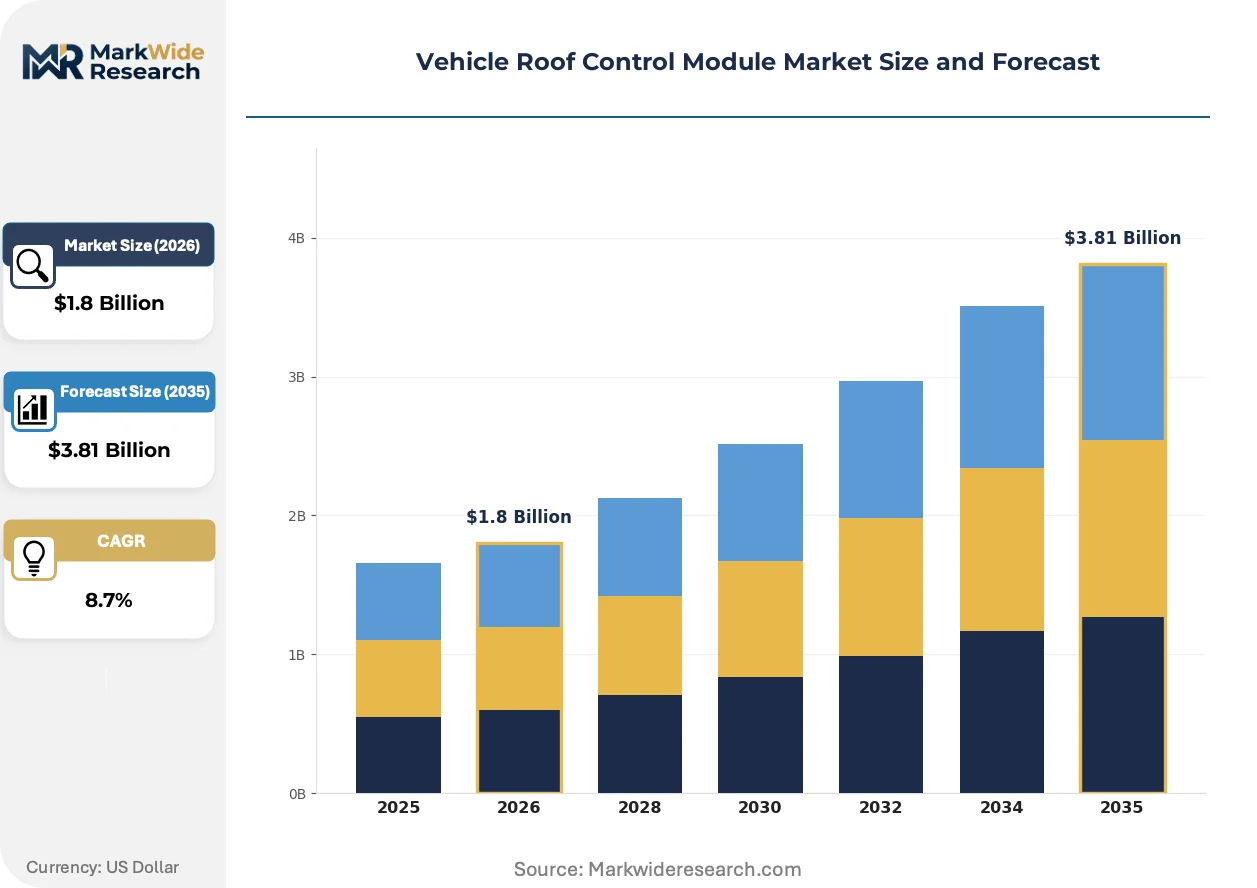
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunroof Module, Convertible Roof System, Panoramic Sunroof, Roof Railing Control Technology: Electrical Control, Mechanical Operation, Hydraulic System, Intelligent System End User: OEMs, Aftermarket Providers, Assembly Plants, Tier-1 Suppliers Installation: Factory Installed, Aftermarket Installation, Integrated Solutions, Custom Solutions |
| Companies Covered | Webasto Group, Magna International Inc., AISIN SEIKI, Valmet Automotive Inc., Inteva Products LLC, AAS Automotive, Inalfa Roof Systems Group, BOS Group, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Roof Control Module Market Emerging Trajectories
Software-defined roof functionality is displacing discrete electromechanical controls as OEMs consolidate body electronics into domain controllers. This convergence is compressing supplier engineering margins while expanding the addressable value pool for integrated module architectures.
Polymer carrier substrates with embedded conductive traces are fragmenting traditional wire harness architectures in roof module assemblies. Premium electric vehicle platforms from German and South Korean OEMs are adopting these substrates at 18-24 month replacement cycles versus 7-10 year harness refresh rates. The shift is fragmenting Tier-2 supply relationships and concentrating value capture with in-house mechatronics specialists.
REACH substance restrictions on certain adhesive chemistries are forcing reformulation of glass-to-frame bonding systems used in panoramic configurations. European module suppliers are qualifying UV-cured acrylic alternatives that maintain shear strength across temperature cycling. Convertible roof segments face the steepest compliance cost escalation due to larger bonded surface areas and dynamic load requirements.
Fleet procurement of intelligent roof modules is consolidating around outcome-based performance guarantees rather than unit pricing. Rental and subscription vehicle operators in the United States are prioritizing warranty terms covering sensor calibration and actuator longevity over upfront capital expenditure. This behavioral shift is visible most acutely in corporate fleet channels where total cost of ownership models now dominate supplier selection criteria.
Vehicle Roof Control Module Market Segmentation
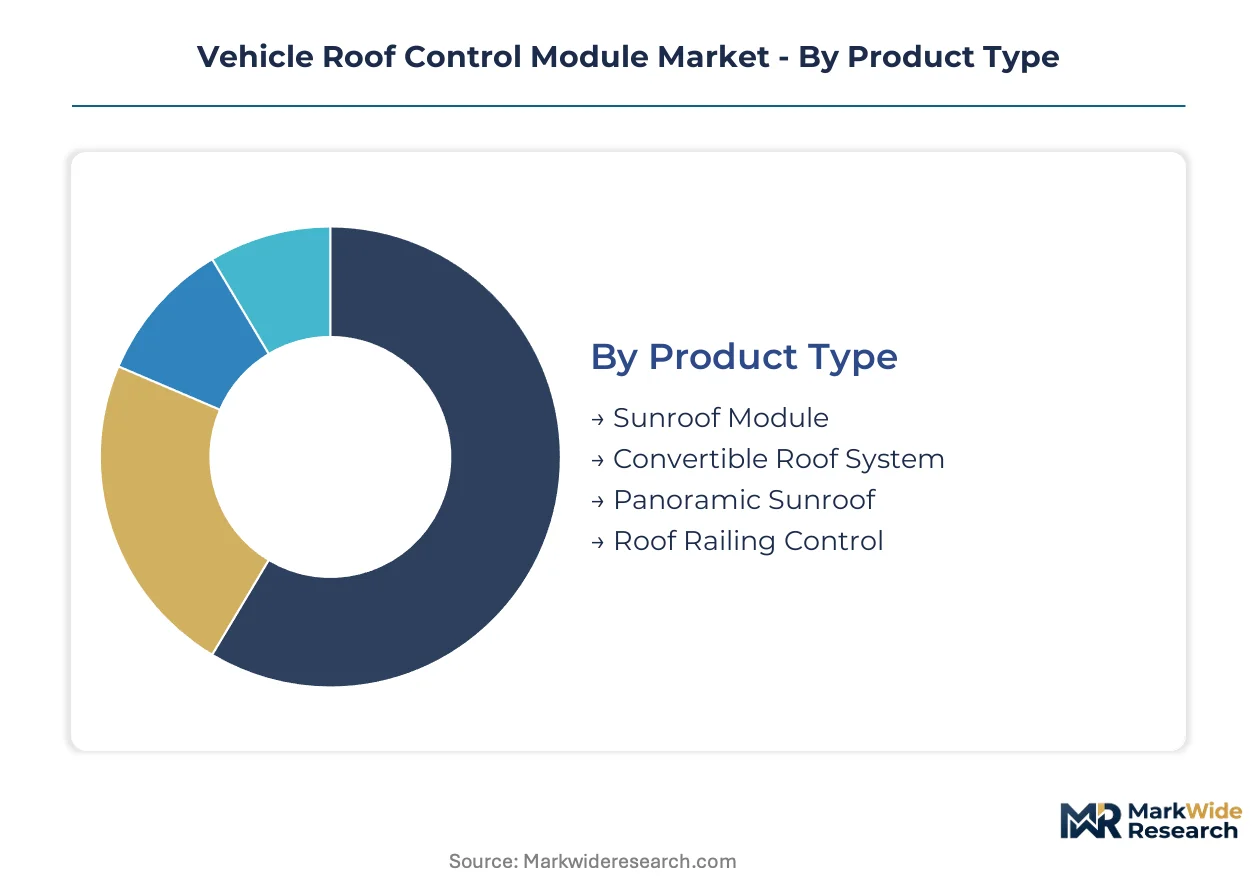
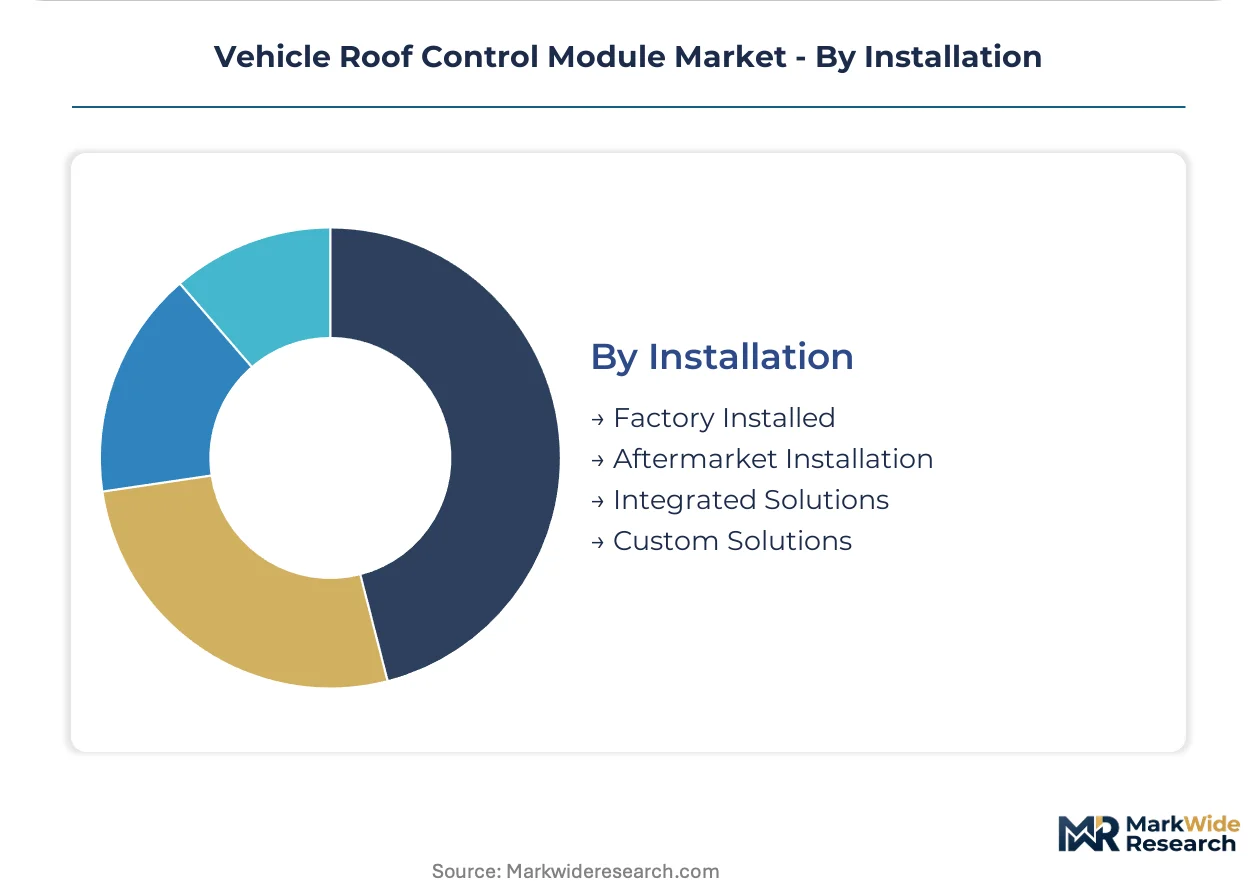
Roof control module procurement flows through distinct channel configurations that reshape supplier priorities. Factory-installed intelligent systems concentrate volume with vertically integrated Tier-1s, while aftermarket channels fragment across independent service networks and retrofit specialists.
Product Type:
Channel mix varies sharply by product complexity—panoramic and intelligent configurations anchor OEM direct procurement, while railing controls and basic sunroof modules distribute more evenly through Tier-1 and aftermarket channels.
- Panoramic Sunroof:Multi-panel laminated glass assemblies with reinforced aluminum carriers dominate premium electric vehicle factory installations. German OEMs anchor engineering specifications for these modules, driving consolidation among suppliers with captive glass bonding and mechatronics integration capabilities.
- Sunroof Module:Single or dual-panel electromechanical assemblies with embedded position sensors and climate seals constitute the highest-volume production category. Assembly plants in the United States and Germany concentrate procurement for mid-luxury sedans and crossovers where aperture operation reliability shapes warranty exposure.
- Convertible Roof System:Heavy-duty folding mechanisms with dynamic load distribution for open-air structural integrity.
- Roof Railing Control:Modular carrier systems for accessory mounting with integrated aerodynamic management.
By volume, Sunroof Module leads. By growth pace, Panoramic Sunroof is climbing the fastest.
Technology:
Cost tier stratification separates electrical and intelligent platforms from legacy mechanical alternatives, with hydraulic systems occupying a narrow premium niche for torque-intensive applications.
- Intelligent System:CAN-bus integrated architectures with rain-sensing closure, voice-activated positioning, and embedded control algorithms represent the steepest expansion trajectory. ISO 26262 functional safety compliance and embedded software talent scarcity in Stuttgart and Munich inflate development costs for this tier.
- Electrical Control:Electromechanical actuators with discrete sensor feedback dominate current production volumes across mass-market and premium platforms. NHTSA FMVSS 216 roof crush resistance mandates accelerate material upgrades toward aluminum-reinforced polymer carriers within this technology base.
- Hydraulic System:High-torque fluid power mechanisms retained in heavy convertible applications where electromechanical limits are exceeded.
- Mechanical Operation:Manual or basic cable-actuated systems with minimal electronic content for entry vehicle segments.
By installed base, Electrical Control dominates. By value capture rate, Intelligent System is gaining share fastest.
End User:
Customer type determines specification authority—OEMs and Tier-1s control design validation, while assembly plants and aftermarket providers execute installation and service with limited engineering influence.
- OEMs:Brand-holding manufacturers with direct specification authority over module architecture, material selection, and embedded software functionality. Luxury electric vehicle OEMs are compressing validation cycles and expanding liability exposure as roof modules absorb greater functional scope from discrete body electronics.
- Tier-1 Suppliers:System integrators responsible for mechatronics assembly, glass bonding, and OEM interface management. REACH substance restrictions on adhesive chemistries force reformulation of bonding systems, concentrating compliance cost escalation among European-based Tier-1s.
- Assembly Plants:Final vehicle manufacturing facilities executing module installation per OEM build specifications.
- Aftermarket Providers:Independent service channels and retrofit specialists targeting rain-sensing closure modules for existing panoramic sunroof install bases exceeding 12 million units in the United States.
By procurement value, OEMs lead. By channel expansion, Aftermarket Providers are expanding most quickly.
Installation:
Maturity gradient separates established factory-installed volumes from emerging integrated and custom solution architectures that blur traditional build-phase boundaries.
- Factory Installed:Line-fit assembly during vehicle manufacturing with full design integration and warranty alignment. Fleet procurement is consolidating around outcome-based performance guarantees rather than unit pricing, prioritizing sensor calibration and actuator longevity coverage.
- Integrated Solutions:Pre-assembled module-carrier combinations with embedded electronics and climate management for streamlined OEM assembly. Polymer carrier substrates with embedded conductive traces are fragmenting traditional wire harness architectures, adopted by German and South Korean OEMs at accelerated replacement cycles.
- Aftermarket Installation:Post-production retrofit services for feature upgrades or replacement of failed modules.
- Custom Solutions:Bespoke configurations for limited-production vehicles or specialized commercial applications.
By unit volume, Factory Installed leads. By specification evolution, Integrated Solutions are advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering specifications for intelligent roof systems flow outward to assembly plants in the United States and South Korea, establishing cross-border technical standards that reshape supplier qualification requirements.
United States
NHTSA FMVSS 216 roof crush resistance mandates drive material upgrades toward aluminum-reinforced polymer carriers in Detroit-area assembly plants. The Inflation Reduction Act's domestic content incentives concentrate module sourcing decisions with North American Tier-1s capable of bonded glass assembly. Michigan and Ohio anchor manufacturing scale for mid-luxury crossovers where warranty exposure shapes procurement priorities.
Germany
Premium electric vehicle OEMs in Stuttgart and Munich compress validation cycles as roof modules absorb body electronics functionality. REACH substance restrictions on adhesive chemistries force reformulation of glass-to-frame bonding systems among Baden-Württemberg-based suppliers. Bavaria concentrates embedded software talent for ISO 26262-compliant control algorithms, inflating compensation premiums for functional safety engineers.
China
Dual carbon goals accelerate lightweighting requirements for electric vehicle roof assemblies in the Yangtze River Delta. MIIT vehicle safety standards tighten structural specifications for panoramic configurations in domestic premium platforms. Shanghai and Jiangsu province concentrate glass lamination capacity, though structural rollover-rated supply remains import-dependent from German and Japanese sources.
Japan
METI industrial policy supports mechatronics integration for next-generation aperture mechanisms in Kanto-region manufacturing clusters. JIS standards for automotive electronics filter through OEM technical specifications to Tier-1 engineering targets. Aichi prefecture anchors precision actuator production, with Nagoya-based suppliers specializing in torque-dense electromechanical systems for multi-panel architectures.
South Korea
Seoul Capital Area OEMs adopt polymer carrier substrates with embedded conductive traces at accelerated replacement cycles versus conventional wire harness architectures. MFDS automotive safety guidelines shape validation protocols for intelligent roof systems in domestic electric vehicle platforms. Gyeonggi-do province concentrates module assembly for export-bound premium crossovers, with Hyundai-Kia supply chains driving specification authority.
Vehicle Roof Control Module Market Vendor Landscape
Player mix skews toward vertically integrated glass-bonding specialists with captive mechatronics capabilities. The supplier base concentrates around three strategic archetypes: European premium-system integrators with OEM co-development relationships, North American scale manufacturers serving multi-platform assembly contracts, and Asian precision-component specialists feeding modular architectures. Competitive moves center on M&A to secure glass lamination capacity and strategic partnerships to embed software-defined functionality.
Within the integrated-system tier, Webasto Group and Magna International Inc. exemplify contrasting geographic anchoring strategies. Webasto represents European premium-brand co-development depth, while Magna occupies a position as North American multi-platform scale supplier. Inalfa Roof Systems Group sits within the modular-architecture specialization vector, illustrating how weight-reduction and acoustic-performance capabilities capture procurement interest from German OEMs expanding electric portfolios.
| Leading Market Players |
|---|
| Webasto Group |
| Magna International Inc. |
| AISIN SEIKI |
| Valmet Automotive Inc. |
| Inteva Products LLC |
| AAS Automotive |
| Inalfa Roof Systems Group |
| BOS Group |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German OEMs and Baden-Württemberg glass bonding specialists lock in aluminum-reinforced polymer carrier supply while anchoring module pricing visibility across multi-year vehicle platform cycles. These contracts insulate Tier-1s from laminated glass input volatility while committing buyers to volume thresholds that shape capital allocation for cleanroom lamination facilities.
Pricing Analysis
Next-generation intelligent system modules command 40-60% premiums over electrical control platforms due to ISO 26262 functional safety certification requirements and embedded software development costs. Three-tier pricing structure across premium, standard, and economy levels separates panoramic multi-panel configurations from single-aperture sunroof modules and basic railing controls. Cost compression in standard electrical tiers is intensifying because REACH adhesive reformulation expenses concentrate among European suppliers without captive chemistry capabilities. Fleet procurement teams exhibit lowest price sensitivity as outcome-based performance guarantees prioritize warranty coverage over unit economics.
Supply Chain Analysis
Strategic stockpiling of rollover-rated laminated glass dominates Tier-1 procurement behavior given 8-14 month ECE R66 certification timelines that disrupt just-in-time assembly rhythms. Manufacturing gravity centers on Germany, Japan, and the United States, with structural glass supply drawing from captive German and Japanese sources that create single-source vulnerability for Chinese and South Korean OEMs. Aluminum extrusion-to-glass bonding equipment, embedded conductive trace polymer substrates, and precision electromechanical actuators constitute critical input dependencies. Distribution runs through OEM direct channels for factory-installed intelligent systems, while aftermarket channels fragment across independent service networks targeting the 12 million-unit panoramic install base in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software engineering depth for CAN-bus integrated roof architectures is concentrating in Stuttgart and Munich at rates that outstrip supply, creating a capability-scarcity environment where functional safety talent commands compensation premiums that reshape supplier economics.
For Market Incumbents: Shield glass bonding and mechatronics integration capabilities through backward integration into aluminum extrusion supply or capacity reservation agreements with Baden-Württemberg lamination specialists. Prioritize ISO 26262 certification investment to defend against emerging modular-architecture competitors from South Korea that lack embedded software depth but capture share through polymer substrate innovation. For New Entrants and Emerging Players: Differentiate on acoustic performance specialization and NVH reduction for German premium electric vehicle portfolios where procurement teams prioritize cabin experience over cost minimization. Target aftermarket rain-sensing closure retrofits in the United States where independent service channels face 12 million-unit install bases with limited intelligent system penetration. Pursue white-label partnerships with Tier-1 system integrators lacking in-house software development capacity. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated glass-bonding specialists with captive mechatronics capabilities and established OEM co-development relationships in European premium segments. Long-term viability hinges on embedded software talent access and cleanroom lamination asset ownership rather than pure assembly scale. Monitor MFDS and MIIT safety standard harmonization as the inflection signal for Chinese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Glass Bonding Capacity Expansion | Captive lamination facilities in Baden-Württemberg insulate Tier-1s from REACH compliance cost escalation. |
| Embedded Software Acquisition | Functional safety engineering teams in Stuttgart and Munich command premiums that reshape supplier valuation models. |
| Polymer Substrate Partnership | South Korean OEM adoption of conductive trace carriers at 18-24 month cycles fragments traditional wire harness supply. |
| Aftermarket Channel Development | Rain-sensing closure modules penetrate independent service networks targeting 12 million-unit US panoramic install base. |
| Regulatory Certification Investment | ECE R66 and FMVSS 216 compliance capabilities differentiate suppliers in OEM procurement decisions. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 procurement directors, aftermarket service operators, and embedded software specialists converged on the working assumptions driving module demand forecasts. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 216 test records, and ECE R66 certification filings. Bottom-up triangulation across component bill-of-materials analysis and top-down reconciliation with OEM platform rollout schedules anchored volume estimates.
Segmentation dimensions modeled span product type, technology generation, end-user channel, and installation configuration across the projection horizon. Vehicle class, propulsion architecture, content per vehicle, and regional production cluster variations shaped analytical framework construction. CAGRs derived from installed base evolution, replacement cycle compression for polymer substrates versus wire harnesses, and intelligent system penetration curves. Forecast inputs incorporated NHTSA structural testing mandate timelines, REACH substance restriction implementation phases, and fleet procurement behavioral shifts toward outcome-based contracting.
Material uncertainties — tariff exposure on German and Japanese structural glass, embedded software talent scarcity inflation, and MIIT safety standard acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about OEM platform standardization trajectories and Tier-1 consolidation patterns that practitioners should keep alternative scenarios live as regulatory harmonization and supply chain regionalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Global Automotive Engine Management System Market