
 Automotive Throttle Position Sensor Market | 2026-2036
Automotive Throttle Position Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Throttle Position Sensor Market Outlook
The gap between precision-engineered contactless sensors and cost-optimized potentiometric units is realigning procurement patterns across OEM and aftermarket channels. Robert Bosch GmbH leverages its integrated electronics foundry network to sustain margin capture in Hall Effect modules. Continental AG dominates European OEM supply agreements through captive sensor-ASIC design capabilities. Delphi Technologies anchors North American aftermarket distribution with broad catalog coverage of analog replacement units.
An automotive throttle position sensor translates accelerator pedal angle into voltage signals that engine control modules process for fuel injection timing, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius with resolution below one percent. Hall Effect and magnetic technologies lead new platform design-ins as automakers eliminate mechanical wear points in electrified powertrains, while potentiometric architectures retain aftermarket volume due to backward compatibility with legacy internal combustion fleets. OEMs capture the dominant value share of original equipment sensor demand, though aftermarket providers concentrate margin in diagnostic-intensive replacement cycles for aging commercial vehicle populations.
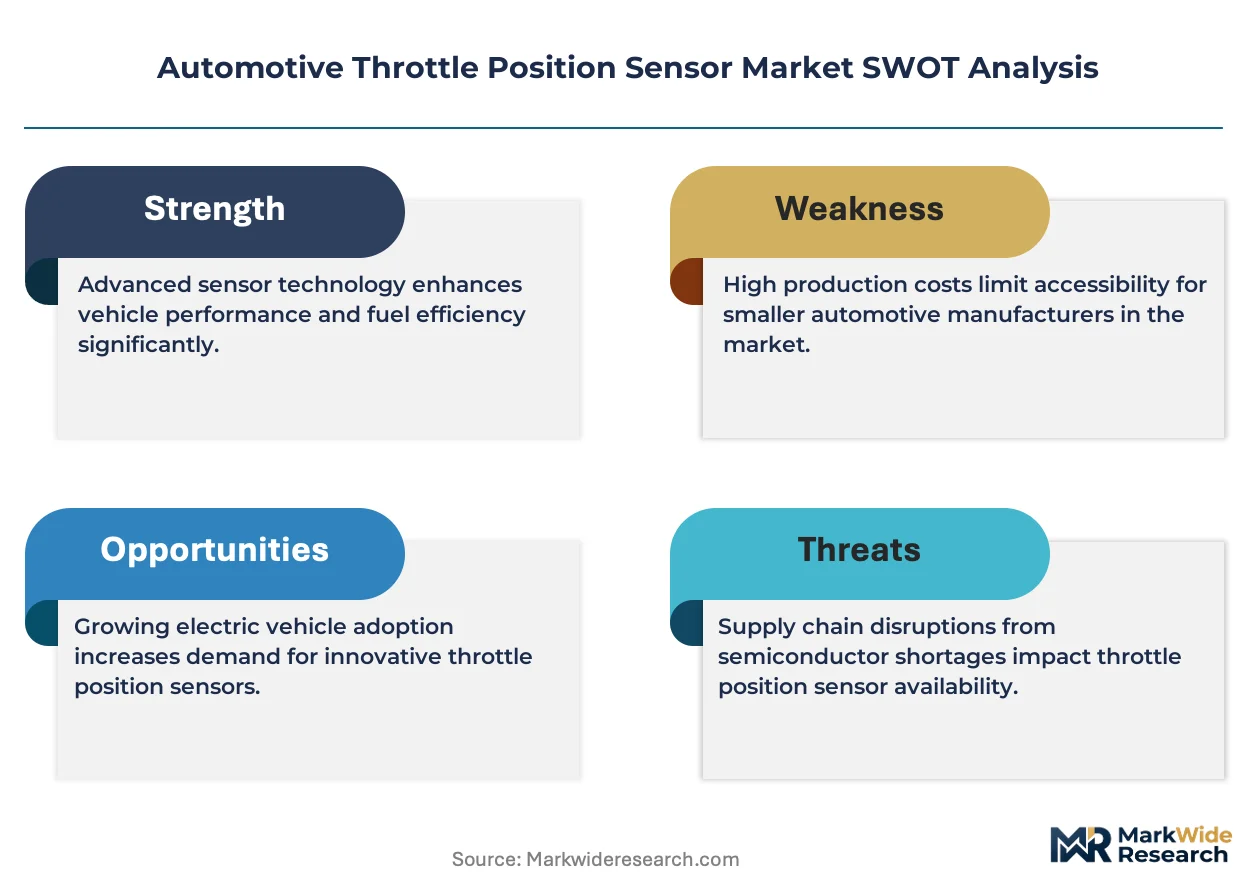
NHTSA enforces functional safety standards that mandate redundant throttle-position validation in drive-by-wire architectures, while EPA tailpipe regulations indirectly shape sensor precision requirements through emissions-calibration stringency. ISO 26262 automotive safety integrity levels constrain supplier qualification timelines and elevate testing documentation burdens for new market entrants. Stakeholders must weigh technology transition risk against aftermarket service-life extension as powertrain electrification accelerates sensor specification divergence between platforms.
Market Dynamics
Powertrain electrification is fragmenting sensor specifications as automakers split development resources between legacy internal combustion platforms and dedicated EV architectures. This divergence compresses procurement timelines while multiplying validation requirements for suppliers serving both technology streams.
Growth Catalysts
- EPA emissions-calibration stringency:Tailpipe enforcement protocols in the United States mandate finer throttle-resolution granularity, forcing sensor upgrades across light-duty and commercial vehicle fleets.
- China EV production scaling:Domestic electric vehicle manufacturing concentrates demand for contactless Hall Effect modules as local OEMs eliminate mechanical wear components from powertrain designs.
- ISO 26262 functional safety mandates:Automotive safety integrity levels require redundant throttle-position validation, expanding sensor count per vehicle in drive-by-wire architectures.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings squeeze margins on Hall Effect sensor production, particularly for suppliers without long-term offtake agreements.
- Foundry capacity concentration:Automotive-grade ASIC fabrication concentrates in Taiwan and South Korea, creating geographic supply risk for sensor-integrated electronics.
- Potentiometric obsolescence pressure:Mechanical contact-based sensors face gradual displacement as OEMs prioritize contactless architectures, stranding aftermarket inventory investments.
Strategic Opportunities
- India commercial vehicle retrofit demand:Aging truck and bus fleets require throttle sensor replacements as the country's emissions enforcement tightens, creating aftermarket volume.
- Magnetic-inductive convergence:Hybrid sensing architectures combining Hall Effect precision with inductive robustness open design-in opportunities for next-generation EV platforms.
- United States IRA clean vehicle incentives:Domestic EV production subsidies accelerate localized sensor sourcing requirements, favoring regional manufacturing investments.
Industry Challenges
- Embedded software certification backlog:ISO 26262 documentation requirements for sensor-integrated firmware extend supplier qualification timelines by 12-18 months.
- Legacy fleet compatibility maintenance:Aftermarket providers must sustain potentiometric production lines alongside contactless development, splitting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Throttle Position Sensor Market |
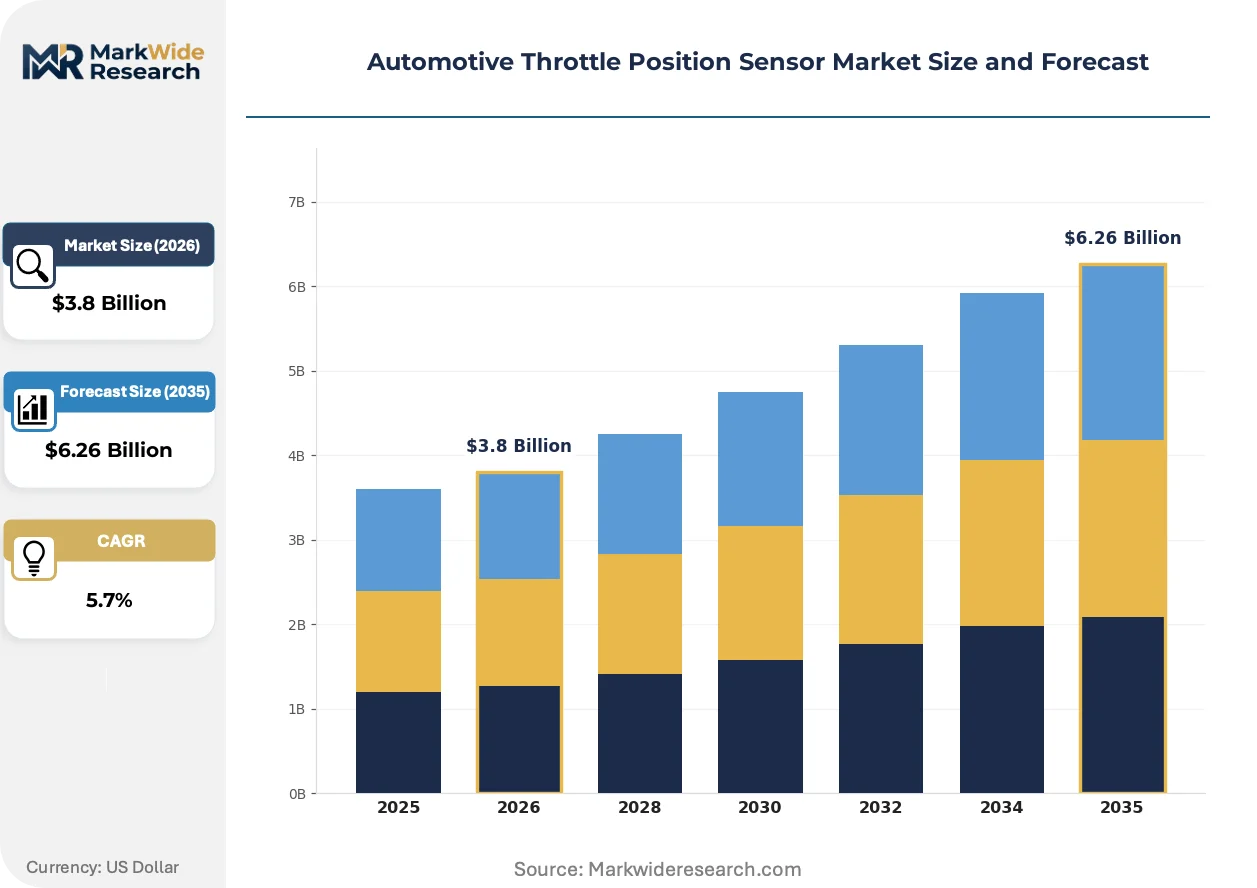
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Sensors, Non-Contact Sensors, Digital Sensors, Analog Sensors Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Technology: Hall Effect, Potentiometric, Magnetic, Optical |
| Companies Covered | HELLA GmbH & Co. KGaA, Delphi Technologies, Robert Bosch GmbH, TE Connectivity, Sensata Technologies, Denso Corporation, CTS Corporation, Mitsubishi Electric Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Throttle Position Sensor Market Strategic Shifts
Sensor architecture consolidation is compressing component counts while elevating performance thresholds. Three developments are actively restructuring competitive requirements and procurement patterns.
Contactless magnetic sensing is unifying position-detection functions previously handled by separate angle and linear sensors into single-package modules. Tier 1 suppliers serving European and North American OEMs are accelerating design-ins for 2027-2028 platform cycles. This consolidation is unifying procurement specifications across vehicle segments, reducing supplier qualification overhead while raising performance barriers for single-function competitors.
NHTSA functional safety enforcement is mandating redundant throttle-position validation channels in all drive-by-wire systems. The regulation requires independent sensor outputs cross-checked by engine control modules before actuation commands execute. Light-duty OEMs in the United States are responding with dual-Hall architectures, while commercial vehicle manufacturers pursue magnetic-inductive hybrid designs for enhanced fault tolerance.
Sensor-ASIC integration is compressing bill-of-materials costs as suppliers move signal conditioning onto the same die as the sensing element. Tier 1 procurement teams are favoring vertically integrated suppliers offering packaged module solutions over discrete component sourcing. This preference shift is most visible in China, where domestic EV platforms prioritize cost-optimized integrated sensors for volume production models.
Automotive Throttle Position Sensor Market Segmentation
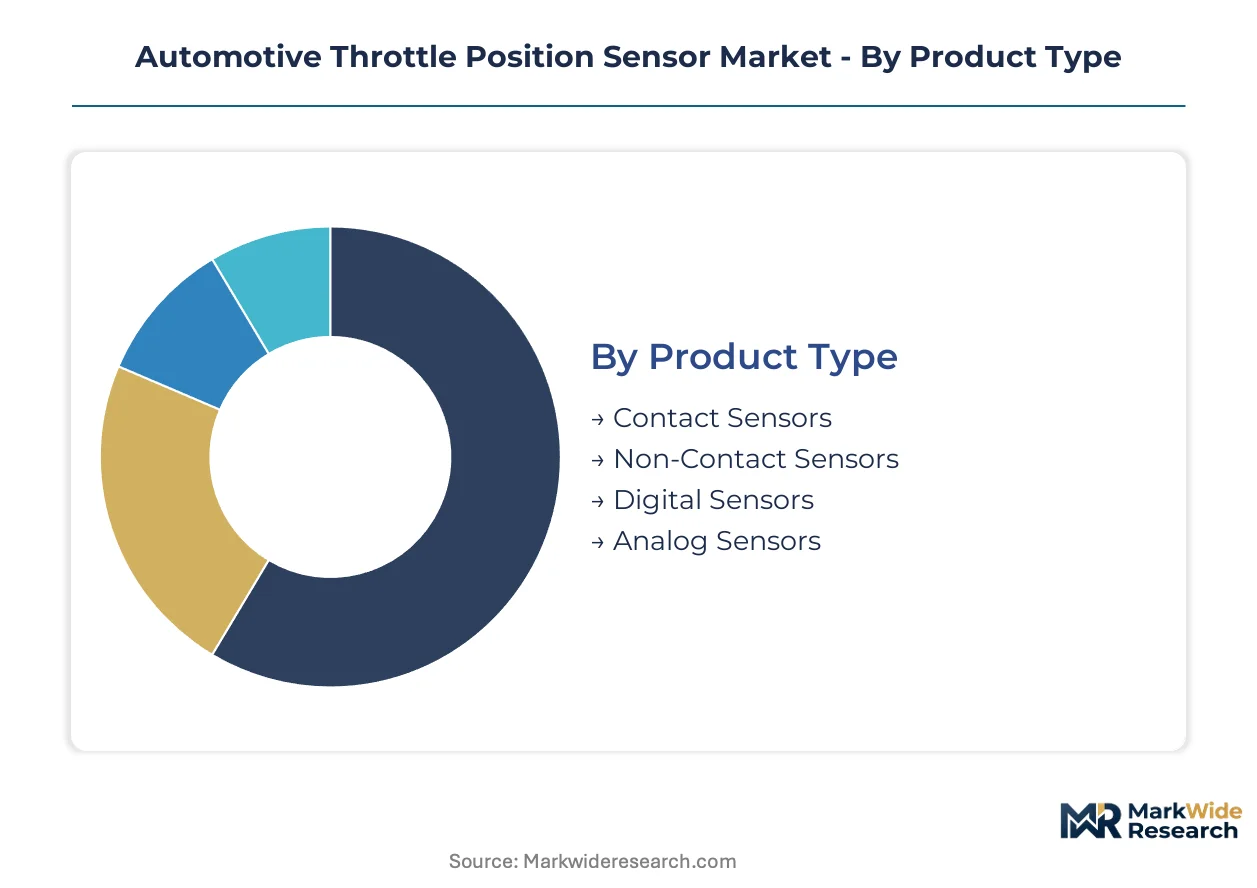
Throttle position sensor procurement splits sharply between legacy replacement cycles and next-generation platform specifications. Capital allocation across these segments determines supplier survival as powertrain electrification accelerates.
Product Type:
Non-contact architectures demand the heaviest upfront tooling investment for magnetic calibration and ASIC integration, while contact-based production lines amortize equipment costs across decades of aftermarket service.
- Contact Sensors:Mechanical potentiometric designs use conductive plastic or cermet resistor tracks with physical wiper contact. Demand concentrates in North American and European aftermarket channels serving aging internal combustion fleets where backward compatibility overrides performance upgrades.
- Non-Contact Sensors:Hall Effect and magnetic-inductive architectures eliminate mechanical wear through semiconductor-based position detection. Chinese EV platforms are absorbing the bulk of new capacity as domestic OEMs specify contactless modules for drive-by-wire throttle systems.
- Digital Sensors:Pulse-width modulation and SENT protocol outputs integrate directly with CAN bus architectures.
- Analog Sensors:Voltage-divider outputs persist in cost-optimized vehicle segments and legacy fleet maintenance.
Contact sensors absorb the bulk of installed capacity; non-contact sensors are expanding most quickly.
Application:
Passenger vehicle programs generate the highest unit volumes but compress margins through consolidated procurement, while commercial vehicle specifications sustain premium pricing for enhanced durability requirements.
- Passenger Vehicles:Light-duty OEM platforms specify compact, integrated sensor modules with redundant validation channels. European and Japanese manufacturers are consolidating supplier bases around dual-Hall architectures for 2027 platform cycles.
- Commercial Vehicles:Heavy-duty throttle sensors face vibration, thermal cycling, and contamination loads exceeding passenger car specifications. Fleet operators in India and Brazil are driving aftermarket replacement volume as emissions enforcement tightens on aging truck populations.
- Electric Vehicles:Dedicated EV architectures eliminate mechanical throttle linkages entirely, repurposing position sensors for pedal-by-wire and regenerative braking modulation.
- Hybrid Vehicles:Dual-mode powertrains require sensors capable of operating across both combustion and electric drive states.
Passenger vehicles dominate current procurement volume; electric vehicles are gaining share fastest.
End User:
OEM qualification timelines stretch 24-36 months but lock in multi-year supply agreements, whereas aftermarket channels convert inventory rapidly with minimal technical documentation burdens.
- OEMs:Original equipment manufacturers specify sensors at platform development inception, embedding suppliers into vehicle architecture decisions. Tier 1 procurement teams in Germany and Japan are consolidating around vertically integrated module suppliers offering ASIC-plus-sensor packaged solutions.
- Aftermarket Providers:Independent distributors and private-label suppliers stock broad catalog coverage for legacy vehicle populations. North American warehouse distributors are expanding diagnostic-intensive replacement programs for commercial vehicle fleets.
- Vehicle Assemblers:Contract manufacturers and kit builders source sensors through tiered supply arrangements.
- Repair Shops:Independent service facilities prioritize immediate availability and installation compatibility over specification optimization.
OEMs command the largest revenue concentration; aftermarket providers are climbing the fastest.
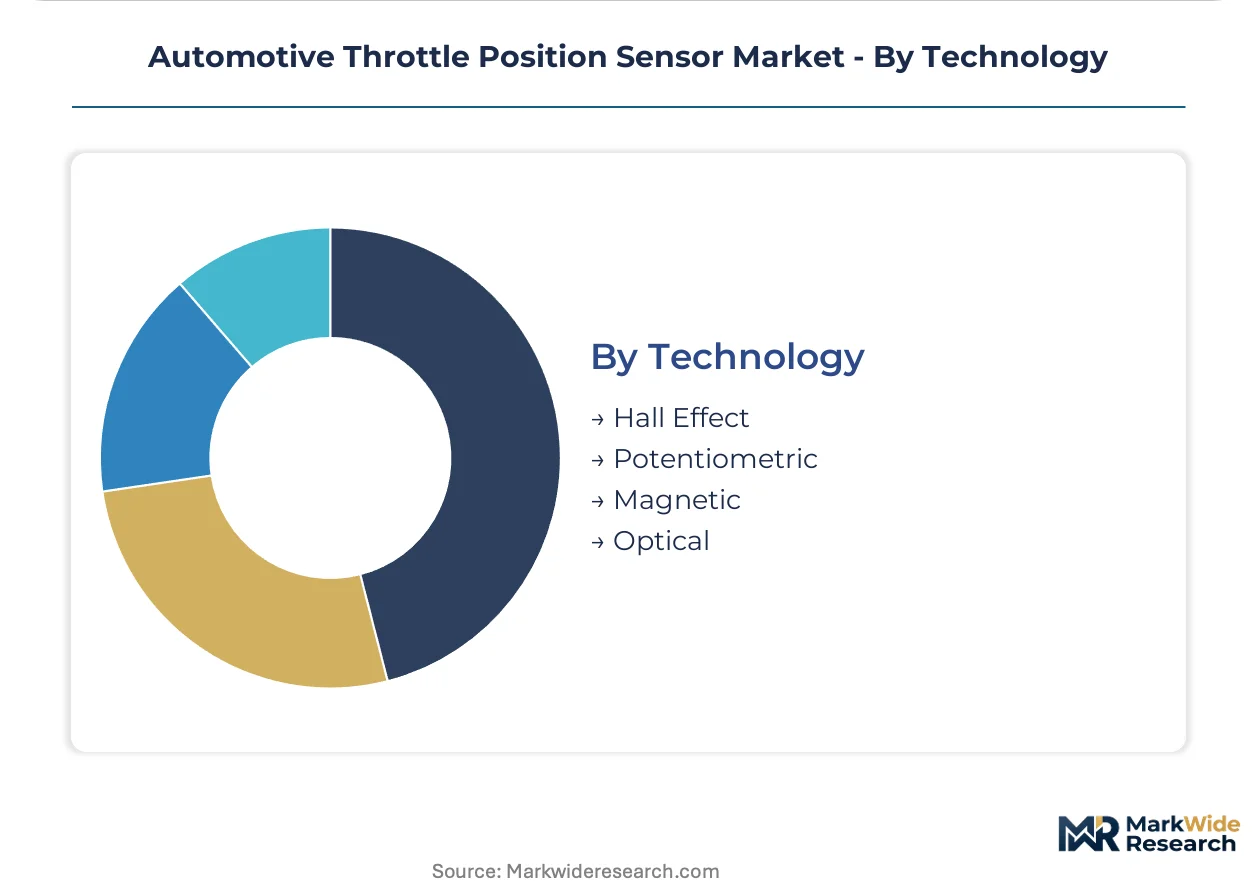
Technology:
Hall Effect production requires semiconductor foundry access and magnetic material supply chains, while potentiometric manufacturing leverages conventional machining and assembly equipment with lower barrier to entry.
- Hall Effect:Semiconductor-based magnetic field detection delivers contactless operation with temperature stability from minus forty to one hundred fifty degrees Celsius. Chinese domestic EV production is scaling Hall module procurement fastest as local OEMs eliminate mechanical wear components.
- Potentiometric:Resistive track technology with physical wiper contact dominates legacy fleet replacement demand. European aftermarket distributors are sustaining production lines for analog replacement units serving aging diesel commercial vehicles.
- Magnetic:Anisotropic magnetoresistive and tunnel magnetoresistive variants offer enhanced precision for redundant validation architectures.
- Optical:Photoelectric position detection remains niche due to contamination sensitivity and packaging constraints.
Potentiometric technology retains the largest installed base; Hall Effect is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors sensor engineering concentration in Germany's automotive corridor, where Bosch and Continental maintain captive foundry relationships. Tier 1 procurement teams in this cluster specify redundant Hall Effect architectures for 2027-2028 platform cycles. Regulatory divergence across major economies is fragmenting validation requirements.
United States
NHTSA functional safety mandates drive dual-channel throttle validation in Detroit's drive-by-wire programs. The IRA clean vehicle incentives accelerate domestic EV production subsidies, favoring localized sensor sourcing. Michigan and Ohio house the primary engineering clusters where OEMs consolidate supplier qualifications.
Germany
Continental AG's captive ASIC design capabilities dominate European OEM supply agreements through ISO 26262 certification. The KBA enforces redundant sensor architectures in premium vehicle platforms. Bavaria and Baden-Württemberg concentrate Hall Effect module production for export markets.
China
Domestic EV manufacturing scales fastest in Shanghai and Shenzhen, absorbing bulk contactless sensor capacity. MIIT standards accelerate mechanical component elimination from powertrain designs. Local OEMs prioritize cost-integrated sensor modules for volume production models.
Japan
Denso Corporation and Mitsubishi Electric anchor precision sensor development in Nagoya and Tokyo corridors. METI industrial policy supports magnetic-inductive hybrid architectures for next-generation platforms. Tier 1 suppliers consolidate around vertically integrated module solutions.
India
Aging commercial vehicle fleets in Maharashtra and Gujarat generate diagnostic-intensive aftermarket replacement volume. The PLI scheme for automotive components attracts sensor assembly investments. BIS emissions enforcement tightens throttle calibration requirements for retrofit markets.
Automotive Throttle Position Sensor Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth, with ASIC-plus-sensor packaged solutions commanding qualification advantages. The vendor base stratifies into three tiers: vertically integrated module suppliers, discrete component specialists, and aftermarket catalog distributors. German and Japanese conglomerates exemplify captive design capabilities, while North American providers concentrate distribution breadth. M&A activity targets magnetic material supply security, and capacity expansion concentrates in Taiwan and South Korea foundry corridors.
Among German-based engineering conglomerates, Continental AG and Robert Bosch GmbH exemplify the vertically integrated tier through captive electronics foundry networks. Delphi Technologies occupies a position within North American aftermarket distribution archetypes. Sensata Technologies and TE Connectivity represent the precision-component specialist tier, with geographic footprints spanning multiple industrial corridors. CTS Corporation anchors a position among diversified sensor manufacturers with cross-industry portfolio exposure.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Delphi Technologies |
| Robert Bosch GmbH |
| TE Connectivity |
| Sensata Technologies |
| Denso Corporation |
| CTS Corporation |
| Mitsubishi Electric Corporation |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet pricing volatility flows from Chinese rare earth processing dominance through Hall Effect sensor module costs into tiered procurement brackets, with OEMs absorbing premium grades and aftermarket channels trading analog potentiometric units on spot-adjacent terms.
Pricing Analysis
Value-based pricing anchored to ISO 26262 ASIL certification tier separates qualified module suppliers from commodity component vendors. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with redundant dual-Hall architectures commanding OEM premiums and single-channel analog units facing price erosion from Chinese domestic EV cost compression. Fleet operators in India and Brazil exhibit highest price sensitivity in commercial vehicle retrofit procurement, while German premium OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with automotive-grade ASIC fabrication concentrating in Taiwan and South Korea foundry corridors. Magnetic core production draws from Chinese rare earth processing and Japanese precision magnet manufacturing, while resin housings and connector systems source from Thailand and Mexico assembly plants. Tariff exposure on semiconductor inputs creates geographic supply risk for European and North American module assemblers. Distribution runs through tiered automotive supplier networks with captive logistics rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification is forcing consolidation as dual-platform suppliers split R&D resources between legacy potentiometric maintenance and contactless Hall Effect development, squeezing mid-tier players lacking captive foundry access or aftermarket scale.
For Market Incumbents: Deploy captive ASIC design capabilities to lock in OEM platform engineering relationships before 2027-2028 vehicle cycles solidify supplier bases. Accelerate backward integration into magnetic material supply through long-term offtake agreements with Chinese rare earth processors, insulating margin from neodymium price swings that threaten Hall Effect module profitability.
For New Entrants and Emerging Players: Magnetic-inductive hybrid sensing architectures offer a technology-first wedge into commercial vehicle drive-by-wire retrofit demand in India and Brazil, where emissions enforcement tightens on aging fleets but OEM-qualified suppliers remain thin. Target aftermarket diagnostic-intensive replacement programs through direct distributor partnerships rather than tiered supply hierarchies.
For Investors and Strategic Acquirers: Foundry capacity expansion announcements in Taiwan are the leading indicator that supply-constrained sensor-integrated electronics will shift from shortage pricing toward normalized procurement terms within the 5-10 year viability window. Pursue acquisition targets with established ISO 26262 documentation libraries and existing OEM qualification relationships, as embedded software certification backlogs extend new entrant timelines by 12-18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive ASIC Design Investment | Reduces foundry dependency for Bosch and Continental in German automotive corridor. |
| Magnetic Material Supply Agreement | Locks neodymium pricing for Hall Effect module production against rare earth volatility. |
| Dual-Hall Architecture Standardization | Meets NHTSA redundant validation mandates in Detroit drive-by-wire programs. |
| Aftermarket Diagnostic Platform Launch | Captures aging commercial vehicle replacement cycles in India and Brazil. |
| Regional Manufacturing Footprint Expansion | Aligns with IRA clean vehicle incentives for domestic EV sensor sourcing. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, and SEC filings from listed sensor manufacturers, complemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership service operations. Secondary validation drew from NHTSA enforcement protocols, EPA emissions calibration guidelines, and MIIT standards documentation. Bottom-up unit demand modeling triangulated against top-down market value estimates from industry trade associations.
Historical shipment patterns cross-referenced against expert panel input on platform cycle timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from slope analysis of technology transition curves and replacement cycle dynamics, with EV platform sensor penetration and legacy fleet age distribution serving as primary forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in functional safety enforcement, geopolitical disruption to rare earth supply chains, and breakthrough sensor technologies displacing Hall Effect architectures. Forecasts reflect documented assumptions about OEM platform consolidation timelines and aftermarket inventory turnover rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Dual Circuit Brakes System Market