
 Automotive Idle Air Control Valve Market | 2026-2036
Automotive Idle Air Control Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Idle Air Control Valve Market Outlook
Aftermarket diagnostic subscriptions for idle system monitoring is recalibrating how valve manufacturers monetize long-term customer relationships. Robert Bosch GmbH leverages its embedded software portfolio to bundle predictive maintenance alerts with hardware sales. DENSO Corporation anchors its competitive stance through captive production of precision electromagnetic actuators for electronic valve variants. Continental AG differentiates by controlling the calibration protocol layer that ties valve response to engine control unit maps.
An automotive idle air control valve modulates bypass airflow around the throttle plate during engine idle, typically employing a stepper motor or solenoid actuator with positional accuracy within 0.1 millimeters to maintain stable RPM. The component prevents stalling while supporting emission control systems by optimizing combustion at low engine speeds. Electronic valves command the dominant share of product type revenue as powertrain electrification demands finer idle resolution, though pneumatic variants retain niche positions in cost-sensitive commercial vehicle segments. Passenger car applications lead vehicle type demand, while hybrid vehicle integration represents the fastest-growing sub-area as start-stop systems require more frequent idle transitions.
EPA emission thresholds in the United States and EU Green Deal carbon benchmarks in Europe enforce stricter idle combustion efficiency, compelling valve redesigns with tighter airflow tolerances. China's MIIT fuel consumption standards and GB emissions regulations mandate idle stop functionality in new vehicle certifications, directly expanding electronic valve fitment rates. Stakeholders must weigh software-enabled remote calibration capabilities against hardware refresh cycles as powertrain architectures diverge across regulatory jurisdictions.
Market Dynamics
Software-defined engine management is compressing hardware refresh cycles while expanding the attach rate of calibration services to idle air control valve shipments. Tier 1 suppliers now compete on embedded firmware capabilities rather than mechanical precision alone.
Growth Catalysts
- EPA Tier 3 emission standards:Idle combustion efficiency mandates in the United States force tighter airflow tolerances, expanding electronic valve fitment across light-duty vehicle platforms.
- Hybrid powertrain integration:Start-stop system proliferation in China's automotive manufacturing corridors demands more frequent idle transitions and finer RPM resolution.
- Aftermarket service contracts:Commercial fleet operators in the United States are adopting diagnostic subscriptions for idle system recalibration, creating recurring revenue streams for valve suppliers.
Market Restraints
- Neodymium price volatility:Rare-earth magnet costs for stepper motor actuators fluctuate with export quota policies from China's MIIT, compressing margin stability for electromagnetic valve producers.
- Pneumatic valve substitution:Cost-sensitive commercial vehicle segments in India and Brazil retain vacuum-actuated idle bypass systems, limiting electronic valve penetration in heavy-duty categories.
- REACH substance restrictions:EU regulations on hexavalent chromium coatings constrain traditional plating processes for valve spool surfaces, forcing process requalification investments.
Strategic Opportunities
- Remote calibration capabilities:Over-the-air software updates enable valve response remapping without physical replacement, creating service monetization opportunities in connected vehicle fleets.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive electronics attract idle control valve manufacturing investment toward domestic OEM supply chains.
- Sensor-actuator convergence:Integration of airflow sensing with valve positioning eliminates separate MAF sensor hardware, reducing system cost and package size for compact engine bays.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety compliance for valve control algorithms extends development timelines and requires specialized automotive software engineering talent.
- Legacy ECU integration:Backward compatibility with 1990s-era engine control unit architectures complicates electronic valve deployment in aftermarket replacement channels.
- Precision machining capacity:Sub-10-micron tolerance requirements for valve seat geometries strain available Swiss-turn machining capacity at specialized component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Idle Air Control Valve Market |
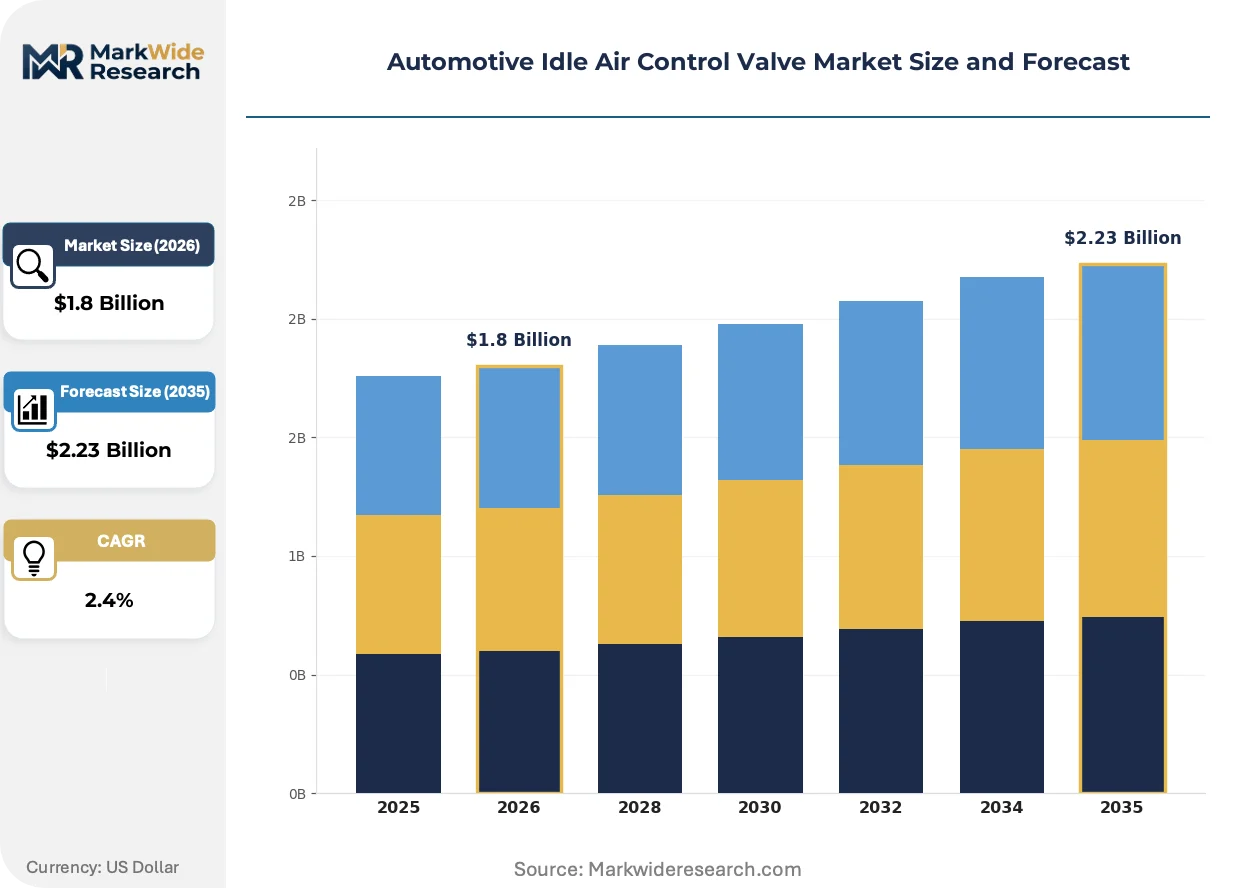
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Pneumatic, Hydraulic, Mechanical Vehicle Type: Passenger Car, Commercial Vehicle, Electric Vehicle, Hybrid Vehicle End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Functionality: Emissions Control, Engine Performance, Fuel Efficiency, Idle Management |
| Companies Covered | AISIN SEIKI Co., Ltd., Delphi Technologies, Robert Bosch GmbH, Valeo SA, Hitachi Automotive Systems, Ltd., DENSO Corporation, BorgWarner Inc., Magneti Marelli S.p.A., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Idle Air Control Valve Market Strategic Shifts
Electrification of auxiliary systems and embedded intelligence are transforming idle air control valves from passive airflow modulators into active combustion optimization nodes. Three developments dominate supplier R&D allocation.
Smart valve architectures with integrated position sensing and local PID control loops are unifying sensor and actuator functions into single electromechanical packages. Hybrid vehicle OEMs in Japan and South Korea are adopting these units for sub-50-millisecond response times during engine restart events. This convergence is compressing the traditional multi-component supply chain into consolidated mechatronic module sourcing.
EU Green Deal carbon benchmarks are tightening idle CO2 emission thresholds for new vehicle type approvals, compelling valve redesigns with laminar flow optimization and reduced hysteresis. German KBA certification protocols now require documented idle stability across altitude variations from sea level to 3000 meters. European passenger car platforms are responding with dual-solenoid redundant valve configurations to ensure compliance under single-fault conditions.
Fleet management platforms are unbundling hardware procurement from calibration service subscriptions, with commercial vehicle operators in the United States paying per-vehicle-month fees for predictive idle system monitoring. This displaces traditional upfront parts-plus-labor transaction models at independent repair facilities. The shift is most visible among last-mile delivery fleets operating in California's South Coast Air Quality Management District, where emission compliance reporting requirements favor continuous monitoring over periodic inspection.
Automotive Idle Air Control Valve Market Segmentation
Idle air control valve procurement patterns diverge sharply across product architectures and vehicle electrification levels. Segment boundaries determine which suppliers capture software-enabled service revenue versus commodity hardware replacement cycles.
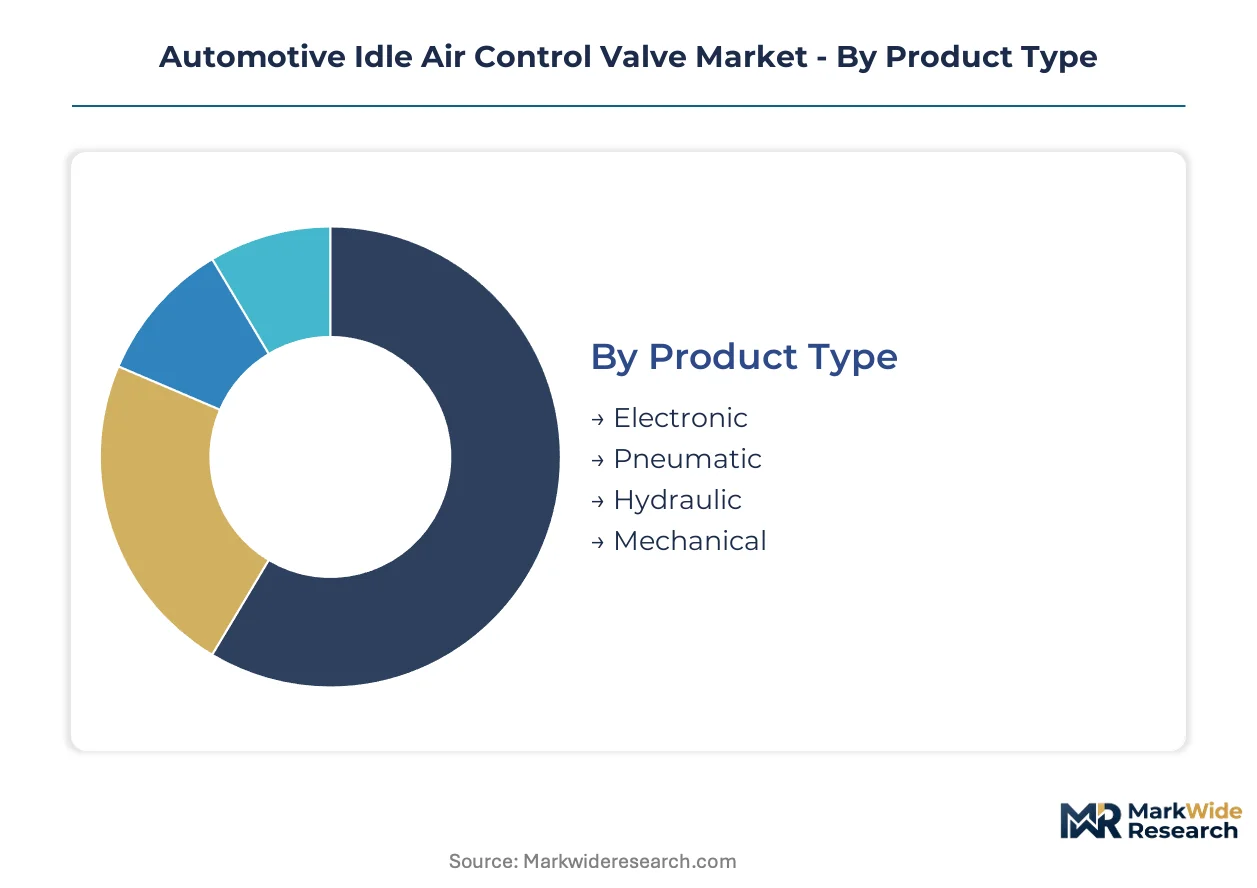
Product Type:
Replacement cycles for electronic valves compress as embedded firmware becomes the primary value driver, while pneumatic and mechanical variants persist in cost-optimized fleet retrofits.
- Electronic:Stepper motor or solenoid actuators with positional feedback loops enable sub-50-millisecond response times for hybrid restart events. China's MIIT fuel consumption standards mandate electronic fitment for idle-stop certification, concentrating demand in domestic OEM hybrid platforms.
- Pneumatic:Vacuum-actuated bypass systems rely on engine manifold pressure differentials without electrical control. Cost-sensitive commercial vehicle segments in India and Brazil retain these units, constraining electronic valve penetration in heavy-duty categories where uptime cost trumps precision.
- Hydraulic:Fluid-pressure modulation systems appear in specialized industrial engine applications requiring high-torque idle stability.
- Mechanical:Spring-loaded thermal or cable-operated valves serve legacy vehicle parc and developing-market aftermarket channels.
Volume placements concentrate in Electronic; the faster expansion belongs to Electronic as powertrain electrification demands finer idle resolution.
Vehicle Type:
Cost tier stratification separates precision-engineered hybrid integration from standardized commercial vehicle fitment.
- Passenger Car:Multi-cylinder engines with automatic climate loads require continuous idle compensation across temperature extremes. EPA Tier 3 emission thresholds in the United States force tighter airflow tolerances, expanding electronic valve fitment across light-duty platforms.
- Hybrid Vehicle:Start-stop system proliferation demands frequent idle transitions with instantaneous restart capability. Japanese and South Korean OEMs specify smart valve architectures with integrated PID control loops for sub-50-millisecond response, climbing the fastest among vehicle categories.
- Commercial Vehicle:Diesel idle management prioritizes fuel conservation over emission precision in long-haul applications.
- Electric Vehicle:Range-extender and series-hybrid architectures retain internal combustion idle modes requiring valve control.
Passenger Car holds the installed base; Hybrid Vehicle gains share fastest as China's automotive manufacturing corridors expand domestic OEM integration.
End User:
Customer type determines whether procurement emphasizes upfront hardware cost or lifetime calibration service attachment.
- OEMs:Vehicle manufacturers specify valve-response maps tied to engine control unit architectures during platform development. Tier 1 suppliers compete on embedded firmware capabilities rather than mechanical precision alone.
- Aftermarket Providers:Independent repair facilities and diagnostic subscription services monetize idle system recalibration. Commercial fleet operators in the United States adopt per-vehicle-month monitoring fees, displacing traditional parts-plus-labor transactions.
- Vehicle Assemblers:Contract manufacturers source valves to OEM specification without design authority.
- Tier-1 Suppliers:System integrators bundle idle control modules with broader engine management portfolios.
OEM procurement dominates absolute volume; Aftermarket Providers expand most quickly as fleet management platforms unbundle hardware from software services.
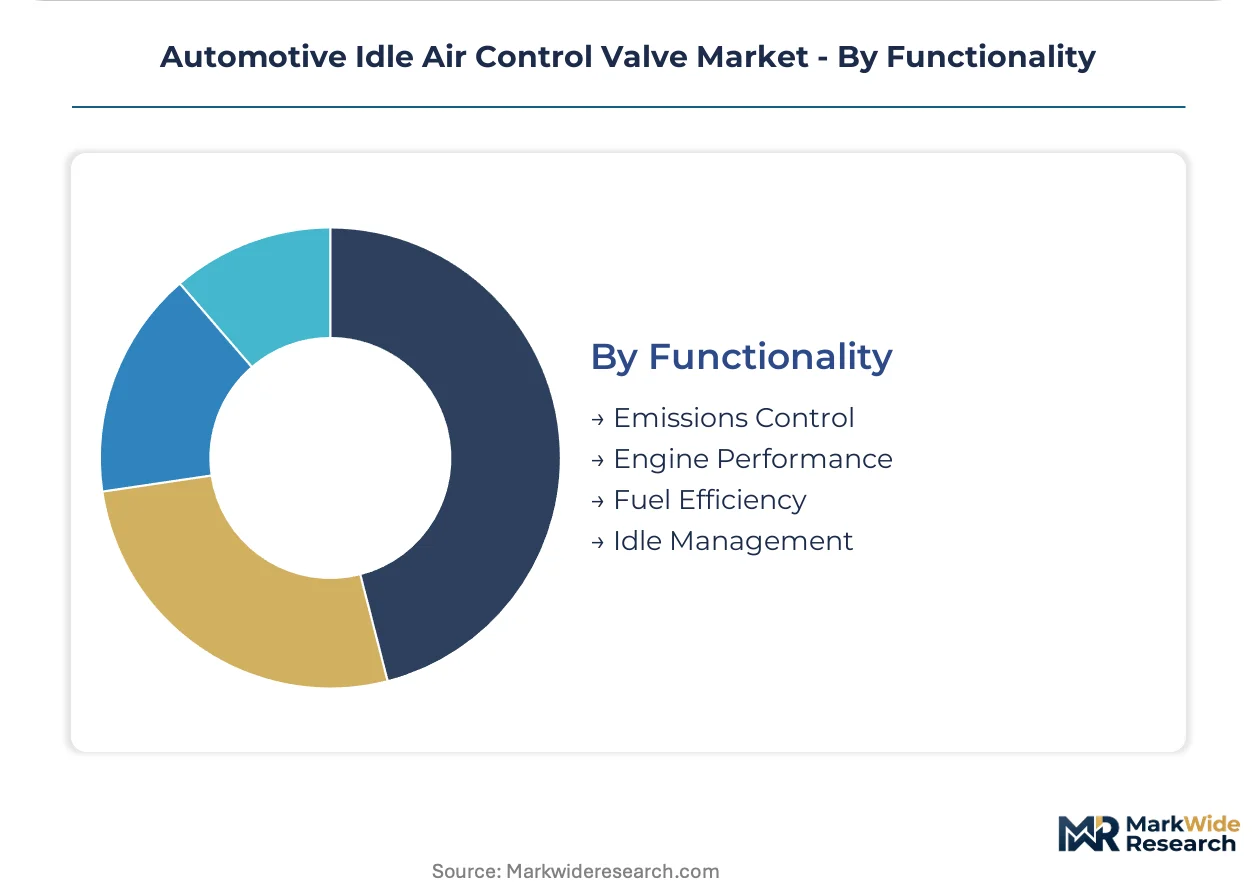
Functionality:
Application focus shifts from emission compliance hardware toward combustion optimization software.
- Emissions Control:Idle combustion efficiency directly impacts type-approval CO2 and NOx thresholds. EU Green Deal carbon benchmarks enforce stricter idle stability requirements, compelling German KBA certification protocols across altitude variations.
- Idle Management:RPM stability during accessory loading and thermal transient conditions prevents stall events. Start-stop system proliferation in China's automotive manufacturing corridors demands finer resolution for frequent transition cycles.
- Engine Performance:Power delivery consistency at low speeds supports drivability metrics.
- Fuel Efficiency:Optimized bypass airflow reduces consumption during stationary operation.
Emissions Control commands the specification authority; Idle Management captures the steepest expansion trajectory as hybrid powertrain integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of idle air control valves while the United States and Germany consume the most advanced electronic variants. Production concentrates in automotive corridors serving domestic OEM hybrid platforms. Demand patterns split between emission-compliant precision markets and cost-optimized fleet retrofits.
United States
Commercial fleet operators adopt diagnostic subscriptions for idle system recalibration, creating recurring revenue channels. EPA Tier 3 emission standards enforce tighter airflow tolerances across light-duty platforms. California's South Coast Air Quality Management District drives continuous monitoring requirements among last-mile delivery operators.
China
Domestic OEMs expand idle control integration across hybrid powertrains in the Yangtze River Delta manufacturing belt. MIIT fuel consumption standards mandate idle-stop functionality for new vehicle certifications. Shenzhen and Shanghai automotive clusters prioritize electronic valve fitment for export-bound hybrid platforms.
Germany
KBA certification protocols require documented idle stability across altitude variations from sea level to 3000 meters. EU Green Deal carbon benchmarks tighten idle CO2 emission thresholds for type approvals. Stuttgart and Munich engineering centers develop dual-solenoid redundant valve configurations for premium passenger car platforms.
Japan
Hybrid vehicle OEMs specify smart valve architectures with integrated PID control loops for sub-50-millisecond restart response. METI policies support powertrain electrification component development. Toyota City and Nagoya manufacturing corridors anchor precision electromagnetic actuator production for electronic valve variants.
India
PLI scheme incentives for advanced automotive electronics attract idle control valve manufacturing investment toward domestic OEM supply chains. Cost-sensitive commercial vehicle segments retain vacuum-actuated idle bypass systems. Pune and Chennai automotive clusters balance electronic valve adoption with pneumatic variant persistence in heavy-duty categories.
Automotive Idle Air Control Valve Market Competitive Environment
Top-tier vendors anchor the integrated systems tier, while specialized component fabricators occupy mid-market positions. The supplier base organizes around three archetypes: diversified automotive electronics conglomerates with embedded software portfolios, precision electromagnetic actuator specialists with captive production capabilities, and regional component suppliers serving aftermarket retrofit channels. Consolidation pressures favor acquisition of firmware competencies over mechanical capacity expansion. Strategic partnerships between valve suppliers and engine control unit map developers reshape procurement relationships.
Within the diversified systems tier, Robert Bosch GmbH and DENSO Corporation exemplify integrated portfolio approaches. Continental AG occupies a position at the calibration protocol layer where valve response ties to engine control unit architectures. Delphi Technologies and Hitachi Automotive Systems, Ltd. represent the precision actuator specialization vector. BorgWarner Inc. and Valeo SA anchor geographic diversification strategies across multiple regulatory jurisdictions. AISIN SEIKI Co., Ltd. and Magneti Marelli S.p.A. sit within the captive supply archetype serving affiliated OEM manufacturing networks.
| Leading Market Players |
|---|
| AISIN SEIKI Co., Ltd. |
| Delphi Technologies |
| Robert Bosch GmbH |
| Valeo SA |
| Hitachi Automotive Systems, Ltd. |
| DENSO Corporation |
| BorgWarner Inc. |
| Magneti Marelli S.p.A. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Domestic OEM hybrid platform procurement in China's Yangtze River Delta manufacturing belt anchors contract-based long-term offtake agreements, compressing spot-market liquidity and elevating supplier pricing power for electronic valve variants with embedded firmware capabilities.
Pricing Analysis
Margin tightening in standard-grade electronic valves reflects neodymium price volatility under China's MIIT export quota policies. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified smart valve architectures from basic solenoid actuators and legacy pneumatic alternatives. Cost-down pressure accelerates as Tier 1 suppliers bundle calibration subscriptions with hardware shipments. Commercial fleet operators in the United States demonstrate highest price sensitivity through per-vehicle-month diagnostic fee resistance, while German premium passenger car OEMs absorb firmware premiums for KBA altitude-compliance certification.
Supply Chain Analysis
Remanufacturing flows for legacy mechanical valves from 1990s-era vehicle parc create secondary supply channels competing with new electronic unit shipments. Component fabrication concentrates in China, Japan, and Germany, with precision electromagnetic actuator production anchored in Toyota City and Nagoya corridors. Rare-earth magnet supply draws from China's Inner Mongolia mining districts and Malaysian processing facilities. Single-source vulnerability persists for sub-10-micron Swiss-turn machining capacity at specialized valve seat suppliers. Distribution runs through captive OEM supply chains for Tier 1 integrators, with aftermarket channels served by independent diagnostic subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swiss-turn machining capacity constraints for sub-10-micron valve seat geometries prop pricing premiums for qualified suppliers across the analysis window.
For Market Incumbents: Anticipate margin compression from pneumatic valve substitution in India's cost-sensitive commercial vehicle segments by deepening backward integration into precision electromagnetic actuator production. Lock in long-term rare-earth magnet offtake agreements before China's MIIT tightens export quotas. Prioritize firmware certification investment for ISO 26262 compliance to defend against embedded software specialists entering the calibration protocol layer. For New Entrants and Emerging Players: Capture aftermarket diagnostic subscription revenue among United States last-mile delivery fleets operating under California's South Coast Air Quality Management District continuous monitoring mandates. India's PLI scheme for advanced automotive electronics offers the most penetrable entry point for domestic OEM supply chain qualification. Lead with sensor-actuator convergence architectures that eliminate separate MAF sensor hardware to differentiate against established multi-component suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with captive Swiss-turn capacity in Germany and Japan amid Tier 1 consolidation pressures. Five-to-ten year viability hinges on software-defined engine management attach rates overtaking hardware refresh cycles. Monitor EPA Tier 3 implementation timing and EU Green Deal carbon benchmark enforcement as inflection indicators for electronic valve demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Firmware Certification | ISO 26262 compliance unlocks premium pricing in German KBA-certified platforms. |
| Rare-Earth Magnet Integration | Captive neodymium sourcing insulates margins from China's MIIT quota volatility. |
| Sensor-Actuator Convergence | Eliminating separate MAF sensors reduces package size for compact Japanese hybrid engine bays. |
| Remote Calibration Capability | Over-the-air valve remapping enables recurring revenue from United States fleet operators. |
| Precision Machining Capacity Expansion | Sub-10-micron tolerance qualification secures supply position for European altitude-compliance valves. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. SAE International technical standards, EPA emission certification databases, MIIT fuel consumption bulletins, and KBA type-approval registries provided segmentation benchmarks. Bottom-up valve shipment tallies triangulated against top-down powertrain production estimates from vehicle registration databases.
Data-stream reconciliation across electronic, pneumatic, hydraulic, and mechanical product architectures, passenger car, hybrid, commercial, and electric vehicle categories, and OEM, aftermarket, and Tier 1 end-user channels shaped the analytical framework over the projection horizon. CAGRs derived from fitted trend extrapolation with powertrain electrification adoption curves and regulatory compliance phase-in schedules as key inputs. Hybrid vehicle integration intensity and software-defined engine management penetration served as primary demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to China's rare-earth export policy shifts and REACH substance restriction expansions. Forecasts reflect documented assumptions regarding EPA Tier 3 enforcement timing and EU Green Deal implementation pace. Practitioners should monitor MIIT dual carbon goal acceleration and India PLI scheme disbursement triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market